
 Zinc Eugenol Market | 2026-2036
Zinc Eugenol Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Eugenol Market Outlook
Aftermarket service revenue from dental cement application training and chairside support is rewriting how manufacturers capture value downstream. Dentsply Sirona leverages its installed base of dental equipment to bundle cement products with technical education programs. BASF SE anchors its position through backward integration into eugenol feedstock sourcing from clove oil derivatives. Firmenich SE competes on flavor-masking technology that improves patient compliance during temporary cementation procedures.
Zinc eugenol denotes a dental material formed from zinc oxide and eugenol oil that sets via chelation to produce a hard, insulating cement with pH near 7 and thermal conductivity of approximately 0.004 cal/cm/sec/°C, used primarily for temporary restorations, pulp protection, and root canal sealing. The paste form dominates clinical workflows due to controlled setting times and ease of manipulation, while powder formulations sustain demand in hospital settings where bulk mixing protocols persist. Endodontic applications represent the fastest-expanding segment as retreatment cases rise and clinicians seek sealants with antimicrobial properties and dimensional stability.
The U.S. FDA regulates zinc eugenol dental cements as Class II medical devices under 21 CFR 872.3275, requiring substantial equivalence demonstrations for market entry, while the EU MDR demands updated clinical evaluation reports and post-market surveillance systems that lengthen approval timelines. India's CDSCO aligns with ISO 9917 standards for dental water-based cements, creating a harmonized but documentation-intensive pathway for imported products. Stakeholders must monitor evolving biocompatibility testing protocols and decide whether to invest in in-house toxicology data generation or outsource to specialized contract research organizations.
Market Dynamics
The EU Medical Device Regulation is compressing approval timelines while simultaneously demanding expanded biocompatibility documentation, forcing manufacturers to restructure clinical evaluation workflows and toxicology data generation strategies.
Growth Catalysts
- Retreatment case volume:Rising endodontic retreatment procedures in private dental chains across India's tier-two cities is expanding addressable demand for antimicrobial sealants with dimensional stability.
- REACH compliance alignment:Harmonized chemical safety documentation across EU member states is reducing redundant testing burdens for eugenol-based formulations entering multiple national markets.
- Equipment bundling:Dental equipment manufacturers are integrating cement products with technical education programs, creating captive demand channels through installed base leverage.
Market Restraints
- Clove oil feedstock volatility:Eugenol sourcing concentration in Indonesian and Madagascan agricultural supply exposes formulators to weather-driven price swings and crop yield uncertainty.
- Polymer-based substitution:Glass ionomer and resin-modified glass ionomer cements are displacing zinc eugenol in select temporary restoration applications due to superior aesthetic matching.
- ISO 9917 documentation intensity:India's CDSCO alignment with international cement standards creates prolonged import clearance timelines for foreign manufacturers lacking pre-existing test portfolios.
Strategic Opportunities
- Flavor-masking technology convergence:Combining eugenol odor suppression with patient compliance monitoring systems opens premium positioning in pediatric and anxiety-prone patient segments.
- Chairside support unbundling:Technical training and application assistance services represent separable revenue streams beyond product sales, particularly in rapidly scaling clinic chains.
- Backward integration into cultivation:Direct clove oil extraction partnerships in Kerala and Zanzibar offer supply security and cost structure control for integrated manufacturers.
Industry Challenges
- Toxicology data generation capacity:In-house biocompatibility testing requires specialized personnel and capital equipment that mid-tier formulators struggle to acquire.
- Post-market surveillance system integration:EU MDR mandates for ongoing clinical performance tracking demand IT infrastructure investments that fragment compliance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Eugenol Market |
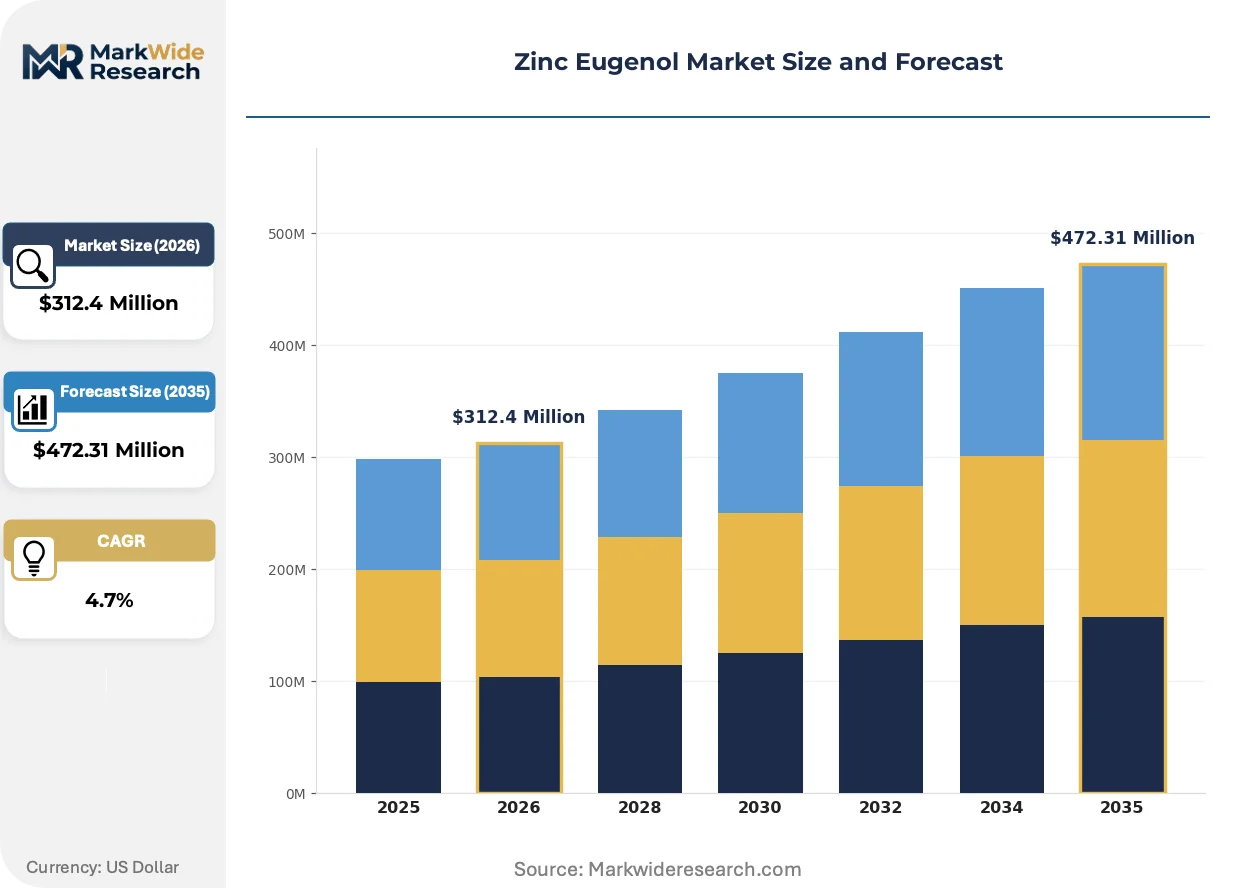
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Cement, Temporary Filling Material, Permanent Cement, Root Canal Sealants Application: Dental Procedures, Endodontics, Restorative Dentistry, Orthodontics End User: Dentists, Dental Clinics, Hospitals, Research Laboratories Form: Paste, Powder, Liquid, Gel |
| Companies Covered | Dupont, SOLVAY, Dow, BASF SE, Firmenich SE, LANXESS, International Flavors & Fragrances, Symrise, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Eugenol Market Strategic Shifts
Digital workflows and regulatory harmonization pressures are converging to reshape how zinc eugenol products are developed, validated, and delivered to clinical end-users across fragmented national markets.
Smart dispensing systems embedded with setting-time sensors and mixing ratio feedback are digitizing chairside cement preparation protocols. Large dental service organizations in Germany and the United States are piloting these devices to standardize temporary restoration quality across multi-location practices. The technology is digitizing quality assurance processes that previously relied on operator judgment, reducing variability in chelation completion and final cement hardness.
The EU MDR's expanded clinical evaluation report requirements are lengthening approval timelines for dental cement manufacturers seeking CE marking renewals. Device sponsors must now demonstrate substantial equivalence through expanded patient follow-up data, particularly for formulations claiming extended antimicrobial activity. German notified bodies are applying the most stringent interpretations, creating a de facto regulatory bottleneck that smaller formulators are addressing through consortium-based clinical trial cost sharing.
Aftermarket service contracts are displacing traditional product-only procurement in high-volume dental clinic chains. Technical education programs covering cement selection, mixing technique, and failure mode analysis now accompany bulk supply agreements in India's expanding corporate dental networks. This shift is most pronounced in Hyderabad and Chennai, where chain operators prioritize predictable restoration outcomes over per-unit material cost minimization.
Zinc Eugenol Market Segmentation
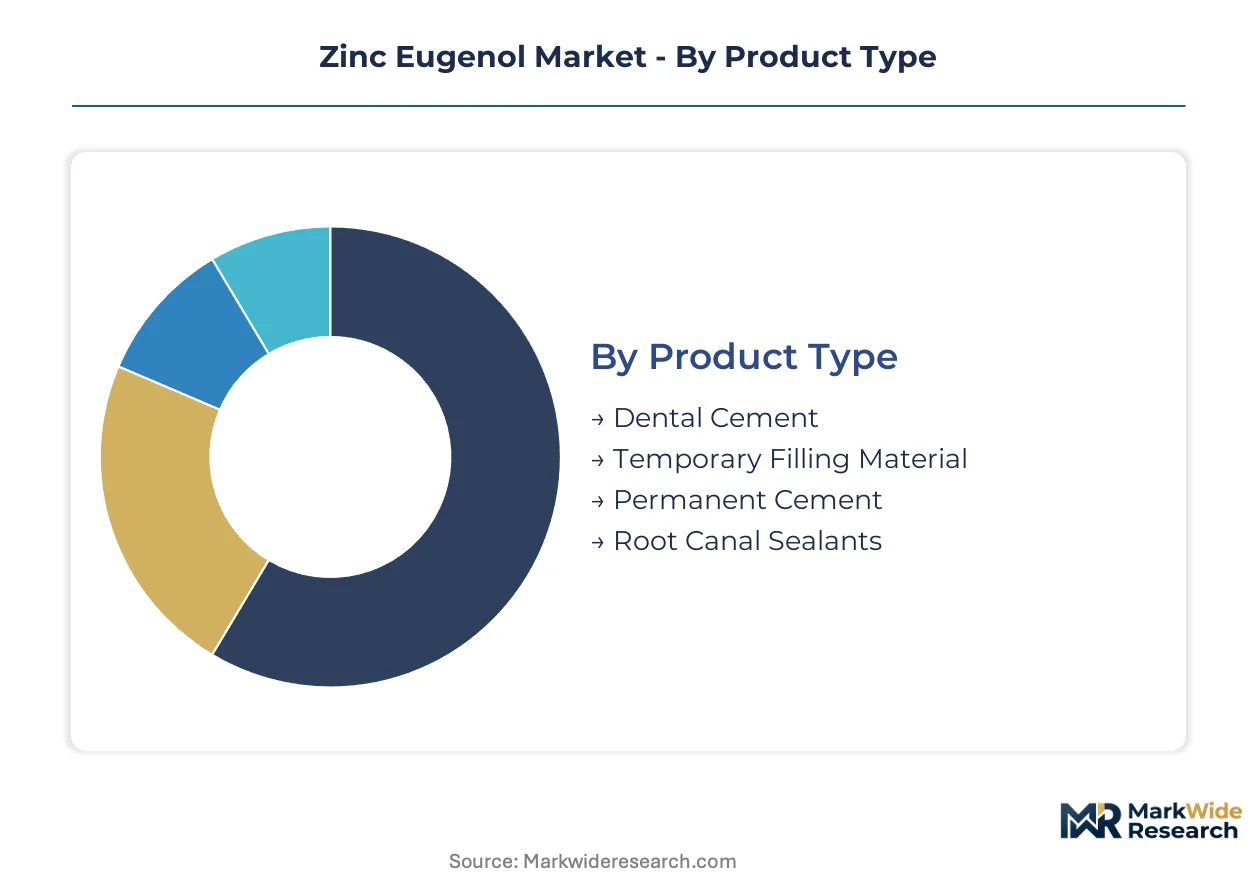
Segmentation in the zinc eugenol market determines how manufacturers align product portfolios with distinct clinical workflows and procurement patterns. Service intensity varies sharply across end-user types, with dental clinic chains demanding bundled technical support that commodity-focused hospital buyers rarely require.
Product Type:
After-sales service intensity diverges substantially across product categories, with temporary materials requiring frequent chairside troubleshooting while permanent cements demand failure-analysis support.
- Dental Cement:Zinc oxide-eugenol formulations set via chelation to produce hard, insulating layers with thermal conductivity near 0.004 cal/cm/sec/°C. Demand concentrates in German dental clinics expanding restorative workflows under tightened EU MDR biocompatibility documentation requirements.
- Temporary Filling Material:Paste-based provisional restorations offer controlled setting times and easy manipulation for short-term pulp protection. India's tier-two private clinic chains are scaling procurement of these materials as retreatment case volumes rise.
- Permanent Cement:Long-duration formulations compete against glass ionomer alternatives in final restoration applications. ISO 9917 compliance documentation creates import friction for foreign suppliers entering Indian hospital tenders.
- Root Canal Sealants:Antimicrobial sealants with dimensional stability address endodontic retreatment growth. Eugenol feedstock volatility from Indonesian and Madagascan clove oil sourcing compresses margin structures for specialized formulators.
Dental Cement holds the largest share; momentum sits with Root Canal Sealants.
Application:
Cost tier stratification separates high-volume routine procedures from specialized interventions requiring premium material specifications and extended manufacturer warranties.
- Dental Procedures:General restorative applications encompass temporary crowns, bridges, and cavity linings across mixed clinical settings. Paste formulations dominate due to chairside mixing convenience and predictable handling characteristics.
- Endodontics:Root canal therapy and retreatment procedures demand sealants combining antimicrobial properties with dimensional stability for long-term canal obturation. This segment is expanding most quickly as retreatment case volumes climb in India's corporate dental networks.
- Restorative Dentistry:Permanent and semi-permanent reconstructions utilize zinc eugenol for pulp capping and base applications beneath definitive restorations. EU MDR clinical evaluation report requirements lengthen approval timelines for formulations claiming extended therapeutic performance.
- Orthodontics:Band cementation and appliance fixation represent niche demand with distinct mixing protocol requirements. Powder formulations persist in orthodontic hospital departments maintaining bulk preparation standards.
Restorative Dentistry anchors volume; Endodontics shows the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with corporate dental chains negotiating service-inclusive supply contracts while independent practitioners prioritize per-unit cost minimization.
- Dentists:Independent practitioners and small group practices select materials based on handling familiarity and established supplier relationships. Technical education programs from equipment manufacturers increasingly influence cement selection in the United States.
- Dental Clinics:Multi-location chains in Hyderabad and Chennai prioritize predictable restoration outcomes through standardized product protocols and bundled chairside support services. Aftermarket training contracts now accompany bulk supply agreements.
- Hospitals:Institutional procurement emphasizes powder formulations compatible with bulk mixing protocols and centralized sterilization workflows. CDSCO alignment with ISO 9917 standards creates documentation-intensive clearance pathways for imported cements.
- Research Laboratories:Academic and commercial R&D facilities drive formulation innovation and biocompatibility testing protocol development. Toxicology data generation capacity constraints limit mid-tier formulator participation in preclinical validation studies.
Dental Clinics capture the fastest-growing procurement volume; Hospitals maintain the largest installed base.
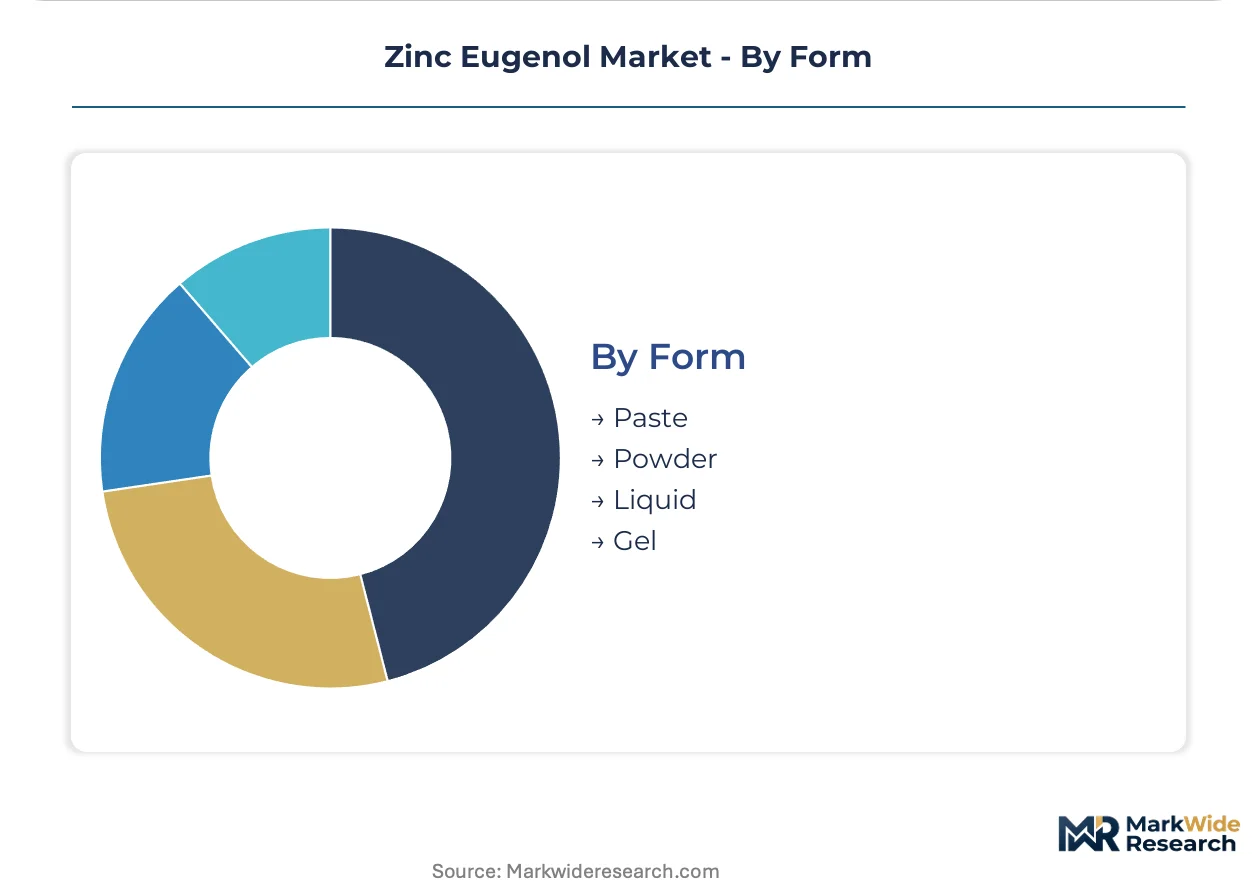
Form:
Supply concentration in paste manufacturing reflects clinical workflow preferences, while powder production retains relevance in institutional settings with established compounding infrastructure.
- Paste:Pre-mixed or dual-paste systems enable controlled setting times and simplified chairside manipulation without proportioning errors. Smart dispensing systems with mixing ratio feedback are digitizing quality assurance in German and U.S. dental service organizations.
- Powder:Zinc oxide base requiring liquid eugenol activation supports bulk preparation protocols in hospital and institutional settings. This form sustains demand where centralized pharmacy services manage cement inventory.
- Liquid:Pure eugenol oil or modified resin vehicles for custom formulation adjustments by specialized practitioners. Direct clove oil extraction partnerships in Kerala and Zanzibar offer integrated manufacturers supply security.
- Gel:Thixotropic preparations for specific application techniques including periodontal packs and surgical dressings. Flavor-masking technology convergence creates premium positioning opportunities in pediatric and anxiety-prone patient management.
Paste dominates clinical workflows; Gel formulations are gaining share fastest in specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: German clinics prioritize biocompatibility documentation under EU MDR, while Indian operators emphasize cost-efficient retreatment protocols in rapidly scaling chains.
United States
Private dental service organizations drive demand for bundled cement-and-training procurement models. FDA Class II device oversight under 21 CFR 872.3275 requires substantial equivalence demonstrations that lengthen entry timelines for novel formulations. Smart dispensing system pilots concentrate in Texas and Florida multi-location practices seeking workflow standardization.
Germany
Dental clinics expand restorative workflows incorporating zinc eugenol materials with enhanced documentation packages. EU MDR clinical evaluation report mandates from German notified bodies create regulatory bottlenecks favoring established suppliers with pre-existing toxicology portfolios. Bavarian dental equipment clusters anchor technical education program bundling.
India
Corporate dental chains in Hyderabad and Chennai scale procurement of antimicrobial sealants for retreatment cases. CDSCO alignment with ISO 9917 standards imposes documentation-intensive clearance pathways on imported cements. Tier-two city clinic expansion concentrates demand growth in Telangana and Tamil Nadu.
China
Hospital procurement systems favor powder formulations compatible with bulk mixing protocols and centralized pharmacy services. NMPA medical device registration requires biocompatibility testing harmonized with international standards. Yangtze River Delta dental manufacturing clusters supply domestic formulators with zinc oxide feedstock.
Indonesia
Clove oil cultivation in Sulawesi and Maluku supplies eugenol feedstock to international formulators, exposing pricing to monsoon-driven yield volatility. Agricultural processing infrastructure limitations concentrate extraction capacity in Surabaya and Makassar industrial zones. Feedstock security concerns drive integrated manufacturers toward direct plantation partnerships.
Zinc Eugenol Market Competitive Environment
Capability concentration sits with specialized dental material formulators possessing in-house toxicology data generation; scale advantage sits with diversified chemical conglomerates commanding eugenol feedstock security. The vendor base stratifies into three tiers: equipment-integrated dental specialists, backward-integrated fragrance-chemical hybrids, and regional commodity formulators. Dominant competitive moves include backward integration into clove oil sourcing and aftermarket service unbundling into separable technical training revenue streams.
Among diversified chemical conglomerates, BASF SE and LANXESS exemplify the feedstock-integrated archetype through upstream control over eugenol derivative supply chains. Dentsply Sirona occupies a position representing the equipment-leveraged specialist tier, anchoring cement distribution through installed base technical education programs. Firmenich SE sits within the fragrance-technology crossover segment, occupying a position where sensory formulation expertise converges with dental material compliance requirements.
| Leading Market Players |
|---|
| Dupont |
| SOLVAY |
| Dow |
| BASF SE |
| Firmenich SE |
| LANXESS |
| International Flavors & Fragrances |
| Symrise |
| Dentsply Sirona |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Indonesian clove oil extraction facilities is compressing eugenol feedstock margins and forcing formulators toward long-term offtake contracts that lock in volume commitments while sacrificing pricing flexibility. This utilization dynamic cascades through zinc oxide procurement and final cement formulation, creating divergent cost structures between integrated manufacturers and commodity assemblers.
Pricing Analysis
Long-term offtake agreements dominate eugenol procurement, insulating large formulators from spot market volatility while smaller competitors absorb weather-driven price swings. Price differentiation hinges on ISO 9917 certification tier and after-sales technical education bundling, with premium tiers commanding substantial service attach rates. Pricing pressure stems from polymer-based cement substitution in aesthetic-sensitive applications. Hospital procurement committees exhibit highest price sensitivity due to bulk tender protocols, whereas corporate dental chains prioritize outcome predictability over per-unit cost minimization.
Supply Chain Analysis
Export-control regimes on agricultural biotechnology have minimal direct impact, though EU REACH documentation requirements functionally restrict eugenol derivative flows from non-compliant processors. Feedstock supply concentrates in Indonesia, Madagascar, and Comoros, with zinc oxide sourcing anchored in China and Germany. The chain draws from clove oil cultivation, zinc oxide refining, and flavor-masking additive production. Single-source vulnerability in Sulawesi and Maluku clove plantations exposes formulators to monsoon-driven yield disruption. Distribution runs through dental equipment OEMs, regional chemical distributors, and direct hospital contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical training and chairside support contracts are expanding at multiples of hardware growth, transforming zinc eugenol from commodity transaction into recurring service relationship. This service-attach layer rewards manufacturers with installed base leverage and penalizes pure-product competitors.
For Market Incumbents: Entrench position through backward integration into Kerala and Zanzibar clove oil extraction partnerships that neutralize feedstock volatility threats. Deepen regulatory moats by pre-building EU MDR clinical evaluation report portfolios ahead of smaller competitors. Prioritize smart dispensing system co-development with German dental service organizations to cement workflow dependency. For New Entrants and Emerging Players: Build out flavor-masking technology capabilities targeting pediatric and anxiety-prone patient segments where incumbent coverage remains thin. India's tier-two corporate dental chains represent the most penetrable geography, with procurement decisions increasingly influenced by bundled training rather than legacy supplier relationships. Pursue white-label manufacturing partnerships with established eugenol feedstock controllers to bypass capital-intensive toxicology data generation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-integrated dental specialists with captive technical education platforms, suggesting superior cash flow quality versus commodity formulators. Acquisition targets should display backward integration into clove oil sourcing or proprietary biocompatibility testing infrastructure. Watch for EU MDR approval timeline compression as signal of regulatory capacity advantage converting to market share capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clove Cultivation | Direct plantation partnerships in Kerala and Zanzibar neutralize Indonesian supply volatility. |
| EU MDR Clinical Evaluation Pre-Investment | Early toxicology portfolio builds de facto approval bottleneck against smaller formulators. |
| Smart Dispensing System Co-Development | German dental service organization pilots create workflow lock-in through digitized quality assurance. |
| Technical Education Service Unbundling | Hyderabad and Chennai chain contracts separate training revenue from product sales. |
| Flavor-Masking Technology Acquisition | Pediatric segment premium positioning leverages Firmenich SE sensory formulation expertise. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with dental material procurement managers, biomedical engineers at hospital purchasing committees, GPO contracts specialists, and clove oil extraction facility operators; and secondary validation through FDA 510(k) filings, EU MDR notified body guidance documents, CDSCO import clearance records, and ISO 9917 certification databases. Bottom-up demand modeling from clinic procurement volumes triangulated against top-down chemical feedstock consumption estimates.
Forecast inputs considered product type segmentation across paste, powder, liquid, and gel formulations; application splits between restorative dentistry, endodontics, and orthodontics; end-user differentiation among independent dentists, corporate chains, and hospitals; and geographic regulatory cluster variations. CAGRs derived from installed base expansion rates, retreatment case volume trajectories, and cement-to-equipment bundling penetration curves across the projection horizon.
Sensitivities concentrate around EU MDR approval timeline shifts, Indonesian monsoon patterns affecting clove yields, and polymer-based cement substitution rates in temporary restoration applications. Forecasts reflect documented assumptions on regulatory harmonization progress and corporate dental chain scaling trajectories. Material shifts in REACH compliance stringency or NMPA biocompatibility testing requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
Iron Phosphate Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
Special Boiling Point Solvents Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Ethyl Cellulose Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Acetum Market
Specialty Chemicals
Alkoxide Market
Specialty Chemicals
Alpha Bisabolol Market
Specialty Chemicals
Global Immersion Oil Market
Specialty Chemicals
Perfluoroalkoxy Alkane (PFA) Market
Specialty Chemicals
Ethyl Ascorbic Acid Market
Specialty Chemicals
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market