
 Europe Malic Acid Market | 2026-2036
Europe Malic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Malic Acid Market Insights
Project finance for fermentation-based production facilities is reconfiguring competitive entry barriers across the European malic acid landscape. Jungbunzlauer Suisse AG leverages its Swiss manufacturing base to dominate natural L-malic acid supply for premium food accounts. BASF SE anchors industrial-scale DL-malic acid output through integrated petrochemical feedstock access. Tate & Lyle PLC competes via specialty distribution networks serving beverage reformulation demand.
Malic acid is a dicarboxylic acid with molecular formula C4H6O5, existing as L-, D-, and racemic DL- stereoisomers, typically manufactured through petrochemical synthesis or bio-fermentation of carbohydrates using Aspergillus species; it functions primarily as an acidulant, pH buffer, and flavor enhancer across food, pharmaceutical, and cosmetic systems. The L-Malic Acid segment leads value generation due to natural-source labeling preferences among European food manufacturers, while DL-Malic Acid sustains volume share through cost-sensitive industrial applications. Powder form dominates pharmaceutical and food blending operations where precise dosing and extended shelf stability matter, whereas liquid malic acid concentrates in large-scale beverage production lines.
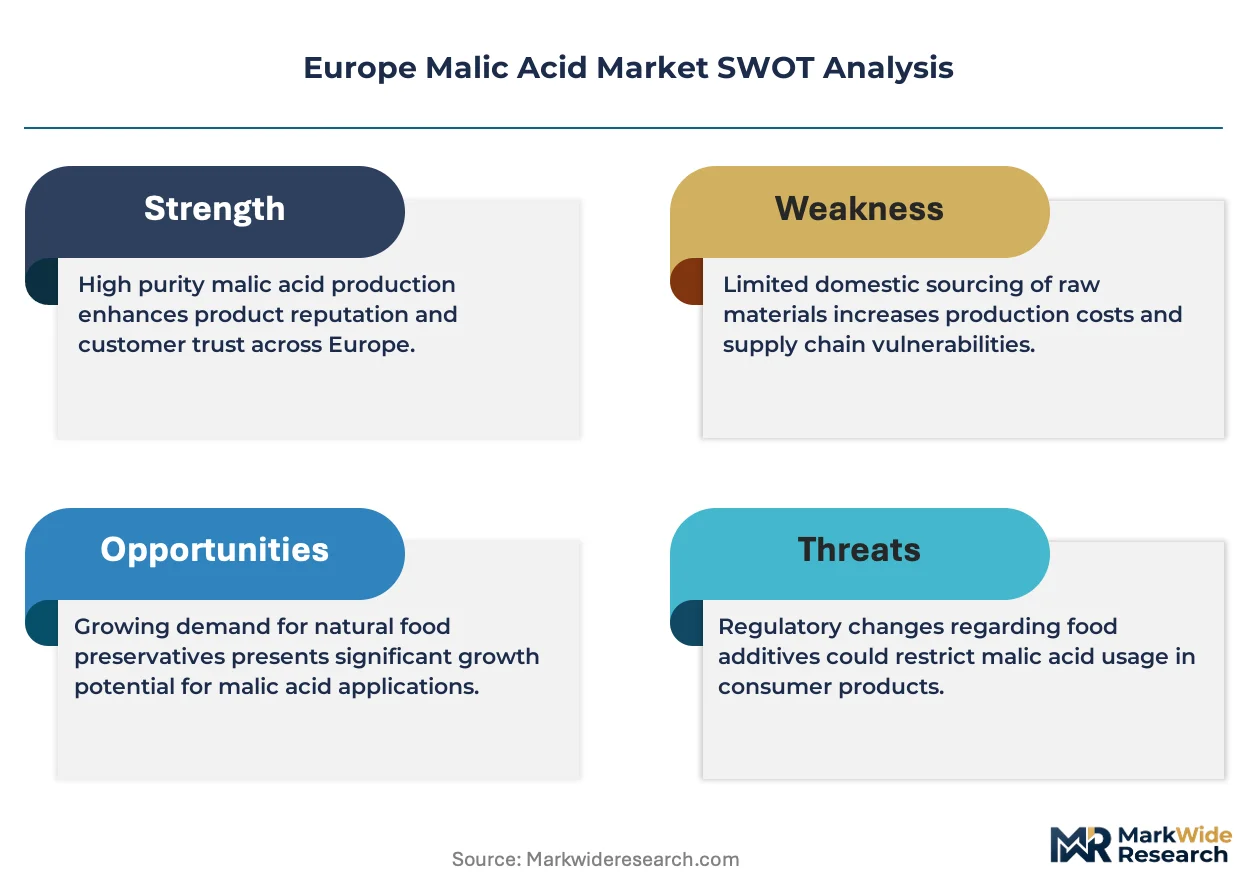
REACH registration requirements administered by ECHA constrain non-European suppliers and elevate compliance investments for market participants. The EU Green Deal and F-Gas Regulation indirectly shape malic acid demand by accelerating shifts toward bio-based acidulants in refrigerated food chains. Food manufacturers must monitor fermentation capacity buildouts and regulatory divergence between EU member states on natural claim definitions.
Market Dynamics
Fermentation technology maturation is compressing the cost gap between petrochemical-derived DL-malic acid and bio-based L-malic acid, forcing incumbent suppliers to reconfigure capital deployment toward carbohydrate feedstock processing. REACH registration burdens and ECHA compliance timelines simultaneously filter out marginal producers while rewarding integrated European manufacturers with captive fermentation capacity.
Growth Catalysts
- EU Green Deal bio-acidulant mandates:Refrigerated food chain decarbonization targets accelerate substitution of synthetic acidulants with fermentation-derived L-malic acid in beverage and confectionery applications.
- Clean-label formulation clusters:Western European food processing centers around Stuttgart and Lyon drive concentrated procurement of natural-source acidulants for premium product lines.
- F-Gas Regulation spillover:Cold chain equipment phase-outs indirectly stimulate demand for pH-stable bio-preservatives in temperature-sensitive packaged foods.
Market Restraints
- Carbohydrate feedstock volatility:Wheat and corn price swings directly compress fermentation-based L-malic acid margins versus petrochemical alternatives.
- REACH registration concentration:ECHA dossier preparation costs exceeding six figures exclude non-European suppliers from direct market access.
- Citric acid substitution:Lower-cost citric acid from Chinese fermentation capacity displaces malic acid in cost-sensitive industrial pH adjustment applications.
Strategic Opportunities
- Polish and Romanian food manufacturing expansion:Central European processing capacity buildouts create underpenetrated demand nodes for acidulant suppliers with regional distribution infrastructure.
- Pharmaceutical-grade certification:EMA excipient qualification pathways enable premium pricing for GMP-compliant L-malic acid in effervescent tablet formulations.
- Direct-to-blender digital channels:B2B platform procurement is collapsing traditional distributor markups for mid-sized beverage compounders seeking spot volume flexibility.
Industry Challenges
- Fermentation scale-up engineering:Aspergillus strain optimization and bioreactor design expertise shortages delay capacity expansion timelines for bio-based producers.
- Natural claim definitional divergence:Inconsistent member-state interpretations of EU natural labeling criteria create compliance uncertainty for cross-border food marketing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Malic Acid Market |
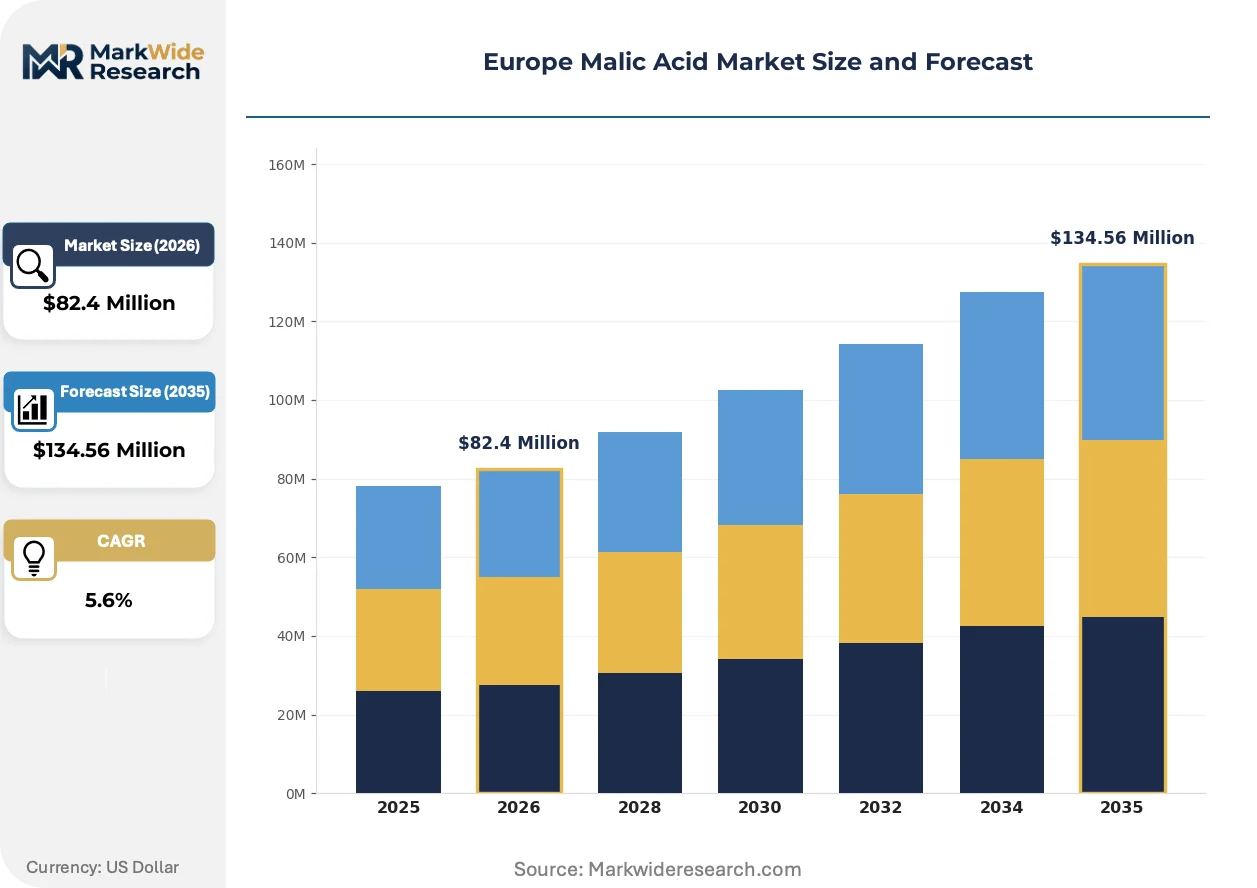
| Market Size in 2026 | $82.4 Million |
| Market Size in 2035 | $134.56 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Malic Acid, D-Malic Acid, DL-Malic Acid, Malate Application: Food & Beverage, Pharmaceuticals, Cosmetics, Agricultural End User: Food Manufacturers, Beverage Producers, Cosmetic Companies, Agricultural Firms Form: Liquid, Powder, Crystalline, Granular |
| Companies Covered | BASF SE, Tate & Lyle PLC, Jungbunzlauer Suisse AG, Polynt SpA, Cornelius Group, Lonza Group Ltd, Fuso Chemical Co., Ltd., Bartek Ingredients Inc., Thirumalai Chemicals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Malic Acid Market Trends and Innovations
Bio-fermentation process intensification is collapsing the historical cost premium of natural-source acidulants, while regulatory pressure on synthetic chemical portfolios accelerates reformulation timelines across European food manufacturing.
Continuous fermentation systems using immobilized cell technology are collapsing batch-to-batch variability in L-malic acid titer yields. German and Swiss ingredient suppliers deploy these systems to secure pharmaceutical-grade certification for effervescent and chewable dosage forms. The technology is collapsing quality-adjusted cost differentials between European bio-based output and Asian citric acid imports.
REACH substance evaluation under ECHA's 2023-2025 work program intensifies scrutiny of petrochemical-derived acidulants for persistent, bioaccumulative, and toxic properties. Industrial compounders face reformulation deadlines as member-state competent authorities advance restriction proposals. Food and beverage manufacturers accelerate natural-source acidulant qualification to preempt supply interruption risks.
Compounders in the Nordic markets now specify fermentation-derived L-malic acid in 80% of new beverage briefs, displacing synthetic DL grades previously accepted for cost optimization. Swedish and Danish retail chains enforce clean-label standards that cascade through their private-label supplier networks. This specification tightening is compressing synthetic acidulant volume share in premium beverage segments.
Europe Malic Acid Market Segmentation
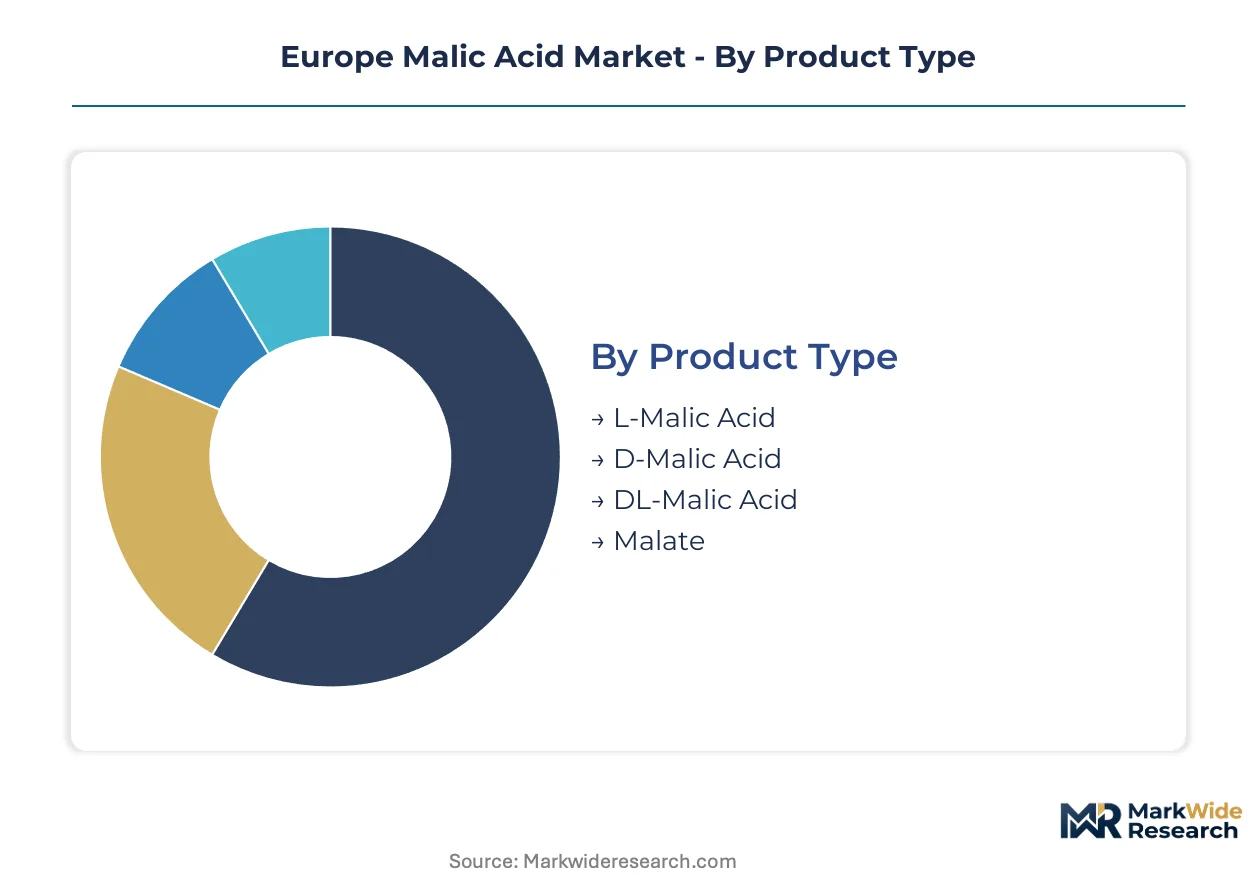
European malic acid procurement patterns diverge sharply across product grades and formulation requirements. Food manufacturers in Germany and France prioritize natural-source specifications, while industrial compounders balance acidulant performance against citric acid substitution economics.
Product Type:
Formulation chemists select malic acid stereoisomers based on labeling claims, thermal stability requirements, and cost-positioning against fermentation-derived alternatives.
- L-Malic Acid:The naturally occurring stereoisomer produced through carbohydrate fermentation using Aspergillus niger or A. oryzae strains. EFSA natural claim recognition drives premium positioning across Swiss and German confectionery houses seeking clean-label differentiation.
- DL-Malic Acid:Racemic mixture synthesized from maleic anhydride via hydration chemistry. Industrial pH adjustment applications in Eastern European metal finishing and textile processing sustain volume throughput despite REACH substance evaluation pressures.
- D-Malic Acid:Synthetic enantiomer with limited commercial production; specialty pharmaceutical applications requiring chiral purity specifications represent isolated demand pockets.
- Malate:Salt derivatives including calcium, sodium, and potassium malates deployed as buffering agents in sports nutrition and effervescent formulations.
Established volume favors DL-Malic Acid; emerging adoption favors L-Malic Acid.
Application:
End-use concentration tracks Western European food processing clusters and pharmaceutical excipient qualification pathways.
- Food & Beverage:Acidulant and flavor enhancement functions dominate procurement, with beverage compounders specifying malic acid for its tart, lingering taste profile distinct from citric acid sharpness. Stuttgart and Lyon formulation centers drive concentrated demand for natural-grade material.
- Pharmaceuticals:EMA excipient qualification requirements elevate GMP-grade L-malic acid pricing for tablet disintegration and pH buffering in effervescent dosage forms.
- Cosmetics:Alpha-hydroxy acid functionality in exfoliation products generates modest volume through Paris and Milan beauty formulation houses.
- Agricultural:Micronutrient chelation and feed acidification applications in Polish and Romanian livestock operations represent price-sensitive demand segments.
Pharmaceutical-grade certification commands premium positioning; food and beverage applications deliver volume scale.
End User:
Procurement sophistication varies across customer scale, with multinational food manufacturers enforcing supplier audit protocols unavailable to mid-tier compounders.
- Food Manufacturers:Confectionery and bakery operations across Belgium and the Netherlands specify fermentation-derived acidulants for premium product lines.
- Beverage Producers:Carbonated and still drink formulators in Sweden and Denmark cascade clean-label requirements through private-label supplier networks.
- Cosmetic Companies:R&D-driven ingredient selection prioritizes INCI listing compliance and dermatological testing documentation.
- Agricultural Firms:Feed additive procurement emphasizes cost-per-unit acidification versus performance optimization.
Beverage producers are expanding specification fastest; agricultural firms remain most price-elastic.
Form:
Physical state selection reflects handling infrastructure, dosing precision requirements, and dissolution kinetics in target applications.
- Powder:Free-flowing material with defined particle size distribution enables precise batch weighing in pharmaceutical tableting and dry food blending operations. German contract manufacturers prefer this form for GMP environment compatibility.
- Liquid:Aqueous solutions or concentrated syrups integrate directly into large-scale beverage production lines, eliminating dissolution steps and reducing dust exposure. French mineral water bottlers specify liquid delivery for continuous processing efficiency.
- Crystalline:High-purity solid form supporting extended shelf stability and controlled release characteristics in specialty pharmaceutical applications.
- Granular:Intermediate particle size reducing caking tendency versus fine powders while maintaining rapid dissolution in beverage systems.
Powder form anchors pharmaceutical and food blending; liquid concentrates gain share in automated beverage production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European malic acid procurement concentrates among multinational food manufacturers with clean-label mandates, regional beverage compounders seeking acidulant differentiation, and pharmaceutical excipient formulators requiring GMP certification. These buyer archetypes cluster in Western European processing hubs and emerging Central European manufacturing zones.
Germany
Stuttgart and Munich formulation centers drive concentrated demand for fermentation-derived L-malic acid in premium confectionery and bakery applications. EFSA natural claim recognition under EU Regulation 1169/2011 shapes supplier qualification protocols for clean-label product lines. BASF SE anchors industrial-scale DL-malic acid production through integrated petrochemical feedstock access in Ludwigshafen.
France
Lyon beverage compounding clusters specify natural-source acidulants for mineral water and carbonated drink reformulations. REACH registration requirements administered by ECHA elevate compliance investments for non-European suppliers seeking market entry. Parisian beauty formulation houses generate modest volume for alpha-hydroxy acid applications in exfoliation products.
Switzerland
Jungbunzlauer Suisse AG leverages its Swiss manufacturing base to dominate natural L-malic acid supply for premium food accounts across Alpine and adjacent markets. Swissmedic pharmaceutical-grade certification pathways enable premium pricing for GMP-compliant excipients in effervescent tablet formulations. Basel pharmaceutical clusters anchor regional demand for high-purity acidulant grades.
Sweden
Retail chains enforce clean-label standards that cascade through private-label supplier networks, with Nordic beverage briefs now specifying fermentation-derived L-malic acid in premium segments. EU Green Deal bio-acidulant mandates accelerate substitution of synthetic acidulants in refrigerated food chains. Stockholm and Copenhagen formulation centers drive specification tightening across Scandinavian markets.
Poland
Central European food manufacturing expansion creates underpenetrated demand nodes for acidulant suppliers with regional distribution infrastructure. Agricultural feed additive procurement emphasizes cost-per-unit acidification in livestock operations. Warsaw and Łódź processing capacity buildouts attract acidulant distributors seeking volume growth beyond saturated Western European markets.
Europe Malic Acid Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Integrated European manufacturers with captive fermentation capacity capture premium positioning through REACH compliance and natural-source certification. Three archetypes dominate: petrochemical-derived DL-malic acid producers, bio-fermentation L-malic acid specialists, and regional distribution intermediaries serving mid-tier compounders. Competitive moves concentrate on capacity expansion in carbohydrate feedstock processing and strategic partnerships securing pharmaceutical-grade certification pathways.
Within the integrated manufacturing tier, Jungbunzlauer Suisse AG and BASF SE exemplify divergent feedstock strategies—bio-fermentation versus petrochemical synthesis—while Tate & Lyle PLC occupies a position bridging specialty distribution with beverage reformulation demand. These three companies represent the structural fault lines between natural-source and synthetic acidulant positioning, with each archetype commanding distinct price premiums based on certification grade and end-use specification intensity.
| Leading Market Players |
|---|
| BASF SE |
| Tate & Lyle PLC |
| Jungbunzlauer Suisse AG |
| Polynt SpA |
| Cornelius Group |
| Lonza Group Ltd |
| Fuso Chemical Co., Ltd. |
| Bartek Ingredients Inc. |
| Thirumalai Chemicals |
| Others |
Pricing and Supply Chain Analysis
Ludwigshafen's petrochemical complex anchors synthetic DL-malic acid capacity, while Swiss fermentation facilities command premium positioning through EFSA natural claim certification. This geographic bifurcation concentrates pricing power among integrated manufacturers with captive carbohydrate processing or maleic anhydride access, forcing distributors and compounders into volume-commitment contracts that transfer feedstock volatility risk downstream.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade GMP material and industrial pH-adjustment grades. Three-tier pricing structure across premium natural-source, standard synthetic-food, and economy industrial grades reflects EMA excipient qualification costs and REACH registration investments. Cost compression in synthetic DL grades is intensifying because Asian citric acid imports displace volume in metal finishing applications. Agricultural feed additive buyers exhibit highest price elasticity, while Swiss confectionery houses accept substantial premiums for EFSA-compliant natural labeling.
Supply Chain Analysis
Carbohydrate feedstock sourcing from German and French wheat processing centers feeds fermentation-based L-malic acid production, while maleic anhydride streams from Ludwigshafen petrochemical operations supply synthetic DL output. Wheat and corn price volatility constitutes the dominant supply chain risk, compressing bio-based margins during commodity spikes. Distribution runs through specialty chemical distributors serving beverage compounders in Lyon and Stuttgart, with direct-to-blender digital procurement emerging for mid-sized accounts seeking spot volume flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's malic acid market is recovering from cyclical feedstock cost compression as fermentation technology maturation restores bio-based competitiveness against petrochemical alternatives.
For Market Incumbents: Harden natural-source certification moats through Swissmedic pharmaceutical-grade qualification and EFSA clean-label recognition investments. Expand carbohydrate fermentation capacity in Central European processing corridors to preempt Polish and Romanian demand buildouts. Citric acid substitution in industrial pH applications represents the primary volume threat requiring cost-positioning responses. For New Entrants and Emerging Players: Mid-tier beverage compounders in Poland and Romania seeking spot volume flexibility represent the most penetrable entry point for regional distribution infrastructure investments. Pharmaceutical-grade GMP certification gaps among established suppliers create white-space for excipient-focused entrants. Direct-to-blender digital procurement platforms offer the strongest go-to-market angle for bypassing incumbent distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-capable assets with REACH registration dossiers and established EFSA natural claim pathways. Long-term viability rests on carbohydrate feedstock processing economics displacing maleic anhydride dependence. Watch Aspergillus strain optimization breakthroughs as the inflection signal for bio-based cost parity achievement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbohydrate Feedstock Processing | Captive wheat and corn supply secures margin stability against commodity volatility for fermentation-based producers. |
| Swissmedic Pharmaceutical-Grade Certification | GMP-compliant L-malic acid unlocks premium pricing in Basel effervescent tablet formulation clusters. |
| Direct-to-Blender Digital Channel Development | B2B platform procurement collapses distributor markups for Lyon and Stuttgart beverage compounders. |
| Polish Distribution Infrastructure Expansion | Warsaw and Łódź processing capacity buildouts create underpenetrated demand nodes beyond saturated Western markets. |
| Continuous Fermentation Technology Deployment | Immobilized cell systems collapse batch variability for pharmaceutical-grade titer yield consistency. |
Research Methodology
Desk research of ECHA registration databases, EU trade statistics, and Cefic chemical industry reports preceded structured interviews with fermentation plant managers, beverage procurement leads at compounders, specialty chemical distributors, and EMA regulatory affairs specialists. Primary fieldwork captured capacity utilization rates, certification timeline experiences, and reformulation decision criteria across Stuttgart, Lyon, and Basel formulation centers. Secondary validation drew from SEC filings of listed ingredient suppliers, customs import data, and EFSA natural claim guidance documents. Bottom-up volume modeling triangulated against top-down market sizing from production capacity aggregates.
Assumptions held fixed include REACH regulatory framework continuity and EFSA natural labeling criteria interpretation stability, while carbohydrate feedstock price trajectories and citric acid substitution elasticity were varied across sensitivity scenarios. Segmentation dimensions encompassed stereoisomer grade, end-use application intensity, certification tier, and regional manufacturing cluster. CAGRs were derived from production capacity expansion announcements, demand elasticity estimates from beverage reformulation briefs, and historical price-volume relationships across the projection horizon. Fermentation yield improvement curves and petrochemical feedstock cost pass-through mechanisms served as industry-specific forecast inputs.
Practitioners should monitor ECHA substance evaluation outcomes for petrochemical-derived acidulants and Aspergillus strain optimization breakthroughs for early signals of competitive cost structure shifts. Forecasts reflect assumptions about regulatory continuity and technology diffusion rates that carbohydrate price spikes or REACH restriction proposals could materially revise. Cross-checking against Cefic acidulant trade flow data and EFSA natural claim approval timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Global Metal Chelates Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
Acesulfame Potassium Market
Specialty Chemicals
Fatty Acid Methyl Ester Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Mequinol Market
Specialty Chemicals
Synthetic and Bio-Based Adipic Acid Market
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
Silicone Oil Market
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
Sialic Acid Market
Specialty Chemicals
Rosin Market
Specialty Chemicals
Bio-Based Phenol Market