
 Global Aerosol Market | 2026-2036
Global Aerosol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerosol Market Analysis
Fragmentation across emerging retail consumers and service providers is repositioning procurement patterns throughout the aerosol value chain. Procter & Gamble leverages its brand strength to dominate shelf space in mass-market personal care aerosols across North America. Henkel sustains manufacturing scale advantages in European household cleaning aerosols through integrated production networks. SC Johnson anchors its competitive stance via specialized expertise in insecticide formulations and controlled-release technologies.
Aerosol denotes a suspension of fine solid particles or liquid droplets in a gas, typically packaged under pressure with propellants such as liquefied petroleum gas, dimethyl ether, or compressed gases in aluminum or tinplate containers, serving industrial coating, personal care delivery, and sanitation functions. Personal care aerosols command established margin pools due to premium pricing on deodorants and hair sprays, while bag-on-valve packaging competes aggressively in cosmetics and food applications by eliminating traditional propellant contact with contents. Industrial aerosols occupy a mature trajectory in paints and lubricants, whereas cleaning product applications lead volume expansion through institutional and healthcare sanitation protocols.
The EPA regulates volatile organic compound emissions from aerosol products under the Clean Air Act, while REACH governs chemical safety and propellant substitutions across European supply chains, and India's BIS mandates container pressure standards for domestic manufacturers. These frameworks force reformulation investments and regional compliance divergence that shapes market access costs. Stakeholders must monitor propellant transition timelines and packaging material recyclability mandates to align capacity decisions with evolving enforcement intensity.
Market Dynamics
Propellant chemistry transitions under REACH and the EU F-Gas Regulation are forcing simultaneous reformulation across European supply chains while Indian urban households accelerate aerosol consumption patterns. This dual pressure compresses R&D timelines and reallocates manufacturing capacity toward compliant chemistries.
Growth Catalysts
- Bag-on-valve packaging:Cosmetic and food-grade applications in Germany and France are adopting this technology to eliminate propellant-content contact. Premium positioning in skincare aerosols supports margin expansion.
- India BIS container standards:Domestic manufacturing compliance mandates are formalizing quality tiers that favor organized producers with testing infrastructure. Urban household penetration of automotive and cleaning aerosols accelerates.
- Healthcare sanitation protocols:Institutional cleaning aerosol volumes are expanding in US hospital systems and Japanese medical facilities. Surface disinfection specifications now require validated spray distribution.
Market Restraints
- Aluminum sheet supply concentration:Rolled aluminum for aerosol cans concentrates among Chinese and Gulf smelter networks. Container producers face input cost volatility and extended lead times.
- Dimethyl ether feedstock exposure:Methanol-to-DME conversion economics tie propellant costs to natural gas and coal pricing in key production zones. Formulators lack short-term hedging instruments.
- REACH substance evaluation timelines:ECHA's rolling review of existing propellant chemistries creates uncertainty windows. Product registration investments face stranded risk if candidate list expansions accelerate.
Strategic Opportunities
- Brazil ANVISA pharmaceutical aerosol pathway:Inhalation drug delivery systems remain underpenetrated relative to North American and European markets. Local partnership requirements favor early regulatory engagement.
- Compressed gas propellant convergence:Nitrogen and compressed air systems are converging with precision valve engineering to enable water-based formulations. Personal care brands in Nordic markets pilot these platforms.
- EU Green Deal packaging recyclability mandates:Mono-material aluminum can designs and tethered cap requirements create specification windows. First-movers capture retailer shelf-space commitments.
Industry Challenges
- Propellant formulation chemistry expertise:Fluorocarbon phase-out timelines compress the available talent pool for alternative stability testing. Cross-functional teams spanning toxicology and materials science command premium compensation.
- Legacy filling line reconfiguration:Bag-on-valve and compressed gas systems require capital-intensive retooling. Mid-tier contract manufacturers face make-or-buy decisions on specialized equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerosol Market |
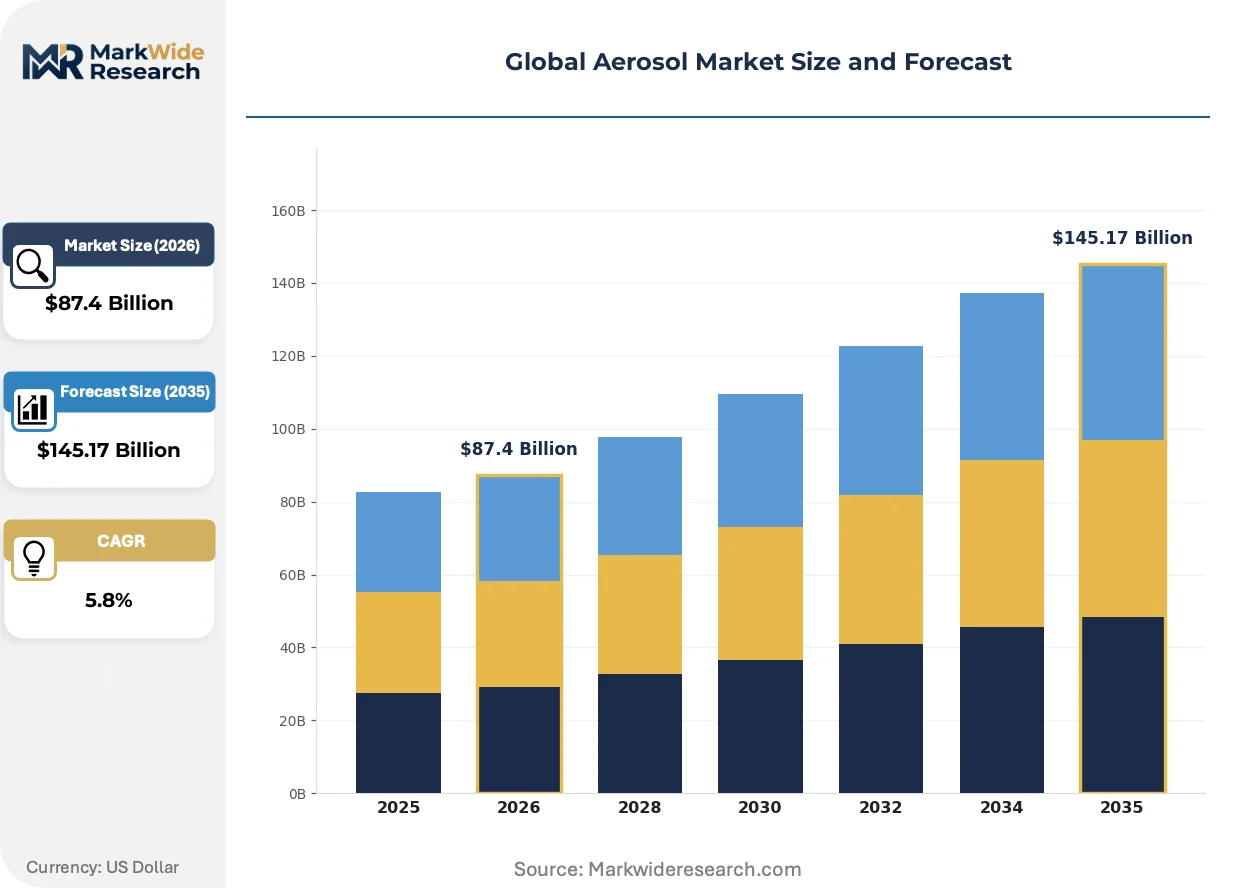
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $145.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Care, Household, Industrial, Automotive Packaging Type: Aerosol Can, Pump Spray, Non-aerosol Container, Bag-on-valve End User: Retail Consumers, Manufacturers, Distributors, Service Providers Application: Cosmetics, Cleaning Products, Insecticides, Paints |
| Companies Covered | 3M, SC Johnson, Ball Corporation, Crown Holdings, AptarGroup, Berry Global, Henkel, Procter & Gamble, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerosol Market Emerging Trajectories
Reformulation imperatives are intersecting with packaging engineering advances to redefine product architecture across personal care, industrial, and food-grade segments. Technical differentiation now centers on propellant-content separation and precision delivery mechanisms.
Bag-on-valve systems are converging with high-viscosity cosmetic formulations to enable preservative-free skincare aerosols. Premium beauty brands in South Korea and France are piloting these platforms for serum and mask applications. The technology compresses traditional preservative load requirements while extending claimed shelf stability.
ECHA's F-Gas Regulation phasedown mandates are forcing hydrofluorocarbon propellant substitution in metered-dose inhalers and technical aerosols. German and Italian formulators are accelerating dimethyl ether and hydrocarbon blends. Medical device manufacturers face the steepest compliance curves given validation protocol requirements.
Direct-to-consumer subscription models are displacing conventional retail replenishment cycles for household cleaning aerosols. US and UK digitally native brands are capturing recurring revenue through concentrated refill formats. This channel rotation compresses traditional distributor margins while demanding flexible contract manufacturing volumes.
Global Aerosol Market Segmentation
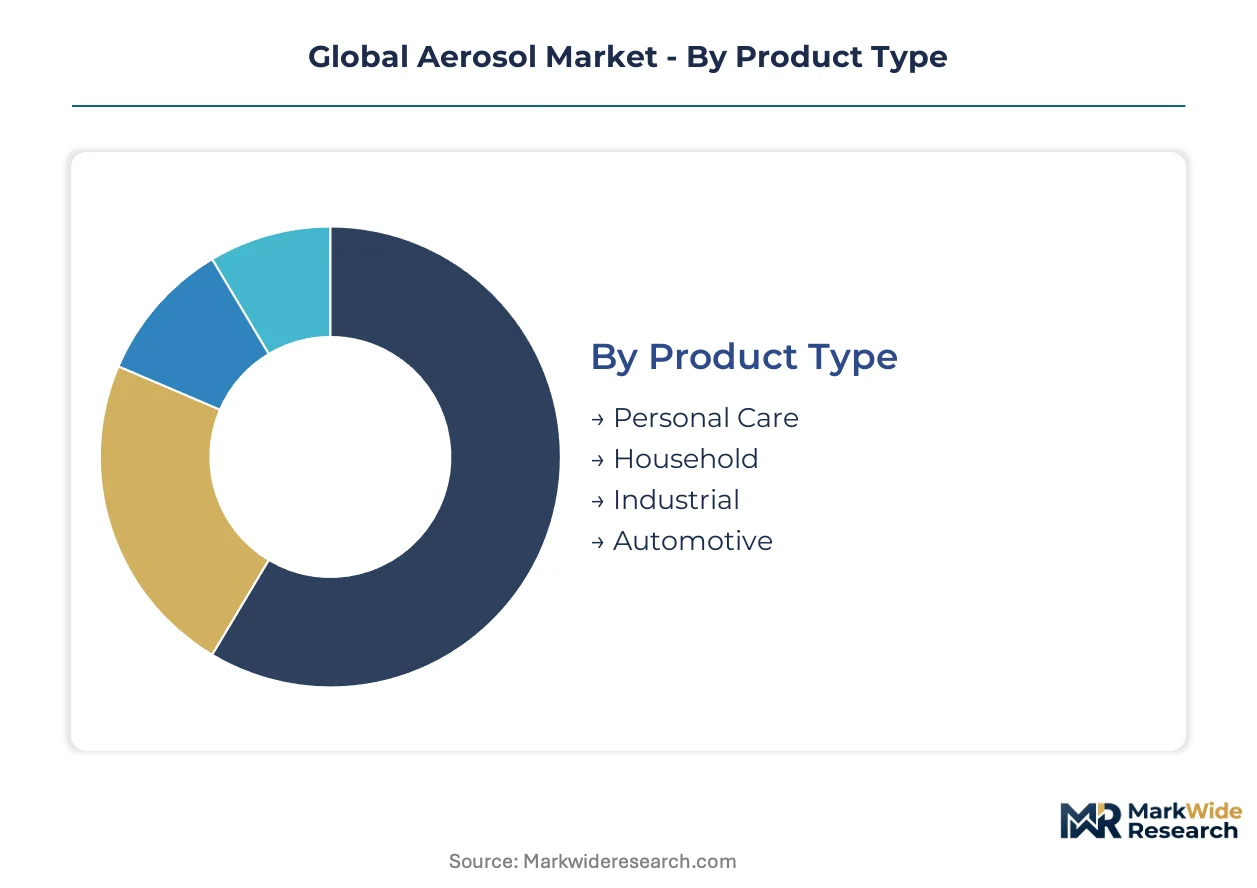
Segmentation in the aerosol market reveals how propellant chemistry, packaging engineering, and distribution channel requirements fragment procurement decisions. Formulators align R&D investments with the technical specifications and margin profiles of distinct product architectures.
Product Type:
Propellant selection and pressure specifications vary sharply across functional use cases, determining aluminum gauge requirements and valve engineering complexity.
- Personal Care:Deodorants and hair sprays utilize hydrocarbon propellants in standard-pressure aluminum cans. Demand concentrates in US and German retail channels where premium pricing supports fragrance-loaded formulations.
- Household:Surface cleaners and air fresheners deploy dimethyl ether blends for solvency compatibility. Indian urban households accelerate volume expansion as BIS-compliant domestic manufacturing scales.
- Industrial:Coatings and lubricants require high-pressure tinplate construction for solvent resistance. Mature deployment sits with industrial maintenance aerosols. Newer deployment is concentrated in precision electronics cleaning formulations.
- Automotive:Brake cleaners and tire shines specify low-residue propellant systems. Aftermarket distributors in Brazil and Mexico drive regional formulation customization.
Mature deployment sits with Household. Newer deployment is concentrated in Personal Care.
Packaging Type:
Container architecture directly determines propellant-content contact protocols, recyclability compliance, and filling line capital requirements.
- Aerosol Can:Rolled aluminum or tinplate cylinders with internal bag separation dominate high-volume production. REACH and EU F-Gas Regulation timelines force simultaneous reformulation across European supply chains.
- Bag-on-valve:Laminated film bags welded to aerosol valves eliminate propellant-product contact. South Korean and French cosmetic brands pilot preservative-free skincare applications with extended shelf stability claims.
- Pump Spray:Mechanical pressure systems bypass compressed propellants entirely. US institutional cleaning contracts specify pump formats for healthcare sanitation protocols.
- Non-aerosol Container:Trigger sprayers and squeeze bottles serve price-sensitive segments. Dollar-store distribution in India favors these formats for household cleaning penetration.
Volume leadership rests with Aerosol Can. Technology investment flows toward Bag-on-valve.
End User:
Procurement scale and specification authority fragment across channel types, reshaping contract manufacturing priorities.
- Retail Consumers:Individual purchase decisions favor brand recognition and shelf visibility. Mass-market personal care aerosols in North American drugstores command premium placement fees.
- Manufacturers:Industrial buyers specify technical aerosols for in-process coating and maintenance. Japanese automotive OEMs validate spray distribution tolerances for production-line integration.
- Distributors:Wholesale intermediaries aggregate fragmented demand across independent repair shops. Brazilian aftermarket networks require localized labeling and propellant registration.
- Service Providers:Fleet maintenance and facility management contractors purchase institutional cleaning aerosols under multi-year supply agreements. US hospital systems mandate validated surface disinfection specifications.
Margin compression hits Distributors. Specification authority concentrates with Manufacturers.
Application:
Formulation chemistry and regulatory classification diverge across end-use scenarios, determining registration pathways and channel access.
- Cosmetics:Skincare and fragrance aerosols require cosmetic-grade propellant purity and preservative optimization. Nordic personal care brands pilot compressed nitrogen platforms for water-based formulations.
- Cleaning Products:Surface disinfectants and degreasers balance efficacy against VOC emission limits. EPA Clean Air Act enforcement shapes US formulator compliance investments.
- Insecticides:Pyrethroid and botanical formulations demand specialized valve actuators for droplet size control. SC Johnson anchors market position via controlled-release expertise.
- Paints:Touch-up and marking aerosols specify pigment suspension stability under pressure. Industrial maintenance applications in German manufacturing clusters sustain volume.
Regulatory scrutiny intensifies for Insecticides. Formulation innovation concentrates in Cosmetics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration clusters in Germany, the United States, India, Japan, and Brazil, where distinct regulatory pressures and industrial ecosystems reshape procurement patterns for aerosol formulators and packaging suppliers.
United States
Hospital sanitation protocols and automotive aftermarket maintenance sustain institutional and retail aerosol volumes. EPA Clean Air Act enforcement on volatile organic compound emissions forces continuous reformulation investments by domestic formulators. Gulf Coast petrochemical corridors supply hydrocarbon propellant feedstocks to regional filling operations.
Germany
Cosmetic bag-on-valve adoption and pharmaceutical metered-dose inhaler production concentrate precision aerosol demand. ECHA's REACH substance evaluations and F-Gas Regulation phasedown mandates accelerate hydrofluorocarbon substitution timelines. Industrial clusters in North Rhine-Westphalia host specialized propellant blending and valve engineering facilities.
India
Urban household penetration of cleaning and automotive aerosols accelerates as organized retail expands in metropolitan centers. BIS container pressure standards formalize quality tiers that favor domestic manufacturers with testing infrastructure. Manufacturing corridors in Maharashtra and Gujarat scale aluminum can production for regional consumer goods brands.
Japan
Medical facility surface disinfection specifications and precision electronics cleaning sustain technical aerosol demand. METI industrial standards govern compressed gas propellant systems for water-based formulations. Kanto region contract manufacturers validate spray distribution tolerances for automotive OEM integration.
Brazil
Aftermarket automotive maintenance and household insecticide applications drive volume expansion across independent retail channels. ANVISA pharmaceutical aerosol registration pathways remain underpenetrated relative to developed markets. São Paulo industrial zones concentrate localized labeling and propellant registration capabilities for regional distribution networks.
Global Aerosol Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue preservative-free cosmetic platforms and compressed gas delivery systems. The market structures around three tiers: multinational consumer goods conglomerates with captive brand portfolios, specialized industrial formulators with technical validation capabilities, and regional contract manufacturers serving private-label demand. Strategic moves concentrate on bag-on-valve filling line investments and mono-material aluminum can designs aligned with EU Green Deal recyclability mandates.
Within the multinational tier, Procter & Gamble and Henkel exemplify divergent geographic anchoring strategies, with the former representing North American mass-market dominance and the latter illustrating European integrated production scale. SC Johnson occupies a specialist position exemplifying controlled-release formulation expertise. These three entities represent distinct competitive archetypes: brand-led shelf-space capture, manufacturing-scale efficiency, and technical differentiation through proprietary delivery mechanisms.
| Leading Market Players |
|---|
| 3M |
| SC Johnson |
| Ball Corporation |
| Crown Holdings |
| AptarGroup |
| Berry Global |
| Henkel |
| Procter & Gamble |
| Unilever |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange aluminum price volatility cascades through aerosol can manufacturing into three-tier pricing structure across premium, standard, and economy levels, with REACH-compliant propellant formulations commanding certification premiums and Indian BIS-grade containers anchoring mid-market positioning.
Pricing Analysis
Volume-mass personal care aerosols in North American drugstores operate on thin margins driven by shelf-space fees and promotional intensity, while bag-on-valve cosmetic platforms in Germany and France capture premium positioning through preservative-free claims and extended stability validation. Price differentiation hinges on propellant certification tier and aluminum gauge specification, with pharmaceutical-grade metered-dose inhalers showing lowest price sensitivity due to regulatory validation requirements. Cost compression in standard-pressure household cleaning aerosols is intensifying because dimethyl ether feedstock ties to volatile methanol pricing.
Supply Chain Analysis
Direct-to-retail channels handle mass-market personal care volumes through Procter & Gamble and Henkel captive distribution networks, while contract manufacturers serve private-label demand via wholesale intermediaries. Rolled aluminum supply concentrates in Chinese and Gulf smelter networks, with dimethyl ether production anchored in coal-rich Chinese provinces and natural gas-based Middle Eastern facilities. Single-source vulnerability sits with specialized valve engineering from German and Italian precision component suppliers. Distribution runs through Brazilian aftermarket networks for localized automotive aerosol labeling and Indian organized retail expansion for urban household penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerosol sector sits in a propellant chemistry transition phase, with compressed nitrogen and air-based systems displacing hydrocarbon and fluorocarbon platforms across Nordic personal care and Japanese medical device applications.
For Market Incumbents: Lock in mono-material aluminum can supply agreements ahead of EU Green Deal recyclability mandates, and accelerate backward integration into propellant blending capacity in North Rhine-Westphalia to offset REACH substance evaluation uncertainty. Hydrocarbon propellant phase-out timelines threaten stranded formulation investments; captive valve engineering capabilities provide defensive moats.
For New Entrants and Emerging Players: Digitally native subscription platforms offer white-space entry for concentrated refill formats in US and UK household cleaning segments, with Brazilian ANVISA pharmaceutical aerosol pathways showing underpenetrated inhalation drug delivery potential. Direct-to-consumer channel partnerships bypass traditional distributor margin compression.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier contract manufacturers with bag-on-valve filling line investments in Maharashtra and Gujarat, where BIS compliance formalization is consolidating quality tiers. Long-term viability hinges on propellant-transition execution capability; monitor ECHA candidate list expansion velocity as inflection signal for stranded asset risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Propellant Chemistry Transition | Compressed nitrogen platforms enable water-based cosmetic formulations for Nordic personal care brands. |
| Bag-on-Valve Capacity Expansion | South Korean and French cosmetic pilots validate preservative-free skincare aerosol shelf stability claims. |
| Mono-Material Aluminum Can Design | EU Green Deal tethered cap requirements create first-mover shelf-space capture with retailer commitments. |
| Backward Integration into Propellant Blending | German industrial clusters secure dimethyl ether supply continuity amid methanol price volatility. |
| Direct-to-Consumer Channel Development | US digitally native brands displace traditional distributor margins through concentrated refill subscriptions. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with aerosol plant managers, procurement leads at personal care OEMs, distribution channel partners, and technical R&D directors. ECHA substance evaluation databases, EPA Clean Air Act enforcement records, BIS certification registries, and aluminum trade statistics provided validation layers. Bottom-up volume modeling across propellant types and packaging formats triangulated against top-down consumer expenditure patterns.
Segment-level granularity modeled propellant chemistry, container architecture, end-use application, and regional regulatory cluster across the analysis window. CAGRs derived from fitted growth curves applied to base-year consumption estimates, with cross-validation against aluminum can production capacity announcements and propellant feedstock supply forecasts. Dimethyl ether methanol conversion economics and compressed gas valve engineering adoption curves informed scenario-weighted projections.
Several conditions sit outside the modeled scope, including abrupt REACH candidate list expansions, aluminum tariff regime shifts, and pandemic-resurgence sanitation demand spikes. Forecasts reflect base-case assumptions around regulatory phasedown timelines and urban household penetration rates in India. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Isophytol Market
Specialty Chemicals
Biobased Propylene Glycol Market
Specialty Chemicals
Phytosphingosine Market
Specialty Chemicals
Global Vinyl Sulfone Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
Alkoxide Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
Multimodal Chromatography Columns Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Shikimic Acid Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
Food Grade Paraffin Market