
 Automotive Radiator Grille Market | 2026-2036
Automotive Radiator Grille Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Radiator Grille Market Analysis
Polypropylene is repositioning steel in lower-cost grille assemblies, cutting weight and enabling complex mold geometries for tier-one suppliers. Plastic Omnium SE leverages its injection-molding scale to dominate European OEM programs. Magna International Inc. sustains North American share through backward integration into paint and finishing operations. Toyoda Gosei Co. Ltd. anchors Asian supply chains with JIS-certified thermal-cycle durability testing.
An automotive radiator grille is a protective and decorative front-facing panel, typically molded from ABS, polycarbonate, or painted metal, designed to permit airflow to the cooling system while shielding radiators and condensers from road debris. The component integrates with active shutter systems to modulate drag coefficient and engine warm-up times across drive cycles. Plastic grilles lead volume in mass-market sedans where cost-per-unit and styling flexibility govern OEM sourcing decisions. Aluminum segments occupy the premium tier for SUVs and trucks, where surface finish durability and brand differentiation justify higher material outlays. Composite formulations represent the fastest-growing product category as thermal expansion coefficients improve and recycling pathways mature.
EPA Corporate Average Fuel Economy standards and Euro 7 emission protocols are tightening aerodynamic performance requirements, compelling grille suppliers to engineer active airflow management into every platform. NHTSA pedestrian-impact rules in the United States and ECE R127 regulations in Europe are reshaping grille edge radii and breakaway mounting designs, adding compliance cost but creating barrier-to-entry advantages for tested suppliers. Stakeholders must monitor how Chinese MIIT new-energy vehicle efficiency mandates and evolving GB standards for exterior plastic parts alter material qualification timelines and tooling investments.
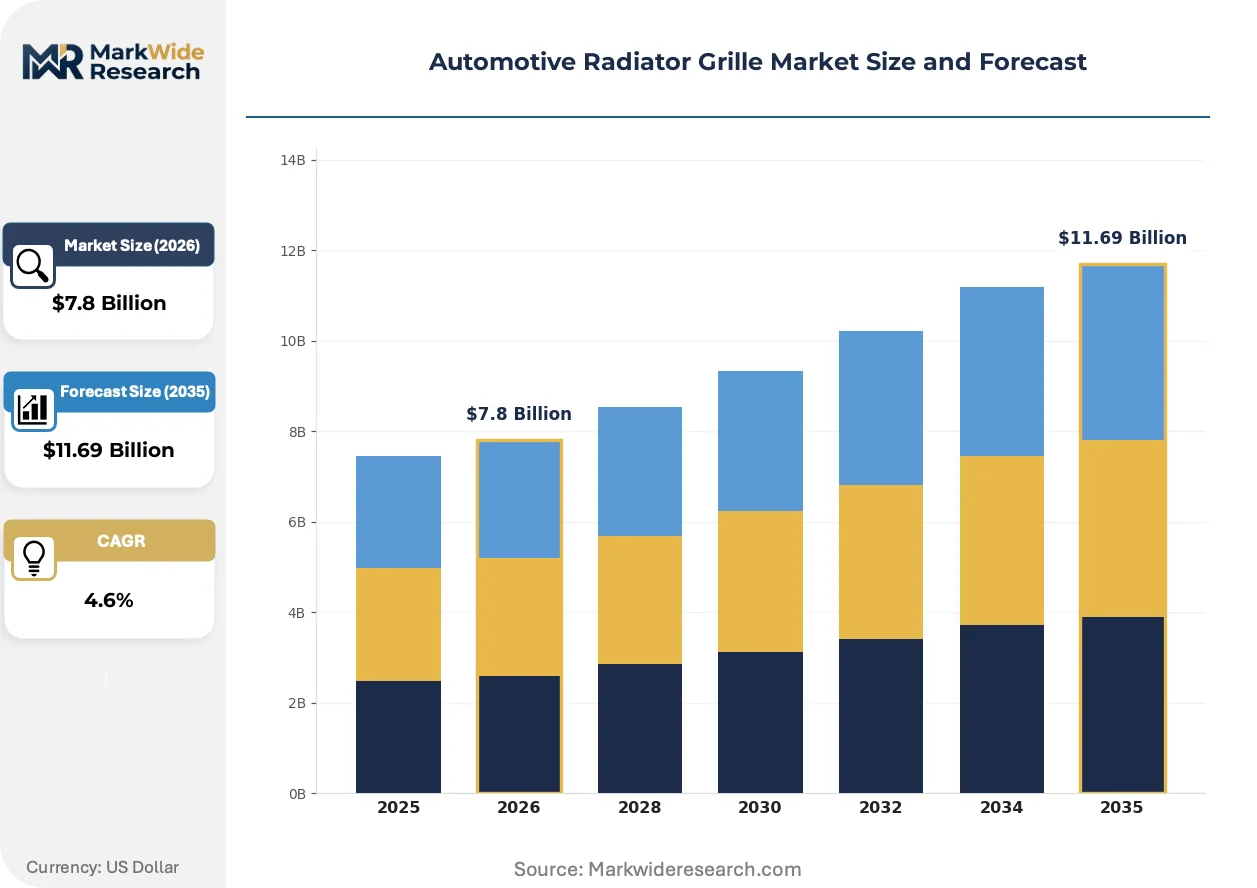
Market Dynamics
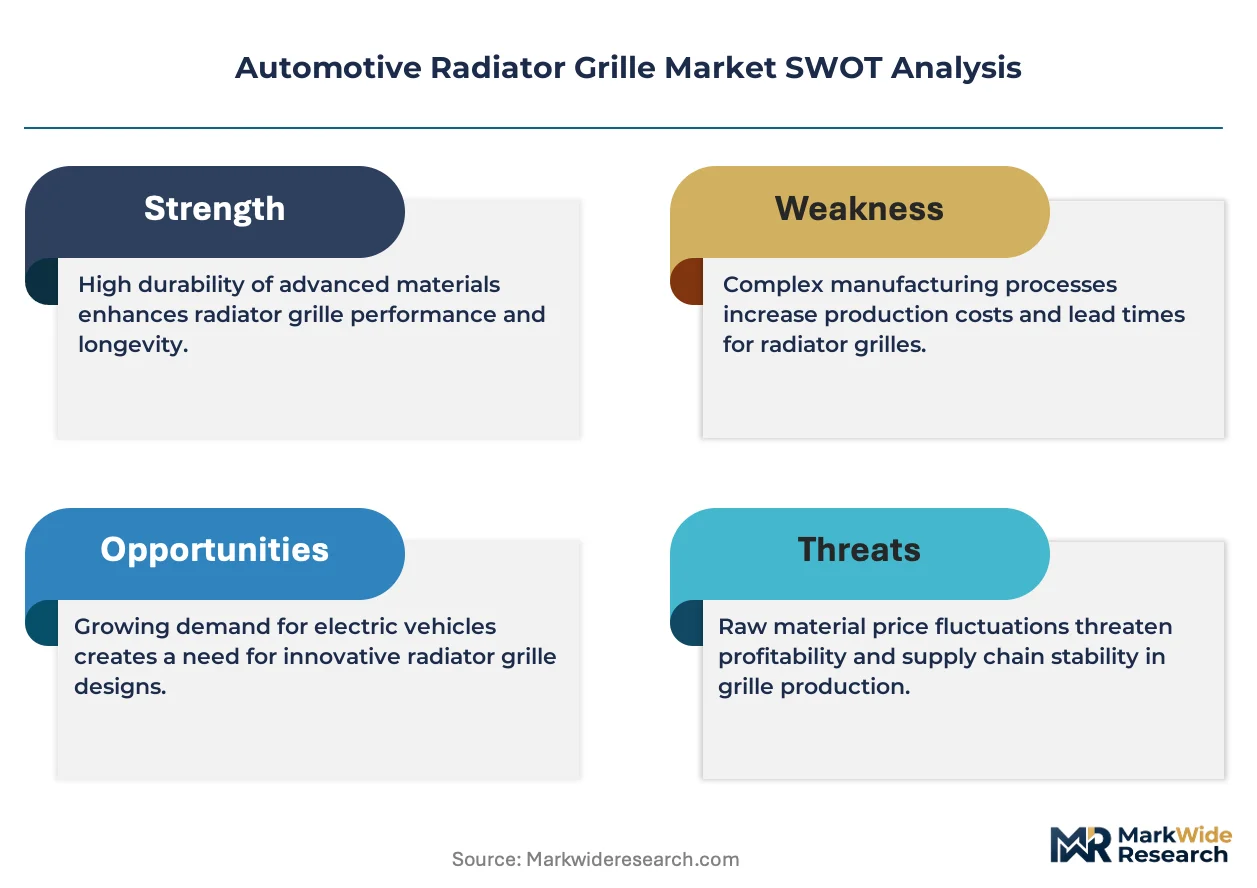
OEM procurement of lightweight composite grilles is accelerating as automakers pursue fuel-efficiency targets under Euro 7 and EPA tailpipe rules. Active grille shutter integration for thermal management optimization is becoming a standard specification across new vehicle platforms.
Growth Catalysts
- Euro 7 emission protocols:Tightening aerodynamic performance requirements compel grille suppliers to engineer active airflow management into every platform.
- Polypropylene substitution:The material is repositioning steel in lower-cost grille assemblies, cutting weight and enabling complex mold geometries for tier-one suppliers.
- China EV thermal management:Domestic electric vehicle brands prioritize active grille shutter integration, driving specialized component demand.
Market Restraints
- Aluminum input cost volatility:Premium-tier SUV and truck segments face margin pressure from fluctuating metal prices and surface finishing requirements.
- Supply concentration in East Asia:JIS-certified testing capacity and injection-molding scale cluster in Japan and China, creating geographic dependency.
- ECE R127 regulatory friction:Pedestrian-impact rules reshape grille edge radii and breakaway mounting designs, adding compliance cost without volume expansion.
Strategic Opportunities
- Composite recycling pathway maturation:Thermal expansion coefficient improvements and closed-loop material recovery create circular economy positioning.
- MIIT new-energy vehicle efficiency mandates:Chinese regulatory tailwinds accelerate material qualification timelines for lightweight exterior components.
- Active shutter-converged sensor integration:Radar and lidar accommodation within grille assemblies opens ADAS-tier supplier relationships.
Industry Challenges
- GB standards certification timeline:Exterior plastic parts qualification under evolving Chinese national standards extends tooling investment payback periods.
- Paint and finishing capex intensity:Backward integration into color-matched, weather-resistant surface treatments demands specialized capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Radiator Grille Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Plastic, Aluminum, Composite Installation Type: Front Mount, Rear Mount, Side Mount, Integrated Vehicle Type: Sedans, SUVs, Trucks, Vans Market Channel: OEM, Aftermarket, Direct Sales, Distributors |
| Companies Covered | Magna International Inc., Toyoda Gosei Co. Ltd., Plastic Omnium SE, SRG Global Inc., Faltec Co. Ltd., Sakae Riken Kogyo Co. Ltd., TPR Co. Ltd., Dorman Products Inc., Putco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Radiator Grille Market Emerging Trajectories
Active airflow management systems are migrating from premium segments to mass-market platforms as thermal efficiency becomes a regulated performance metric. Material science advances and molding precision improvements are compressing cost differentials between composite and metal solutions.
Continuous fiber-reinforced thermoplastic composites are overtaking short-glass formulations in load-bearing grille frames. European OEM programs specify these materials for active shutter housings requiring dimensional stability across thermal cycles. The technology is overtaking conventional injection-molded grades in applications where creep resistance and fatigue performance govern warranty exposure.
EPA Corporate Average Fuel Economy standards are tightening aerodynamic drag coefficient thresholds for light-duty vehicle fleets. Grille suppliers must validate active shutter duty cycles across standardized drive profiles to maintain OEM program eligibility. North American truck and SUV platforms face the steepest compliance gradients, accelerating electromechanical actuator integration into traditionally passive grille designs.
Fleet procurement of standardized grille architectures is compressing model-specific tooling runs. Volume aggregators and rental fleet operators specify modular subassemblies that reduce part proliferation and simplify collision repair. This pattern is most visible in North American commercial vehicle segments where total cost of ownership calculations override styling differentiation.
Automotive Radiator Grille Market Segmentation
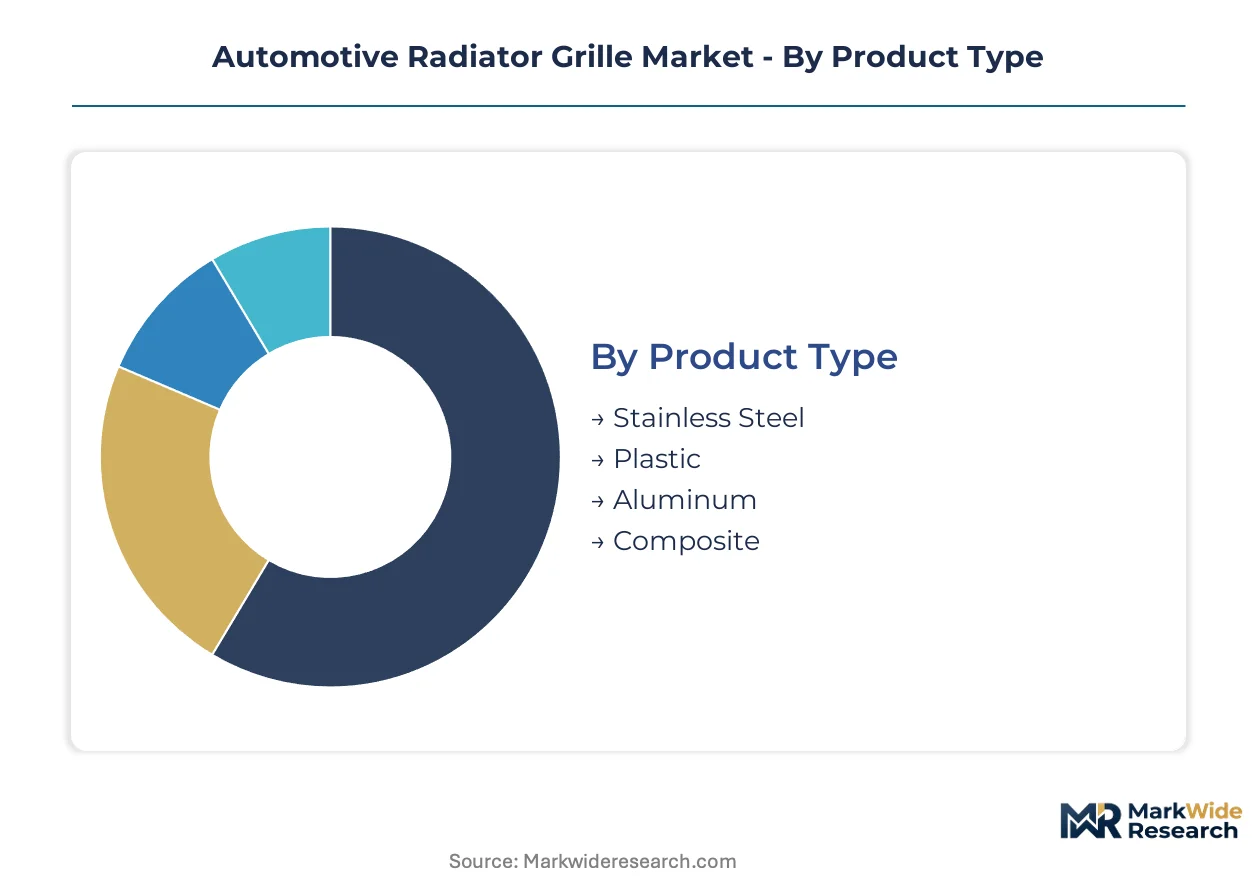
Segmentation in the automotive radiator grille market reveals how material selection, mounting architecture, and vehicle platform requirements fragment procurement patterns. Each dimension carries distinct tooling investments and regulatory compliance obligations that reshape supplier competitive positioning.
Product Type:
Supply concentration in injection-molding capacity and metal stamping infrastructure determines which material formats dominate regional sourcing decisions.
- Plastic:Polypropylene and ABS formulations enable complex geometries through high-pressure injection molding. Mass-market sedan programs in China and Germany specify these materials for active grille shutter housings where weight reduction and thermal cycle durability govern qualification.
- Composite:Continuous fiber-reinforced thermoplastics deliver dimensional stability across temperature extremes for load-bearing shutter frames. European OEM platforms specify these for electromechanical actuator integration where creep resistance minimizes warranty exposure.
- Aluminum:Cast and extruded grades serve premium SUV and truck segments requiring surface finish durability and brand differentiation through polished or brushed aesthetics.
- Stainless Steel:Chrome-plated and painted variants persist in commercial vehicle applications where impact resistance and repair simplicity override weight penalties.
Plastic absorbs the bulk of installed capacity; composite is expanding most quickly.
Installation Type:
Mounting architecture selection tracks directly to thermal management system complexity and aerodynamic optimization requirements across vehicle platforms.
- Front Mount:The dominant configuration integrating with active shutter systems to modulate drag coefficient and engine warm-up times. EPA fuel economy validation protocols mandate standardized duty cycle testing for these assemblies.
- Integrated:Converged sensor housings accommodating radar and lidar modules for ADAS functionality. Premium EV platforms specify these for streamlined exterior surfacing and reduced part count.
- Rear Mount:Secondary cooling applications and auxiliary radiator protection in heavy-duty truck configurations.
- Side Mount:Niche applications for high-performance vehicles with auxiliary oil coolers or brake ducting requirements.
Front mount configurations command the highest engineering resource allocation; integrated designs are climbing the fastest as sensor fusion requirements proliferate.
Vehicle Type:
Platform-specific thermal loads and styling differentiation priorities segment demand across passenger and commercial vehicle categories.
- SUVs:Larger frontal areas and higher towing duty cycles drive specification of aluminum and composite grilles with enhanced airflow capacity. North American truck-based SUV platforms prioritize breakaway mounting designs for NHTSA pedestrian impact compliance.
- Sedans:Cost-optimized plastic grilles dominate where aerodynamic efficiency targets and manufacturing scale economies converge. Chinese domestic brands lead active shutter adoption for MIIT new-energy vehicle efficiency certification.
- Trucks:Commercial and consumer pickup segments balance durability requirements with fuel economy regulations, favoring modular subassemblies for fleet standardization.
- Vans:Delivery and passenger van applications emphasize repair simplicity and parts commonality across model years.
SUVs concentrate value-based procurement activity; sedans drive volume scale for material suppliers.
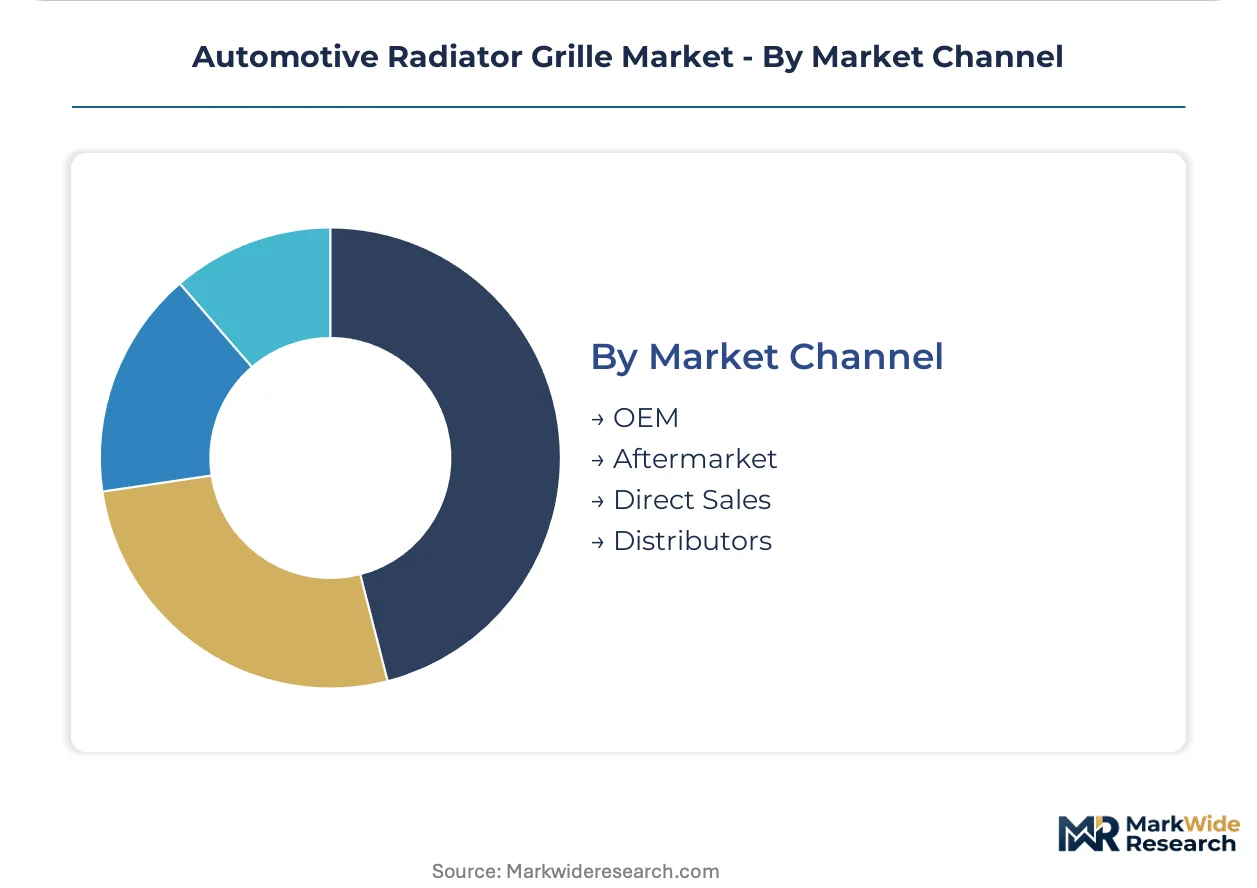
Market Channel:
Channel structure reflects the divergence between platform-integrated engineering contracts and replacement part logistics.
- OEM:Direct supply relationships with tier-one integrators for platform-specific design, validation, and just-in-sequence delivery. Euro 7 and EPA compliance documentation requirements create substantial barrier-to-entry advantages for incumbent suppliers.
- Aftermarket:Collision repair and styling upgrade demand served through distributor networks and direct-to-consumer channels. ECE R127-certified breakaway designs and color-matched finishes differentiate premium from economy offerings.
- Distributors:Wholesale intermediaries aggregating volume across multiple supplier brands for independent repair facilities.
- Direct Sales:Limited to fleet operators specifying standardized modular architectures for total cost of ownership optimization.
OEM channels absorb the majority of engineering-intensive revenue; aftermarket volume is gaining share fastest as vehicle parc ages and repair frequency rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the largest share of OEM procurement for active grille shutter systems, driven by domestic EV platform expansion and MIIT efficiency mandates. Germany and the United States follow as regulatory pressure from Euro 7 and EPA rules accelerates lightweight composite adoption. Japan maintains specialized testing infrastructure for thermal-cycle durability certification.
China
Domestic electric vehicle brands BYD and NIO specify active grille shutter integration for MIIT new-energy vehicle efficiency certification. GB standards for exterior plastic parts extend tooling investment payback periods for tier-one suppliers. Yangtze River Delta injection-molding clusters around Shanghai and Suzhou dominate JIS-certified thermal management component production for export programs.
Germany
BMW and Volkswagen accelerate composite grille procurement under Euro 7 aerodynamic performance requirements. KBA enforces ECE R127 pedestrian-impact compliance for breakaway mounting designs. Bavaria's automotive supplier corridor between Munich and Ingolstadt anchors European active shutter engineering and validation capacity.
United States
Ford and GM specify active airflow management for EPA Corporate Average Fuel Economy validation across truck and SUV platforms. NHTSA pedestrian-impact rules reshape grille edge radii for North American frontal designs. Detroit-Windsor stamping and molding infrastructure supports just-in-sequence delivery to Michigan assembly plants.
Japan
Toyota and Honda prioritize thermal-cycle durability testing under METI carbon-neutrality roadmaps for hybrid thermal management. JIS standards certification creates barrier-to-entry advantages for incumbent grille suppliers. Nagoya's Chubu industrial zone concentrates injection-molding scale for Asian OEM export programs.
South Korea
Hyundai and Kia integrate active shutters for KSA fuel efficiency labeling compliance on domestic and export sedans. MFDS automotive component standards align with EU-type approval reciprocity agreements. Seoul Capital Area suppliers cluster around Pyeongtaek and Hwaseong for Hyundai Motor Group platform integration.
Automotive Radiator Grille Market Vendor Landscape
Backward integration into paint and finishing operations dominates the current landscape as suppliers defend margin position against aluminum input cost volatility. The vendor base separates into three tiers: global integrators with full-service platform engineering, regional specialists with certified testing infrastructure, and commodity molders competing on cycle time. Strategic archetypes include European OEM program anchors, Asian thermal-management specialists, and North American fleet-standardization aggregators. Capacity expansion in continuous fiber-reinforced thermoplastics and M&A targeting sensor-integration capabilities represent the two dominant competitive vectors reshaping supplier positioning.
Among the named tier-one integrators, Magna International Inc. and Plastic Omnium SE exemplify divergent geographic anchoring strategies, with the former representing North American backward integration archetypes and the latter occupying European injection-molding scale positions. Toyoda Gosei Co. Ltd. sits within the Asian specialist tier where JIS-certified durability testing infrastructure creates regulatory compliance advantages. These three entities collectively span the regulatory jurisdictions—EPA, Euro 7, and METI—that govern global OEM program eligibility.
| Leading Market Players |
|---|
| Magna International Inc. |
| Toyoda Gosei Co. Ltd. |
| Plastic Omnium SE |
| SRG Global Inc. |
| Faltec Co. Ltd. |
| Sakae Riken Kogyo Co. Ltd. |
| TPR Co. Ltd. |
| Dorman Products Inc. |
| Putco Inc. |
| Others |
Supply Flow & Price Mechanics
Aluminum LME spot volatility cascades through automotive radiator grille supply chains, compressing margins for premium-tier suppliers while polypropylene resin indices stabilize procurement for mass-market plastic assemblies. This input-cost divergence stratifies pricing power across material tiers and reshapes backward integration decisions among tier-one integrators.
Pricing Analysis
Volume-scale plastic grilles operate on thin margins while composite and aluminum segments capture value through performance differentiation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and thermal-cycle durability testing. Cost compression in aluminum-intensive segments is intensifying because of metal price volatility and surface finishing requirements. Fleet procurement managers exhibit highest price sensitivity; luxury OEM platform engineers prioritize warranty performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, China, and Japan coordinate hub-and-spoke patterns for just-in-sequence delivery to OEM assembly plants. Injection-molding capacity clusters in the Yangtze River Delta and Chubu industrial zone draw from polypropylene, ABS, and continuous fiber-reinforced thermoplastic feedstocks. Single-source vulnerability in JIS-certified thermal testing infrastructure concentrates risk for European and North American programs. Distribution runs through tier-one integrators with captive paint and finishing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive radiator grille procurement is supply-constrained by certified thermal-cycle testing capacity, which props pricing for validated suppliers and extends tooling investment payback periods for new market entrants.
For Market Incumbents: Anchor platform engineering relationships through Euro 7 and EPA compliance documentation, locking out unvalidated competitors. Expand backward integration into color-matched finishing operations to defend margin position against aluminum input volatility. Prioritize capacity addition in continuous fiber-reinforced thermoplastics for active shutter housing applications. For New Entrants and Emerging Players: The premium-to-economy price-point gap in aftermarket collision repair offers white-space entry for ECE R127-certified breakaway designs with color-matched logistics. Target fleet-standardization aggregators in North American commercial vehicle segments with modular subassemblies. Pursue JIS certification partnerships with Nagoya testing infrastructure as the fastest qualification pathway. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap composite specialists with MIIT-qualified tooling in China over capital-intensive aluminum stampers. Long-term viability hinges on sensor-integration capabilities for ADAS-converged grille architectures. Watch active grille shutter penetration rates in Chinese domestic EV brands as the inflection signal for material substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Paint and Finishing | Magna International Inc. defends margin position against aluminum LME volatility through captive surface treatment operations. |
| JIS-Certified Thermal Testing Capacity Expansion | Toyoda Gosei Co. Ltd. creates barrier-to-entry advantages for Asian OEM export programs requiring durability validation. |
| Active Shutter-Sensor Convergence Development | Plastic Omnium SE opens ADAS-tier supplier relationships through radar and lidar accommodation engineering. |
| Composite Recycling Pathway Investment | European OEM programs accelerate closed-loop material recovery for circular economy positioning under EU Green Deal. |
| MIIT Fast-Track Qualification Partnership | Yangtze River Delta suppliers compress GB standards certification timelines for new-energy vehicle efficiency mandates. |
Methodological Framework
Independent corroboration across OEM platform engineering leads, tier-one supplier procurement directors, and aftermarket distributor operations underwrites the qualitative findings in this study. Primary fieldwork with thermal management specialists, paint and finishing process engineers, and JIS certification auditors combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC automotive supplier filings, and MIIT new-energy vehicle certification records. Bottom-up volume aggregation and top-down market sizing triangulate segment-level outputs.
Comparable-period anchoring to historical vehicle platform launches and active grille shutter adoption curves structured the forecast window across the projection horizon. The analytical framework models segmentation dimensions including material format, mounting architecture, vehicle class, propulsion architecture, and regional production cluster. CAGRs derive from regression analysis of content-per-vehicle trajectories and OEM procurement volume trends, with inputs from EPA fuel economy validation protocols and Euro 7 aerodynamic performance requirements.
Inputs from OEM platform engineering leads and tier-one supplier procurement directors were available through the study window; gaps in aftermarket pricing transparency and composite recycling cost curves introduce uncertainty bands around material substitution forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Electric Vehicle Fluid Lubricants Market
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
Argentina Automotive Electric Actuators Market
Automotive Components
Alloys for Automotive Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Canada Automotive Glass Fiber Composites Market
Automotive Components
Automotive Gear Oil Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Italy Automotive Sunroof Market
Automotive Components
Global Automotive Active Body Panel Market
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Torque Vectoring Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market