
 MEMS Automobile Sensors Market | 2026-2036
MEMS Automobile Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
MEMS Automobile Sensors Market Foresight
The EU Green Deal is expanding mandatory emissions monitoring requirements for internal combustion and hybrid powertrains. Robert Bosch GmbH leverages its Stuttgart manufacturing base to dominate pressure and motion sensor supply for German OEMs. STMicroelectronics sustains R&D intensity across analog and digital MEMS process nodes. Analog Devices specializes in high-reliability inertial measurement units for safety-critical chassis applications.
MEMS automobile sensors are microelectromechanical devices fabricated on silicon substrates using bulk or surface micromachining, typically measuring pressure, acceleration, or rotational rate with micron-scale mechanical structures transduced to electrical signals. Their primary purpose is real-time physical parameter acquisition for engine management, occupant protection, and vehicle dynamics control. Pressure sensors anchor the largest revenue pool given pervasive deployment in tire monitoring, manifold absolute pressure, and hydraulic brake systems. Motion sensors represent the fastest-expanding category as automakers add roll detection, pedestrian impact sensing, and autonomous emergency braking functions. Smart sensor technology captures widening margin pools through on-chip signal processing and CAN-FD bus integration that reduces ECU complexity.
NHTSA in the United States enforces Federal Motor Vehicle Safety Standards that mandate electronic stability control and tire pressure monitoring, directly specifying sensor performance thresholds. The EPA coordinates with California Air Resources Board on onboard diagnostics regulations that require continuous exhaust pressure and temperature sensing. EMA in Europe enforces Euro 7 pollutant limits that expand sensor count for real-driving emissions verification. Stakeholders must monitor divergence between NHTSA self-certification and EMA type-approval testing protocols when designing unified sensor platforms.
Market Dynamics
Sensor fusion architectures are compressing discrete component counts while elevating performance thresholds for inertial measurement and pressure sensing nodes in chassis and powertrain domains.
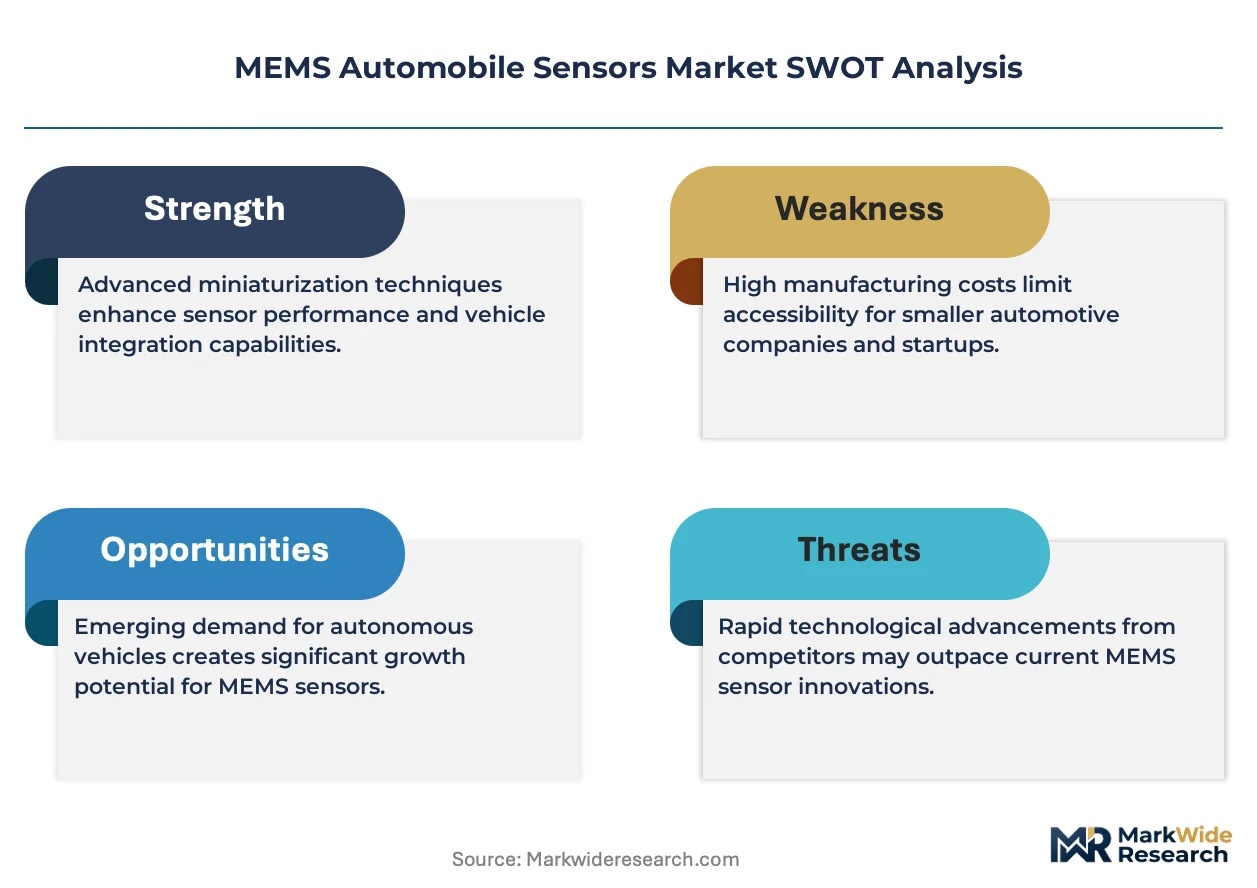
Growth Catalysts
- Euro 7 pollutant limits:EMA mandates expand real-driving emissions verification, forcing OEMs to embed additional exhaust pressure and temperature sensors across hybrid and internal combustion powertrains.
- Silicon photonics integration:Optical MEMS structures are penetrating LiDAR and cabin monitoring applications, opening new wafer demand for compound semiconductor foundries.
- German automotive electronics clusters:Stuttgart and Ingolstadt anchor concentrated R&D ecosystems where Bosch, Continental, and ZF co-locate packaging and test facilities adjacent to OEM engineering centers.
Market Restraints
- 300mm silicon wafer cost volatility:MEMS-specific SOI substrates face pricing pressure from competing demand in logic and memory fabs, squeezing gross margins for discrete sensor suppliers.
- Packaging concentration in Southeast Asia:Molded leadframe and ceramic lid assembly for automotive-grade hermetic seals clusters in Malaysia and Thailand, exposing supply chains to geographic risk concentration.
- Functional safety certification timelines:ISO 26262 ASIL-D qualification for brake and steering sensors extends development cycles by 18-24 months, delaying revenue recognition for new entrants.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced automotive electronics are attracting MEMS packaging investments to Tamil Nadu and Gujarat manufacturing corridors.
- Vehicle-to-everything communication:C-V2X roadside units require high-g accelerometers for collision avoidance, creating incremental sensor demand in smart city infrastructure deployments.
- On-chip AI inference:Edge neural processing units integrated with MEMS transducers enable predictive maintenance algorithms, shifting value capture from raw sensing to diagnostic software layers.
Industry Challenges
- Multi-physics simulation expertise:Coupled electro-mechanical-thermal modeling for MEMS design requires rare cross-disciplinary talent combining finite element analysis with semiconductor process knowledge.
- Legacy ECU integration complexity:CAN-FD and Ethernet-TSN migration paths force backward compatibility engineering for sensors serving 10-15 year vehicle lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEMS Automobile Sensors Market |
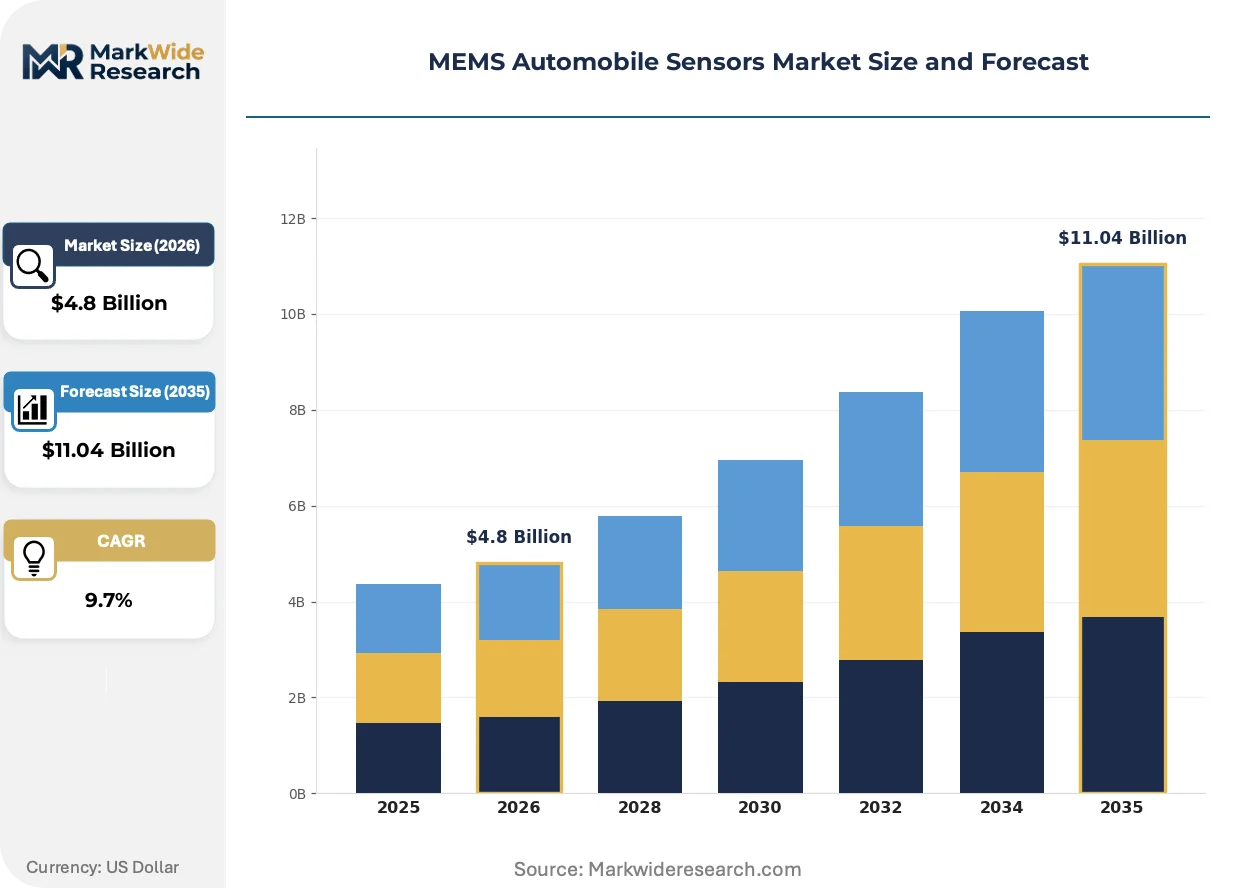
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Motion Sensors, Humidity Sensors Application: Safety Systems, Navigation Systems, Telematics, Engine Control End User: OEMs, Aftermarket Providers, Fleet Management, Dealerships Technology: Analog, Digital, Wireless, Smart Sensors |
| Companies Covered | Robert Bosch GmbH, STMicroelectronics, Analog Devices, Infineon Technologies AG, Denso Corporation, NXP Semiconductors, Sensata Technologies, Panasonic Corporation, Murata Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEMS Automobile Sensors Market Shifts & Advancements
Monolithic integration of sensing, signal conditioning, and communication interfaces is collapsing bill-of-materials complexity while demanding advanced packaging competencies from traditional discrete suppliers.
Piezoelectric aluminum nitride thin films are displacing capacitive transduction in resonant pressure and inertial sensors, offering higher Q-factors and temperature stability. Tier 1 suppliers are adopting AlN-on-silicon processes for next-generation manifold absolute pressure modules. This material transition is converging with foundry investments in 200mm MEMS-specific capacity expansion.
EPA coordination with California Air Resources Board on onboard diagnostics regulations is mandating continuous exhaust pressure and temperature sensing with defined accuracy bands. Powertrain engineers must architect sensor redundancy to satisfy both federal and state compliance pathways. Diesel and lean-burn gasoline platforms face the steepest sensor count inflation under these rules.
Fleet operators and mobility service providers are consolidating sensor procurement through long-term supply agreements with direct foundry access, bypassing traditional distribution channels. Tier 2 module suppliers respond by offering sensor-as-a-service contracts with guaranteed uptime and predictive replacement scheduling. This procurement model compression is most visible in North American commercial vehicle and European ride-hail electrification programs.
MEMS Automobile Sensors Market Segmentation
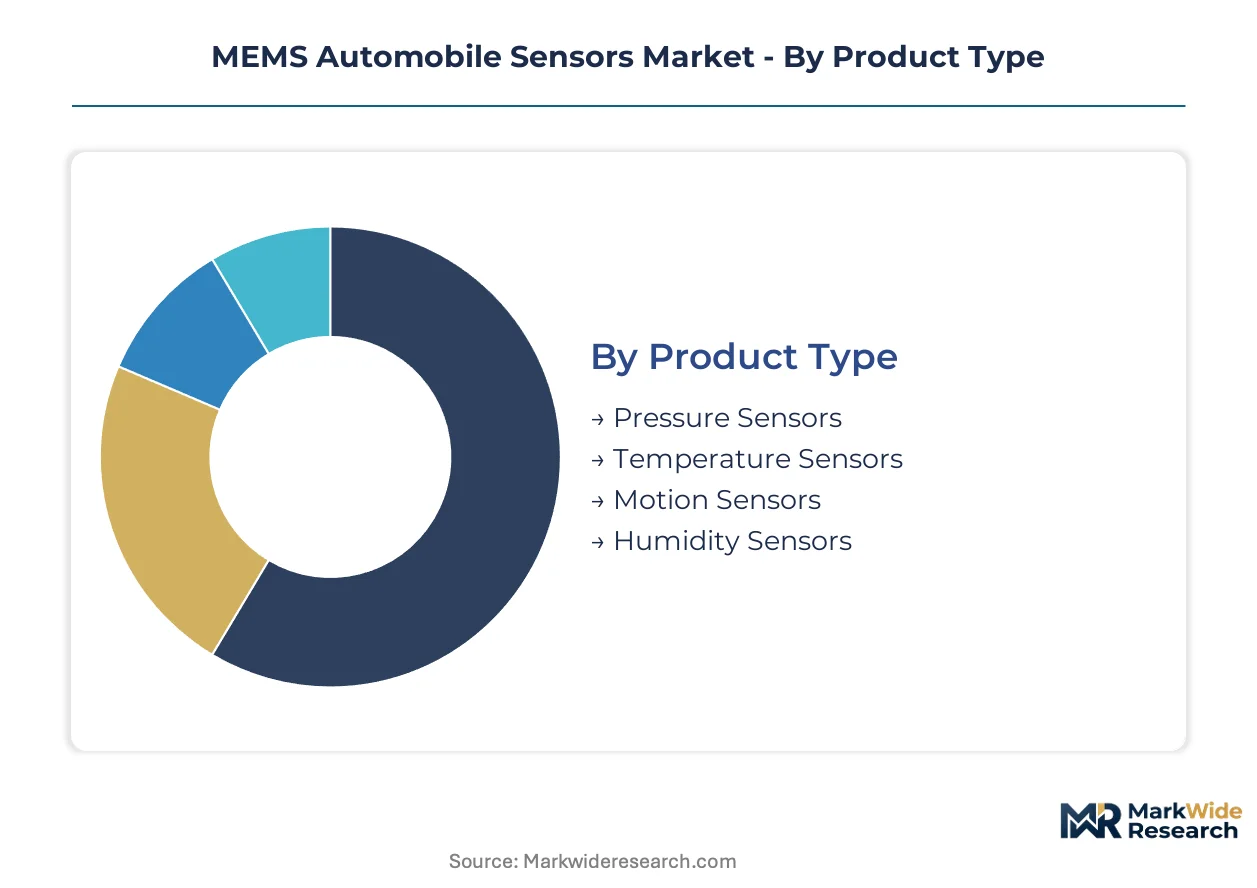
MEMS automobile sensors fragment across four intersecting dimensions that shape procurement economics and supplier margin structures. Product type determines silicon wafer allocation and packaging complexity. Application dictates functional safety certification tiers and OEM qualification timelines.
Product Type:
Cost tier drives buyer selection, with pressure sensors commanding premium pricing for manifold absolute pressure modules while motion sensors penetrate fastest through ADAS mandates.
- Pressure Sensors:Piezoresistive silicon diaphragms transduce manifold absolute pressure, tire pressure, and hydraulic brake force into voltage signals. German OEMs in Stuttgart anchor demand for high-temperature exhaust pressure variants under Euro 7 verification requirements. Foundry capacity constraints at Bosch's Reutlingen facility limit supply elasticity for 350°C-rated ceramic-packaged units.
- Motion Sensors:Capacitive and piezoelectric accelerometers plus Coriolis vibratory gyroscopes enable electronic stability control and roll-over detection. NHTSA mandates for autonomous emergency braking accelerate deployment across Detroit Three platforms. Supply concentrates in STMicroelectronics' Agrate Brianza 200mm MEMS line.
- Temperature Sensors:Thermopile and platinum thin-film resistors measure exhaust gas and coolant temperatures with ±2°C accuracy.
- Humidity Sensors:Polymer-based capacitive elements monitor cabin air quality and battery pack condensation risk.
Pressure sensors lead on scale; motion sensors lead on momentum.
Application:
Volume concentration clusters in powertrain and chassis domains where sensor counts per vehicle exceed ten units.
- Safety Systems:Airbag deployment accelerometers, pedestrian impact sensors, and tire pressure monitors require ASIL-D functional safety certification. EPA-coordinated regulations with California Air Resources Board mandate continuous tire pressure verification. Analog Devices' Wilmington facility specializes in high-g shock sensors for frontal collision detection.
- Engine Control:Manifold absolute pressure, exhaust gas recirculation, and fuel rail sensors optimize combustion efficiency. Euro 7 real-driving emissions verification forces hybrid powertrains to embed additional temperature and pressure nodes. Bosch supplies integrated pressure-temperature combo sensors from its Stuttgart campus.
- Navigation Systems:Six-axis inertial measurement units compensate for GPS signal loss in urban canyons.
- Telematics:Accelerometer data streams enable usage-based insurance and fleet diagnostics.
Engine control dominates unit volume; safety systems capture the steepest expansion trajectory.
End User:
Customer type determines contract structure, with OEMs demanding 15-year supply agreements while fleet operators shift toward sensor-as-a-service procurement.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz specify proprietary sensor interfaces and calibration protocols. Direct foundry relationships with Bosch and Continental bypass traditional distribution channels. Tier 1 module suppliers absorb qualification costs for ASIL-D brake and steering sensors.
- Fleet Management:Commercial vehicle operators in North America consolidate procurement through long-term supply agreements with predictive replacement scheduling. Sensor-as-a-service contracts guarantee uptime for Class 8 truck telematics platforms.
- Aftermarket Providers:Independent distributors serve replacement demand for TPMS and OBD-II diagnostic sensors.
- Dealerships:Authorized service networks handle warranty-related sensor replacements with OEM-mandated calibration procedures.
OEMs anchor revenue stability; fleet management is expanding most quickly.
Technology:
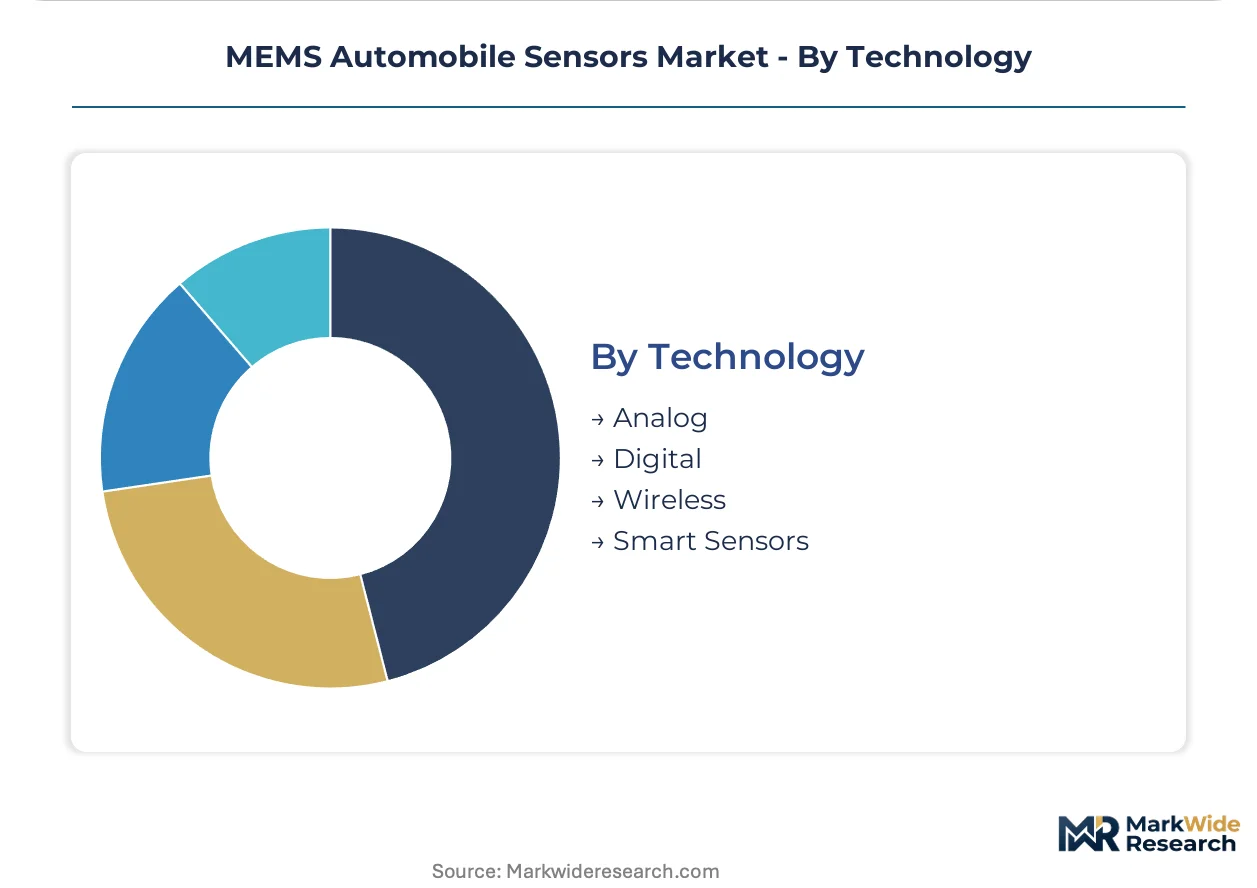
Margin differentiation separates analog commodity sensors from digital smart sensors with on-chip signal processing.
- Smart Sensors:Integrated ASICs perform temperature compensation, self-diagnostics, and CAN-FD bus communication on the same die. On-chip AI inference enables predictive maintenance algorithms for battery thermal management. STMicroelectronics and Bosch lead foundry investments in 200mm MEMS-specific capacity.
- Digital:SPI and I2C interfaces reduce ECU complexity through direct microcontroller connectivity. SENT protocol adoption spreads across powertrain sensors for deterministic latency.
- Analog:Voltage-output sensors serve legacy ECU architectures with minimal interface cost.
- Wireless:BLE and UWB-enabled sensors eliminate wiring harness weight for TPMS and seat occupancy detection.
Smart sensors command premium positioning; digital interfaces gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEMS sensor engineering talent clusters in Germany's Stuttgart region, Japan's Nagoya industrial corridor, and Michigan's automotive engineering belt. These workforce concentrations anchor design, packaging, and OEM qualification workflows. Geographic proximity between foundries and vehicle engineering centers compresses development cycles.
Germany
EMA's Euro 7 mandates drive exhaust pressure sensor demand across Volkswagen, BMW, and Mercedes-Benz powertrains. The EU Green Deal accelerates real-driving emissions verification requirements. Stuttgart anchors Bosch and Continental packaging facilities adjacent to OEM engineering centers.
United States
NHTSA electronic stability control and tire pressure monitoring mandates sustain accelerometer and pressure sensor volumes. EPA coordination with California Air Resources Board expands onboard diagnostics for exhaust sensing. Michigan's Detroit Three engineering clusters absorb qualification costs for ASIL-D brake sensors.
Japan
METI fuel efficiency standards and safety regulations elevate inertial measurement unit deployment in Toyota and Honda platforms. The country's national automotive regulator enforces pedestrian protection mandates requiring impact detection sensors. Nagoya's Chubu region concentrates Denso and Panasonic MEMS packaging operations.
China
MIIT new energy vehicle mandates and GB standards for battery thermal management expand temperature and pressure sensor counts. The national automotive regulator enforces intelligent connected vehicle specifications requiring chassis sensing nodes. Yangtze River Delta fabs serve domestic OEMs and Tier 1 module suppliers.
South Korea
METI-equivalent fuel economy regulations and MFDS-connected vehicle standards accelerate motion sensor integration in Hyundai and Kia platforms. The Seoul Capital Area concentrates Samsung electro-mechanics and domestic foundry capacity for automotive-grade MEMS.
MEMS Automobile Sensors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the MEMS automobile sensor supply base. IDM foundries with captive 200mm MEMS lines dominate pressure and inertial sensing, while fabless specialists license process technology to merchant foundries. Three archetypes define competitive positioning: integrated device manufacturers with automotive heritage, semiconductor conglomerates diversifying from consumer MEMS, and Tier 1 module suppliers backward-integrating into sensor design. Dominant competitive moves include foundry capacity expansion in automotive-qualified 200mm lines and strategic partnerships for ASIL-D certification acceleration.
Within the integrated device manufacturer tier, Robert Bosch GmbH and STMicroelectronics exemplify capital-intensive positioning with foundry ownership and direct OEM relationships. Analog Devices occupies a specialist position in high-reliability inertial measurement for safety-critical chassis applications. These three companies represent distinct archetypes: Bosch anchors German automotive electronics clusters with vertical process control, STMicroelectronics exemplifies European semiconductor diversification into automotive MEMS, and Analog Devices demonstrates focused specialization on performance-tier sensing nodes.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| STMicroelectronics |
| Analog Devices |
| Infineon Technologies AG |
| Denso Corporation |
| NXP Semiconductors |
| Sensata Technologies |
| Panasonic Corporation |
| Murata Manufacturing |
| Others |
Supply & Pricing Matrix
300mm silicon-on-insulator wafer pricing volatility cascades through MEMS sensor manufacturing tiers, compressing margins for discrete suppliers while concentrating pricing power with integrated device manufacturers holding captive foundry capacity. Cost pass-through mechanisms diverge across ASIL-D certified safety nodes and commodity pressure sensors, fragmenting procurement economics for German OEMs and North American fleet operators.
Pricing Analysis
Bundled sensor-as-a-service contracts for fleet telematics platforms command premium positioning against unbundled per-unit transactional sales to aftermarket distributors. Three-tier pricing structure across ASIL-D certified, automotive-grade, and industrial-grade certification levels reflects ISO 26262 qualification investment recovery timelines. Pricing pressure stems from foundry capacity constraints at Bosch's Reutlingen and STMicroelectronics' Agrate Brianza facilities limiting supply elasticity. Aftermarket providers exhibit highest price sensitivity; OEM direct procurement through long-term offtake agreements shows lowest.
Supply Chain Analysis
ISO 26262 ASIL-D qualification gates concentrate automotive-grade MEMS supply in Germany, Japan, and the United States, where Bosch, Denso, and Analog Devices maintain captive packaging and test infrastructure. Raw material dependencies center on silicon-on-insulator wafers, ceramic lid substrates for hermetic sealing, and aluminum nitride thin films for piezoelectric transduction. Single-source vulnerability concentrates in Malaysian and Thai molded leadframe assembly for automotive hermetic seals. Distribution runs through Tier 1 module suppliers with direct OEM engineering relationships, bypassing traditional component distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MEMS automobile sensor market functions as a stable compounder anchored by regulatory mandates for emissions monitoring and safety systems that sustain per-vehicle sensor count expansion regardless of macroeconomic cycles.
For Market Incumbents: Deploy foundry capacity expansion in automotive-qualified 200mm MEMS lines as the primary lever against fabless specialists encroaching on pressure sensing applications. Deepen backward integration into aluminum nitride thin-film deposition processes to secure piezoelectric material supply. Accelerate ASIL-D certification pipelines for brake and steering sensors to extend qualification timelines that delay competitive entry. For New Entrants and Emerging Players: Fleet management procurement consolidation offers the most penetrable entry vector for sensor-as-a-service business models with predictive replacement scheduling. Target India's Tamil Nadu and Gujarat manufacturing corridors where PLI scheme incentives reduce packaging cost structures for export-oriented production. Pursue direct foundry relationships with Yangtze River Delta fabs serving domestic Chinese OEMs to bypass established Tier 1 supplier channels. For Investors and Strategic Acquirers: Asymmetric upside sits with fabless specialists possessing multi-physics simulation expertise and existing ASIL-B certification footholds capable of escalating to ASIL-D. Long-term viability favors acquisition targets with demonstrated OEM qualification workflows and on-chip AI inference capabilities for predictive maintenance applications. Watch for inflection signals in C-V2X roadside infrastructure deployment contracts that accelerate high-g accelerometer demand beyond passenger vehicle applications.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | 200mm MEMS-specific lines at Bosch's Reutlingen facility alleviate supply constraints for Euro 7 exhaust pressure sensors. |
| ASIL-D Certification Acceleration | Compressed ISO 26262 qualification timelines at Analog Devices' Wilmington facility defend positioning in safety-critical chassis applications. |
| Sensor-as-a-Service Contracts | Outcome-based procurement models with North American Class 8 truck fleets shift value capture from hardware to diagnostic software layers. |
| India PLI Scheme Participation | Production-linked incentives for Tamil Nadu packaging investments reduce geographic risk concentration in Southeast Asian assembly. |
| On-Chip AI Inference Integration | Edge neural processing units from STMicroelectronics enable predictive battery thermal management algorithms for electric vehicle platforms. |
Research Methodology
Multiple input streams — primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, IHS Markit registration data, and SEC filings from semiconductor conglomerates; plus customs records for MEMS-specific substrate trade flows — were reconciled through bottom-up unit economics modeling and top-down market sizing triangulation. Stakeholder conversations spanned sensor module design, foundry process engineering, and fleet operator procurement functions.
Historical production volume trajectories were cross-referenced against panel input from platform engineers at Volkswagen Group, BMW, and Mercedes-Benz to establish content-per-vehicle assumptions across the projection horizon. Segmentation dimensions modeled included product type, application domain, end-user archetype, and technology tier. CAGRs were derived from regression analysis of sensor count expansion against regulatory mandate implementation schedules and powertrain electrification penetration curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Euro 7 implementation delays, 300mm SOI wafer pricing volatility, and C-V2X infrastructure deployment cadence. Forecasts reflect documented assumptions regarding OEM qualification timelines and foundry capacity expansion schedules. A model refresh is warranted upon material change in EMA real-driving emissions verification protocols or NHTSA autonomous vehicle sensor mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Automotive Brake Tube Market
Automotive Components
Automotive Solenoid Market
Automotive Components
Automotive Differential Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
Automotive Steering Column Market
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
Auto Fender Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
Europe Automotive Market
Automotive Components
Automotive Key Market