
 Automotive Grille Market | 2026-2036
Automotive Grille Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Grille Market Analysis
Multi-source procurement for exterior trim modules is repositioning how tier-one suppliers secure grille contracts across vehicle programs. Magna International Inc. leverages its integrated stamping and assembly footprint to capture large-platform OEM awards. HBPO GmbH anchors its position through specialized front-end module integration that bundles grilles with active air-flap systems. SRG Global Inc. competes on chrome-plated and painted surface finishes that command premium placement in luxury vehicle lines.
An automotive grille is a structural front-opening component, typically injection-molded from ABS or polycarbonate blends or stamped from aluminum and steel alloys, engineered to protect radiator and sensor packages while managing airflow for engine cooling and aerodynamic drag reduction. Plastic and composite grille constructions are gaining share as OEMs pursue mass reduction targets tied to fleet emissions compliance. Aluminum grille segments sustain higher average selling prices in premium applications where surface finish durability and thermal expansion control carry greater weight. The OEM end-user channel dominates volume, though aftermarket providers occupy meaningful margin pools in collision repair and styling customization.
NHTSA pedestrian impact standards in the United States, ECE R127 regulations across European type-approval markets, and China's GB standards for exterior projections collectively shape grille height, edge radius, and breakaway requirements that constrain design freedom. EPA and European Commission CO2 fleet targets further redirect engineering resources toward active grille shutters that modulate airflow and reduce warm-up fuel consumption. Stakeholders must monitor how sensor integration for adaptive cruise and LiDAR placement reshapes grille aperture geometry and supplier value capture.
Market Dynamics
Sensor integration for advanced driver-assistance systems is compressing grille aperture geometry and forcing simultaneous redesigns of airflow management, pedestrian impact absorption, and brand identity expression.
Growth Catalysts
- Active Grille Shutter Mandates:EPA CO2 fleet targets and European Commission emissions rules are accelerating OEM adoption of airflow-modulating shutters that reduce engine warm-up fuel consumption.
- Electric Vehicle Platform Expansion:Battery-electric architectures require redesigned front-end modules where grilles protect sensor suites rather than radiators, creating fresh engineering contracts.
- Pedestrian Safety Regulations:NHTSA impact standards and ECE R127 type-approval requirements are driving replacement cycles for legacy grille designs that fail edge-radius and breakaway tests.
Market Restraints
- Aluminum Price Volatility:Premium grille segments depend on aluminum alloy sheet, exposing margins to London Metal Exchange price swings and energy-intensive smelting costs.
- Tooling Concentration Risk:Large-platform injection molds for ABS-polycarbonate blends concentrate with a limited supplier base in southern Germany and coastal China.
- Sensor Interference Constraints:Metallic grille finishes create radar signal attenuation that limits adaptive cruise and LiDAR placement options behind aperture surfaces.
Strategic Opportunities
- India Passenger Vehicle Growth:Domestic OEMs and joint ventures are localizing front-end module production to serve sub-4-meter vehicle segments with cost-optimized plastic grille architectures.
- Biomaterial Substitution:Flax fiber and recycled polymer compounds offer path to lightweighting compliance under EU Green Deal circular-economy procurement guidelines.
- Aftermarket Customization Channels:Direct-to-consumer digital platforms are disintermediating traditional collision repair distributors for styling-focused grille replacements.
Industry Challenges
- Thermoforming Tool Lead Times:Complex chrome-plated surface finish dies require 18-24 month development cycles that misalign with compressed vehicle platform launch schedules.
- Cross-Functional Integration:Grille engineering now demands simultaneous thermal management, sensor packaging, and styling studio coordination that strains traditional supplier organizational boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Grille Market |
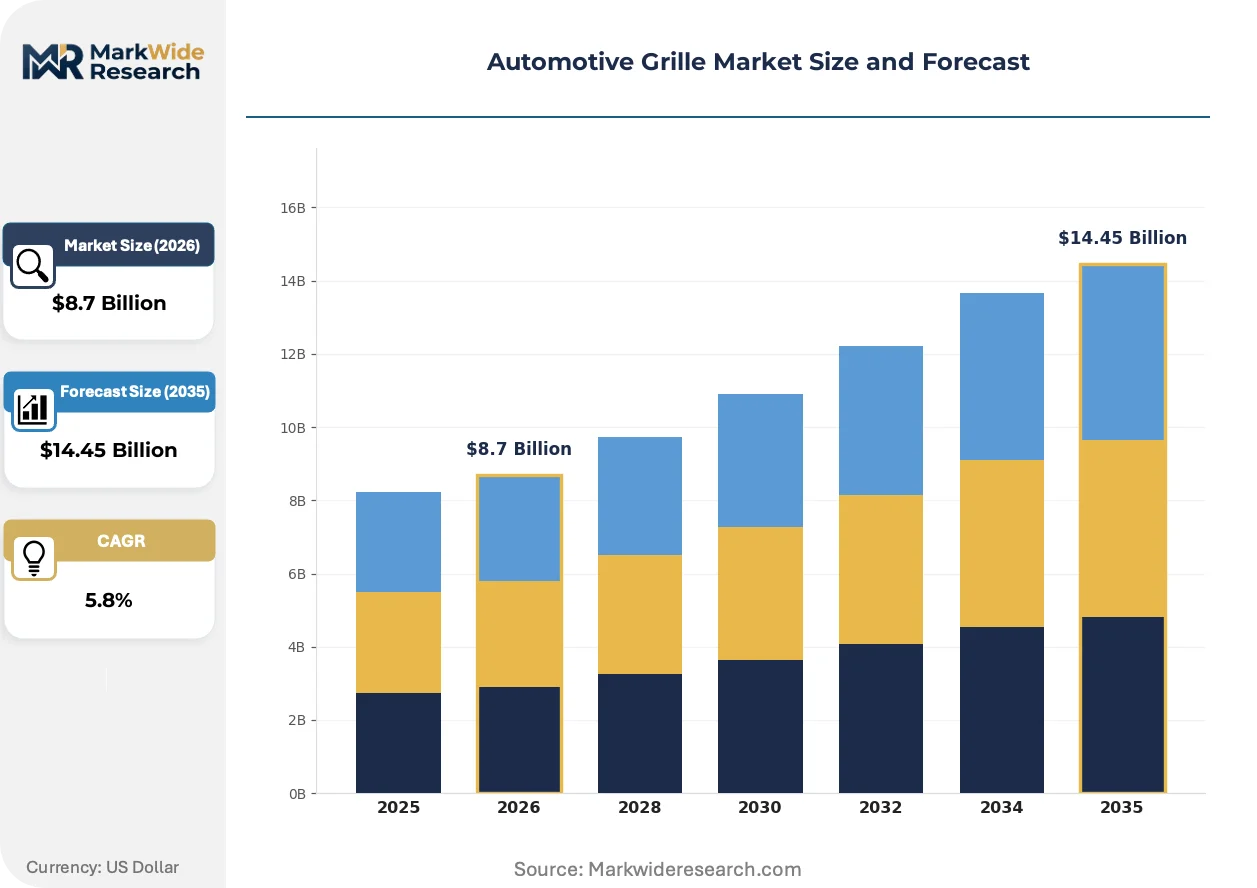
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Plastic, Composite Material: ABS, Polycarbonate, Stainless Steel, Carbon Fiber Feature: Decorative, Functional, Aerodynamic, Impact-Resistant End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Dealerships |
| Companies Covered | Magna International Inc., HBPO GmbH, SRG Global Inc., Toyoda Gosei Co. Ltd., Hyundai Mobis Co. Ltd., Dorman Products Inc., COMPAGNIE PLASTIC OMNIUM SE, Lacks Enterprises Inc., Putco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Grille Market Emerging Trajectories
Grille functionality is bifurcating between sensor-transparent aperture designs for electric vehicles and active airflow systems for combustion platforms, with surface finish technology becoming the primary differentiation vector.
Polycarbonate-ABS composite formulations with integrated metallic flake are integrating radar-transparent electromagnetic properties directly into injection-molded substrate layers. Tier-one suppliers serving premium electric vehicle programs are adopting these compounds to eliminate secondary coating steps. This integration is compressing value capture toward material science specialists and away from traditional plating houses.
REACH substance restrictions on hexavalent chromium plating are forcing conversion to trivalent chrome and physical vapor deposition finishes across European type-approval markets. German KBA enforcement timelines are accelerating supplier qualification requirements. Premium OEMs with heritage grille identities are responding by accelerating in-house surface engineering capabilities.
Fleet procurement departments are consolidating exterior trim sourcing under single-source module contracts that bundle grilles with bumpers and lighting assemblies. Tier-two finish specialists are losing direct OEM access as Magna and HBPO capture integrated program awards. This concentration is most visible in United States full-size truck and German luxury sedan segments where platform scale justifies dedicated assembly lines.
Automotive Grille Market Segmentation
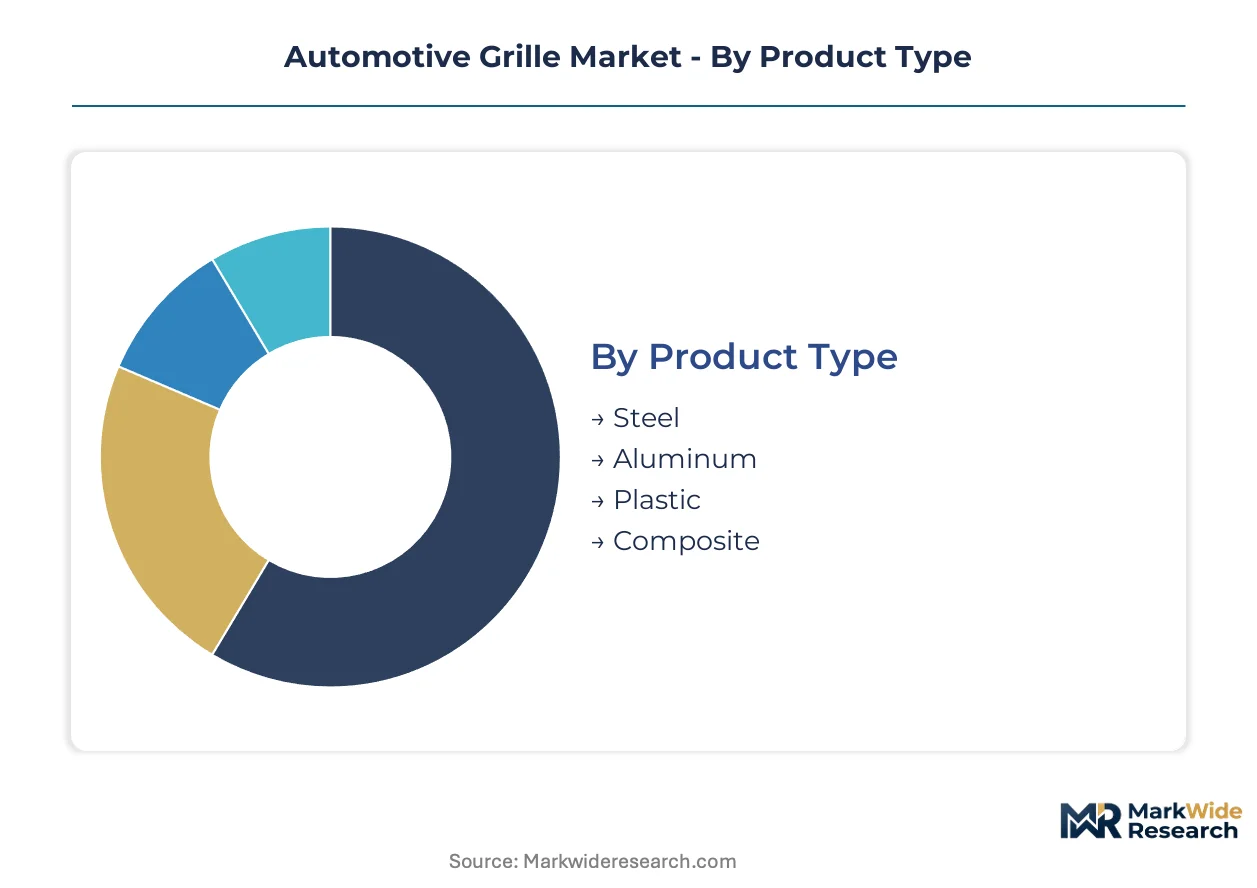
Automotive grille procurement splits sharply between cost-driven plastic architectures for volume platforms and premium metal finishes for luxury positioning. Material selection cascades through regulatory compliance, thermal management requirements, and surface engineering capabilities that define supplier tiering.
Product Type:
Volume production concentrates on plastic and steel constructions, while aluminum and composite variants command premium placement in differentiated vehicle lines.
- Steel:Stamped mild and high-strength steel alloys dominate full-size truck and commercial vehicle programs where impact resistance and repairability outweigh mass penalties. Detroit Three OEMs specify steel grilles for their heavy-duty pickup architectures to satisfy NHTSA frontal barrier requirements without costly material substitution.
- Aluminum:Extruded and cast aluminum sheet delivers surface finish durability and thermal expansion control for German luxury sedans and electric vehicle platforms. Premium OEMs in Stuttgart and Munich specify aluminum to achieve heritage grille identities with reduced mass versus steel equivalents.
- Plastic:Injection-molded ABS-polycarbonate blends serve mass-market passenger vehicles where tooling amortization across high volumes offsets per-unit material costs. Chinese domestic OEMs favor plastic architectures for sub-4-meter vehicle segments to meet MIIT fleet efficiency targets.
- Composite:Glass- and carbon-fiber reinforced polymers occupy niche performance and electric vehicle applications requiring radar transparency and extreme lightweighting. Tier-one suppliers are qualifying flax-fiber compounds under EU Green Deal circular-economy procurement guidelines.
Mature deployment sits with steel. Newer deployment is concentrated in composite formulations for sensor-transparent electric vehicle front ends.
Material:
Substrate chemistry determines electromagnetic properties, coating adhesion, and end-of-life recyclability that shape OEM sourcing decisions.
- ABS:Acrylonitrile-butadiene-styrene copolymers provide cost-optimized impact resistance and chrome-plating receptivity for mid-market vehicle programs. ABS formulations from southern German compounders dominate European type-approval markets subject to ECHA REACH substance restrictions.
- Polycarbonate:High-flow polycarbonate grades enable complex thin-wall designs with integrated metallic flake for radar-transparent electromagnetic properties. Tier-one suppliers serving premium electric vehicle programs in California and Shanghai are adopting these compounds to eliminate secondary coating steps.
- Stainless Steel:Austenitic and ferritic stainless grades deliver corrosion resistance for commercial vehicle and aftermarket replacement channels where durability expectations exceed passenger car norms.
- Carbon Fiber:Prepreg and sheet molding compound carbon fiber occupies ultra-premium and motorsport applications where gram-level mass reduction justifies material cost multiples.
ABS and polycarbonate formulations are expanding most quickly as active grille shutter mandates accelerate plastic architecture adoption across combustion and hybrid platforms.
Feature:
Engineering emphasis shifts between aesthetic differentiation and functional performance based on vehicle segment and powertrain architecture.
- Decorative:Surface finish engineering commands disproportionate margin capture in luxury segments where brand identity expression depends on chrome, paint, and illumination effects. German KBA enforcement of hexavalent chromium restrictions is accelerating trivalent chrome and physical vapor deposition qualification timelines.
- Functional:Active grille shutters, integrated sensors, and thermal management apertures define functional category requirements for EPA and European Commission emissions compliance. Tier-one suppliers bundle functional grilles with front-end module contracts to capture integrated program awards.
- Aerodynamic:Computational fluid dynamics-optimized louver geometries reduce drag coefficients for electric vehicle range extension and combustion platform fuel economy. Aerodynamic feature sets are climbing the fastest in battery-electric architectures where cooling demand is reduced but drag sensitivity is heightened.
- Impact-Resistant:Pedestrian safety compliance drives breakaway and energy-absorption engineering for NHTSA and ECE R127 type-approval markets. Impact-resistant designs concentrate in European and North American regulatory jurisdictions with stringent pedestrian protection mandates.
Decorative feature deployment dominates premium positioning. Functional and aerodynamic integration is concentrating in electric vehicle platform engineering.
End User:
Channel structure bifurcates between captive OEM supply and independent aftermarket distribution with diverging margin and specification requirements.
- OEMs:Original equipment manufacturers specify grille architectures during platform development, locking in multi-year supply agreements with tier-one module integrators. OEM procurement departments are consolidating exterior trim sourcing under single-source contracts that bundle grilles with bumpers and lighting assemblies.
- Aftermarket Providers:Independent distributors and collision repair specialists serve styling customization and insurance-funded replacement demand outside vehicle warranty periods. Direct-to-consumer digital platforms are disintermediating traditional distributors for styling-focused grille replacements in United States and European markets.
- Vehicle Assemblers:Contract manufacturers and joint venture assembly plants procure grilles as part of complete front-end module kits from tier-one system suppliers. Assembler channel volume concentrates in China and India where domestic OEMs localize production for cost-optimized vehicle segments.
- Dealerships:Authorized dealer networks handle warranty replacements and factory-approved accessories, maintaining OEM brand standards for fit and finish. Dealership channel margins depend on OEM parts pricing structures and regional collision repair market concentration.
Aftermarket and dealership channels represent the steepest expansion trajectory as vehicle parc growth and styling customization demand outpace new vehicle production rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelting corridors in Quebec and alumina refining clusters in Western Australia anchor raw material flows for premium grille architectures. Engineering talent concentrates in Stuttgart, Detroit, and Shanghai where OEM development centers co-locate with tier-one module integrators.
United States
Full-size truck programs from Detroit Three OEMs drive steel grille demand for NHTSA frontal barrier compliance. EPA CO2 fleet targets accelerate active grille shutter adoption across combustion and hybrid platforms. Engineering concentration in southeast Michigan supports integrated front-end module development for North American vehicle programs.
Germany
Premium sedan and electric vehicle platforms from Stuttgart and Munich manufacturers sustain aluminum grille specifications for heritage brand identities. KBA enforcement of REACH hexavalent chromium restrictions accelerates trivalent chrome and physical vapor deposition qualification timelines. Supplier tooling concentration in southern Germany dominates European type-approval markets for ABS-polycarbonate injection molds.
China
Domestic OEMs and joint ventures localize plastic grille production for sub-4-meter vehicle segments under MIIT fleet efficiency mandates. MIIT regulations on exterior projections and pedestrian safety shape GB standard compliance for grille height and edge radius requirements. Yangtze River Delta manufacturing clusters host the densest concentration of grille molding capacity serving both domestic and export vehicle programs.
India
Passenger vehicle growth from domestic OEMs and joint ventures drives localization of cost-optimized plastic grille architectures. Central government PLI scheme incentives support tier-one supplier establishment for front-end module production. Tamil Nadu and Gujarat automotive corridors concentrate assembly plant demand for grille procurement under single-source module contracts.
Japan
Keiretsu supply structures sustain captive grille procurement relationships between domestic OEMs and affiliated tier-one suppliers. METI carbon neutrality roadmaps redirect engineering resources toward radar-transparent polycarbonate formulations for sensor integration. Kanto region engineering centers coordinate thermal management and aerodynamic optimization for hybrid platform grille specifications.
Automotive Grille Market Vendor Landscape
Module integration contracts dominate the current landscape as OEM procurement departments consolidate exterior trim sourcing under single-source awards. The vendor base organizes around three strategic archetypes: integrated module suppliers capturing bundled program awards, surface finish specialists defending premium placement in luxury segments, and regional fabricators serving cost-optimized vehicle lines. Capacity expansion and qualification acceleration for radar-transparent materials represent the dominant competitive moves as electric vehicle platform launches compress development timelines.
Within the integrated module tier, Magna International Inc., HBPO GmbH, and SRG Global Inc. exemplify contrasting geographic and structural positioning. The Canadian-incorporated Magna anchors North American full-size truck and crossover program awards through captive stamping and assembly footprint. The German GmbH-structured HBPO occupies a specialized position in front-end module integration that bundles grille architectures with active air-flap systems. The US-incorporated SRG Global represents surface finish specialization, with chrome-plated and painted capabilities commanding premium placement in luxury vehicle lines where brand differentiation carries disproportionate weight.
| Leading Market Players |
|---|
| Magna International Inc. |
| HBPO GmbH |
| SRG Global Inc. |
| Toyoda Gosei Co. Ltd. |
| Hyundai Mobis Co. Ltd. |
| Dorman Products Inc. |
| COMPAGNIE PLASTIC OMNIUM SE |
| Lacks Enterprises Inc. |
| Putco Inc. |
| Others |
Supply Flow & Price Mechanics
Premium and electric vehicle OEM procurement concentration sustains contract-based long-term offtake pricing with active grille shutter and sensor-integration bundles commanding premium placement over commodity plastic architectures. Cost compression in mass-market ABS-polycarbonate segments intensifies as Chinese domestic OEMs localize production for sub-4-meter vehicle programs.
Pricing Analysis
Warranty and service bundling separates tier-one module integrators from tier-two finish specialists, with Magna and HBPO capturing integrated front-end module awards that include multi-year sensor calibration support. Three-tier pricing structure across premium, standard, and economy levels tracks material substrate—aluminum commands highest placement for heritage brand identities, while plastic architectures compete on MIIT fleet efficiency compliance. Price differentiation hinges on radar-transparent electromagnetic formulation certification and active air-flap system integration. Margins are tightening in chrome-plated finishes as REACH hexavalent chromium restrictions force trivalent chrome conversion costs onto suppliers. Aftermarket providers show greatest price sensitivity due to direct-to-consumer digital platform disintermediation.
Supply Chain Analysis
Freight cost exposure concentrates in aluminum alloy sheet flows from Quebec smelting corridors to Stuttgart and Detroit assembly plants, with energy-intensive smelting amplifying London Metal Exchange volatility pass-through. Tooling for ABS-polycarbonate injection molds concentrates in southern Germany and coastal China, drawing from Saudi Arabian petrochemical feedstock and German compounder formulations. Single-source vulnerability sits with 18-24 month thermoforming die lead times for complex chrome-plated surface finishes. Distribution runs through tier-one module integrators bundling grilles with bumper and lighting assemblies, squeezing tier-two finish specialists from direct OEM access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized thermoforming capacity scarcity for radar-transparent polycarbonate formulations props pricing power for qualified suppliers as electric vehicle platform launches compress development timelines.
For Market Incumbents: Anticipate sensor interference constraints from metallic grille finishes accelerating qualification timelines for polycarbonate-ABS compounds with integrated electromagnetic properties. Defend module integration contracts by deepening backward integration into surface engineering capabilities as REACH restrictions displace traditional plating houses. Prioritize capacity addition in Tamil Nadu and Gujarat corridors to capture PLI scheme incentives for front-end module localization. For New Entrants and Emerging Players: Direct-to-consumer digital platforms offer the most penetrable route for styling-focused grille replacements disintermediating traditional collision repair distributors. Target aftermarket customization channels in United States and European markets where vehicle parc growth outpaces new vehicle production. Pursue biomaterial substitution angle—flax fiber and recycled polymer compounds—for EU Green Deal circular-economy procurement compliance. For Investors and Strategic Acquirers: The window for entry favors material science specialists with radar-transparent formulation capabilities ahead of electric vehicle platform volume ramp. Long-term viability centers on suppliers qualifying polycarbonate grades with integrated metallic flake eliminating secondary coating steps. Watch KBA enforcement timelines for trivalent chrome and physical vapor deposition qualification as inflection indicator for surface engineering value capture shift.| Strategic Initiative | Industry Significance |
|---|---|
| Radar-Transparent Material Qualification | Polycarbonate-ABS compounds with integrated electromagnetic properties capture sensor-integration contracts from traditional plating houses. |
| Active Grille Shutter Integration | EPA CO2 fleet targets and European Commission emissions rules mandate airflow-modulating systems bundling with front-end modules. |
| Biomaterial Substitution Development | Flax fiber and recycled polymer compounds align with EU Green Deal circular-economy procurement guidelines for lightweighting compliance. |
| Regional Manufacturing Footprint Expansion | Tamil Nadu and Gujarat corridors concentrate PLI scheme incentives for tier-one supplier establishment serving domestic OEMs. |
| Surface Engineering Capability Acquisition | Trivalent chrome and physical vapor deposition expertise defends premium placement as REACH hexavalent chromium restrictions accelerate. |
Methodological Framework
Document review covered vehicle production databases, IHS Markit registration data, SEC filings from tier-one suppliers, and regulatory submissions to NHTSA and KBA, complemented by interviews with OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and dealership operations managers. Primary fieldwork across Stuttgart, Detroit, and Shanghai engineering centers validated secondary data on grille architecture specifications and module integration contract structures. Bottom-up build from platform-level content per vehicle and top-down triangulation from fleet emissions compliance targets cross-checked volume and value estimates.
Historical production trajectories were cross-referenced against expert panel input from thermal management and sensor packaging specialists to anchor growth assumptions across the analysis window. Segmentation modeling incorporated vehicle class, propulsion architecture, material substrate, and regional production cluster dimensions. CAGRs were derived from slope analysis of historical penetration rates adjusted for regulatory mandate acceleration and electric vehicle platform launch schedules. Forecast inputs included MIIT fleet efficiency target stringency, EPA CO2 compliance pathway revisions, and active grille shutter adoption curves by OEM tier.
Inputs from OEM platform engineering departments and tier-one supplier program offices were available through the study window; gaps in proprietary tooling cost structures and contract pricing terms introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and electric vehicle platform volume ramp trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Tie Rod Assembly Market
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market
Automotive Assemblies
Automotive Idler Arm Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Automotive Activated Carbon Canister Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Automotive Cross Member Market