
 Automotive Gear Oil Market | 2026-2036
Automotive Gear Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Gear Oil Market Intelligence
The expanding fleet of electric and hybrid vehicles is broadening the product mix beyond traditional manual and automatic transmission fluids for internal combustion engines. This shift creates opportunities for specialized e-axle and reduction gear fluids. Shell plc leverages its extensive distribution network to serve both OEM and aftermarket channels. Concurrently, Fuchs Petrolub SE specializes in high-performance synthetic lubricants for demanding motorsport and commercial vehicle applications.
Automotive gear oil is a specialized lubricant designed to protect, cool, and clean transmissions, differentials, and transfer cases. Its formulation includes base oils and extreme pressure (EP) additives to withstand high loads and prevent wear on gear components. Synthetic gear oil formulations command a price premium due to their superior thermal stability and extended drain intervals. The commercial vehicles segment remains the largest consumer by volume, driven by the needs of heavy-duty truck fleets.
Regulations from bodies like the US EPA and the EU's REACH framework govern the chemical composition and disposal of lubricants. In parallel, China's GB standards set stringent performance and quality benchmarks for products sold within its domestic market. Formulators must now balance performance requirements with evolving environmental compliance and the specific needs of electrified powertrains.
Market Dynamics
The automotive gear oil market is defined by the dual pressures of optimizing lubricants for legacy internal combustion engine (ICE) drivetrains while simultaneously developing novel fluids for the fundamentally different thermal and electrical environments of electric vehicle (EV) powertrains.
Growth Catalysts
- Commercial Vehicle Fleet Expansion:The growth of logistics and heavy-duty trucking fleets, particularly in developing economies, drives volume demand for durable gear oils that extend component life and support longer drain intervals, reducing total cost of ownership for operators.
- Stringent Performance Standards:China's GB standards, which govern lubricant quality and performance, compel both domestic and international suppliers to offer higher-quality formulations, stimulating the premium synthetic gear oil segment within its vast domestic market.
- Advanced Transmission Designs:The adoption of complex multi-speed automatic and dual-clutch transmissions (DCTs) in passenger cars requires specialized, lower-viscosity fluids with specific frictional characteristics, creating new, high-value product categories.
Market Restraints
- Base Oil Price Volatility:The market is exposed to price fluctuations in key raw materials, particularly Group III and IV synthetic base oils, which are derived from crude oil and subject to geopolitical and supply-demand instabilities, impacting formulator margins.
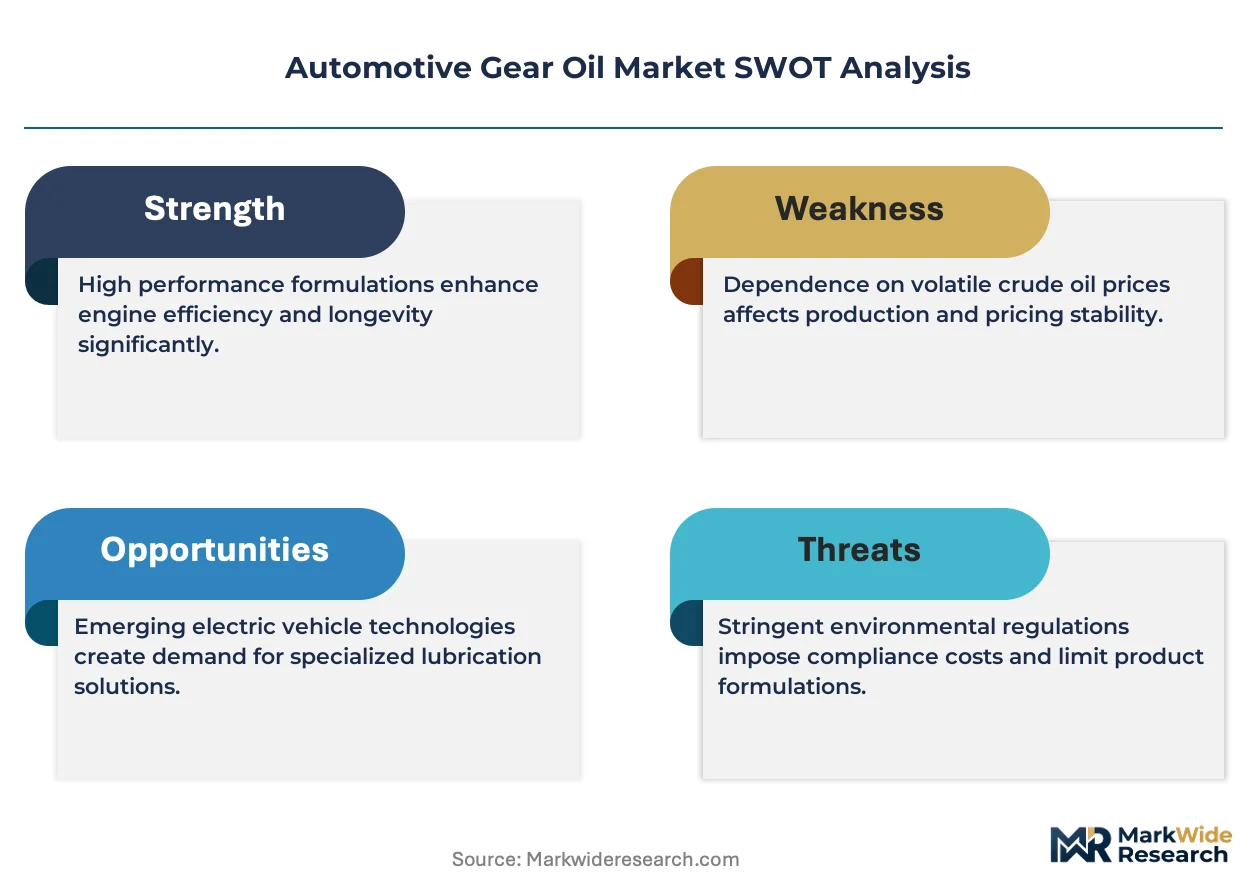
- Threat of Electrification:The transition to battery electric vehicles (BEVs) eliminates the need for traditional transmission and differential gear oils, creating a direct substitution threat as integrated e-axle systems require specialized e-fluids with different properties.
- Regulatory Compliance Overhead:Formulators face significant administrative and testing costs to ensure products comply with disparate chemical regulations, such as the EU's REACH framework and the US EPA's chemical reporting rules, which can slow product development.
Strategic Opportunities
- E-Mobility Fluids:The nascent but rapidly expanding market for EV-specific fluids, including e-axle and reduction gear lubricants, presents a significant opportunity for formulators to develop products with enhanced thermal conductivity and electrical resistivity.
- Bio-Based Lubricants:Growing environmental concerns and corporate sustainability goals create a market for biodegradable gear oils derived from renewable feedstocks, appealing to fleet operators and consumers with a focus on reducing environmental impact.
- Aftermarket in Emerging Economies:Rising vehicle ownership in Southeast Asia and Latin America creates a large, underpenetrated aftermarket for higher-quality gear oils as vehicle owners seek to upgrade from basic lubricants to improve performance and longevity.
Industry Challenges
- Formulation Complexity:Lubricant developers are challenged to create universal fluids that meet the conflicting demands of fuel efficiency, extreme pressure protection, and compatibility with new materials used in modern transmissions and electrified drivetrains.
- Aftermarket Education:A significant challenge lies in educating independent repair shops and technicians on the specific fluid requirements for new technologies like DCTs and EVs, as using incorrect fluids can lead to catastrophic component failure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Gear Oil Market |
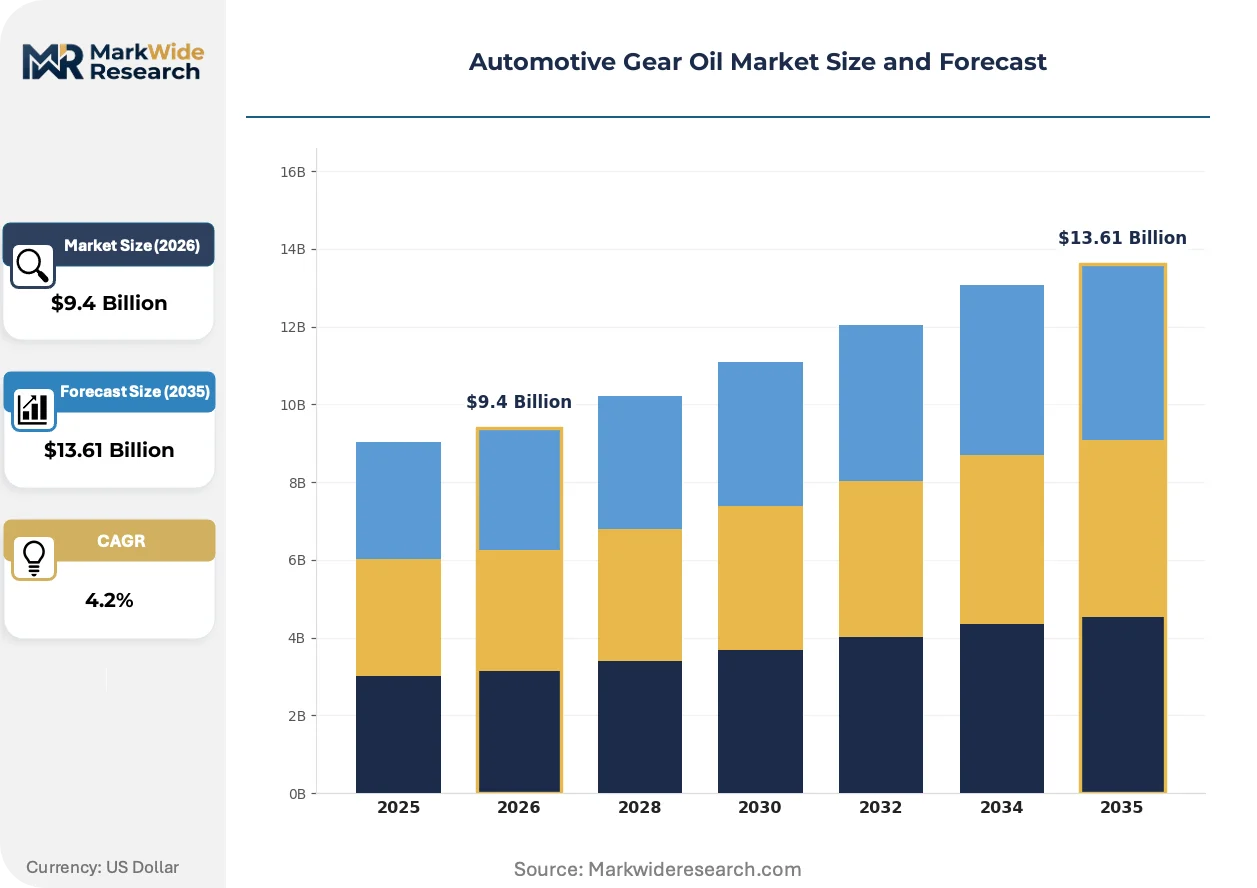
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $13.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Transmission Oil, Automatic Transmission Fluid, Synthetic Gear Oil, Mineral Gear Oil, Semi-Synthetic Oil Viscosity Grade: SAE 75W-80, SAE 80W-90, SAE 85W-140, SAE 90, SAE 75W-90 Application: Passenger Vehicles, Commercial Vehicles, Off-Highway Vehicles, Marine Equipment, Two-Wheelers End User: OEMs, Automotive Repair Shops, Fleet Operators, Vehicle Maintenance Centers |
| Companies Covered | BP plc, Fuchs Petrolub SE, ExxonMobil Corporation, Valvoline Inc., Phillips 66 Company, Shell plc, TotalEnergies SE, Idemitsu Kosan Co. Ltd, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Gear Oil Market Strategic Shifts & Innovations
Innovation in the automotive gear oil sector is bifurcating. One path focuses on enhancing the efficiency and durability of lubricants for advanced ICE transmissions, while the other involves creating entirely new fluid technologies to meet the unique demands of electric vehicle drivetrains.
Low-viscosity synthetic fluids are becoming the standard for modern driveline components. These formulations use advanced polyalphaolefin (PAO) or ester base oils to reduce internal friction and improve fuel economy. OEMs are increasingly specifying these fluids as factory-fill for multi-speed automatic transmissions and efficiency-focused differentials, and this technology is overtaking higher-viscosity mineral-based oils in new vehicle production.
The EU's REACH regulation is forcing a significant reformulation of additive packages used in gear oils. This framework mandates rigorous testing and registration for all chemical substances, leading to the phase-out of some traditional sulfur-phosphorus extreme pressure (EP) additives. Lubricant manufacturers targeting the European market must invest in R&D to find compliant, high-performance alternatives, particularly for heavy-duty commercial vehicle applications.
A shift from preventative to predictive maintenance is altering purchasing behavior among large fleet operators. Instead of adhering to fixed mileage-based drain intervals, these customers use onboard sensors and regular oil analysis to determine the optimal time for a fluid change. This model disrupts traditional volume-based sales and favors suppliers offering long-life synthetic products and integrated fluid condition monitoring services, a trend most visible in North America.
Automotive Gear Oil Market Segmentation
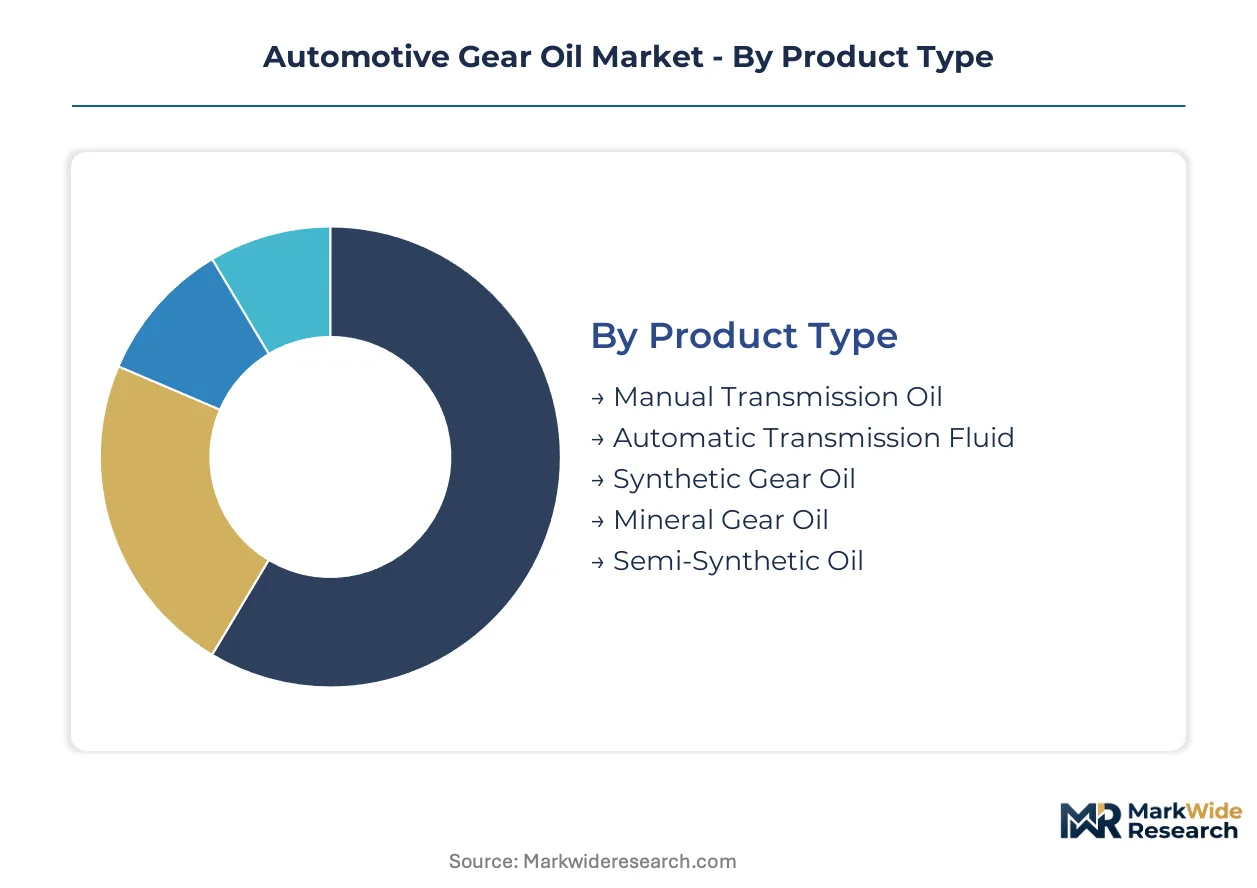
Market segmentation clarifies the diverse product requirements and consumption patterns within the automotive gear oil industry. Understanding these distinctions allows formulators and suppliers to align product development and distribution strategies with specific end-user needs and vehicle technologies. This granular view highlights areas of established volume and emerging growth.
Product Type:
The product type segmentation highlights the trade-off between high-volume, cost-effective formulations and premium, performance-driven lubricants.
- Synthetic Gear Oil:These formulations command a price premium due to superior thermal stability and extended drain intervals, serving demanding motorsport and commercial vehicle applications. Demand for synthetic options increases as fleet operators seek to reduce total cost of ownership.
- Automatic Transmission Fluid:Specialized fluids for complex multi-speed automatic and dual-clutch transmissions (DCTs) in passenger cars require specific frictional characteristics. OEMs increasingly specify these lower-viscosity fluids as factory-fill for efficiency-focused drivetrains.
- Manual Transmission Oil:This category encompasses lubricants designed for traditional manual gearboxes, offering wear protection and smooth shifting performance.
- Mineral Gear Oil:Derived from crude oil, these traditional lubricants provide basic protection for less demanding applications and older vehicle models.
- Semi-Synthetic Oil:A blend of mineral and synthetic base oils, offering improved performance over mineral oils at a more accessible price point.
Today's leader: Mineral Gear Oil. Tomorrow's challenger: Synthetic Gear Oil.
Viscosity Grade:
Viscosity grade differentiation reflects the specific operational requirements and temperature ranges of various automotive components.
- SAE 75W-90:A common synthetic viscosity grade for passenger car differentials and manual transmissions, balancing fuel efficiency with wear protection. OEMs frequently specify this grade for modern driveline components.
- SAE 80W-90:Widely used in heavy-duty commercial vehicle axles and transmissions, this grade provides robust load-carrying capacity and thermal stability. Logistics and trucking fleets rely on its durability.
- SAE 75W-80:A lower-viscosity option gaining traction in newer passenger car manual transmissions for improved fuel economy.
- SAE 85W-140:This higher-viscosity grade is suitable for extreme load applications and older heavy-duty equipment operating in warmer climates.
- SAE 90:A monograde oil typically used in older vehicles or specific industrial gear applications where temperature fluctuations are minimal.
Viscosity grades like SAE 75W-90 are expanding most quickly, driven by modern vehicle specifications.
Application:
Application segmentation reveals how distinct vehicle categories impose unique operational demands on gear oil formulations.
- Commercial Vehicles:This segment remains the largest consumer by volume, driven by heavy-duty truck fleets requiring durable gear oils for extended component life and longer drain intervals. The growth of logistics in developing economies fuels this demand.
- Passenger Vehicles:Advanced transmission designs like multi-speed automatics and DCTs in passenger cars require specialized, lower-viscosity fluids with specific frictional characteristics. The shift to EVs also creates demand for e-fluids in this category.
- Off-Highway Vehicles:Construction equipment, agricultural machinery, and mining vehicles require robust gear oils capable of withstanding extreme loads and harsh operating conditions.
- Marine Equipment:Gear oils for marine applications must offer excellent corrosion protection and perform reliably in wet environments.
- Two-Wheelers:Motorcycles and scooters utilize gear oils tailored to their compact drivetrains, often integrated with engine lubrication systems.
Commercial Vehicles represent the largest demand segment, with Passenger Vehicles dictating fluid innovation for new drivetrain technologies.
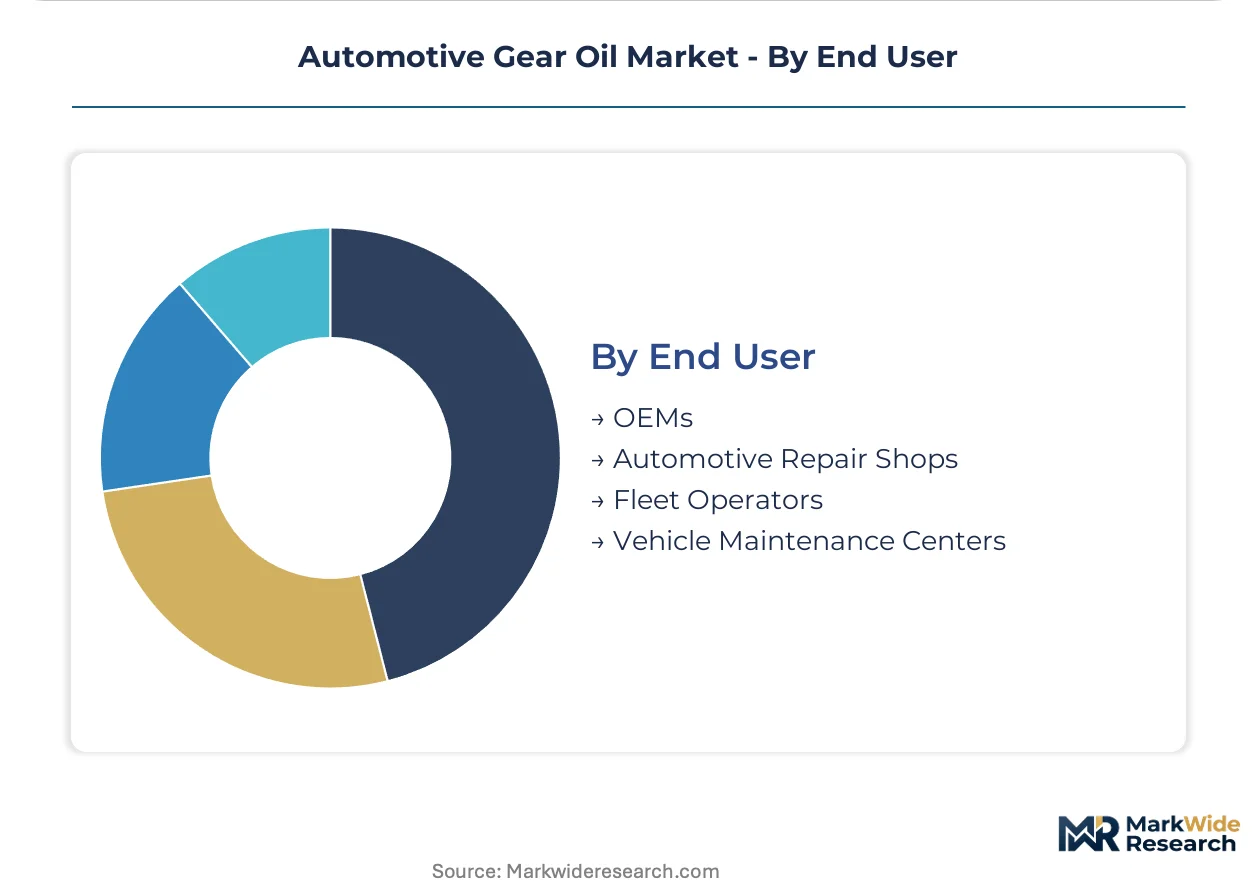
End User:
End user segmentation illustrates the varied distribution channels and purchasing behaviors across the automotive gear oil market.
- Fleet Operators:These large-scale consumers prioritize lubricants that extend component life and reduce maintenance downtime, often adopting integrated fluid condition monitoring services. Their purchasing decisions focus on total cost of ownership.
- OEMs:Original Equipment Manufacturers specify factory-fill lubricants for new vehicles, influencing initial market demand for specialized, lower-viscosity fluids. Their requirements drive much of the R&D in new fluid technologies.
- Automotive Repair Shops:Independent repair shops serve the aftermarket, requiring a wide range of gear oils for various vehicle makes and models. Education on fluid requirements for new technologies is a significant challenge here.
- Vehicle Maintenance Centers:Dealership service centers and chain maintenance facilities provide routine fluid changes, often adhering to manufacturer specifications or established service protocols.
Fleet Operators are a significant volume driver, while OEMs dictate initial product specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive gear oil market faces a dynamic regulatory landscape, where stringent environmental compliance in developed regions can sometimes lead to production shifts towards areas with differing standards. This creates a complex global supply chain for formulators balancing performance with evolving legislative requirements.
China
China drives immense demand for automotive gear oil due to its massive vehicle manufacturing base and expanding commercial fleet. The country's GB standards set rigorous performance and quality benchmarks, compelling lubricant manufacturers to offer high-quality formulations. Industrial clusters in the Yangtze River Delta actively develop specialized e-fluids for the burgeoning domestic EV market.
United States
The United States exhibits strong demand for advanced synthetic gear oils, particularly from its heavy-duty trucking sector and premium passenger vehicle market. The US EPA regulations influence the chemical composition and disposal practices of lubricants, pushing for more environmentally friendly formulations. Detroit's automotive hub continues to innovate, requiring specialized fluids for new transmission designs and electrified powertrains.
Germany
Germany represents a key market for high-performance automotive gear oils, fueled by its robust automotive industry and a strong focus on engineering excellence. The EU's REACH framework mandates rigorous testing and registration for chemical substances, leading to significant reformulation of additive packages. Bavarian manufacturers increasingly specify low-viscosity synthetic fluids for advanced automatic transmissions and electric drivetrains.
India
India's automotive gear oil market expands with its rapidly growing vehicle parc, especially in the commercial vehicle and two-wheeler segments. The country's national environmental policies are gradually tightening, influencing lubricant formulations and disposal. Major industrial corridors like the Delhi-Mumbai Industrial Corridor are seeing increased demand for durable gear oils to support logistics and manufacturing growth.
Japan
Japan's market emphasizes precision engineering and fuel efficiency, driving demand for specialized, low-viscosity gear oils for its advanced passenger car transmissions. JIS standards ensure high quality and performance for lubricants sold within the country. Automotive research centers in Aichi Prefecture actively develop next-generation e-fluids for hybrid and electric vehicle applications.
Automotive Gear Oil Market Key Industry Players
Portfolio diversification dominates the current landscape, as major players adapt to the dual demands of traditional internal combustion engine (ICE) and electric vehicle (EV) drivetrains. The market structure features integrated oil majors alongside specialized lubricant producers and regional manufacturers. Strategic partnerships and targeted acquisitions represent common competitive moves among these diverse entities.
Global integrated energy companies like Shell plc and ExxonMobil Corporation leverage extensive R&D capabilities and vast distribution networks to serve both OEM and aftermarket channels. Fuchs Petrolub SE, a specialist in high-performance lubricants, focuses on advanced synthetic formulations for demanding applications such as motorsport and heavy-duty commercial vehicles. These companies collectively anchor the premium segment, driving innovation in e-fluids and long-drain formulations.
| Leading Market Players |
|---|
| BP plc |
| Fuchs Petrolub SE |
| ExxonMobil Corporation |
| Valvoline Inc. |
| Phillips 66 Company |
| Shell plc |
| TotalEnergies SE |
| Idemitsu Kosan Co. Ltd |
| Chevron Corporation |
| Others |
Cost & Logistics Intelligence
The EU's REACH framework gates qualified lubricant supply and premium-tier pricing access by mandating rigorous chemical substance testing. This regulatory compliance drives up formulation costs across the market, particularly for advanced synthetic gear oils.
Pricing Analysis
Distributor margins reflect the value added through local inventory and technical support for diverse product lines. Transactional pricing dominates for standard mineral and semi-synthetic oils, while long-term contracts secure supply for OEMs. Price differentiation stems from base oil quality, with synthetic formulations commanding a premium due to performance and extended drain intervals. Pricing pressure intensifies on basic mineral oils from raw material volatility, making fleet operators highly price-sensitive for bulk purchases, unlike OEMs who prioritize performance and specification adherence.
Supply Chain Analysis
Regional distribution centers facilitate efficient delivery of gear oils to automotive repair shops and fleet operators. Supply of Group III and IV synthetic base oils concentrates in key refining hubs like North America and the Middle East, with additive packages sourced globally. The supply chain relies on a few major producers for critical raw materials, creating single-source vulnerability for specialized additives. Distribution runs through integrated oil majors leveraging their vast networks and specialized lubricant producers utilizing direct sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive gear oil market functions as a regulatory compounder, with China's GB standards driving demand for higher-quality, compliant formulations. This regulatory push accelerates product innovation and market segmentation.
For Market Incumbents: Anticipate the ongoing shift towards electric vehicles by significantly increasing R&D investment in e-fluids with enhanced thermal and electrical properties. Strengthen OEM partnerships to ensure factory-fill specifications for new EV drivetrains, mitigating the direct substitution threat from electrification. Deepen channel control in aftermarket segments to protect market share for traditional ICE lubricants, leveraging extensive distribution networks.
For New Entrants and Emerging Players: Independent repair shops in emerging economies represent an underserved buyer archetype for high-quality gear oils, particularly those upgrading from basic lubricants. Target specialized e-mobility fluids for the nascent EV aftermarket, focusing on performance differentiation and technical support. Penetrate the growing demand for bio-based lubricants in sustainability-conscious fleets, leveraging environmental compliance as a key market entry point.
For Investors and Strategic Acquirers: Roll-up economics work for specialized lubricant producers because structural fragmentation exists within niche high-performance segments. Focus on acquiring additive package formulators or e-fluid specialists to gain intellectual property and market access for new technologies. The long-term viability of the market remains strong due to the continued need for essential fluids across diverse drivetrains. A signal to watch is the accelerating adoption rates of EVs in commercial fleets, indicating a pivot point for fluid demand.
| Strategic Initiative | Industry Significance |
|---|---|
| E-Fluid R&D Investment | Develops specialized lubricants for EV powertrains, addressing unique thermal and electrical demands. |
| Bio-Lubricant Product Launch | Caters to sustainability-conscious fleet operators and environmental compliance mandates like REACH. |
| OEM Partnership Expansion | Secures factory-fill specifications for advanced transmission designs and new vehicle platforms. |
| Aftermarket Education Program | Informs independent repair shops on correct fluid requirements for new driveline technologies. |
| Additive Package Reformulation | Ensures compliance with evolving chemical regulations, such as the EU's REACH framework. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming a robust data approach. Primary research involved discussions with lubricant R&D directors, fleet maintenance managers, OEM powertrain engineers, and aftermarket distributors. This input was validated against secondary sources including vehicle production databases, customs data, regulatory filings, and industry association reports. A multi-layered bottom-up and top-down triangulation process ensured data coherence and accuracy.
Segment-weighting across product type, viscosity grade, application, end user, and regional regulatory compliance formed the core analytical framework over the projection horizon. Compound Annual Growth Rates were derived from historical data analysis combined with future market growth projections. Key industry-specific forecast inputs included electric vehicle adoption rates and base oil price trends. This granular approach facilitated market sizing and future trend identification.
Underlying measurement precision varies by segment; commercial vehicle and passenger vehicle applications carry tighter precision. Forecasts reflect assumptions regarding technological and regulatory shifts, with geopolitical and raw material disruptions posing risk. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
Automotive Bushing Market
Automotive Components
Automotive Refrigerant Market
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
India Automotive Pneumatic Actuators Market
Automotive Components
Africa and Middle East Automotive Actuators Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Global Automotive HUD Market
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
Automotive Mufflers Market
Automotive Components
Automotive Light Bars Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Global Automotive Sun Visor Market