
 Automobile Fluid Pipe Products Market | 2026-2036
Automobile Fluid Pipe Products Market Size, Share, and Industry Trends Forecast 2026-2036
Automobile Fluid Pipe Products Market Insights
Southeast Asian manufacturing capacity is tilting toward fluid pipe component localization as OEMs diversify supply sources. TI Fluid Systems leverages integrated thermal management portfolios to anchor European and North American OEM relationships. Cooper Standard competes through polymer expertise in lightweight coolant and fuel delivery architectures. Parker Hannifin sustains hydraulic and pneumatic crossover technologies that extend into commercial vehicle fluid routing systems.
Automobile fluid pipe products encompass conduits engineered to transport fuel, brake fluid, coolant, oil, and refrigerant throughout vehicle propulsion and thermal systems, typically fabricated from multi-layer polymer composites, corrosion-resistant aluminum alloys, or coated steel with specified burst pressures and chemical resistance ratings. These components maintain system integrity across temperature extremes from engine bay thermal cycling to underbody exposure, preventing leakage that would compromise safety or emissions compliance. Fuel lines and brake lines command premium margin pools due to stringent safety certification requirements and OEM captive sourcing preferences, while heater hoses see accelerating specification changes as electrified powertrains demand higher-temperature coolant circuits. Plastic and aluminum material categories are gaining specification share against traditional rubber and steel as weight reduction targets intensify across passenger vehicle and light truck applications.
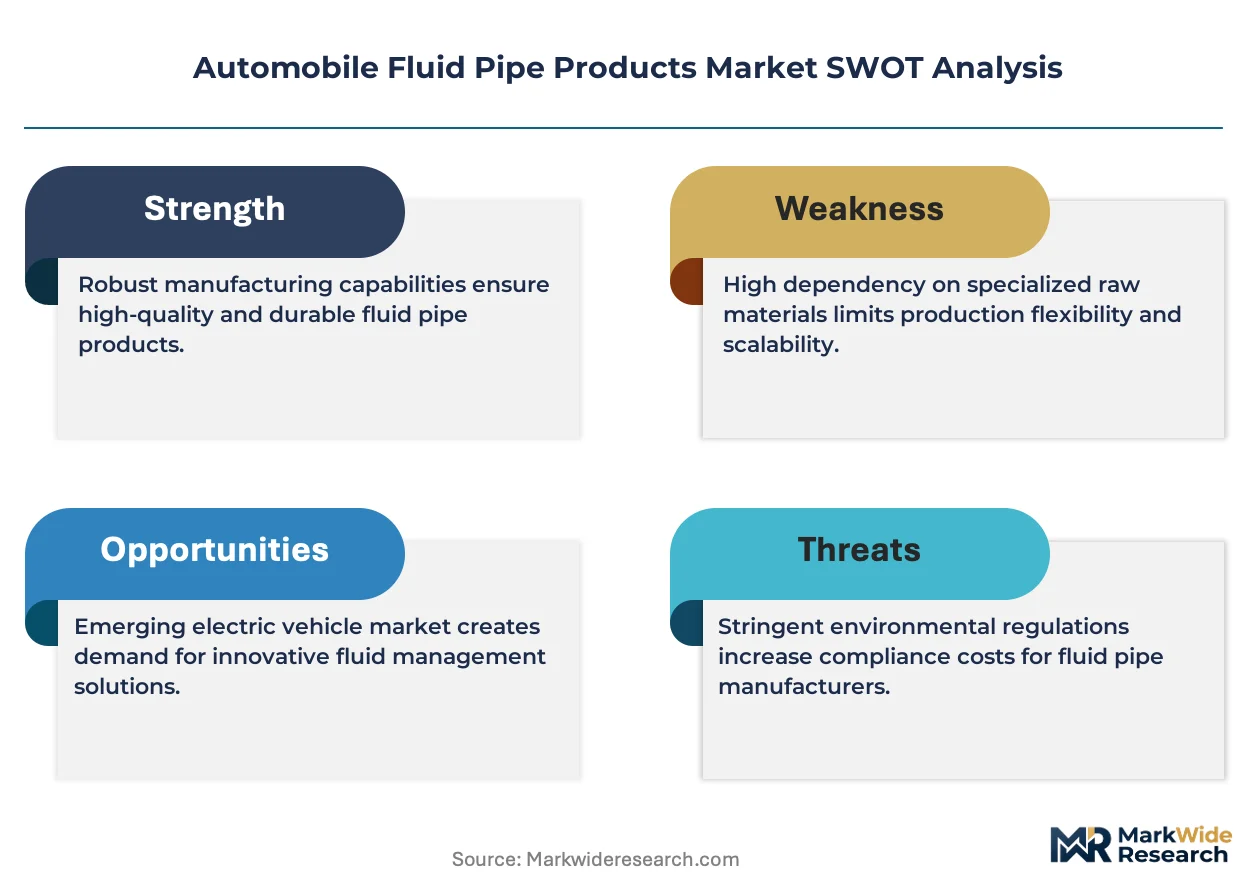
EPA tailpipe and evaporative emissions standards, EU REACH chemical restrictions, and NHTSA brake system safety regulations collectively mandate fluoropolymer barrier layers, low-permeation joint designs, and traceable material certifications that elevate engineering costs and consolidate supplier qualification pools. Japan's METI vehicle energy efficiency frameworks and China's GB standards for automotive fuel systems add further compliance layers for manufacturers serving multi-regional OEM programs. Stakeholders must monitor thermal management architecture shifts in battery electric platforms where coolant pipe complexity and refrigerant circuit integration are redefining component value and qualification timelines.
Market Dynamics
Electrified powertrain architectures are fragmenting fluid pipe demand patterns as battery thermal management systems require entirely different coolant circuit designs than internal combustion engine architectures. OEMs must simultaneously sustain legacy fuel and brake line production while qualifying new refrigerant and battery coolant piping specifications.
Growth Catalysts
- Battery Thermal Management Expansion:Electric vehicle platforms require multi-circuit coolant architectures with higher temperature ratings and refrigerant integration. This specification shift expands addressable component value per vehicle.
- EPA Tier 3 Evaporative Emissions Standards:Low-permeation multi-layer barrier requirements for fuel system components are mandating fluoropolymer upgrades that elevate technical qualification barriers and consolidate supplier pools.
- Thailand and Vietnam Manufacturing Clusters:Southeast Asian OEM assembly capacity expansion is creating localized demand for fluid pipe component fabrication to reduce logistics exposure and tariff friction.
Market Restraints
- Aluminum Alloy Price Volatility:Lightweighting specifications are increasing exposure to London Metal Exchange aluminum price swings, compressing margin predictability for multi-year OEM supply agreements.
- Fluoropolymer Supply Concentration:Barrier layer resin production concentrates among limited chemical suppliers, creating qualification risk if primary sources face force majeure or export restriction events.
- Steel-to-Aluminum Substitution Ceiling:High-pressure brake line applications retain steel specification dominance due to fatigue resistance requirements that aluminum alloys have not yet matched at competitive cost.
Strategic Opportunities
- India Automotive PLI Scheme:Component-level production-linked incentives are attracting fluid pipe manufacturing investment to serve domestic OEM expansion and regional export positioning.
- Refrigerant Circuit Integration:Heat pump thermal management convergence is creating demand for unified refrigerant-coolant piping modules that reduce connection points and assembly labor.
- Direct OEM Tier 1 Qualification:Bypassing traditional system integrator relationships through direct engineering engagement is opening margin capture previously absorbed by intermediate suppliers.
Industry Challenges
- Dual-Architecture Engineering Bandwidth:Suppliers must maintain parallel ICE and BEV fluid system expertise while technical workforce specialization in polymer composite processing remains scarce.
- Homologation Timeline Compression:OEM platform acceleration cycles are compressing burst testing, chemical resistance validation, and thermal cycling certification windows from 24 months toward 14-16 month targets.
- Legacy System Integration Friction:Electrified coolant architectures must interface with existing manufacturing footprints and service infrastructure, creating design constraint complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automobile Fluid Pipe Products Market |
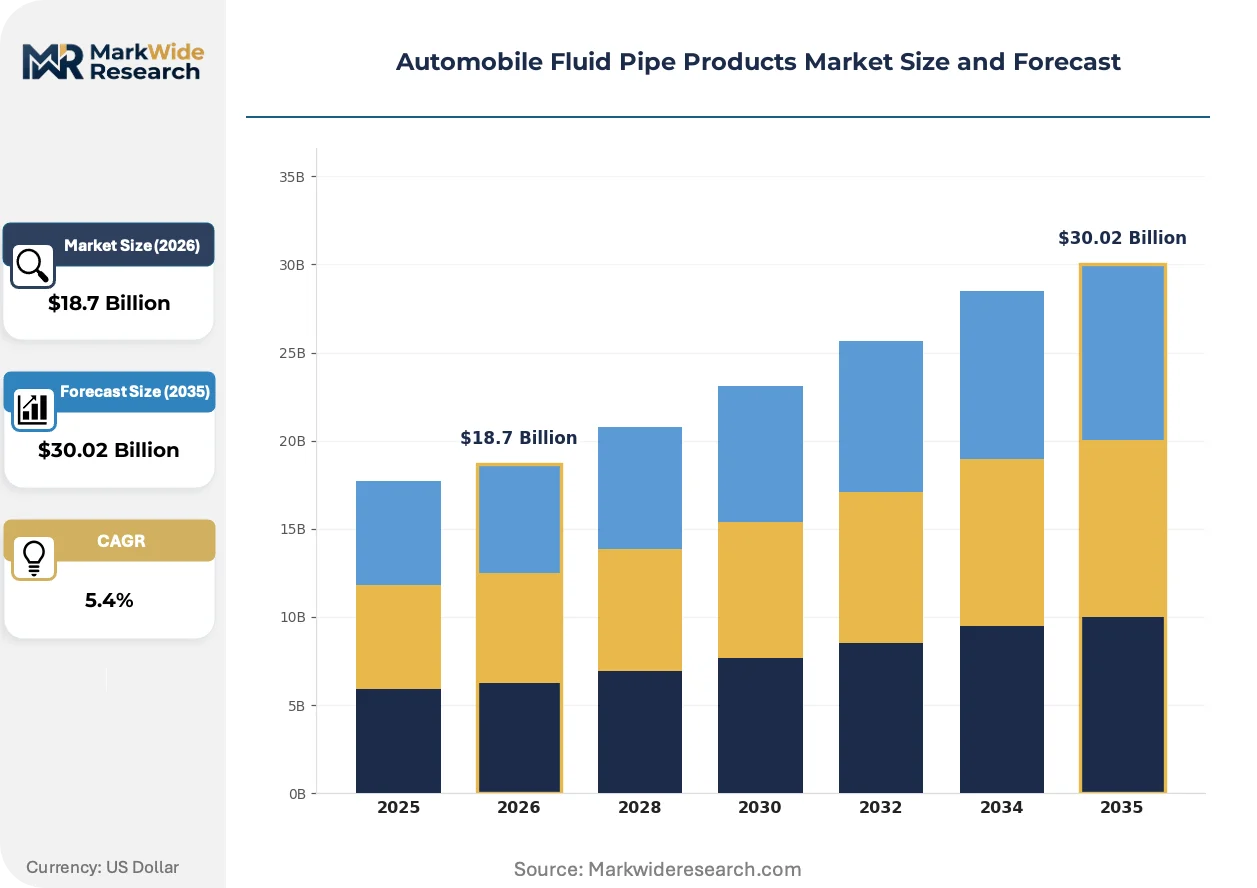
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Lines, Brake Lines, Oil Coolers, Heater Hoses Material: Plastic, Aluminum, Steel, Rubber End User: OEMs, Aftermarket Providers, Dealerships, Repair Shops Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Light Trucks |
| Companies Covered | TI Fluid Systems, Cooper Standard, Parker Hannifin, Motonic, Sumitomo Riko Company Limited, Sanoh Industrial Co., Ltd., Benteler, Linamar, Akwel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automobile Fluid Pipe Products Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to redefine fluid pipe construction methods. Manufacturers are pivoting from established rubber-steel combinations toward engineered polymer systems that satisfy simultaneous weight, permeation, and temperature demands.
Multi-layer polymer composite tubing with ethylene tetrafluoroethylene barrier layers is rendering obsolete traditional nitrile rubber fuel hoses in high-performance applications. European and North American OEMs are specifying these constructions for direct-injection fuel systems and hybrid thermal circuits. The shift is compressing qualification timelines as suppliers must demonstrate 15-year permeation performance with accelerated aging protocols.
EU F-Gas Regulation phasedown schedules are restricting hydrofluorocarbon refrigerant formulations and mandating lower-global-warming-potential alternatives. This chemistry transition requires compatible elastomer and barrier material validation for air conditioning and heat pump circuits. Suppliers serving German and French OEM programs are prioritizing R-1234yf and R-744 system compatibility in new product development pipelines.
Fleet operators and commercial vehicle buyers are consolidating specification authority at the corporate procurement level, displacing decentralized plant-level purchasing for fluid system components. This concentration is compressing supplier counts and elevating annual volume commitment requirements. The pattern is most visible in North American heavy-duty truck and bus manufacturing where fleet standardization programs dominate component selection.
Automobile Fluid Pipe Products Market Segmentation
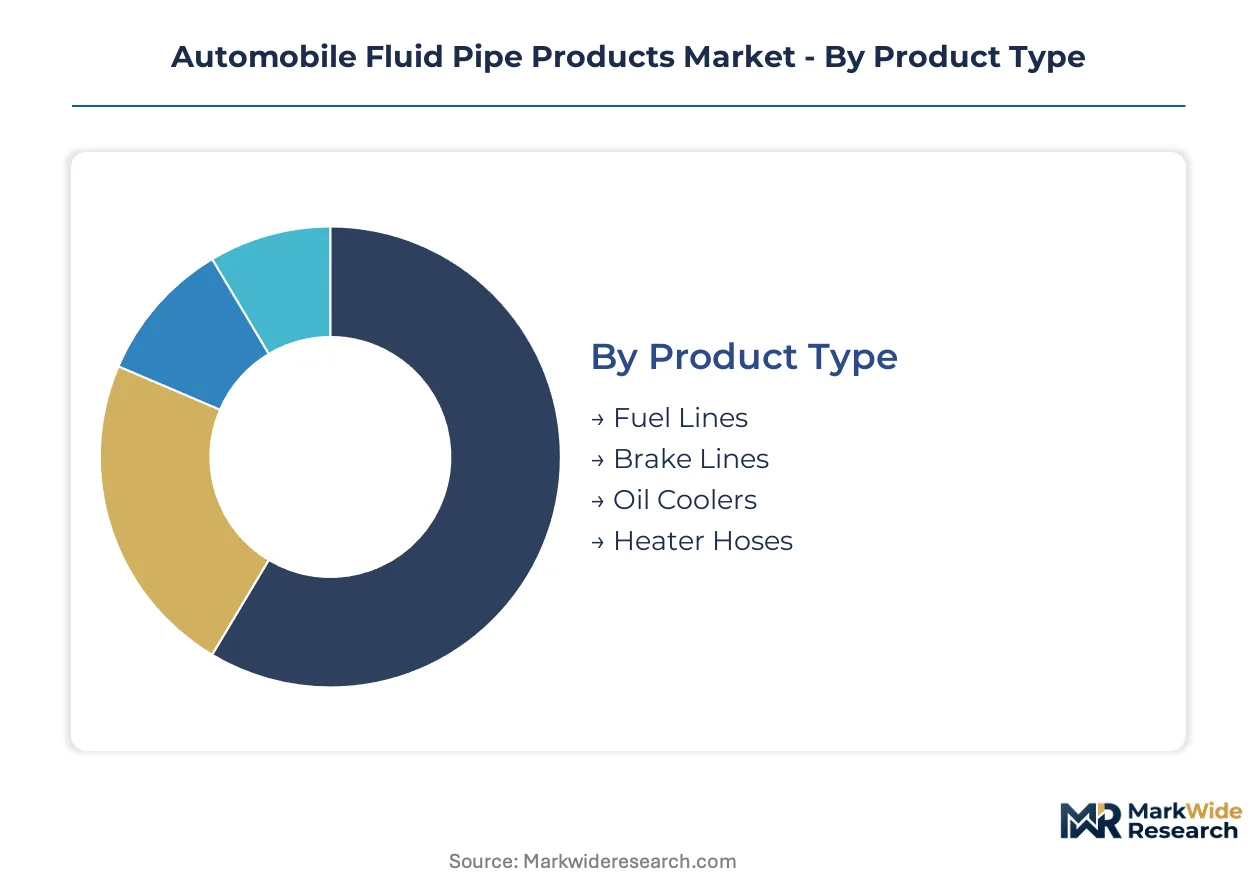
Fluid pipe specification diversity reflects divergent thermal management demands across electrified and combustion architectures. Material selection and end-user channel strategies determine margin capture and qualification burden for component suppliers serving multi-platform OEM programs.
Product Type:
Use-case spectrum spans safety-critical pressure systems to flexible thermal routing circuits with vastly different certification protocols.
- Fuel Lines:Multi-layer polymer composites with fluoropolymer barrier layers deliver sub-permeation performance for direct-injection gasoline and diesel delivery. EPA Tier 3 evaporative emissions mandates in the United States and EU REACH chemical restrictions are consolidating supplier qualification pools around demonstrated 15-year permeation resistance.
- Brake Lines:Double-wall steel tubing with corrosion-resistant coatings maintains dominance in hydraulic brake circuits due to fatigue resistance requirements that aluminum alloys have not yet matched at competitive cost. NHTSA brake system safety regulations mandate burst pressure certification and traceable material documentation that elevate engineering costs.
- Oil Coolers:Aluminum brazed heat exchangers with integrated piping serve transmission and engine oil thermal management in performance and heavy-duty applications.
- Heater Hoses:EPDM rubber and polymer composite constructions route engine coolant to cabin heat exchangers, with specification shifts toward higher-temperature ratings for electrified powertrain coolant circuits.
Established volume favors brake lines; emerging adoption favors fuel lines with advanced barrier specifications.
Material:
Cost tier differentiation separates premium lightweight specifications from commodity corrosion-resistant constructions.
- Plastic:Nylon 12 and polyphenylene sulfide formulations dominate polymer fuel and vapor lines with 40-60% weight reduction versus metal alternatives. Japanese OEMs led specification adoption for hybrid thermal management circuits.
- Aluminum:Extruded and drawn alloy tubing serves air conditioning, charge air cooling, and emerging battery thermal management circuits where weight reduction targets intensify. London Metal Exchange price volatility compresses margin predictability for multi-year supply agreements.
- Steel:Coated and stainless steel retains specification dominance in high-pressure brake and fuel injection applications where fatigue life and crash safety override lightweighting priorities.
- Rubber:EPDM and fluorocarbon elastomer hoses persist in flexible connections and vibration-isolated segments where polymer rigidity limits application.
Steel maintains brake line dominance; aluminum gains share fastest in thermal management expansion.
End User:
Customer type concentration determines pricing leverage and technical engagement depth across the value chain.
- OEMs:Direct Tier 1 qualification for platform-level supply agreements requires 24-36 month engineering validation cycles and captive production capacity commitments. German and Japanese OEMs maintain the most stringent material certification requirements.
- Aftermarket Providers:Independent distributors and private-label suppliers serve vehicle service life replacement demand with reduced barrier layer specifications and shorter qualification windows.
- Dealerships:Authorized service networks source OEM-specified components through franchised distribution with warranty compliance obligations.
- Repair Shops:Independent maintenance facilities prioritize cost-optimized alternatives with functional equivalence to original equipment specifications.
OEM direct relationships capture premium margin; aftermarket channels expand volume through vehicle parc aging.
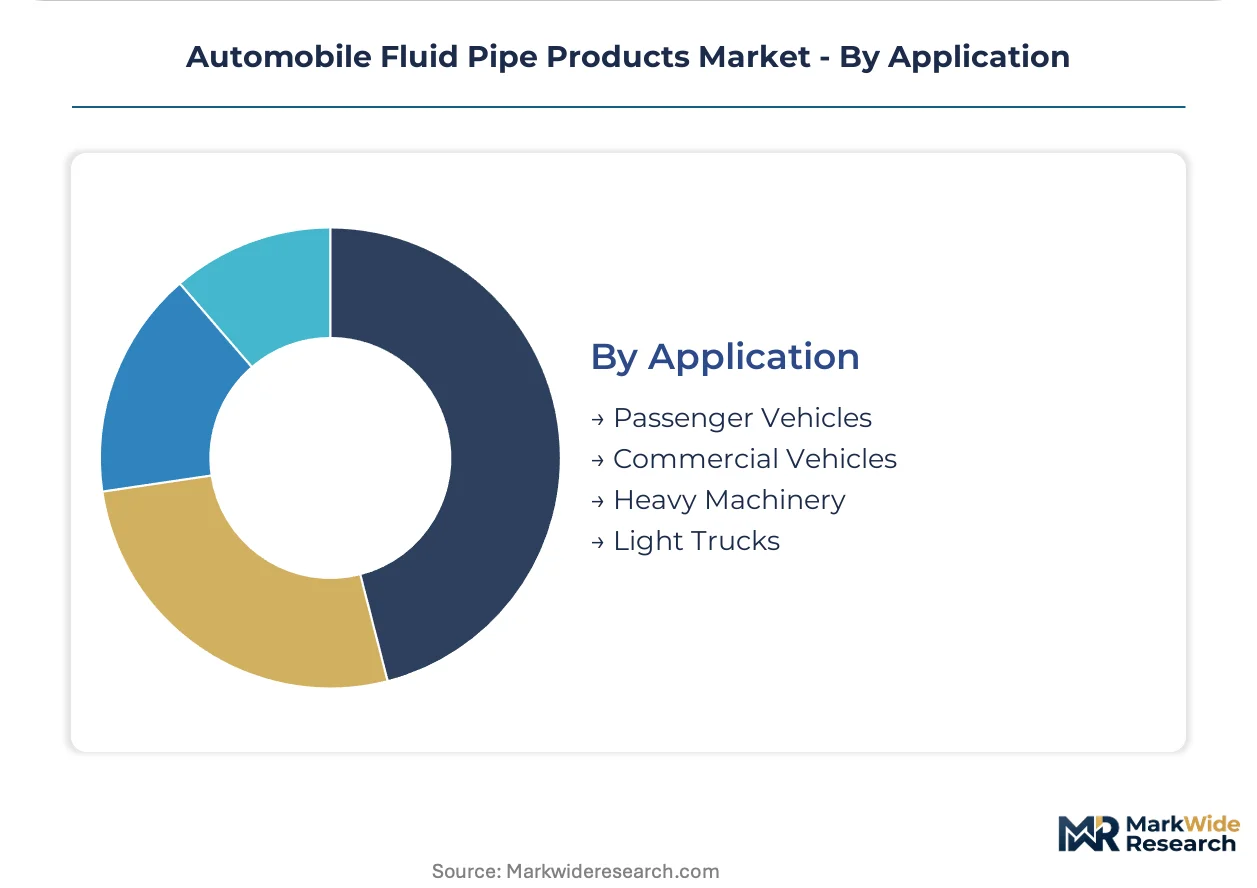
Application:
Volume concentration varies sharply between high-unit passenger production and low-volume heavy-duty specifications.
- Passenger Vehicles:Light-duty automotive platforms generate the highest unit demand for fuel, brake, and thermal management piping with accelerating electrification-driven specification changes.
- Commercial Vehicles:Fleet-operated trucks and buses consolidate procurement authority at corporate levels, compressing supplier counts and elevating annual volume commitment requirements across North American heavy-duty manufacturing.
- Heavy Machinery:Construction and agricultural equipment applications demand enhanced durability ratings and extended service intervals with specialized joint designs.
- Light Trucks:Pickup and van platforms in the United States combine passenger vehicle production scale with commercial-grade durability requirements.
Passenger vehicles anchor unit volume; commercial vehicles concentrate procurement leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluid pipe manufacturing clusters around OEM assembly footprints in Germany, Japan, and the United States, with emerging capacity expansion in Thailand and Vietnam reshaping supplier geography.
United States
Detroit-area OEMs and Southern transplant factories drive demand for lightweight fuel and brake line specifications. EPA Tier 3 evaporative emissions standards mandate fluoropolymer barrier layers that elevate technical qualification thresholds. Texas and Michigan host the densest supplier fabrication corridors serving North American light truck and passenger vehicle programs.
Germany
Premium OEM thermal management requirements accelerate specification shifts toward multi-layer polymer composites and aluminum coolant architectures. EU F-Gas Regulation phasedown schedules force rapid material validation for R-1234yf and R-744 refrigerant compatibility. Baden-Württemberg and Bavaria concentrate Tier 1 engineering centers and prototype testing facilities.
Japan
Hybrid and battery electric platform proliferation generates specialized coolant circuit demand distinct from legacy combustion architectures. METI vehicle energy efficiency frameworks impose material traceability and permeation performance documentation requirements. Kanto and Chubu regions anchor polymer composite processing expertise for domestic OEM captive supply relationships.
China
Domestic EV platform volume expansion creates the world's largest addressable market for battery thermal management piping. GB standards for automotive fuel systems and MIIT new energy vehicle mandates impose dual compliance layers for multi-regional suppliers. Yangtze River Delta and Pearl River Delta manufacturing zones attract foreign joint venture fluid pipe capacity to localize for export and domestic OEM programs.
Thailand
OEM assembly diversification from China-origin supply chains accelerates component localization mandates for Japanese and American transplant factories. Board of Investment automotive sector incentives reduce tariff exposure for fluid pipe manufacturers establishing Thai production bases. Eastern Economic Corridor industrial zones concentrate new extrusion and brazing capacity to serve Southeast Asian export platforms.
Automobile Fluid Pipe Products Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying materials and joint technologies. The supplier base fragments across three capability layers: multinational system houses with thermal management portfolios, regional metal-forming specialists with OEM captive relationships, and material science firms with barrier layer resin expertise. Consolidation pressure concentrates among mid-scale fabricators lacking either scale economies or differentiated polymer processing capabilities. Strategic moves center on backward integration into fluoropolymer resin supply and geographic expansion into India and Southeast Asian manufacturing corridors.
Among the named participants, TI Fluid Systems and Cooper Standard exemplify integrated thermal management platform providers with multi-regional OEM qualification depth, while Parker Hannifin occupies a position spanning hydraulic crossover technologies and commercial vehicle fluid routing. Motonic, Sumitomo Riko, and Sanoh Industrial represent Asia-Pacific-based specialists with polymer and rubber processing heritage serving domestic OEM captive supply structures. Benteler and Linamar anchor European and North American metal-forming capabilities with aluminum extrusion and precision tubing expertise for high-pressure applications.
| Leading Market Players |
|---|
| TI Fluid Systems |
| Cooper Standard |
| Parker Hannifin |
| Motonic |
| Sumitomo Riko Company Limited |
| Sanoh Industrial Co., Ltd. |
| Benteler |
| Linamar |
| Akwel |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor carries fluoropolymer barrier resins and aluminum alloy feedstock at freight rates that directly compress Tier 2 supplier margins while amplifying price differentiation between certified OEM-grade and aftermarket fluid pipe specifications. This logistics chokepoint concentrates supply-side pricing power among resin producers in Japan and Germany who command premium positioning through REACH-compliant material traceability.
Pricing Analysis
EPA Tier 3 evaporative emissions standards dictate the pricing tier structure across the Automobile Fluid Pipe Products Market, separating fluoropolymer-barrier fuel lines from commodity rubber constructions through 15-year permeation certification requirements. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with OEM direct contracts capturing margin pools unavailable to aftermarket channels. Cost compression in the standard tier is intensifying because aluminum price volatility feeds through multi-year supply agreements. Fleet procurement officers at commercial vehicle operators show the highest price sensitivity, while German premium OEM platform engineers prioritize performance compliance over unit cost.
Supply Chain Analysis
Export control regimes restricting fluoropolymer resin technology transfers limit supply diversification for barrier-layer materials, concentrating upstream chemical production in Japan, Germany, and the United States. Raw material flows draw from London Metal Exchange aluminum contracts, ethylene tetrafluoroethylene resin supply, and coated steel coil from South Korean mills. Single-source vulnerability runs through fluoropolymer resin qualification timelines that extend 18-24 months for OEM approval. Distribution runs through Tier 1 system integrators who bundle fluid pipes into thermal management modules for final assembly delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation across North American heavy-duty manufacturing has shifted buyer power toward volume-commitment leverage, fragmenting supplier counts and elevating annual contract thresholds.
For Market Incumbents: Entrench platform-level relationships through captive production capacity in Thailand's Eastern Economic Corridor and backward integration into fluoropolymer resin supply. Battery thermal management circuit complexity threatens margin pools for legacy fuel line specialists; counter by accelerating R-1234yf refrigerant compatibility certification ahead of EU F-Gas phasedown deadlines.
For New Entrants and Emerging Players: India's Automotive PLI scheme corridors offer underpenetrated manufacturing capacity for component-level localization serving domestic OEM expansion. Battery electric vehicle coolant piping modules present the most penetrable segment given qualification timeline compression and incumbent bandwidth constraints. Pursue direct OEM Tier 1 engineering engagement bypassing traditional system integrator relationships to capture margin previously absorbed by intermediate suppliers.
For Investors and Strategic Acquirers: Regional metal-forming specialists with aluminum extrusion expertise and established OEM captive relationships represent acquisition targets with defensive positioning against polymer composite substitution. Long-term viability across the analysis window hinges on thermal management architecture convergence in electrified platforms. Watch for inflection signals in heat pump refrigerant-coolant circuit integration mandates from German and Japanese OEMs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin Supply | Captures margin from concentrated Japanese and German chemical suppliers while securing qualification continuity. |
| Geographic Manufacturing Footprint Expansion | Eastern Economic Corridor and Indian PLI zones reduce tariff exposure and logistics costs for Southeast Asian OEM programs. |
| Refrigerant Circuit Integration Investment | R-1234yf and R-744 compatibility positions suppliers for EU F-Gas Regulation phasedown compliance. |
| Direct OEM Tier 1 Qualification | Bypassing system integrators opens margin capture previously absorbed by intermediate thermal management module suppliers. |
| Battery Thermal Management Platform Standardization | Multi-circuit coolant architectures for electric vehicles expand addressable component value per vehicle. |
Research Methodology
A standing panel of OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distribution managers, and polymer composite processing specialists provided ongoing calibration against secondary validation from vehicle production databases, IHS Markit registration data, EPA certification filings, and EU REACH substance registration records. Bottom-up unit volume modeling across propulsion architectures triangulated with top-down market sizing from automotive trade association capacity reports.
Scenario-bracketing framed demand projections across the modeling period, modeling segmentation dimensions including propulsion architecture, material category, application system, and regional production cluster. CAGRs derived from fitted growth curves applied to platform-level content-per-vehicle assumptions, with battery thermal management piping intensity and refrigerant circuit complexity serving as primary forecast inputs.
Practitioners should monitor aluminum price volatility, fluoropolymer resin supply disruption events, and OEM platform acceleration cycle compression for early signals requiring forecast reassessment. Material shifts in battery thermal management architecture standards or EU F-Gas Regulation enforcement timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
India Automotive Airfilters Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Automotive Metal Stamping Market
Automotive Components
Automotive Bearing Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
UAE Automotive Composites Market
Automotive Components
Middle East and Africa Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Headliners Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Automotive Resonator Market
Automotive Components
Iran Automotive Lubricants Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Asia Pacific Automotive Actuators Market