
 Electric Vehicle Fluid Lubricants Market | 2026-2036
Electric Vehicle Fluid Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Fluid Lubricants Market Foresight
REACH compliance in Europe is consolidating the cost-of-entry calculus for EV fluid lubricant manufacturers, forcing smaller blenders to invest in biodegradable formulation R&D or exit the market. ExxonMobil Corporation leverages its integrated base oil supply chain to sustain cost advantages across synthetic transmission fluid grades. Shell plc anchors its position through direct OEM partnerships with European and Asian automakers. FUCHS specializes in high-voltage dielectric coolants, differentiating its portfolio from commodity lubricant suppliers.
Electric vehicle fluid lubricants encompass thermally stable, electrically insulating, and low-conductivity formulations engineered for battery thermal management, e-motor cooling, and electrified drivetrain friction reduction, typically operating within dielectric strength thresholds above 30 kV and viscosity indices optimized for temperatures from minus forty to one hundred fifty degrees Celsius. These fluids prevent electrical shorting in high-voltage architectures while transferring heat from battery packs and power electronics to maintain thermal equilibrium. Transmission fluids and coolants command the deepest margin pools as OEMs specify proprietary thermal management chemistries tied to warranty coverage. Synthetic formulations are displacing mineral-based alternatives in passenger vehicle applications where extended drain intervals and thermal stability justify premium positioning. Aftermarket providers occupy a structurally weaker position as OEM-controlled service networks increasingly gate fluid specifications.
The EPA in the United States, ECHA under REACH in Europe, and China's MEE collectively shape product standards through chemical registration requirements, biodegradability mandates, and carbon intensity disclosures that determine market access. These frameworks force reformulation cycles that favor suppliers with in-house testing and regulatory affairs capabilities. Stakeholders must monitor how OEM warranty terms evolve to restrict aftermarket fluid compatibility, as this shift will determine whether independent lubricant brands retain channel access or face systematic displacement.
Market Dynamics
OEM-controlled thermal management specifications are consolidating procurement authority away from aftermarket channels, as warranty coverage increasingly mandates proprietary fluid chemistries that lock fleet operators into captive supply arrangements.
Growth Catalysts
- Dual carbon goals in China:MEE mandates on carbon intensity disclosures accelerate reformulation requirements, forcing suppliers to develop low-carbon base stocks and biodegradable additives.
- Electrified commercial transport:Fleet operators expanding electrified bus and truck deployments generate concentrated demand for high-volume transmission fluid and coolant contracts.
- Dielectric coolant innovation:Advancements in electrically insulating formulations with dielectric strength above 30 kV enable safer high-voltage battery architectures in premium passenger segments.
Market Restraints
- Synthetic base oil cost volatility:PAO and ester feedstock prices fluctuate with petrochemical crack spreads, compressing blender margins on premium formulations.
- REACH compliance burden:ECHA registration requirements and biodegradability testing costs create fixed cost barriers that disadvantage smaller European blenders.
- Mineral oil substitution ceiling:Cost-sensitive commercial vehicle segments in emerging markets retain mineral-based fluids where drain intervals and thermal loads remain moderate.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic manufacturing incentives attract fluid suppliers to localize blending capacity for the expanding two-wheeler and three-wheeler electrification pipeline.
- E-motor and power electronics convergence:Integrated thermal management systems combining battery, motor, and inverter cooling create demand for multi-functional dielectric fluids.
- Direct OEM service network partnerships:Exclusive supply agreements with manufacturer-controlled maintenance channels bypass traditional distributor relationships.
Industry Challenges
- Formulation chemist scarcity:Expertise in high-voltage dielectric engineering and thermal stability modeling concentrates among a limited pool of specialists with battery-electric system experience.
- OEM specification fragmentation:Proprietary thermal management chemistries tied to warranty terms create SKU proliferation and testing duplication across automaker platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Fluid Lubricants Market |
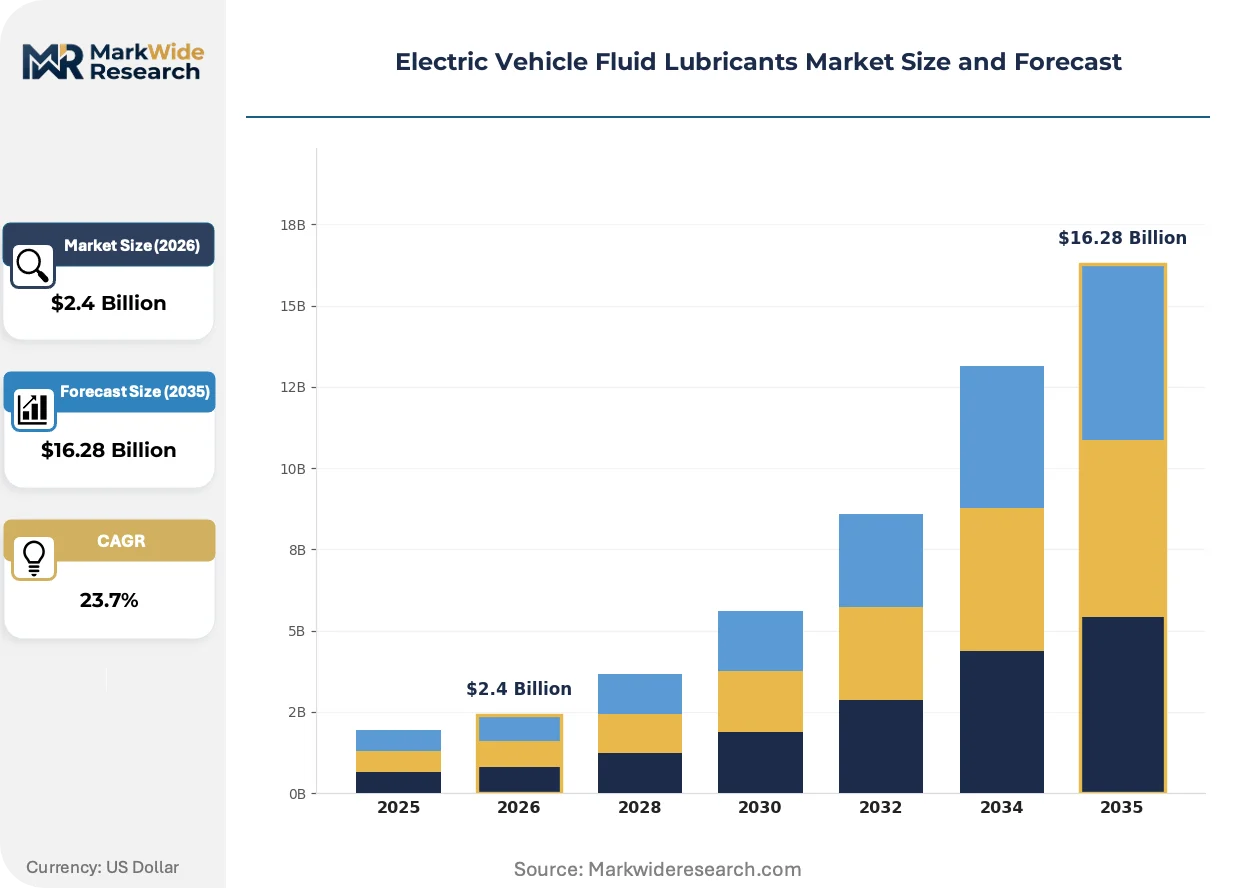
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $16.28 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
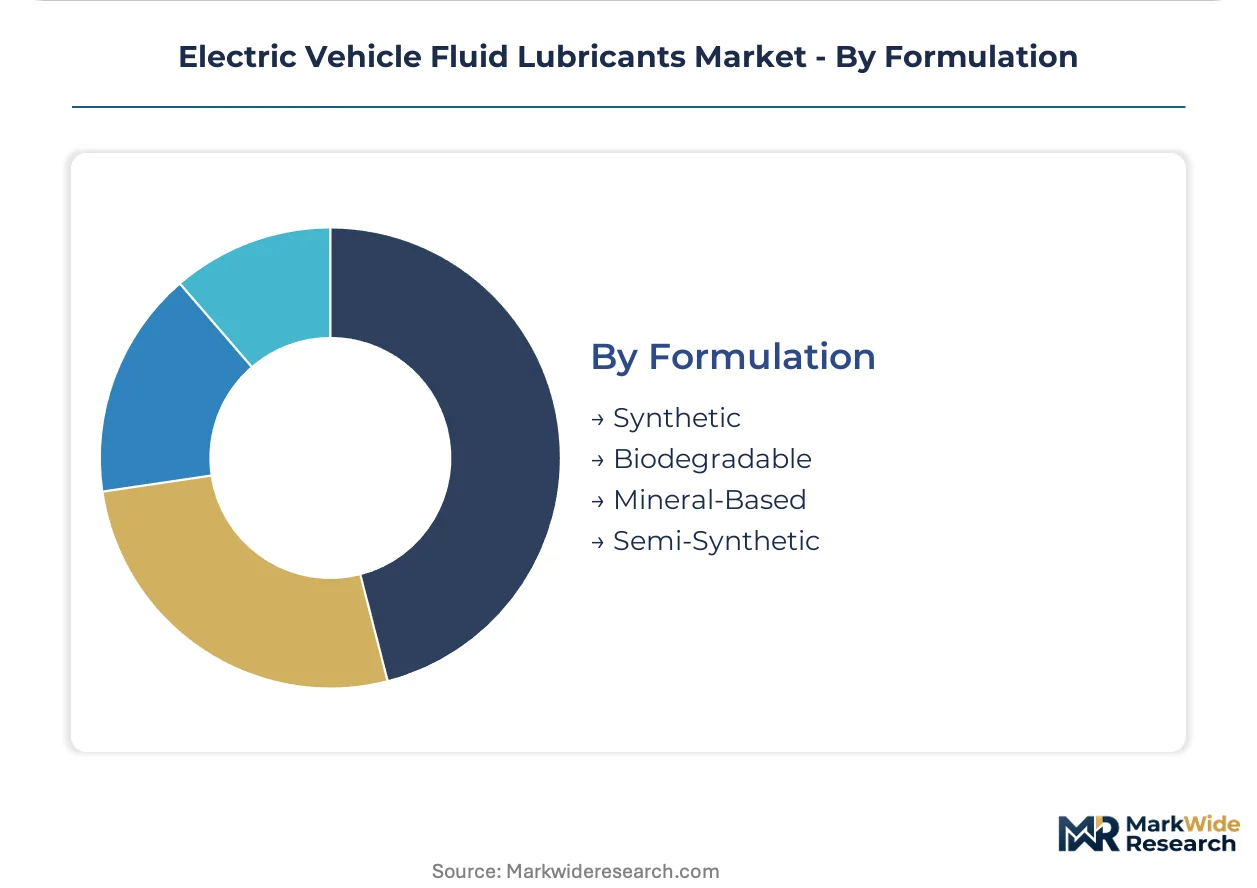
| Segmentation | Product Type: Transmission Fluids, Brake Fluids, Coolants, Hydraulic Fluids End User: OEMs, Fleet Operators, Aftermarket Providers, Maintenance Shops Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Light-Duty Trucks Formulation: Synthetic, Biodegradable, Mineral-Based, Semi-Synthetic |
| Companies Covered | ExxonMobil Corporation, Shell plc, BP plc, TotalEnergies, FUCHS, ENEOS Corporation, Petroliam Nasional Berhad (PETRONAS), Repsol, Valvoline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Fluid Lubricants Market Shifts & Advancements
Fluid formulation architectures are pivoting from commodity lubrication toward engineered thermal management solutions, as electrified powertrains impose dielectric, thermal, and material compatibility requirements absent from internal combustion applications.
Multi-functional dielectric coolants integrating battery thermal management with e-motor and power electronics cooling are decentralizing the traditional separation between transmission fluids and dedicated battery coolants. Commercial vehicle OEMs in Germany and China adopt these unified formulations fastest, driven by packaging constraints in heavy-duty electric axles. This convergence is decentralizing procurement decisions from discrete fluid categories toward system-level thermal management contracts.
REACH in Europe now mandates comprehensive biodegradability testing and carbon footprint disclosure for lubricant chemistries placed on the EU market. The regulation forces reformulation cycles that favor suppliers with in-house regulatory affairs and testing infrastructure. Synthetic transmission fluid grades face the steepest compliance costs, accelerating consolidation among European blenders unable to absorb fixed certification expenses.
Fleet procurement of EV fluids is consolidating around total-cost-of-ownership frameworks that weight extended drain intervals and thermal stability against unit price. Logistics operators with centralized maintenance operations in Germany and the United States negotiate direct supply agreements that displace traditional distributor networks. This shift is most visible in electrified urban bus deployments, where uptime guarantees and warranty compliance override price minimization in supplier selection.
Electric Vehicle Fluid Lubricants Market Segmentation
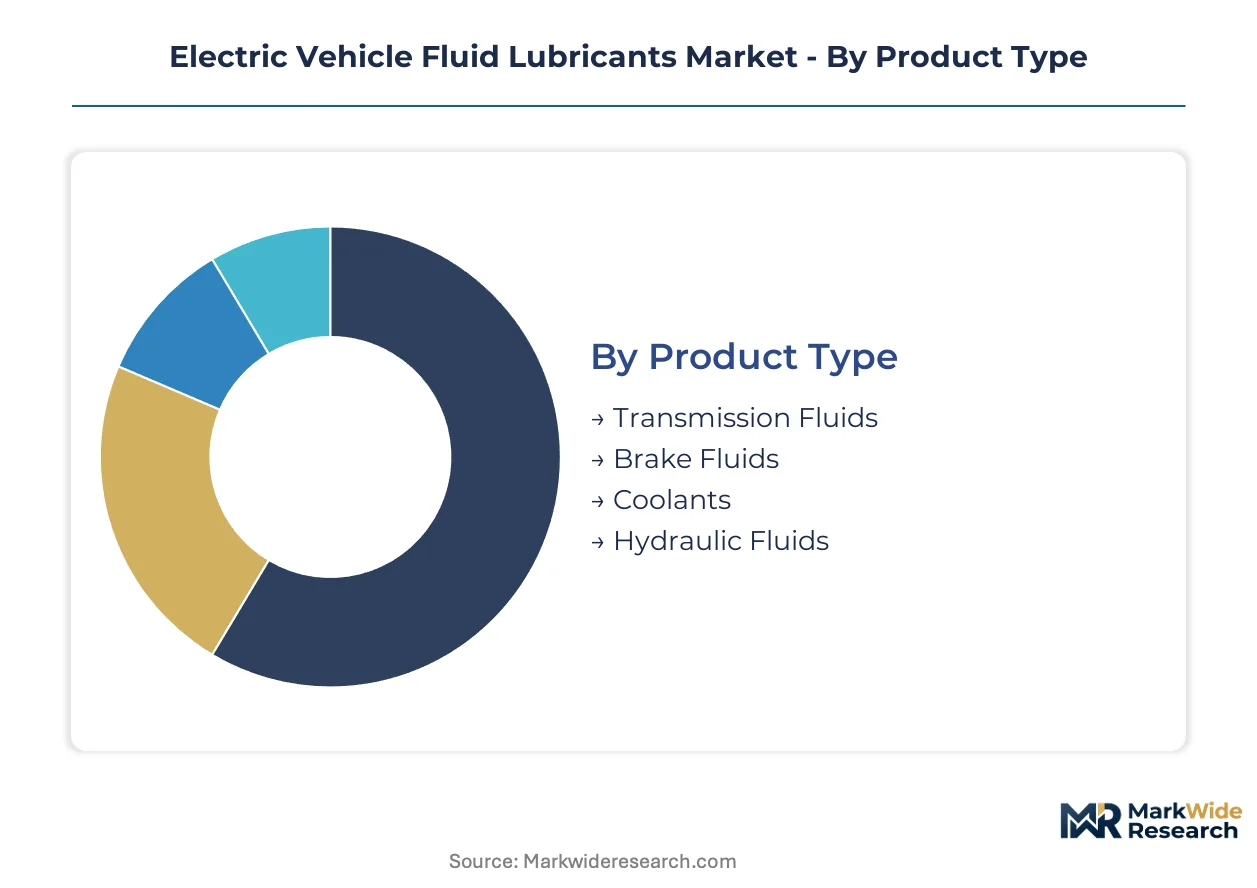
Fluid specifications diverge sharply across electrified powertrain architectures, with dielectric requirements and thermal stability thresholds determining formulation investments. Procurement patterns fragment between OEM-controlled warranty channels and cost-driven aftermarket alternatives.
Product Type:
Dielectric strength and thermal conductivity specifications differentiate fluid categories for battery-electric systems.
- Transmission Fluids:Synthetic formulations engineered for electrified drivetrains operate across minus forty to one hundred fifty degrees Celsius with extended drain intervals. Fleet operators in Germany negotiate direct supply agreements for high-volume electrified bus and truck deployments, prioritizing uptime guarantees over unit economics.
- Coolants:Multi-functional dielectric fluids integrate battery thermal management with e-motor and power electronics cooling, requiring dielectric strength above thirty kilovolts. China's dual carbon goals under MEE mandates accelerate low-carbon base stock development for these formulations.
- Brake Fluids:Low-conductivity specifications prevent electrical interference in brake-by-wire architectures common to premium passenger platforms.
- Hydraulic Fluids:Thermally stable formulations serve steering and suspension actuators in electrified commercial axles with moderate thermal loads.
Transmission fluids lead on scale; coolants lead on momentum.
End User:
Channel control over fluid specifications determines margin capture and formulation access.
- OEMs:Proprietary thermal management chemistries tied to warranty coverage lock fleet operators into captive supply arrangements. Direct partnerships with European and Asian automakers anchor supplier positions.
- Fleet Operators:Centralized maintenance operations in Germany and the United States negotiate total-cost-of-ownership frameworks weighting thermal stability against price. Electrified commercial transport expansion drives concentrated demand for high-volume contracts.
- Aftermarket Providers:Structurally weaker position as OEM-controlled service networks increasingly gate fluid specifications and restrict compatibility.
- Maintenance Shops:Dependent on distributor relationships facing displacement from direct OEM-fleet supply agreements.
OEMs dominate procurement authority; fleet operators are expanding most quickly.
Application:
Thermal load profiles and duty cycles dictate formulation sophistication across vehicle categories.
- Passenger Vehicles:Synthetic formulations displace mineral-based alternatives where extended drain intervals and thermal stability justify premium positioning in high-voltage architectures.
- Commercial Vehicles:Heavy-duty electric axles in Germany and China adopt unified thermal management formulations fastest, driven by packaging constraints and uptime requirements.
- Two-Wheelers:Cost-sensitive segments in India's PLI scheme pipeline retain mineral-based fluids where thermal loads remain moderate.
- Light-Duty Trucks:Intermediate thermal profiles balance synthetic performance against total-cost thresholds for urban delivery fleets.
Passenger vehicles anchor volume concentration; commercial vehicles show steepest expansion trajectory.
Formulation:
Base stock chemistry determines regulatory compliance positioning and thermal performance ceilings.
- Synthetic:PAO and ester base stocks deliver viscosity indices optimized for extreme temperature ranges. REACH compliance costs and petrochemical crack spread volatility compress blender margins on premium grades.
- Biodegradable:ECHA mandates under REACH force reformulation cycles favoring suppliers with in-house testing infrastructure for EU market access.
- Mineral-Based:Cost-sensitive commercial segments in emerging markets retain these fluids where drain intervals and thermal loads remain moderate.
- Semi-Synthetic:Intermediate positioning bridges performance requirements and cost constraints for mid-tier fleet applications.
Synthetic formulations dominate technology investment; biodegradable grades are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridor pioneered synthetic transmission fluid specifications for electrified drivetrains, establishing technical benchmarks that now propagate through supply chains worldwide.
Germany
Fleet operators in North Rhine-Westphalia negotiate direct supply agreements for electrified bus deployments, prioritizing uptime guarantees over unit economics. KBA vehicle regulations mandate dielectric fluid certification for high-voltage architectures above 60V. Stuttgart's automotive cluster hosts OEM fluid specification laboratories that set regional procurement standards for synthetic formulations.
China
Domestic EV manufacturers in the Yangtze River Delta drive concentrated demand for multi-functional dielectric coolants integrating battery and e-motor thermal management. MEE mandates on carbon intensity disclosures accelerate low-carbon base stock development timelines. Shenzhen's electrified commercial vehicle corridor adopts unified thermal management formulations fastest among heavy-duty electric axle deployments.
United States
Centralized fleet maintenance operations in Michigan and California weight total-cost-of-ownership frameworks favoring extended drain intervals. EPA chemical registration requirements for lubricant additives create compliance barriers favoring suppliers with in-house testing infrastructure. Detroit's automotive engineering cluster shapes OEM fluid specifications that propagate through North American warranty networks.
India
Two-wheeler and three-wheeler electrification under the PLI scheme generates demand for cost-optimized synthetic formulations. BIS standards for automotive fluids are tightening dielectric performance thresholds for high-voltage two-wheeler architectures. Tamil Nadu's automotive manufacturing belt attracts fluid suppliers localizing blending capacity for export-oriented EV component production.
Japan
Premium passenger vehicle OEMs in Aichi Prefecture specify proprietary thermal management chemistries with dielectric strength above 30 kV. METI energy efficiency guidelines incentivize fluid formulations that reduce thermal management system energy consumption. Nagoya's automotive technology corridor concentrates dielectric coolant R&D for next-generation solid-state battery thermal architectures.
Electric Vehicle Fluid Lubricants Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical majors with captive base oil supply chains. Three to five global suppliers anchor procurement relationships with European and Asian OEMs through direct partnership frameworks, while mid-tier blenders face displacement from REACH compliance burdens. Two strategic archetypes dominate: vertically integrated energy majors leveraging upstream feedstock control, and specialty chemical houses concentrating high-voltage dielectric expertise. Capacity expansion in low-carbon base stocks and strategic partnerships for integrated thermal management systems represent the dominant competitive moves reshaping supplier positioning.
Among integrated energy majors, ExxonMobil Corporation and Shell plc occupy positions exemplifying the scale-driven archetype through synthetic base oil supply chain control. FUCHS represents the specialization archetype, anchoring the high-voltage dielectric coolant segment distinct from commodity lubricant suppliers. These three companies illustrate how supplier positioning fragments between upstream-integrated volume players and formulation specialists addressing proprietary OEM thermal management specifications.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| BP plc |
| TotalEnergies |
| FUCHS |
| ENEOS Corporation |
| Petroliam Nasional Berhad (PETRONAS) |
| Repsol |
| Valvoline |
| Others |
Supply & Pricing Matrix
Multi-functional dielectric coolant formulation architectures simultaneously compress per-unit manufacturing costs and consolidate procurement authority among integrated petrochemical majors with captive base oil supply chains. China's MEE carbon intensity mandates and REACH biodegradability requirements in Europe accelerate reformulation investments that favor suppliers with in-house testing infrastructure over smaller blenders.
Pricing Analysis
Bundled thermal management system contracts dominate fleet procurement, while unbundled aftermarket fluid sales face systematic displacement. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral-based levels reflects dielectric certification thresholds and OEM warranty compliance tiers. Cost compression in synthetic base stocks intensifies because PAO and ester feedstock prices track volatile petrochemical crack spreads. Fleet operators in Germany exhibit least price sensitivity due to uptime guarantees, while India's cost-optimized two-wheeler segment shows highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for used dielectric coolants remain underdeveloped, constraining circular economy participation and base stock recovery economics. Manufacturing concentrates in Germany, China, and the United States, with formulation blending anchored in Stuttgart's automotive cluster, the Yangtze River Delta, and Michigan's engineering corridor. Feedstock supply draws from PAO and ester production in Belgium, Singapore, and the US Gulf Coast. Single-source vulnerability in high-purity base oil refining creates structural exposure. Distribution runs through direct OEM-fleet agreements that displace traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through synthetic formulation premiumization and extended drain interval value propositions that reduce total cost of ownership for fleet operators.
For Market Incumbents: Anchor procurement relationships through exclusive direct OEM service network partnerships that bypass distributor channels. Deepen backward integration into low-carbon base stock production to defend against REACH compliance cost inflation. Invest in high-voltage dielectric R&D capabilities to offset formulation chemist scarcity threatening technical differentiation.
For New Entrants and Emerging Players: Solid-state battery thermal architecture compatibility offers a technology-first wedge against established coolant suppliers. Target India's PLI scheme pipeline for two-wheeler and three-wheeler electrification as the most penetrable geography with moderate regulatory barriers. Pursue joint development agreements with domestic OEMs seeking localized blending capacity.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier European blenders facing REACH compliance displacement. Long-term viability favors suppliers with integrated thermal management system capabilities spanning battery, e-motor, and power electronics cooling. Monitor OEM warranty term evolution restricting aftermarket fluid compatibility as the decisive inflection signal for channel access consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Low-Carbon Base Stock Capacity Expansion | MEE carbon intensity mandates in China accelerate reformulation timelines for dielectric coolant suppliers. |
| Direct OEM Partnership Structuring | Exclusive supply agreements with European automakers lock fleet operators into captive procurement arrangements. |
| Integrated Thermal Management System Development | Unified battery-motor-inverter cooling contracts in Germany consolidate procurement authority away from discrete fluid categories. |
| Biodegradable Formulation Certification Investment | ECHA REACH requirements create fixed-cost barriers that advantage suppliers with in-house testing infrastructure. |
| Geographic Blending Capacity Localization | India's PLI scheme attracts fluid suppliers to Tamil Nadu for export-oriented EV component production. |
Research Methodology
Direct dialogue with OEM thermal management engineers, fleet procurement directors, lubricant formulation chemists, and regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from EPA chemical registration databases, ECHA REACH substance inventories, MEE carbon disclosure filings, and automotive production statistics. Bottom-up and top-down triangulation cross-checked volume estimates against base oil trade flows and OEM fluid specification announcements.
Bottom-up modeling anchored projections in segment-level content-per-vehicle assumptions across passenger, commercial, and two-wheeler electrification platforms. Top-down constraints incorporated synthetic base oil capacity expansion timelines and regulatory compliance cost trajectories. CAGRs derived from fitted growth curves reflecting fleet electrification penetration rates and thermal management system convergence trends. Modeled dimensions spanned fluid category, vehicle architecture, formulation chemistry, and regional production cluster.
The model holds under stable petrochemical feedstock pricing and continued OEM warranty expansion; deviation in synthetic base oil supply disruptions or regulatory acceleration would shift volume and value trajectories. Practitioners should monitor OEM service network exclusivity announcements and REACH substance restriction proposals for early signals of channel access restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
Automotive Differential Market
Automotive Components
Automotive Metal Stamping Components Market
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Automotive Mufflers Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Argentina Automotive Electric Actuators Market
Automotive Components
Global Automotive Sun Visor Market
Automotive Components
Automotive Metal Stamping Market