
 Europe Pedestrian Detection Systems Market | 2026-2036
Europe Pedestrian Detection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pedestrian Detection Systems Market Foresight
German Tier 1 sensor suppliers is repositioning production capacity toward fused LiDAR-camera architectures for Euro NCAP compliance. Robert Bosch GmbH leverages its Stuttgart engineering base to sustain dominance in radar-based pedestrian detection modules. Continental AG anchors supply relationships with premium OEMs through integrated sensor-to-brake control systems. ZF Friedrichshafen AG competes on thermal imaging fusion, differentiating its portfolio for low-visibility urban scenarios.
Europe Pedestrian Detection Systems combine multispectral sensors, edge-computing processors, and machine-vision algorithms to identify human movement vectors and trigger autonomous braking or alert protocols within milliseconds. The systems primarily serve collision avoidance in dense urban traffic and compliance with mandatory vehicle safety frameworks. Camera-based technology leads installation volumes due to cost scalability, while LiDAR occupies the premium tier where precision range-mapping commands higher margins. Infrastructure-based deployment in smart city pilots across Dutch and Spanish municipalities represents the fastest-growing installation type, though onboard systems still capture the majority of value pools.
The European Union's General Safety Regulation, Euro NCAP testing protocols, and the EU AI Act collectively mandate performance benchmarks for automated detection systems and algorithmic transparency in safety-critical applications. EMA and national type-approval authorities shape market access through homologation requirements that favor pre-certified sensor platforms. Stakeholders must monitor how the EU AI Act's risk-classification rules for autonomous decision-making will reshape supplier liability and software validation costs.
Market Dynamics
The EU General Safety Regulation is compressing adoption timelines for pedestrian detection systems, forcing Tier 1 suppliers to accelerate fused sensor architectures ahead of original equipment refresh cycles.
Growth Catalysts
- Euro NCAP Protocols:The 2026 testing framework mandates vulnerable road user protection scores, compelling OEMs to spec multi-sensor suites as standard fitment rather than option packages.
- German Manufacturing Corridor:Stuttgart-to-Munich production clusters concentrate engineering talent and validation facilities, reducing supplier development cycles for camera-LiDAR fusion modules.
- Urban Traffic Density:Paris, London, and Amsterdam congestion patterns elevate collision-avoidance priority in fleet procurement specifications for delivery vehicles and municipal transport.
Market Restraints
- LiDAR Component Concentration:Solid-state emitter supply chains cluster with Asian photonics foundries, exposing European integrators to input volatility and customs friction.
- Software Validation Burden:The EU AI Act's high-risk system classification imposes documentation and audit requirements that extend homologation timelines by 8-14 months for algorithm updates.
- Camera Performance Limits:Adverse weather degradation in Nordic and Alpine operating conditions forces redundant sensor layering, inflating bill-of-materials costs beyond mass-market price elasticity.
Strategic Opportunities
- Smart City Infrastructure:Dutch and Spanish municipality pilots are deploying roadside LiDAR-to-vehicle communication nodes, creating recurring service revenue streams beyond hardware supply.
- Aftermarket Retrofit Channel:France's mandatory technical inspection regime is creating compliance-driven demand for dealer-installed detection systems in vehicles registered before 2022.
- Thermal Imaging Convergence:Low-light pedestrian identification through far-infrared fusion with visible-spectrum cameras opens premium positioning for night-driving safety packages.
Industry Challenges
- Edge-AI Talent Scarcity:Embedded machine-learning optimization for millisecond inference latency requires specialized firmware engineers, with Stuttgart and Munich employers competing for limited candidate pools.
- Homologation Fragmentation:KBA type-approval in Germany, UTAC in France, and VCA in the United Kingdom maintain divergent test protocols, multiplying certification costs for pan-European product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pedestrian Detection Systems Market |
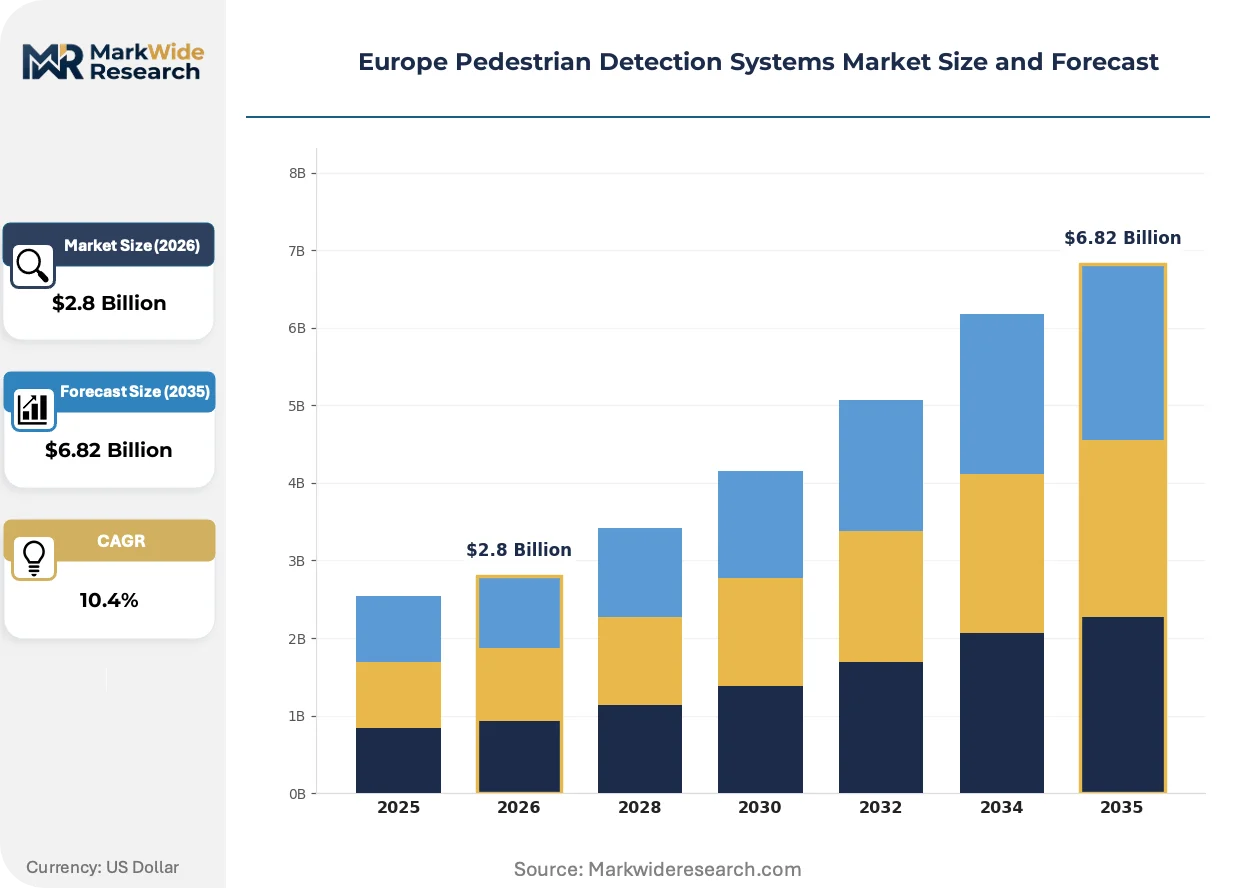
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.82 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Radar, Camera-Based, Ultrasonic Application: Automotive Safety, Smart Cities, Retail Surveillance, Transportation End User: OEMs, Fleet Operators, Municipalities, Security Firms Installation Type: Onboard Systems, Infrastructure-Based, Integrated Solutions, Standalone Units |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Valeo, Aptiv, Autoliv, Denso Corporation, Mobileye, Magna International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pedestrian Detection Systems Market Shifts & Advancements
Sensor fusion architectures are displacing single-modality systems as the baseline specification, with software-defined detection pipelines enabling over-the-air performance updates throughout vehicle lifecycles.
Neural network-based detection algorithms are converging with raw LiDAR point cloud processing at the edge, eliminating latency from central vehicle bus architectures. Premium OEMs in Germany and the United Kingdom are adopting this stack for 2027 model year platforms. The compression of perception pipeline tiers is forcing legacy Tier 2 chip suppliers to reposition toward software licensing models.
The EU AI Act's risk-classification framework is mandating algorithmic explainability documentation for autonomous emergency braking decisions. EMA and national type-approval authorities are incorporating these requirements into homologation checklists. Suppliers serving the French and Italian markets are prioritizing interpretable model architectures over black-box neural approaches to accelerate certification.
Fleet operators in urban logistics are unbundling detection system procurement from full-vehicle purchases, sourcing retrofit packages through certified installer networks. This channel shift bypasses traditional OEM captive supply arrangements. The Netherlands and Belgium show the highest penetration of this procurement model among last-mile delivery contractors.
Europe Pedestrian Detection Systems Market Segmentation
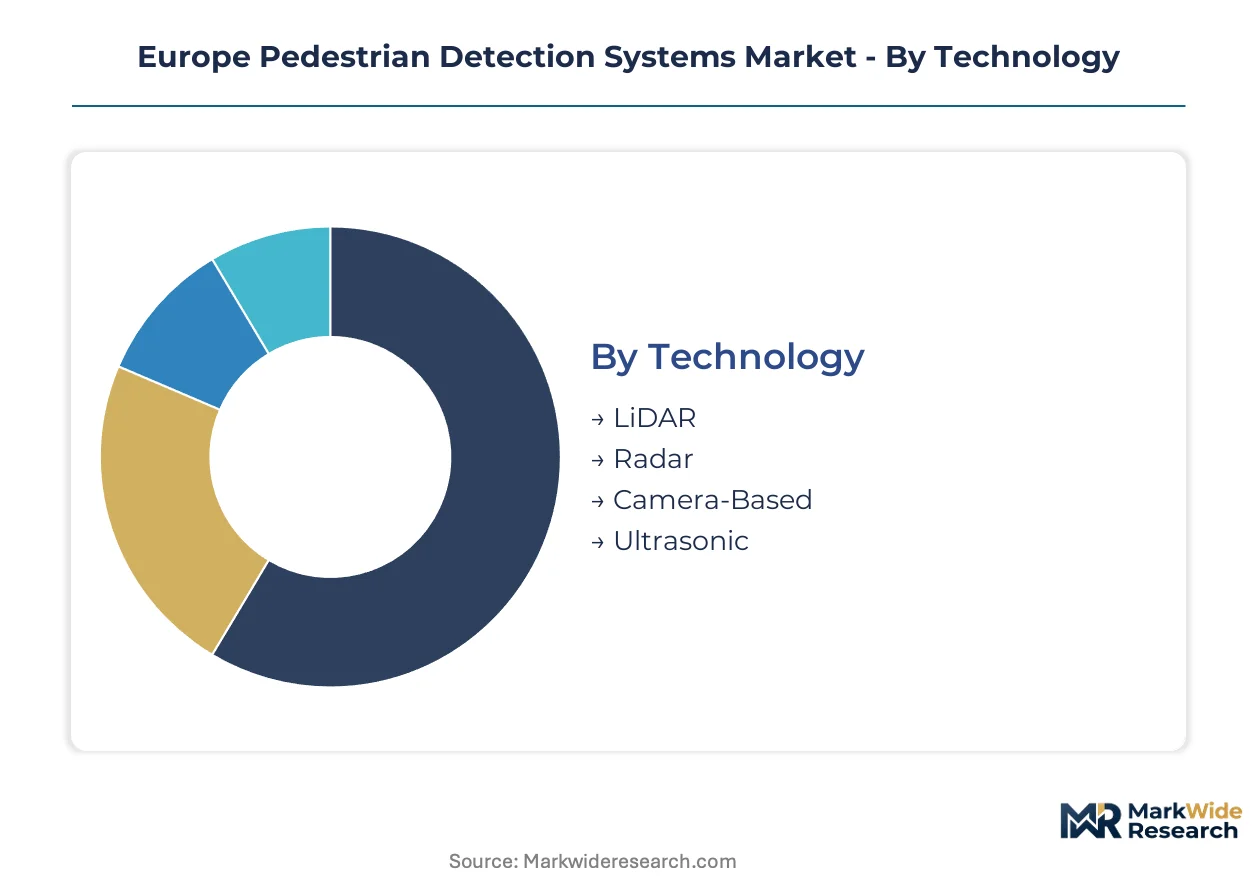
Segmentation in the Europe Pedestrian Detection Systems Market reveals how regulatory pressure and application diversity fragment procurement patterns across sensor technologies and deployment models. Tier 1 suppliers must navigate divergent homologation pathways while serving distinct customer economics from mass-market automotive to municipal infrastructure.
Technology:
KBA type-approval in Germany and UTAC certification in France impose differentiated validation burdens on each sensor modality, with LiDAR facing the most stringent electromagnetic compatibility testing.
- LiDAR:Solid-state emitters generate dense point clouds for centimeter-precision range mapping in urban canyons. German premium OEMs concentrate procurement here for autonomous emergency braking compliance under Euro NCAP protocols, though Asian photonics foundry concentration creates supply vulnerability.
- Camera-Based:Visible-spectrum and near-infrared sensors dominate installation volumes through cost scalability and mature image-processing pipelines. France's automotive corridor sources heavily here for mid-market vehicle platforms where price elasticity limits multi-sensor layering.
- Radar:Frequency-modulated continuous-wave modules operate reliably through Nordic precipitation conditions that degrade optical sensors. Bosch anchors production in Stuttgart for radar-based pedestrian detection serving Alpine fleet operators.
- Ultrasonic:Short-range proximity detection supplements primary sensors in low-speed parking and maneuvering scenarios. Limited to backup and close-quarters applications due to range constraints.
Leading the category by volume: Camera-Based. Growing fastest: LiDAR.
Application:
Cost tier stratification separates premium safety mandates from discretionary municipal spending, with automotive applications commanding hardware margins threefold above retail surveillance deployments.
- Automotive Safety:Collision-avoidance systems integrate with vehicle brake-by-wire architectures for millisecond intervention latency. The EU General Safety Regulation mandates fitment across all new passenger vehicles, compressing adoption timelines.
- Smart Cities:Roadside LiDAR-to-vehicle communication nodes in Dutch and Spanish municipalities generate recurring service revenue beyond hardware supply. Barcelona and Rotterdam pilots validate V2X integration for vulnerable road user protection.
- Retail Surveillance:Storefront-mounted cameras track pedestrian flow patterns for occupancy analytics and loss prevention. GDPR compliance requirements constrain data retention and facial recognition capabilities.
- Transportation:Rail crossings and tramway corridors deploy thermal-camera fusion for nighttime worker detection. Paris and Berlin transit authorities prioritize these installations for union-mandated safety upgrades.
Highest revenue capture: Automotive Safety. Steepest expansion trajectory: Smart Cities.
End User:
Customer type determines procurement channel structure, with OEM captive supply arrangements yielding to fleet operator direct sourcing and municipal tender processes.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz integrate detection systems at vehicle design phase, locking in multi-year sensor supply agreements with Tier 1 integrators.
- Fleet Operators:Last-mile delivery contractors in the Netherlands and Belgium unbundle detection procurement from full-vehicle purchases, sourcing retrofit packages through certified installer networks.
- Municipalities:Dutch province-level governments and Spanish regional authorities deploy infrastructure-based systems through public procurement frameworks emphasizing total cost of ownership.
- Security Firms:Private operators serve retail and commercial property markets with standalone surveillance integration, prioritizing rapid deployment over automotive-grade validation.
Dominant procurement volume: OEMs. Fastest channel shift: Fleet Operators.
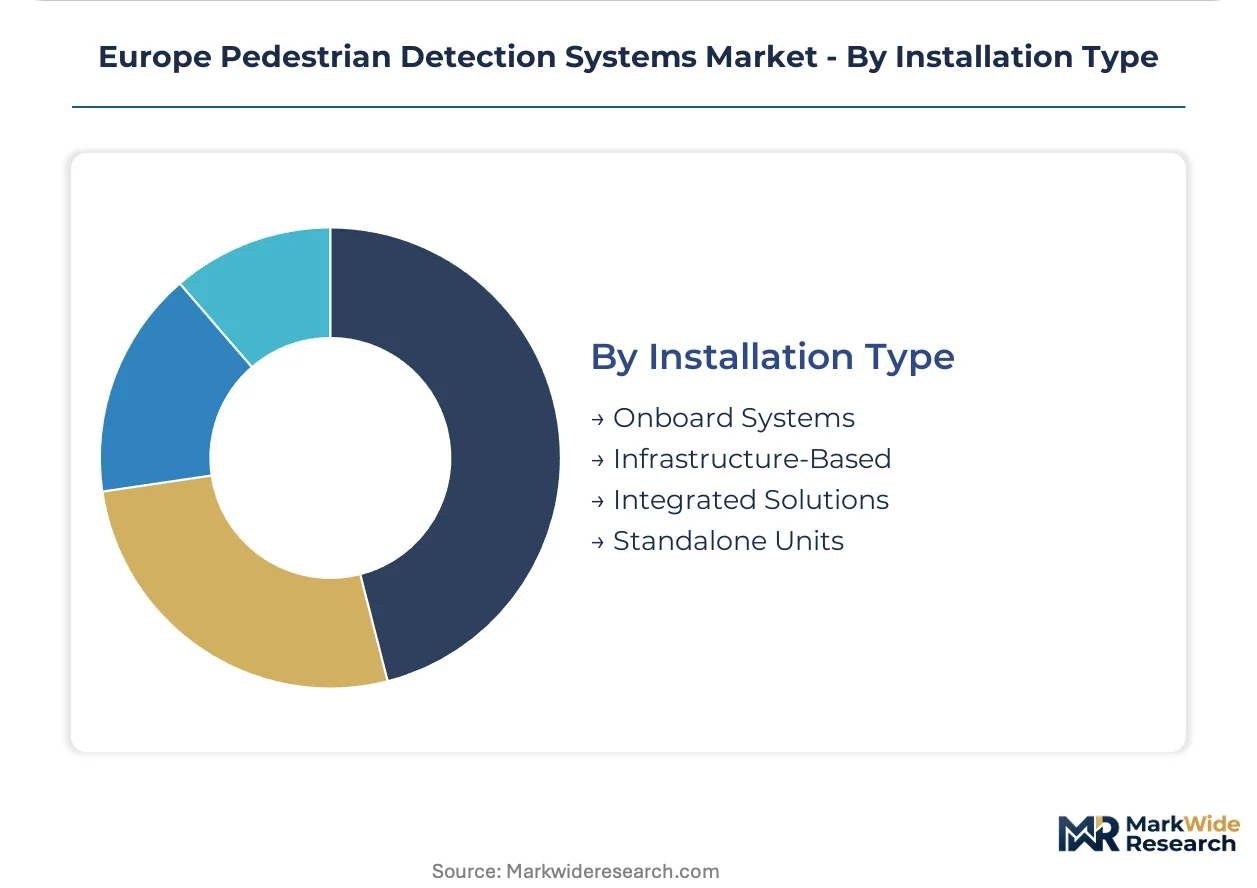
Installation Type:
Supply concentration differs markedly between onboard vehicle integration and roadside deployment, with infrastructure projects demanding civil engineering partnerships absent from automotive supply chains.
- Onboard Systems:Sensor suites embedded within vehicle front grilles and windshields capture the majority of value pools. Stuttgart-to-Munich production clusters concentrate engineering talent for camera-LiDAR fusion module development.
- Infrastructure-Based:Pole-mounted and gantry-deployed sensors communicate with approaching vehicles via C-V2X protocols. Spanish highway authority pilot programs validate this architecture for tunnel and blind-curve coverage.
- Integrated Solutions:Bundled hardware-software-service packages span vehicle and roadside elements, favored by smart city procurements seeking single-vendor accountability.
- Standalone Units:Battery-powered portable detectors serve temporary construction zones and event traffic management. Limited connectivity constrains real-time alerting capabilities.
Value concentration: Onboard Systems. Gaining share fastest: Infrastructure-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's precision optics foundries and photonics engineering clusters supply the sensor substrates that underpin pedestrian detection architectures across the continent.
Germany
Volkswagen Group and BMW procurement specifications drive multi-sensor suite adoption for Euro NCAP compliance. KBA type-approval mandates electromagnetic compatibility validation that extends homologation cycles for LiDAR-camera fusion modules. The Stuttgart-to-Munich corridor concentrates Bosch and Continental engineering facilities for radar-based pedestrian detection R&D.
United Kingdom
London congestion-charge zone expansion elevates collision-avoidance priority in fleet procurement for delivery vehicles. VCA homologation maintains divergent test protocols from continental regulators, multiplying certification costs for pan-European launches. The Midlands automotive cluster hosts Magna International validation facilities serving premium OEM brake-by-wire integration.
France
Paris municipal transport authorities prioritize thermal-camera fusion for tramway nighttime worker detection under union-mandated safety upgrades. UTAC certification imposes differentiated validation burdens on solid-state LiDAR emitters compared to German KBA standards. The Auvergne-Rhône-Alpes region anchors Valeo production capacity for mid-market camera-based detection platforms.
Netherlands
Rotterdam and Amsterdam smart city pilots deploy roadside LiDAR-to-vehicle communication nodes for V2X vulnerable road user protection. Province-level governments procure infrastructure-based systems through public frameworks emphasizing total cost of ownership. Eindhoven's high-tech campus concentrates edge-AI talent for embedded machine-learning optimization.
Spain
Barcelona urban mobility pilots validate C-V2X integration for blind-curve and tunnel coverage where onboard sensors face occlusion limits. The highway authority's infrastructure deployment programs create recurring service revenue streams beyond hardware supply. Basque Country engineering firms specialize in gantry-mounted sensor civil engineering partnerships absent from automotive supply chains.
Europe Pedestrian Detection Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue infrastructure-based service models and aftermarket retrofit channels. The vendor base stratifies across three tiers: Stuttgart-anchored conglomerates with captive OEM relationships, mid-scale specialists in thermal imaging fusion, and municipal-focused integrators serving smart city procurements. Dominant competitive moves include sensor-to-brake control system integration and software-defined detection pipeline licensing.
Within the conglomerate tier, Robert Bosch GmbH and Continental AG exemplify scale-driven positioning through radar and camera-LiDAR fusion architectures. ZF Friedrichshafen AG occupies a differentiated position in thermal imaging convergence for low-visibility applications. Among mid-market specialists, Valeo represents cost-scalable camera platform production serving French and broader European mid-market vehicle segments.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Valeo |
| Aptiv |
| Autoliv |
| Denso Corporation |
| Mobileye |
| Magna International |
| Others |
Supply & Pricing Matrix
Captive in-house production of LiDAR emitter substrates and edge-AI processors anchors Tier 1 suppliers' supply positions while simultaneously hardening their pricing power against Asian component volatility. Bosch, Continental, and ZF leverage Stuttgart-to-Munich engineering clusters to control sensor fusion module costs and reduce exposure to photonics foundry pricing swings.
Pricing Analysis
Extended warranty and over-the-air software update bundling separate premium detection suites from stripped hardware-only configurations. Three-tier pricing structure across premium, standard, and economy levels reflects Euro NCAP certification grade and sensor modality count. Cost compression in camera-based tiers is intensifying because French mid-market OEMs negotiate volume scale discounts for mandatory fitment. Fleet operators in the Netherlands exhibit highest price sensitivity due to unbundled procurement models, while German premium OEMs remain least sensitive when thermal imaging fusion enables night-driving safety positioning.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Volkswagen Group and BMW, while certified installer networks serve fleet retrofit procurement in Belgium and the Netherlands. Solid-state LiDAR emitters draw from Chinese and Taiwanese photonics foundries, with radar substrates sourcing from German and Japanese semiconductor facilities. Single-source vulnerability concentrates in VCSEL emitter supply from Asian foundries, exposing European integrators to customs friction. Distribution runs through Tier 1 system integrators with captive OEM relationships, bypassing independent distributors for automotive safety applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as Tier 1 suppliers pursue backward integration into solid-state emitter manufacturing to secure supply and harden margins against Asian foundry volatility.
For Market Incumbents: Deploy software-defined detection pipeline licensing to lock in recurring revenue across vehicle lifecycles and defend against emerging infrastructure-based service entrants. Deepen captive production of edge-AI processors in Stuttgart engineering clusters to reduce inference latency and accelerate homologation cycles under EU AI Act documentation requirements. For New Entrants and Emerging Players: Capture aftermarket retrofit demand in France's mandatory technical inspection regime for pre-2022 vehicle compliance, where dealer-installed detection systems bypass established OEM supply arrangements. Target roadside LiDAR-to-vehicle communication node deployment in Dutch and Spanish smart city pilots, sourcing through municipal tender processes that favor single-vendor accountability over automotive-grade validation heritage. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to Tier 1 conglomerates seeking thermal imaging fusion capabilities or edge-AI optimization talent. Five-to-ten year viability hinges on algorithmic explainability documentation compliance under EU AI Act risk-classification frameworks. Watch for inflection when KBA and UTAC homologation protocols converge, reducing certification cost multiples for pan-European product launches.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Brake Control Integration | Continental AG's integrated architectures reduce intervention latency for Euro NCAP compliance scores. |
| Software-Defined Detection Pipeline Licensing | Over-the-air update revenue streams extend monetization across vehicle lifecycles beyond hardware margins. |
| Thermal Imaging Fusion Development | ZF's far-infrared convergence targets low-visibility urban scenarios in Nordic and Alpine operating conditions. |
| Roadside Infrastructure Partnership | Rotterdam and Barcelona pilots validate C-V2X communication nodes for recurring service revenue capture. |
| Edge-AI Talent Acquisition | Eindhoven campus recruitment accelerates embedded machine-learning optimization for millisecond inference targets. |
Research Methodology
EU regulatory filings, Euro NCAP test protocol documentation, and KBA type-approval records formed the secondary backbone, cross-referenced against Tier 1 supplier procurement disclosures and municipal tender databases. Primary interviews with OEM platform engineers, Tier 1 sensor integration leads, fleet procurement managers, and smart city infrastructure planners validated demand assumptions and technology adoption timelines. Bottom-up and top-down triangulation reconciled vehicle production forecasts with sensor content-per-vehicle estimates across the analysis window.
Bottom-up modeling aggregated country-level fitment rates by vehicle class and propulsion architecture, while top-down analysis cross-checked against EU General Safety Regulation mandate implementation schedules. Segmentation dimensions included sensor modality, application type, end-user procurement channel, and installation configuration. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory compression effects, with LiDAR cost decline trajectories and camera image-processor efficiency gains as key automotive-specific inputs.
The model holds under sustained EU regulatory enforcement and stable photonics foundry supply; deviation in tariff regimes or homologation protocol divergence would shift volume and value projections. Forecasts reflect documented assumptions regarding Euro NCAP scoring weight evolution and fleet operator procurement channel maturation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Mexico Airbag Systems Market
Automotive Safety and Security Systems
Automotive Smart Security Device Market
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market
Automotive Safety and Security Systems
Automotive Pedestrian Protection System Market
Automotive Safety and Security Systems
Collision Mitigation Technology Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Automotive ABS and ESC Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Automotive Keyless Entry Access Systems Market