
 Alloys for Automotive Market | 2026-2036
Alloys for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Alloys for Automotive Market Analysis
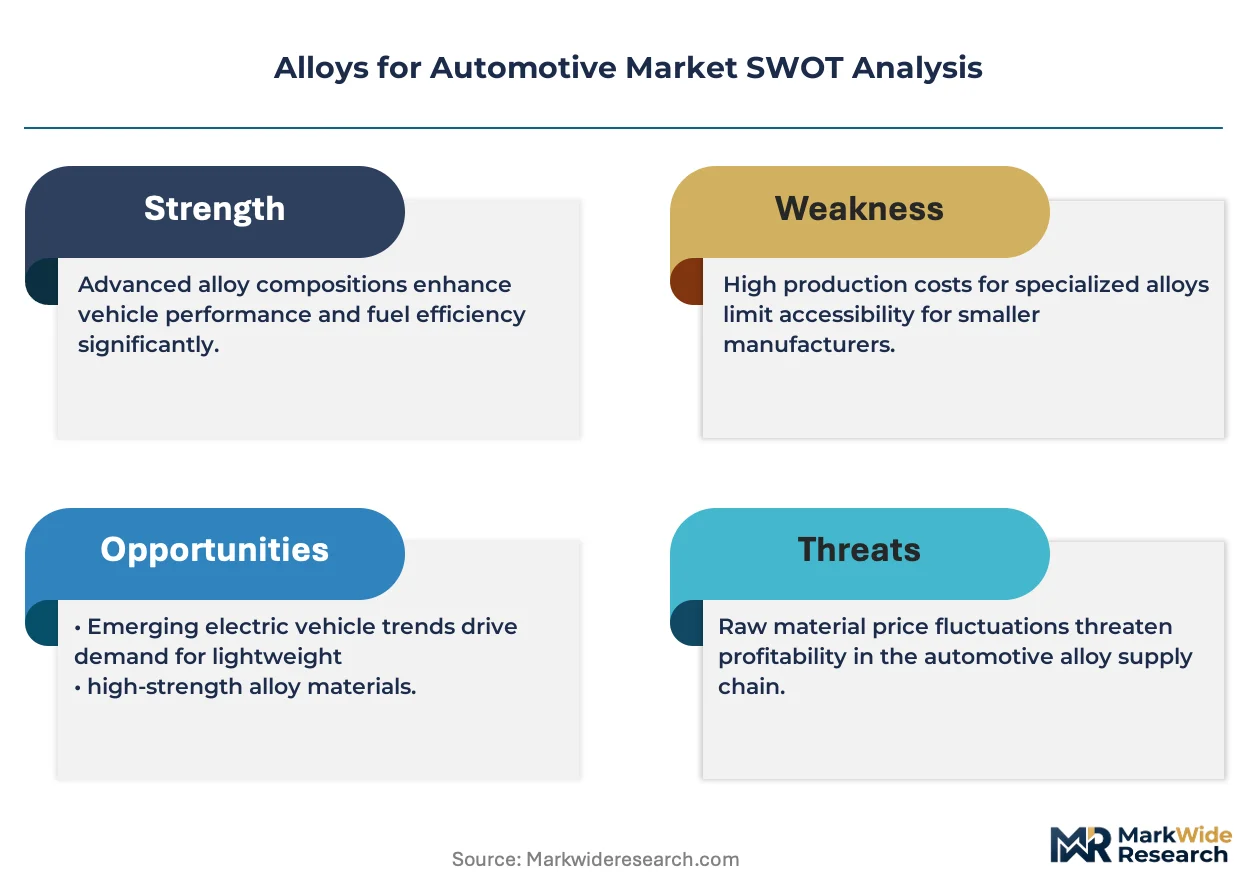
Buyer concentration among electric vehicle OEMs is consolidating as legacy automakers and dedicated EV producers scale aluminum-intensive platforms. ArcelorMittal leverages its integrated steel-aluminum portfolio to serve hybrid material strategies across European and North American assembly lines. Novelis sustains its position through closed-loop recycling systems that supply automakers with certified low-carbon aluminum sheet. Nippon Steel competes by developing next-generation high-tensile steel grades that retain cost advantages in structural applications where aluminum substitution remains incomplete.
Alloys for automotive applications are metallic materials engineered to achieve specific strength-to-weight ratios, corrosion resistance, and formability parameters critical to vehicle performance and manufacturing feasibility. Aluminum alloys typically contain silicon, magnesium, or copper additions and undergo solution heat treatment and aging to achieve T6 or T7 tempers suitable for crash-critical body panels and chassis castings. Steel alloys dominate in chassis and suspension parts where ultimate tensile strength above 1500 MPa justifies density penalties, while aluminum alloys lead in body structure applications where OEMs prioritize mass reduction for battery range extension. Magnesium alloys occupy niche positions in steering wheels and seat frames where further weight savings justify higher raw material costs and corrosion protection requirements.
The EPA enforces Corporate Average Fuel Economy standards that directly incentivize mass reduction through alternative materials, while the EU Green Deal's carbon border adjustment mechanism penalizes imports of high-emission primary aluminum. China's MIIT mandates new energy vehicle production quotas that accelerate domestic demand for lightweight alloys in battery electric architectures. Stakeholders must monitor evolving alloy carbon footprint certification requirements as Scope 3 emissions disclosure obligations expand across automotive supply chains.
Market Dynamics
Electric vehicle platform architectures are forcing a material substitution cascade across body-in-white assemblies, with aluminum alloys displacing conventional steel grades in crash-critical structures where battery mass penalties demand compensatory weight reduction.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:These mandates penalize fleet-wide mass inefficiency, compelling Detroit Three automakers to adopt aluminum-intensive closures and chassis subframes in full-size truck platforms.
- Battery enclosure demand:Extruded aluminum profiles and high-pressure die castings now constitute the dominant material solution for protecting lithium-ion cell arrays in skateboard architectures.
- China's NEV production quotas:MIIT mandates require domestic OEMs to achieve escalating new energy vehicle sales ratios, accelerating aluminum sheet consumption in indigenous EV body shops.
Market Restraints
- Primary aluminum price volatility:Smelter energy costs and alumina supply disruptions transmit directly to automotive alloy premiums, compressing Tier 2 supplier margins.
- High-tensile steel retention:Third-generation advanced high-strength steels above 980 MPa retain structural applications where aluminum's modulus deficit requires prohibitive section thickness.
- EU carbon border adjustment mechanism:This framework penalizes embedded emissions in imported primary aluminum, disadvantaging non-EU smelters without renewable energy certificates.
Strategic Opportunities
- Closed-loop recycling infrastructure:OEMs and mills can capture post-industrial scrap from stamping operations, reducing Scope 3 emissions and securing alloy supply.
- Magnesium alloy expansion:Cast magnesium components in seat frames and steering wheels offer further mass reduction where corrosion protection and flammability standards permit.
- India's PLI scheme for auto components:This incentive program attracts aluminum casting investments for export-oriented component manufacturing serving ASEAN EV assemblers.
Industry Challenges
- Multi-material joining expertise:Dissimilar metal welding between aluminum body panels and steel chassis nodes requires specialized equipment and process control that remains scarce in contract manufacturing.
- Alloy temper certification timelines:New 6xxx and 7xxx series formulations for crash applications require 18-24 month OEM validation cycles before production release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alloys for Automotive Market |
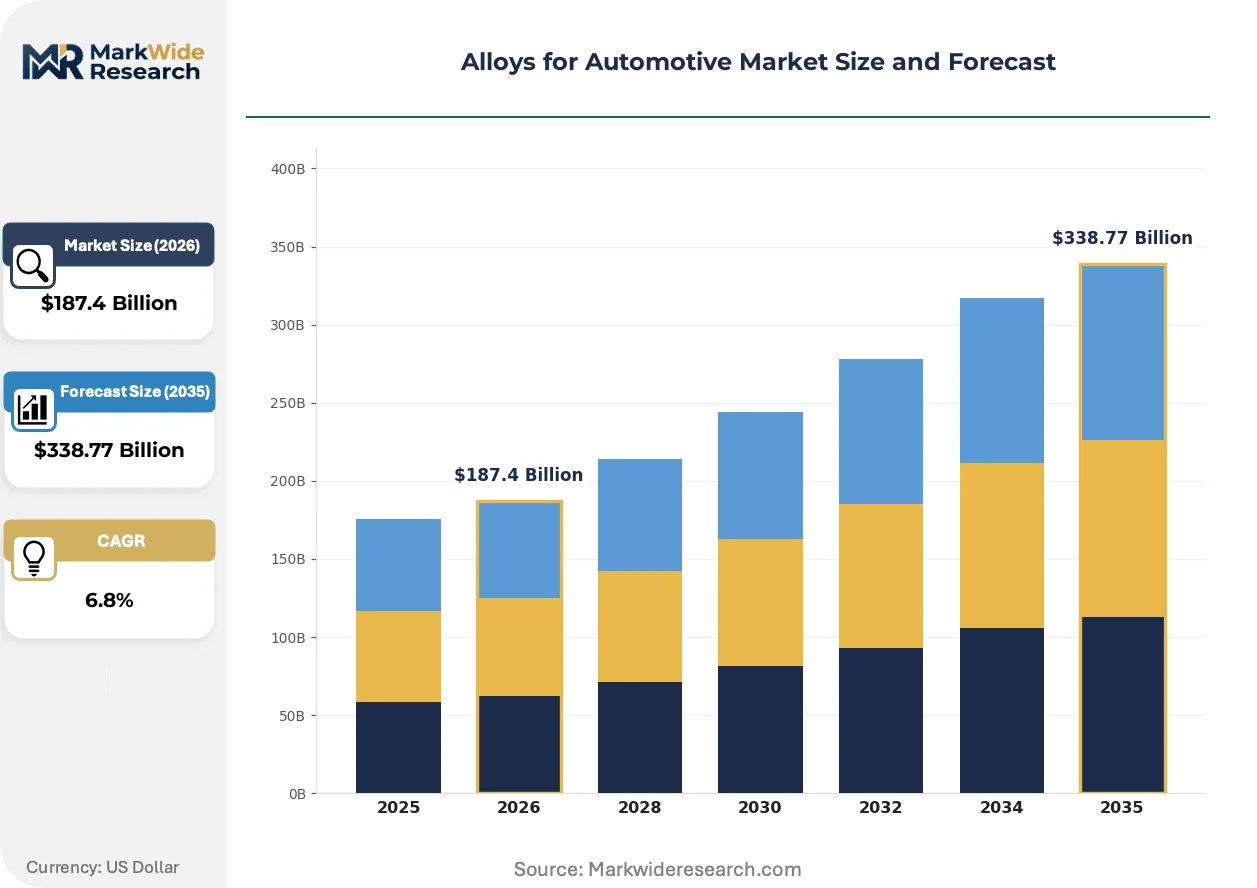
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Alloy Type: Aluminum Alloys, Steel Alloys, Magnesium Alloys, Titanium Alloys End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Chassis, Engine Components, Body Structure, Suspension Parts Manufacturing Stage: Primary Processing, Secondary Processing, Surface Treatment, Finished Products |
| Companies Covered | ArcelorMittal, Novelis, Constellium, Alcoa Corporation, ThyssenKrupp, Nippon Steel, UACJ Corporation, Norsk Hydro, AMG Advanced Metallurgical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alloys for Automotive Market Emerging Trajectories
Material science advances and regulatory carbon accounting are converging to redefine competitive advantage in automotive alloy supply, with sustainability credentials now ranking alongside mechanical performance in procurement decisions.
Gigacasting is rewriting body structure economics. Tesla's proprietary high-pressure die casting machines consolidate 70+ stamped steel components into single aluminum castings for rear underbodies. Chinese EV specialists including BYD and NIO are replicating this approach at scale. The technology is compressing part counts, eliminating welding labor, and enabling geometries impossible with stamped sheet construction.
The EU Green Deal's carbon border adjustment mechanism is reshaping primary aluminum sourcing. European automakers now require mass-balance certificates documenting renewable energy inputs for smelted metal. German OEMs have established direct offtake agreements with Icelandic and Norwegian hydro-powered smelters. The regulation is most acute for structural castings where Chinese primary aluminum carries 3-4x the embedded emissions of European hydro metal.
Buyer concentration among dedicated EV platforms is consolidating alloy procurement. Legacy automakers and battery-electric startups are bypassing traditional distributor networks to negotiate direct mill relationships for certified low-carbon sheet. Tesla, Rivian, and Lucid have established captive aluminum supply chains with volume commitments spanning 5-7 year horizons. This behavior is most visible in North American assembly operations where new greenfield EV plants lack established supplier infrastructure.
Alloys for Automotive Market Segmentation
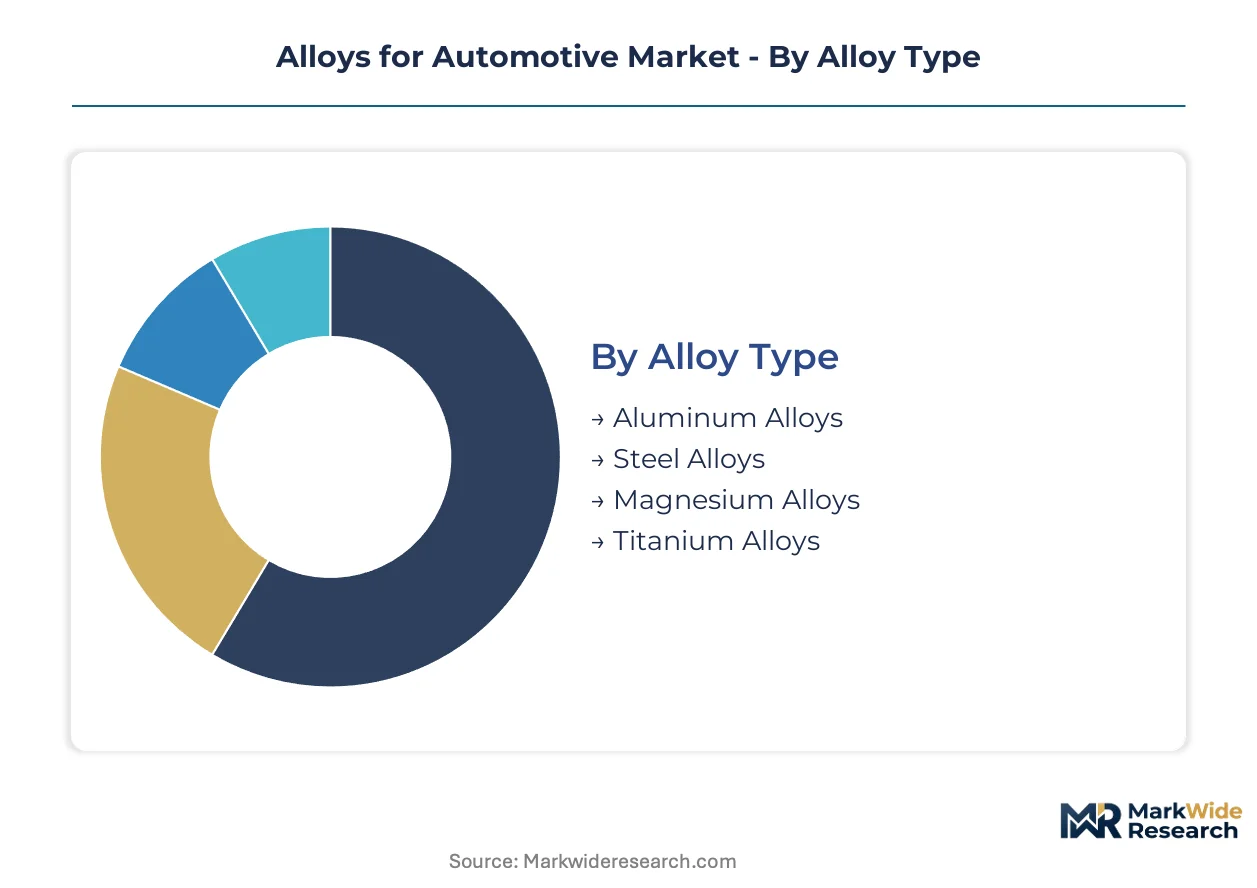
Material selection in automotive alloys operates through distinct technical and commercial pathways. Each segmentation dimension reveals where procurement power concentrates and which specifications command premium positioning.
Alloy Type:
EPA fuel economy certification and EU carbon border adjustment documentation requirements vary sharply across metallic systems, with aluminum alloys facing the most intensive embedded emissions verification.
- Aluminum Alloys:These materials incorporate silicon, magnesium, or copper additions processed to T6 or T7 tempers for crash-critical applications. Demand concentrates in battery enclosure extrusions and gigacast underbody structures for electric vehicle platforms, where OEMs prioritize mass reduction to offset lithium-ion cell weight penalties.
- Steel Alloys:Advanced high-strength grades above 980 MPa retain dominance in chassis rails and suspension knuckles where modulus and fatigue resistance justify density trade-offs. North American full-size truck platforms continue specifying these alloys for frame rails subject to NHTSA crashworthiness validation.
- Magnesium Alloys:AZ91D and AM60B grades serve steering wheels and seat frames where 33% density reduction versus aluminum warrants corrosion protection investments.
- Titanium Alloys:Ti-6Al-4V and related formulations occupy exhaust valves and connecting rod applications in high-performance powertrains where temperature resistance commands extreme cost tolerance.
Aluminum alloys sit at the top of the volume ranking, with magnesium alloys climbing the fastest as EV interior component specifications tighten.
End User:
Procurement scale and technical specification authority separate stakeholders across the supply chain, with direct OEM relationships increasingly displacing distributor intermediaries for certified low-carbon material offtake.
- OEMs:Detroit Three automakers, German luxury manufacturers, and Chinese EV specialists now negotiate direct mill contracts spanning five-to-seven-year horizons for body sheet and structural castings with mass-balance renewable energy certificates.
- Tier-1 Suppliers:Magna, Gestamp, and Benteler operate aluminum stamping and casting facilities supplying multiple OEM platforms under strict alloy temper certification protocols.
- Vehicle Assemblers:Contract manufacturers and joint-venture assembly plants in emerging markets source standardized alloy grades through regional distributor networks with limited specification customization.
- Aftermarket Providers:Collision repair specialists and performance tuning shops consume smaller volumes of certified replacement alloys, often facing 18-24 month validation delays for new temper approvals.
OEMs capture the dominant procurement volume position, though Tier-1 suppliers are expanding most quickly through platform-agnostic component manufacturing investments.
Application:
Functional performance requirements and crash safety validation intensity create divergent material specifications across vehicle systems, with battery electric architectures rewriting traditional application boundaries.
- Body Structure:Aluminum-intensive closures, floor pans, and roof rails now incorporate 6xxx-series sheet and 7xxx-series reinforcements to achieve 2026 EPA fleet mass targets.
- Chassis:Steel dominates frame rails and crossmembers where third-generation advanced high-strength grades above 1180 MPa enable thinner sections without stiffness compromise.
- Engine Components:Cast aluminum cylinder heads and pistons face substitution pressure as battery electric powertrains eliminate thermal management demands.
- Suspension Parts:Forged aluminum control arms and cast iron knuckles split by axle load requirements, with front suspensions favoring mass reduction and rear axles retaining steel for towing capacity.
Body structure applications command the largest alloy tonnage, while chassis specifications are gaining share fastest through truck platform aluminum substitution programs.
Manufacturing Stage:
Value capture potential and technical barrier height vary across processing stages, with surface treatment and finished product operations offering margin expansion opportunities versus commodity primary processing.
- Primary Processing:Smelting and continuous casting operations in Iceland, Norway, and Quebec supply low-carbon aluminum ingot to European and North American automakers meeting EU Green Deal carbon border requirements.
- Secondary Processing:Rolling mills and extrusion presses transform ingot into automotive-grade sheet and profiles, with closed-loop scrap recycling systems at Novelis and Alcoa securing Scope 3 emissions advantages.
- Surface Treatment:Anodizing, conversion coating, and e-coat preparation lines add corrosion protection and paint adhesion properties, commanding 15-25% value-added premiums over base metal.
- Finished Products:Stamped panels, die castings, and machined forgings represent the highest integration stage, where Tier-1 suppliers capture design engineering fees alongside material conversion margins.
Secondary processing handles the greatest material throughput, with surface treatment operations expanding most quickly as OEMs mandate extended corrosion warranties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the highest aluminum alloy intensity per vehicle produced, while China generates the largest absolute tonnage demand through sheer EV production scale. These two markets illustrate divergent pathways—European premium engineering versus Chinese volume manufacturing.
China
Domestic EV producers BYD and NIO are scaling aluminum-intensive skateboard architectures at rates unmatched elsewhere. MIIT production quotas mandate escalating new energy vehicle sales ratios through 2025. The Yangtze River Delta cluster around Shanghai hosts gigacasting facilities supplying battery enclosures for export-oriented assemblers.
Germany
BMW and Mercedes-Benz specify certified low-carbon aluminum sheet for body structures meeting EU Green Deal carbon border requirements. The KBA enforces stringent crashworthiness validation that extends alloy temper certification timelines. Bavaria's Ingolstadt and Munich corridors concentrate closed-loop recycling infrastructure serving premium OEM stamping operations.
United States
Detroit Three automakers adopt aluminum-intensive closures in full-size truck platforms to satisfy EPA Corporate Average Fuel Economy standards. The NHTSA maintains rigorous frame rail crashworthiness protocols that favor advanced high-strength steel retention. Michigan and Ohio assembly corridors source extruded profiles from regional mills with renewable energy certificates.
Japan
Toyota and Honda balance hybrid powertrain retention with selective aluminum substitution in body panels. METI industrial policy supports next-generation high-tensile steel development through public-private R&D consortia. The Nagoya-Tokyo industrial corridor concentrates specialized rolling mills supplying precision-tempered sheet for luxury vehicle architectures.
South Korea
Hyundai and Kia are accelerating aluminum die casting investments for EV-dedicated platforms targeting North American export markets. The MFDS oversees material certification protocols for battery enclosure safety. The Busan-Ulsan manufacturing belt hosts integrated casting and stamping facilities serving ASEAN EV assemblers.
Alloys for Automotive Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct value chain positions. The vendor base stratifies into three tiers—integrated mining-to-sheet operators, independent rolling mills with closed-loop recycling, and specialized casting houses serving single OEM platforms. Archetypes include renewable-energy-certified primary smelters, post-industrial scrap processors, and gigacasting technology licensors. Capacity expansion and strategic partnerships dominate competitive moves as OEMs seek captive supply security.
Among integrated steel-aluminum portfolio operators, ArcelorMittal and Nippon Steel occupy positions spanning hybrid material strategies across multiple regional assembly corridors. Novelis exemplifies the closed-loop recycling archetype, supplying certified low-carbon aluminum sheet through post-industrial scrap recovery systems. These three entities anchor distinct competitive vectors—diversified metallurgy, carbon-accounted recycling, and high-tensile steel retention—reflecting the material substitution tensions reshaping procurement patterns.
| Leading Market Players |
|---|
| ArcelorMittal |
| Novelis |
| Constellium |
| Alcoa Corporation |
| ThyssenKrupp |
| Nippon Steel |
| UACJ Corporation |
| Norsk Hydro |
| AMG Advanced Metallurgical Group |
| Others |
Supply Flow & Price Mechanics
Certified low-carbon aluminum premiums diverge sharply from commodity-grade spot pricing, creating a two-tier structure where EU Green Deal compliance costs propagate through long-term offtake contracts while standard grades trade on volatile smelter energy inputs. This bifurcation concentrates procurement power among OEMs with direct mill relationships, locking in supply security for carbon-accounted material while spot buyers absorb alumina price shocks.
Pricing Analysis
Capacity additions in Iceland and Norway are reshaping price floors for hydro-powered primary aluminum, compressing premiums for renewable-certified ingot against coal-intensive Chinese supply. Contract-based long-term offtake agreements dominate procurement, with price differentiation driven by mass-balance certification tier and volume scale commitments. Pricing pressure stems from energy cost volatility in European smelters, eroding margins for non-integrated distributors. Tier-1 suppliers exhibit lowest price sensitivity due to pass-through clauses, while aftermarket providers face acute cost compression.
Supply Chain Analysis
Closed-loop scrap recovery flows from stamping operations back to rolling mills now constitute critical feedstock for Scope 3 emissions reduction, with Novelis and Alcoa operating integrated networks. Primary supply concentrates in Iceland, Norway, and Quebec for low-carbon ingot, while secondary processing draws from China and Germany for high-volume extrusion. Raw material dependencies center on alumina from Australia and bauxite from Guinea. Single-source vulnerability looms for Icelandic hydro-powered smelters serving German OEMs. Distribution runs through direct mill-OEM contracts bypassing traditional metal traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Alloys for Automotive Market compounds steadily as electric vehicle production quotas across major manufacturing regions institutionalize lightweight material demand through regulatory mandate rather than cyclical preference.
For Market Incumbents: Acquire closed-loop recycling infrastructure to secure post-industrial scrap streams and lock in Scope 3 emissions advantages as EU carbon border adjustment documentation tightens. Defend against Chinese gigacasting technology diffusion by investing in next-generation high-pressure die casting capacity in Mexico and Eastern Europe. Certification investment in renewable energy mass-balancing represents the critical lever for maintaining premium positioning against commodity-grade competitors. For New Entrants and Emerging Players: Capture magnesium alloy expansion opportunities in seat frames and steering wheels where corrosion protection technology gaps limit incumbent saturation. India's PLI scheme for auto components offers the most penetrable geography for export-oriented casting investments serving ASEAN EV assemblers. A specialized go-to-market angle targeting Tier-2 battery enclosure suppliers with certified low-carbon extrusion profiles bypasses direct OEM validation bottlenecks. For Investors and Strategic Acquirers: Consolidation pressure builds where closed-loop recycling capabilities concentrate among pure-play aluminum processors lacking steel portfolio diversification. Long-term viability favors entities with backward integration into renewable-powered primary smelting or captive scrap recovery systems. The signal to watch is OEM direct offtake agreement announcements spanning five-to-seven-year horizons, indicating supply security premiums being capitalized into mill valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Infrastructure | Novelis and Alcoa secure Scope 3 advantages through post-industrial scrap recovery systems serving OEM stamping operations. |
| Gigacasting Capacity Expansion | Tesla's proprietary high-pressure die casting approach consolidates 70+ components, compelling replication by BYD and NIO. |
| Renewable Energy Mass-Balance Certification | German OEMs require documented hydro-powered smelting inputs to satisfy EU Green Deal carbon border adjustment mechanisms. |
| Direct Mill-OEM Ofittake Agreements | Tesla, Rivian, and Lucid bypass distributor networks with five-to-seven-year volume commitments for certified low-carbon sheet. |
| Magnesium Alloy Corrosion Protection R&D | AMG Advanced Metallurgical Group develops surface treatment protocols enabling expanded AZ91D applications in EV interiors. |
Methodological Framework
Direct dialogue with OEM platform engineers, Tier-1 supplier procurement leads, rolling mill operations directors, and aftermarket distribution specialists grounded qualitative assessment of alloy specification evolution and procurement pattern shifts. Secondary validation drew from EPA fuel economy certification databases, EU ETS carbon border adjustment documentation, MIIT new energy vehicle production quotas, and vehicle production registration data from IHS Markit. Bottom-up alloy consumption modeling by vehicle platform triangulated against top-down mill shipment disclosures.
Segment-level value and volume trajectories across the projection horizon reflect disaggregated modeling by alloy type, propulsion architecture, and regional production cluster. The analytical framework incorporated content-per-vehicle assumptions for aluminum-intensive body structures, battery enclosure extrusions, and gigacast underbody components. CAGRs were derived from regression analysis of historical mill shipments against vehicle production forecasts, stress-tested against regulatory mandate compliance timelines.
Underlying measurement precision varies by segment; certified low-carbon aluminum premiums carry tighter precision than commodity-grade spot pricing due to contract transparency. Forecasts reflect assumptions regarding EPA fleet efficiency standard stringency, EU carbon border adjustment phase-in schedules, and Chinese NEV quota enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Automotive Defroster Market
Automotive Components
Automotive Solenoid Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Automotive Glass Market
Automotive Components
Automobile Accessories Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Europe Automotive AHSS Market
Automotive Components
Automotive Comfort Actuators Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
North America Automotive Glass Market
Automotive Components
South Korea Automotive Sunroof Market
Automotive Components
Regenerative Suspension System Market
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
Automotive Refrigerant Market
Automotive Components
Automotive Light Bars Market