
 Canada Automotive Glass Fiber Composites Market | 2026-2036
Canada Automotive Glass Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Automotive Glass Fiber Composites Market Outlook
Project finance tied to clean technology manufacturing is narrowing the competitive field for domestic suppliers. Owens Corning leverages its integrated glass fiber operations to secure long-term supply agreements with Canadian automakers. Solvay Group anchors its position through specialized resin formulations tailored to cold-climate durability requirements. Toray Industries competes by extending its carbon fiber expertise into hybrid glass-carbon solutions for premium vehicle segments.
Canada automotive glass fiber composites combine silica-based glass fibers with thermoset or thermoplastic resin matrices, typically achieving tensile strengths of 300-600 MPa depending on fiber orientation and resin chemistry. These materials reduce component weight by 25-35% compared to stamped steel while maintaining crashworthiness thresholds required for passenger vehicle applications. Sheet molding compound dominates volume consumption in underbody shields and bumper beams where compression molding delivers cycle times under ninety seconds. Structural components represent the fastest-growing application category as unibody electric vehicle architectures demand torsional rigidity without mass penalties. Vacuum infusion technology leads margin pools in low-volume specialty and aftermarket segments where tool-free fabrication offsets higher labor content.
Transport Canada administers the Motor Vehicle Safety Act and correlates with EPA-aligned fuel economy mandates that directly incentivize lightweighting investments. Health Canada and PMRA oversee chemical substance regulations affecting resin formulations, particularly bisphenol-A restrictions in food-contact-adjacent interior applications. The Canadian Environmental Protection Act governs end-of-life composite disposal, pressuring suppliers toward recyclable thermoplastic matrix development. Stakeholders must monitor evolving provincial extended producer responsibility frameworks and their impact on material selection criteria across the automotive value chain.
Market Dynamics
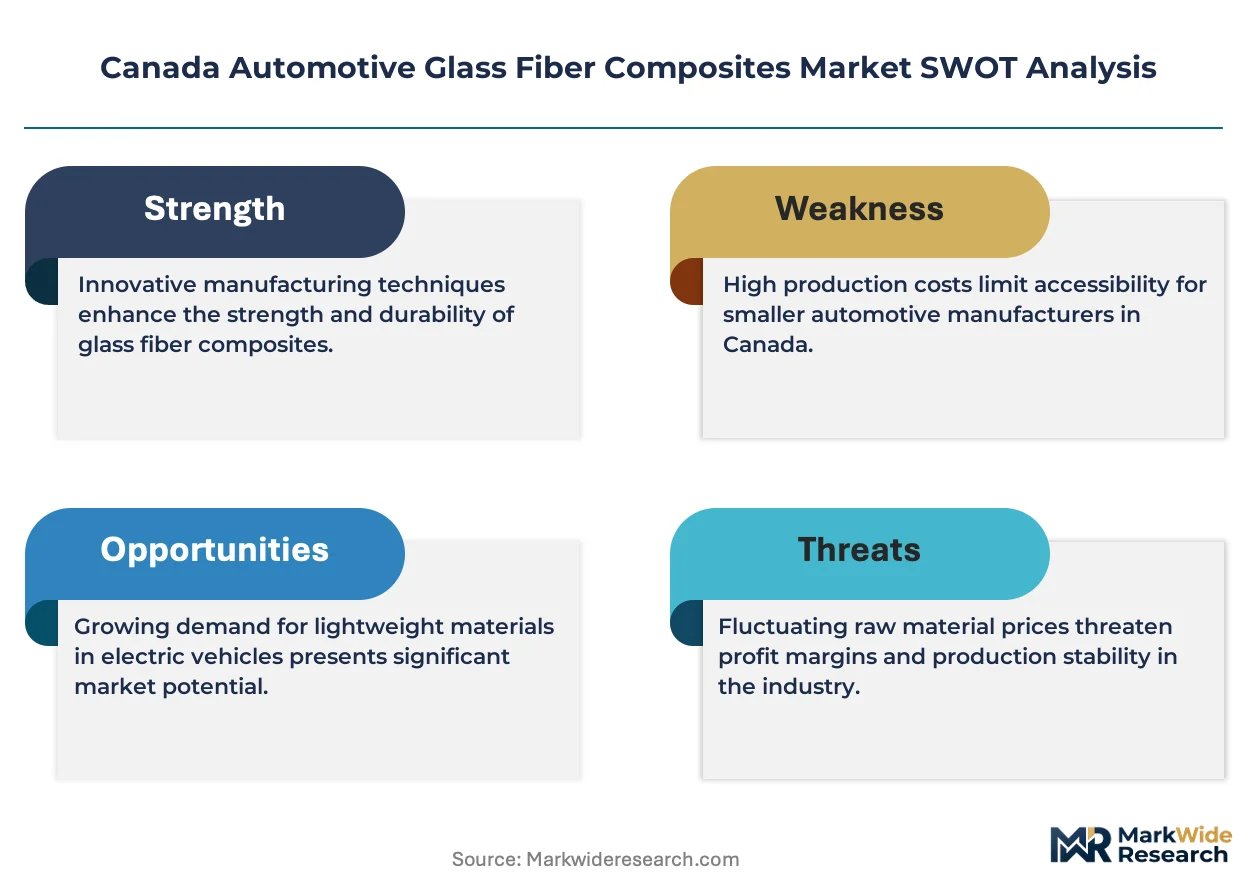
Transport Canada's Clean Fuel Regulations are compressing vehicle mass targets faster than material substitution cycles, forcing Ontario and Quebec assembly plants to requalify lightweight structures mid-platform rather than at redesign gates. This regulatory velocity privileges suppliers with validated resin systems over those with laboratory-scale formulations.
Growth Catalysts
- Clean Fuel Regulations:Transport Canada's escalating fleet-average CO2 mandates compel automakers to shed 150-200 kg per vehicle, accelerating thermoplastic composite trials in structural members previously reserved for steel.
- Unibody EV architectures:Battery pack integration demands torsional rigidity without mass penalties, positioning glass fiber-reinforced thermoplastics as the default material for floor pans and cross-car beams.
- Southern Ontario cluster:Proximity between Windsor toolmakers, Sarnia resin compounders, and Oakville assembly plants reduces logistics friction for just-in-time SMC delivery.
Market Restraints
- Petrochemical input volatility:Epoxy and polyester resin feedstocks track propylene and benzene spot markets, compressing molding compound margins when crude benchmarks swing beyond fifteen percent quarterly.
- Tooling capex concentration:Compression molds for Class A exterior panels require 800-ton presses and 180-day lead times, concentrating supply among three domestic tool-and-die shops.
- End-of-life disposal liability:The Canadian Environmental Protection Act classifies thermoset composites as non-recyclable, exposing automakers to provincial extended producer responsibility fees that thermoplastic alternatives avoid.
Strategic Opportunities
- Quebec battery enclosure supply:Bécancour and Shawinigan lithium refining investments create captive demand for fire-resistant composite housings with 90-minute burn-through ratings.
- Recyclable thermoplastic matrices:Polypropylene and PBT-based systems qualify for closed-loop regrind under emerging provincial circular economy frameworks, differentiating suppliers from thermoset incumbents.
- Cold-climate durability specifications:Health Canada's PMRA scrutiny of plasticizer migration creates premium positioning for resin systems validated to minus forty degrees Celsius impact resistance.
Industry Challenges
- CAE simulation talent scarcity:Fiber orientation prediction in complex geometries requires ANSYS or Moldflow specialists, with fewer than two hundred qualified engineers across the Greater Toronto Area.
- Crashworthiness requalification cycles:Transport Canada's CMVSS 208 and 214 updates demand new pedestrian impact and side-pole intrusion data, extending program timelines by eight to fourteen months.
- Multi-material joining complexity:Dissimilar expansion coefficients between aluminum subframes and glass fiber composites induce galvanic corrosion at bolted interfaces, requiring adhesive process engineering absent from steel-steel heritage designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Automotive Glass Fiber Composites Market |
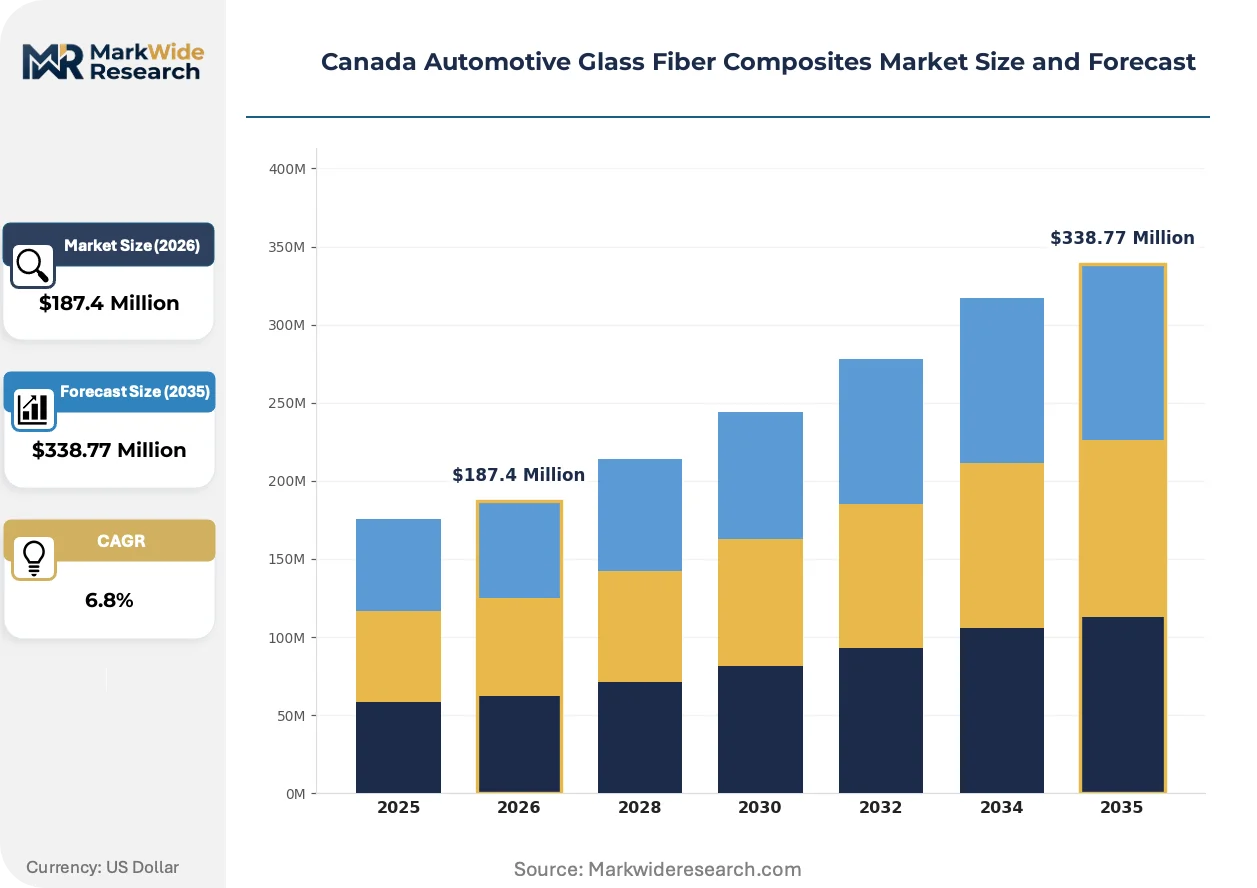
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
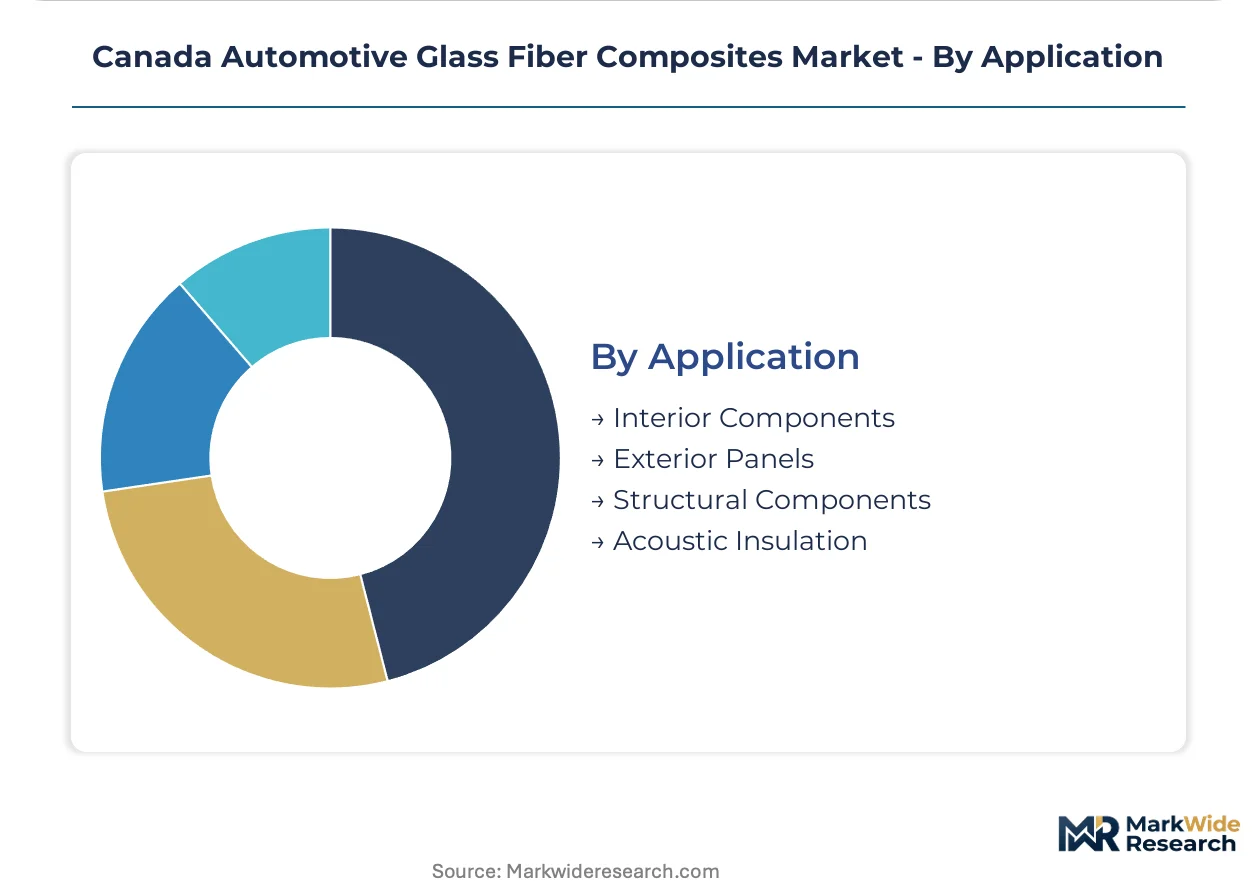
| Segmentation | Product Type: Chopped Strand Mats, Woven Fabrics, Prepregs, SMC End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Resin Transfer Molding, Vacuum Infusion, Pultrusion, Hand Layup Application: Interior Components, Exterior Panels, Structural Components, Acoustic Insulation |
| Companies Covered | Owens Corning, Solvay Group, 3B (Braj Binani Group), Veplas Group, SAERTEX GmbH & Co.KG, Teijin Limited, Toray Industries, Inc., SGL Carbon, Nippon Electric Glass Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Automotive Glass Fiber Composites Market Strategic Shifts
Continuous fiber-reinforced thermoplastic tapes are displacing discontinuous fiber sheet molding compounds in load-bearing applications, compressing the traditional tiering between structural and cosmetic composite grades. This material shift is reconfiguring supplier qualifications and press floor layouts simultaneously.
Direct long-fiber thermoplastic (D-LFT) compounding is rendering obsolete pre-impregnated SMC stock for bumper beams and underbody shields. Tier One suppliers in Windsor and Cambridge are retrofitting 3,000-ton presses with in-line extrusion compounding, cutting material handling costs and enabling real-time fiber length adjustment. The technology is compressing legacy supply chains that separated compounders from molders.
Transport Canada's proposed updates to Motor Vehicle Safety Act testing protocols for electric vehicle battery enclosures are accelerating flame-retardant resin qualification timelines. The regulatory friction is forcing compounders to parallel-track UL 94 V-0 and FMVSS 302 certifications rather than sequential validation. Battery pack suppliers in Oakville and Ingersoll are absorbing six-month schedule premiums to secure dual-compliant material streams.
Fleet procurement departments at major Ontario-based OEMs are consolidating composite supplier rosters from twelve qualified vendors to four strategic partners with captive resin formulation capability. This concentration is displacing spot-market purchasing for commodity SMC grades and privileging long-term offtake agreements with volume commitments. The shift is most visible in exterior panel programs where paint-line compatibility failures carry six-figure rectification costs.
Canada Automotive Glass Fiber Composites Market Segmentation
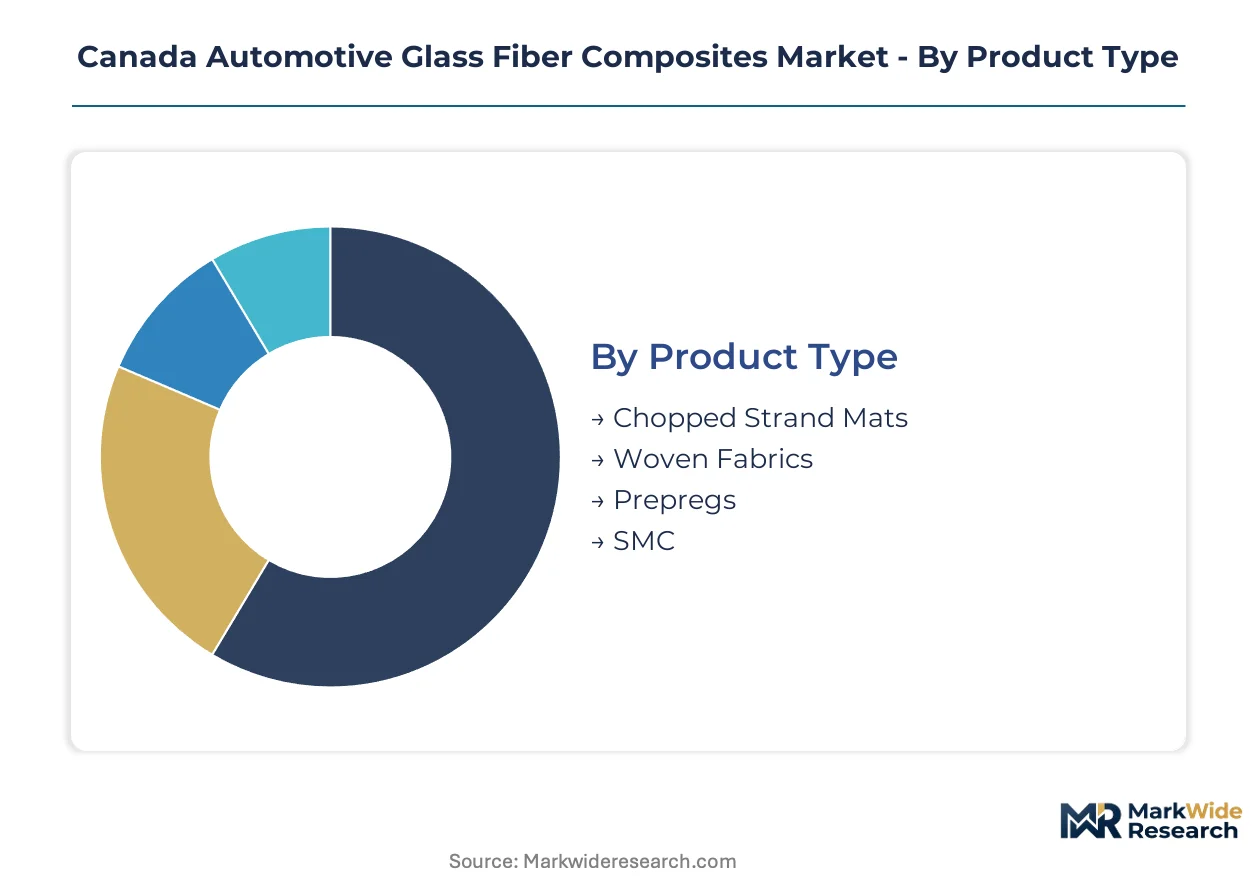
Segmentation in the Canada automotive glass fiber composites market reveals how material form, manufacturing method, and supply chain position determine margin capture. Each dimension carries distinct regulatory exposure and technical qualification barriers that reshape competitive positioning across Ontario and Quebec production corridors.
Product Type:
Cost tier differentiation separates commodity-grade reinforcements from engineered preforms commanding premium pricing.
- SMC:Sheet molding compound combines chopped glass fibers with thermoset polyester resin in ready-to-mold sheets. Compression molding in Windsor and Cambridge tool shops consumes the majority of volume for underbody shields and bumper beams where cycle times under ninety seconds justify press capex.
- Prepregs:Pre-impregnated woven fabrics with partially cured epoxy resin enable complex layup sequences for structural members demanding fiber orientation control. Oakville EV platform suppliers specify prepregs for battery enclosure reinforcements where flame-retardant chemistry must survive Transport Canada burn-through testing.
- Woven Fabrics:Bidirectional and multiaxial weaves serve vacuum infusion applications in low-volume specialty vehicle production around Toronto.
- Chopped Strand Mats:Random-oriented discontinuous fibers anchor hand layup and spray-up processes in aftermarket repair segments across Quebec.
SMC holds installed capacity. Prepregs is rotating up the share rankings.
End User:
Customer type determines specification authority and contract duration across the Canadian automotive value chain.
- OEMs:Ford, Stellantis, and GM Canada retain direct material qualification authority for structural composites in unibody architectures. Their Windsor and Oakville engineering centers mandate resin chemistry validation to minus forty degrees Celsius impact resistance under Health Canada PMRA scrutiny.
- Tier-1 Suppliers:Magna, Linamar, and Martinrea source compound stock under long-term offtake agreements, converting SMC to finished Class A panels. Their procurement consolidation from twelve qualified vendors to four strategic partners privileges suppliers with captive resin formulation.
- Vehicle Assemblers:Contract manufacturers in Ingersoll and Alliston absorb spot-market SMC pricing volatility for limited production runs.
- Aftermarket Providers:Independent collision repair networks in Calgary and Vancouver specify woven fabric kits for heritage vehicle restoration.
OEMs hold installed capacity. Tier-1 Suppliers is rotating up the share rankings.
Technology:
Manufacturing process selection trades labor content against capital intensity and production rate.
- Resin Transfer Molding:Closed-mold injection of catalyzed resin into preplaced fiber preforms yields high surface quality for exterior panels. Quebec compounders near Sarnia supply epoxy formulations calibrated to RTM pressure requirements.
- Vacuum Infusion:Atmospheric pressure drives resin through dry fiber stacks without matched tooling. Toronto-area specialty vehicle producers leverage this for prototype and low-series production where tool-free fabrication offsets labor costs.
- Pultrusion:Continuous pulling of resin-impregnated fibers through heated dies produces constant-cross-section profiles for bumper reinforcement beams.
- Hand Layup:Manual placement of chopped strand mats and woven fabrics persists in aftermarket repair and heritage restoration segments.
Resin Transfer Molding holds installed capacity. Vacuum Infusion is rotating up the share rankings.
Application:
Functional position in the vehicle determines performance specification and regulatory exposure.
- Structural Components:Floor pans, cross-car beams, and battery enclosures demand torsional rigidity without mass penalties. Unibody EV architectures in southern Ontario specify glass fiber-reinforced thermoplastics for these load-bearing elements where Transport Canada crashworthiness standards apply.
- Exterior Panels:Hoods, fenders, and liftgates require Class A surface finish compatible with automotive paint lines. Paint-line compatibility failures carry six-figure rectification costs, concentrating supply among qualified molders with proven track records.
- Interior Components:Door panels, instrument carriers, and seat structures specify lower-cost SMC grades where bisphenol-A restrictions under Health Canada oversight constrain resin selection.
- Acoustic Insulation:Non-structural dash and firewall pads absorb NVH in ICE vehicle platforms.
Structural Components holds installed capacity. Exterior Panels is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transport Canada's Clean Fuel Regulations compress fleet-average CO2 mandates faster than material substitution cycles, forcing assembly plants in Ontario and Quebec to requalify lightweight structures mid-platform. Provincial extended producer responsibility frameworks under the Canadian Environmental Protection Act reshape material selection criteria across the automotive value chain.
Ontario
Unibody EV architectures from Ford, Stellantis, and GM Canada drive demand for glass fiber-reinforced thermoplastics in floor pans and cross-car beams. Transport Canada crashworthiness standards apply to battery enclosures assembled in Oakville and Ingersoll. The Windsor toolmaking cluster supplies compression molds for Class A exterior panels with 90-second cycle times.
Quebec
Bécancour and Shawinigan lithium refining investments create captive demand for fire-resistant composite battery housings with 90-minute burn-through ratings. Health Canada PMRA scrutiny of plasticizer migration privileges resin systems validated to minus forty degrees Celsius impact resistance. Montreal-area compounders specialize in cold-climate durability formulations.
Alberta
Petrochemical feedstock volatility in propylene and benzene spot markets compresses molding compound margins for Calgary-based distributors. The province's energy sector workforce scarcity limits CAE simulation talent pools for fiber orientation prediction. Edmonton suppliers focus on aftermarket repair segments rather than OEM qualification.
British Columbia
Vancouver and Victoria collision repair networks specify woven fabric kits for heritage vehicle restoration using vacuum infusion methods. The Canadian Environmental Protection Act's thermoset disposal liability pushes independent shops toward recyclable thermoplastic alternatives. Low-volume specialty producers leverage tool-free fabrication for prototype work.
Canada Automotive Glass Fiber Composites Market Competitive Environment
On the supply side, the industry is consolidating around suppliers with captive resin formulation capability and validated cold-climate performance data. Three strategic archetypes dominate: integrated glass fiber producers with compound operations, specialized resin formulators with regulatory compliance expertise, and hybrid carbon-glass solution providers targeting premium segments. Competitive moves concentrate on long-term offtake agreements with volume commitments and parallel-track certification for flame-retardant battery enclosure materials.
Within the integrated materials tier, Owens Corning anchors supply relationships through captive glass fiber operations, while Solvay Group exemplifies the specialized resin formulator archetype with cold-climate durability focus. Toray Industries occupies a position bridging carbon fiber expertise into hybrid glass-carbon solutions for premium vehicle applications.
| Leading Market Players |
|---|
| Owens Corning |
| Solvay Group |
| 3B (Braj Binani Group) |
| Veplas Group |
| SAERTEX GmbH & Co.KG |
| Teijin Limited |
| Toray Industries, Inc. |
| SGL Carbon |
| Nippon Electric Glass Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Petrochemical input volatility between Sarnia resin compounders and Alberta propylene suppliers compresses molding compound margins while simultaneously concentrating supply relationships among three domestic tool-and-die shops. This feedstock exposure determines both the spread between thermoset commodity grades and recyclable thermoplastic premiums and the geographic clustering of compression molding capacity around Windsor.
Pricing Analysis
Certification level for Transport Canada crashworthiness and Health Canada PMRA cold-climate validation creates the primary spread between qualified structural prepregs and commodity SMC grades. Contract-based long-term offtake agreements dominate OEM procurement, with volume scale and paint-line compatibility history serving as secondary price differentiation factors. Cost compression in exterior panel programs is intensifying because paint-line failure rectification costs concentrate supply among proven molders. Tier-1 suppliers with captive resin formulation capability exhibit the least price sensitivity; spot-market purchasers in limited production runs absorb the most volatility.
Supply Chain Analysis
Tariff exposure between US glass fiber producers and Canadian compounders dominates supply chain risk calculations for Ontario assembly plants. Raw material dependencies rest on US silica-based fiber, Sarnia-area epoxy and polyester resin feedstocks, and Quebec lithium refining byproducts for fire-resistant battery enclosure formulations. Single-source vulnerability concentrates in 800-ton compression mold supply from Windsor toolmakers. Distribution runs through just-in-time SMC delivery corridors linking Sarnia compounders to Oakville and Ingersoll assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering talent scarcity for CAE fiber orientation simulation constrains expansion velocity, with fewer than two hundred qualified specialists across the Greater Toronto Area anchoring competitive differentiation to human capital capture.
For Market Incumbents: Insulate qualified resin formulation positions by securing long-term offtake agreements with volume commitments before Transport Canada accelerates requalification timelines. Prioritize backward integration into Sarnia-area petrochemical feedstocks to buffer propylene and benzene spot market swings. Capture remaining CAE simulation talent through targeted recruitment from aerospace composites programs. For New Entrants and Emerging Players: Alberta aftermarket repair networks present the most penetrable entry vector, where thermoplastic disposal liability under the Canadian Environmental Protection Act displaces incumbent thermoset suppliers. Target vacuum infusion fabrication for heritage vehicle restoration kits in Calgary and Vancouver. Lead with recyclable polypropylene matrix formulations qualifying for emerging provincial circular economy frameworks. For Investors and Strategic Acquirers: Specialized resin formulators with validated minus forty degrees Celsius impact resistance data represent the priority acquisition archetype. Long-term viability hinges on battery enclosure material streams achieving parallel UL 94 V-0 and FMVSS 302 certifications. Watch Transport Canada Motor Vehicle Safety Act testing protocol updates as the inflection signal for flame-retardant chemistry demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Recyclable Thermoplastic Matrix Development | Qualifies suppliers for provincial extended producer responsibility fee avoidance under the Canadian Environmental Protection Act. |
| CAE Simulation Talent Acquisition | Secures scarce ANSYS and Moldflow specialists for fiber orientation prediction in complex EV unibody geometries. |
| Long-term Supply Agreement with OEMs | Locks in volume commitments as procurement departments consolidate vendor rosters from twelve to four qualified suppliers. |
| Parallel-track Certification Investment | Accelerates flame-retardant battery enclosure qualification timelines under Transport Canada proposed protocol updates. |
| Windsor Toolmaking Cluster Partnership | Guarantees compression mold access for Class A exterior panels with sub-ninety-second cycle times. |
Study Parameters
Desk research of customs and trade flow data, vehicle production databases, and Health Canada PMRA regulatory filings preceded structured interviews with Tier 1 supplier procurement managers, OEM platform engineers, Sarnia resin compounder technical directors, and Windsor tool shop operations leads. Secondary validation drew from SEC filings of integrated materials suppliers, IHS Markit registration data, and provincial extended producer responsibility framework documentation. Bottom-up volume estimates triangulated against top-down market sizing from automotive production forecasts.
The analytical framework held Transport Canada Clean Fuel Regulations enforcement trajectory and EV platform rollout schedules fixed across the projection horizon while varying petrochemical feedstock price assumptions and CAE talent availability. Segmentation dimensions modeled include product form, manufacturing technology, end-user category, and regional production cluster. CAGRs derived from regression analysis of historical lightweighting adoption curves and OEM platform investment disclosures. Industry-specific forecast inputs encompassed battery pack integration timelines and provincial circular economy framework adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by resin formulators or accelerated talent poaching from aerospace sectors would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
Automotive Light Bars Market
Automotive Components
Automotive Part Cleaners and Degreasers Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Automotive Bearing Market
Automotive Components
South Korea Automotive Sunroof Market
Automotive Components
Torque Vectoring Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Filters Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
India Passenger Vehicles Lubricants Market
Automotive Components
Automotive Glass Film Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market