
 Global Automatic Lubrication System Market | 2026-2036
Global Automatic Lubrication System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automatic Lubrication System Market Intelligence
Demand from aftermarket providers is rotating toward large-scale equipment operators who prioritize total cost of ownership and operational uptime. This shift favors systems that can be integrated directly into equipment monitoring platforms. SKF Lubrication Systems leverages its extensive bearing and industrial portfolio to offer integrated solutions. Graco Inc. specializes in fluid-handling components for construction and mining, while Groeneveld-BEKA positions its systems as factory-fit options with major vehicle manufacturers.
An automatic lubrication system is an electro-mechanical or pneumatic device designed to deliver a controlled, precise amount of lubricant to multiple points on a machine while it is in operation. Its primary purpose is to reduce friction and wear, prevent premature component failure, and minimize manual maintenance. Among product types, single-line systems serve smaller machinery, whereas dual-line and progressive systems are specified for heavy-duty applications like mining equipment and metalworking machines.
Regulations from the US Occupational Safety and Health Administration (OSHA) and the EU's Machinery Directive indirectly drive adoption by mandating safer maintenance practices. Environmental standards from bodies like the EPA in the US and China's MEE also limit lubricant spillage, favoring contained, automated systems. System suppliers must decide whether to compete on component cost or focus on integrated, telematics-enabled solutions that prove a return on investment through reduced downtime.
Market Dynamics
The convergence of mechanical lubrication hardware with digital IIoT platforms is the central structural force shaping the market. This integration transforms lubrication systems from passive components into active, data-generating nodes for predictive maintenance and asset management.
Growth Catalysts
- Infrastructure Programs:Large-scale infrastructure projects, particularly in India, create sustained demand for new construction machinery, which increasingly specifies factory-fit automatic lubrication systems to maximize uptime.
- Safety Mandates:Regulations like the EU's Machinery Directive and OSHA standards in the US compel employers to minimize hazardous manual maintenance tasks, indirectly promoting automated solutions.
- Uptime Requirements:In the mining industry, the high cost of equipment downtime makes preventative, automated lubrication a necessity for critical machinery like haul trucks and excavators.
Market Restraints
- High Initial Cost:The significant capital expenditure required to retrofit older, non-automated equipment fleets remains a primary barrier for smaller operators compared to low-cost manual greasing methods.
- Integration Complexity:Integrating advanced lubrication systems with legacy machinery lacking native digital interfaces or standardized communication ports presents significant technical and cost hurdles for fleet owners.
- Manual Method Persistence:For less critical or smaller-scale equipment, the perceived adequacy and lower upfront cost of traditional manual lubrication schedules continue to act as a persistent substitute.
Strategic Opportunities
- Renewable Energy Sector:The expansion of wind energy provides a key opportunity, as lubricating hard-to-access turbine components like pitch and yaw bearings is ideally suited for automated systems.
- Predictive Maintenance Integration:Developing systems that integrate with IIoT platforms to enable predictive alerts for lubricant replenishment or component failure offers a path to higher-margin service contracts.
- Agricultural Mechanization:Targeting large-scale agricultural operations in markets like Brazil with solutions for tractors and harvesters represents a significant underpenetrated application segment.
Industry Challenges
- Technician Skill Gaps:The market faces a shortage of technicians who possess the dual expertise in mechanical systems and the electronic controls and software of modern automated lubricators.
- Interoperability Standards:A lack of universal communication protocols between lubrication systems and OEM equipment telematics platforms complicates fleet-wide integration for end-users with mixed assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automatic Lubrication System Market |
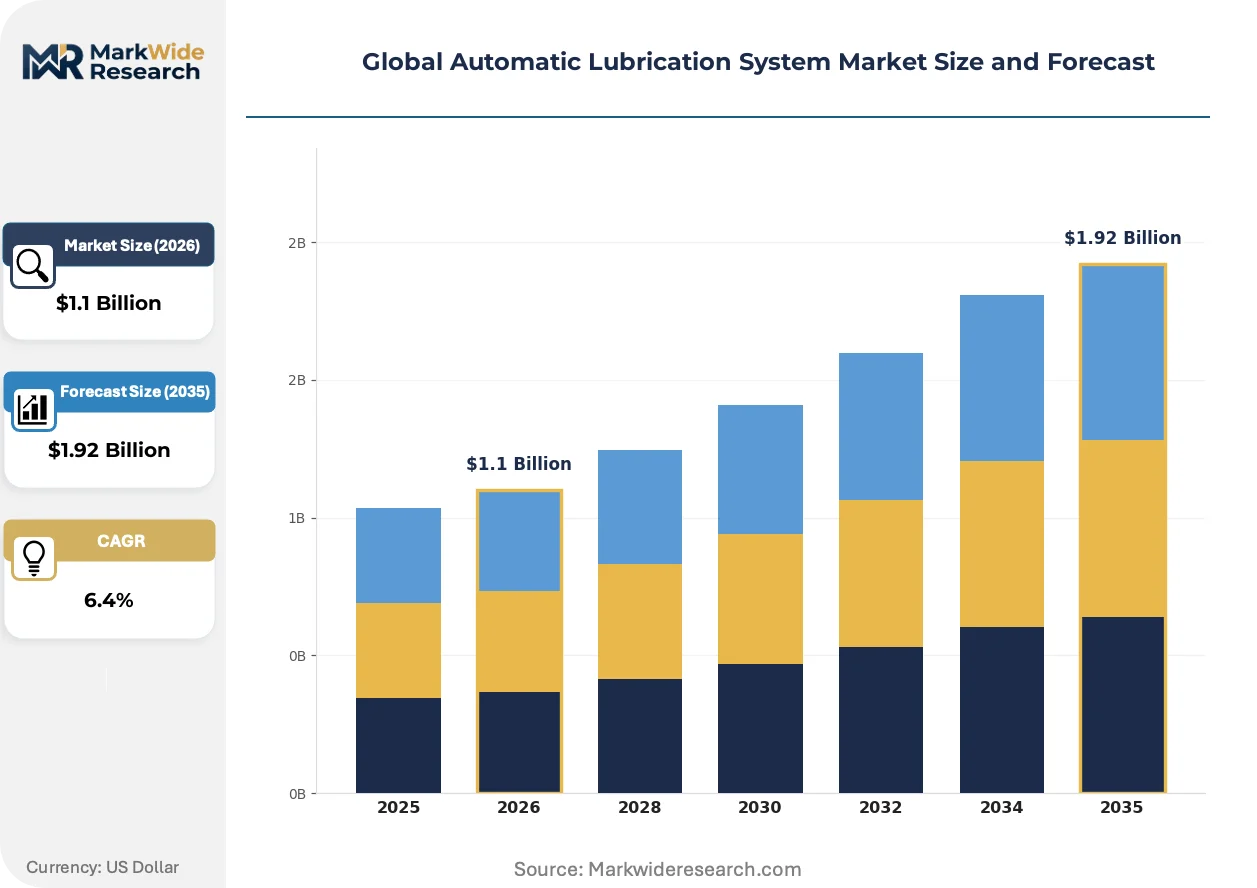
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $1.92 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Line, Dual Line, Multi Line, Progressive, Oil Mist Technology: Electro-Mechanical, Pneumatic, Hydraulic, Battery Operated, Manual Application: Mining Equipment, Construction Machinery, Agricultural Machinery, Metalworking Machines, Textile Machinery End User: Manufacturers, Equipment Operators, Maintenance Facilities, Aftermarket Providers, Industrial Plants |
| Companies Covered | Bijur Delimon International, DropsA USA, Inc., SKF Lubrication Systems, Cenlub Systems, Trico Corporation, Lincoln Industrial, Groeneveld-BEKA, H-T-L perma, Graco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automatic Lubrication System Market Strategic Shifts & Innovations
The market's evolution is defined by the shift from standalone mechanical devices to intelligent, networked systems. This transformation is driven by the need for greater operational efficiency, data visibility, and compliance with stricter operating standards.
Single-point lubricators with integrated MEMS sensors deliver precise, localized lubrication. These are rapidly adopted in space-constrained applications like food processing and packaging machinery. This technology is miniaturizing the lubrication function, allowing automation on smaller components previously serviced by hand.
Environmental rules, including spill prevention mandates from the US EPA and China's MEE, penalize lubricant leakage. This creates a direct incentive to replace manual greasing, which is prone to spillage. Heavy industries like mining and marine are most affected, accelerating investment in contained, automated systems for compliance.
Large-scale equipment operators now evaluate systems on total cost of ownership, not just initial price. This procurement focus favors solution providers who prove ROI through reduced downtime and lower lubricant use. The shift is most visible in capital-intensive sectors like construction and transport in North America and Europe.
Global Automatic Lubrication System Market Segmentation
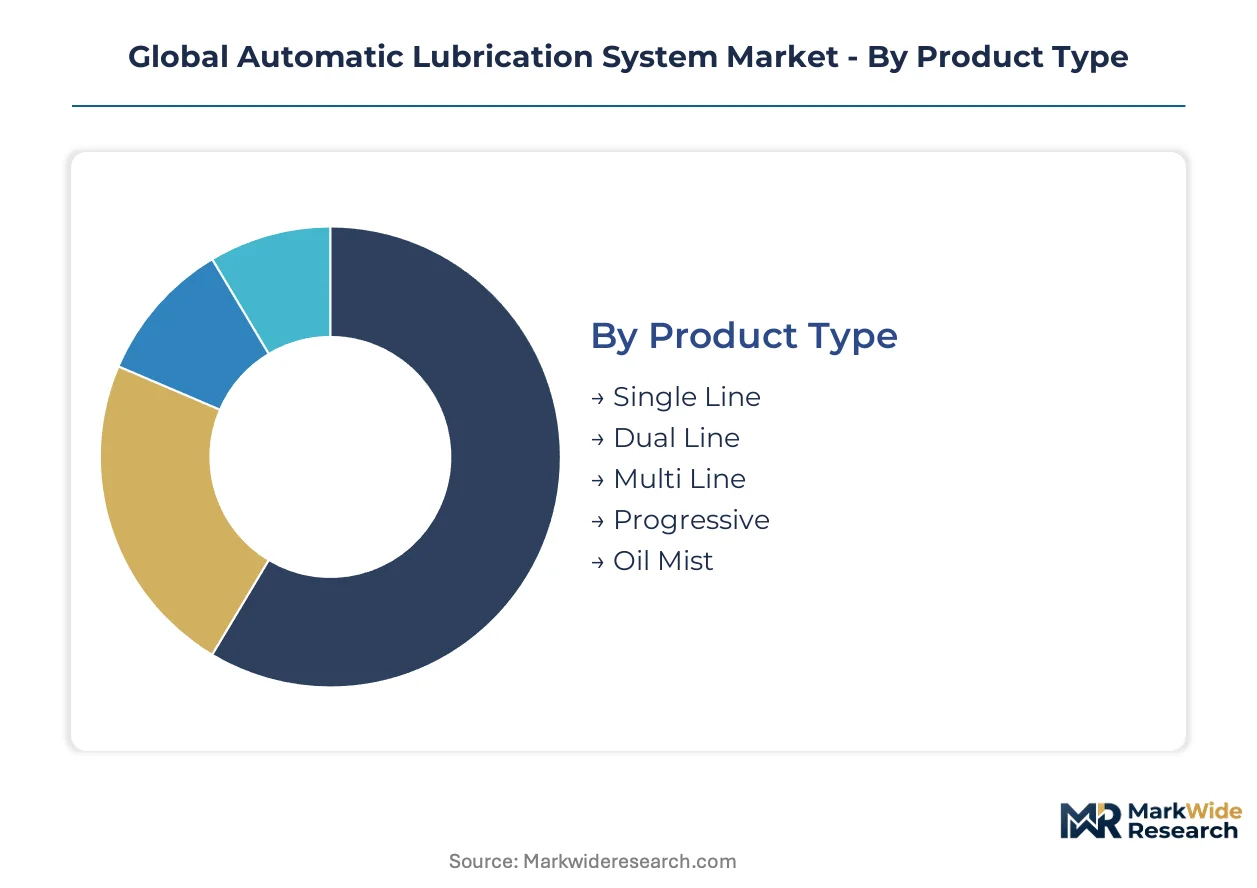
The Global Automatic Lubrication System Market requires precise segmentation to understand demand drivers and technological preferences across diverse industrial applications. Analyzing these distinct segments reveals where market growth concentrates and where competitive pressures are most intense.
Product Type:
The Product Type segment faces significant substitution pressure, particularly from manual greasing methods for smaller systems, while advanced multi-line and progressive systems offer superior performance over simpler designs.
- Dual Line:Dual Line systems utilize two primary lines to deliver precise lubricant volumes alternately to numerous points, making them suitable for large-scale construction machinery in North America where uptime is critical.
- Progressive:Progressive systems deliver lubricant in a sequential manner to various lubrication points, ensuring all points receive their designated amount; demand for these robust systems is high in European metalworking facilities.
- Single Line:Single Line systems use a single main line to feed lubricant, often suitable for smaller industrial machines and light-duty applications.
- Multi Line:Multi Line systems feature independent pumping elements for each lubrication point, providing individual control for diverse industrial plants.
- Oil Mist:Oil Mist systems generate a fine mist of oil and air for continuous lubrication, frequently employed in high-speed spindles and bearings.
Dual Line retains volume leadership; Progressive holds the steepest expansion curve.
Technology:
Technology differentiation often correlates with varying cost tiers, influencing adoption based on initial investment and operational expense considerations for equipment operators.
- Electro-Mechanical:These systems combine electrical and mechanical components for precise lubricant delivery, integrating well with digital control platforms for predictive maintenance in industrial plants.
- Pneumatic:Pneumatic systems use compressed air to drive lubricant, finding extensive use in heavy-duty construction machinery in India due to their robustness and ease of maintenance.
- Hydraulic:Hydraulic systems leverage fluid pressure for lubrication, commonly found in applications requiring high force delivery.
- Battery Operated:Battery Operated systems provide portable and flexible lubrication for remote or mobile equipment, particularly in agricultural settings.
- Manual:Manual lubrication involves direct application by hand, remaining a low-cost option for less critical or smaller equipment.
Electro-Mechanical solutions are gaining market share most quickly, driven by integration with IIoT platforms.
Application:
Application segments reflect distinct volume requirements, with heavy industries driving substantial demand for automated lubrication solutions.
- Mining Equipment:Mining Equipment relies heavily on automated systems to ensure continuous operation of haul trucks and excavators, minimizing costly downtime in remote Australian mines.
- Construction Machinery:Construction Machinery, including cranes and bulldozers, increasingly specifies factory-fit automatic lubrication systems to maximize uptime on large infrastructure projects in China.
- Agricultural Machinery:Agricultural Machinery benefits from automated systems for tractors and harvesters, enhancing efficiency during critical seasonal operations.
- Metalworking Machines:Metalworking Machines require precise lubrication for cutting tools and presses to maintain accuracy and extend component life.
- Textile Machinery:Textile Machinery uses automated systems to prevent wear on high-speed spindles and looms, reducing maintenance in production facilities.
Mining Equipment and Construction Machinery continue to dominate demand, while Agricultural Machinery presents significant underpenetrated growth.
End User:
End User segments delineate distinct customer types, each with unique procurement patterns and operational priorities for lubrication system adoption.
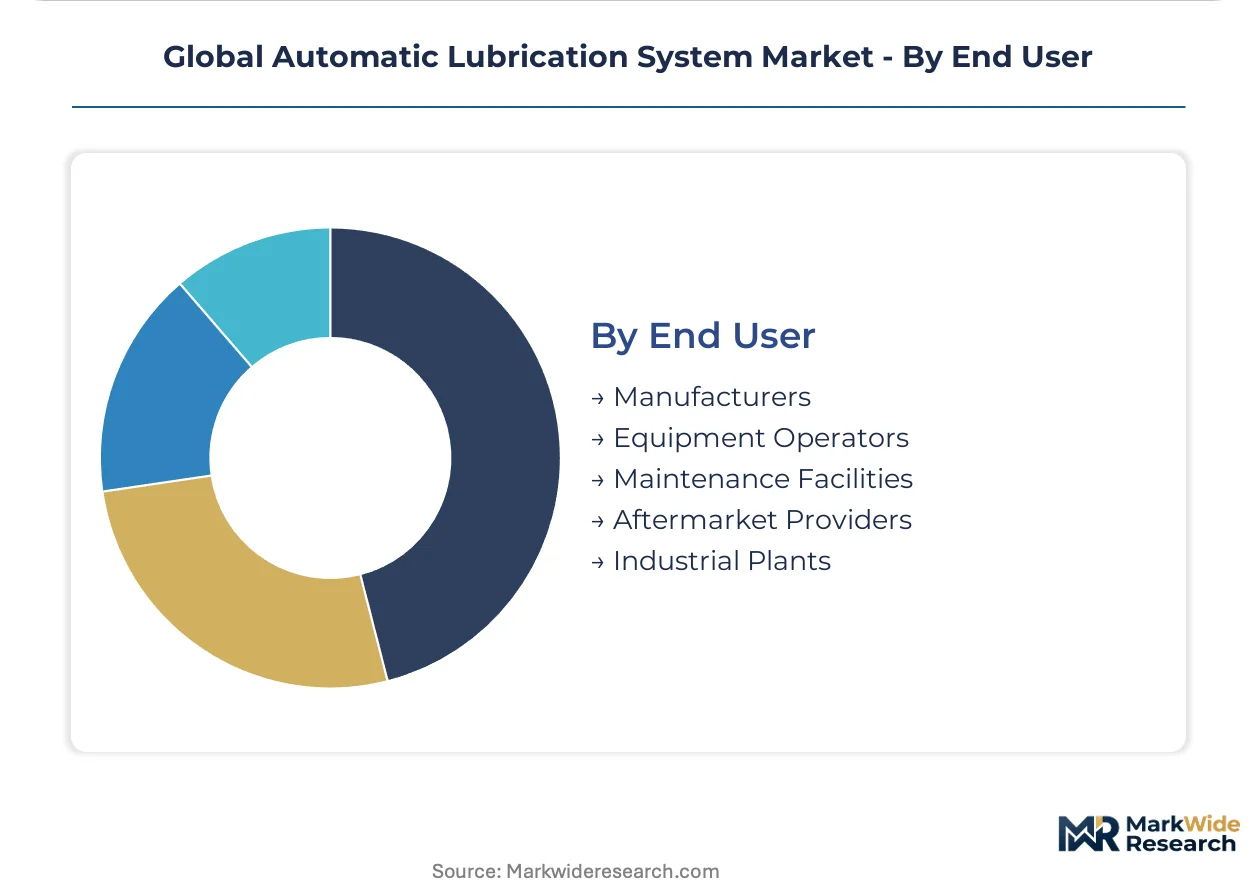
- Equipment Operators:Large-scale Equipment Operators prioritize total cost of ownership and operational uptime, favoring integrated, telematics-enabled solutions for their fleets in North America.
- Aftermarket Providers:Aftermarket Providers supply lubrication systems and services for existing equipment fleets, focusing on retrofit solutions and maintenance contracts for diverse industries globally.
- Manufacturers:Manufacturers integrate automatic lubrication systems as factory-fit options into new equipment, enhancing product value and reliability.
- Maintenance Facilities:Maintenance Facilities install and service lubrication systems, catering to equipment owners seeking specialized upkeep and repair.
- Industrial Plants:Industrial Plants deploy automated lubrication across various production lines to ensure continuous operation and reduce manual intervention.
Equipment Operators drive immediate demand for new installations, while Aftermarket Providers underpin sustained service revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetype concentration among large-scale equipment operators prioritizing total cost of ownership and operational uptime drives regional demand for automatic lubrication systems. Both industrializing economies and mature markets exhibit distinct procurement patterns. This global shift underpins the market's geographic expansion.
United States
United States demand arises from construction machinery and mining equipment, alongside stringent uptime requirements for critical assets. OSHA standards and EPA environmental rules compel adoption for safer operations and reduced lubricant spillage. Midwest manufacturing hubs adopt electro-mechanical systems for industrial plants, enhancing precision and efficiency across production lines.
India
India's market expansion is propelled by large-scale infrastructure projects and sustained demand for construction machinery. Government infrastructure programs, like the National Infrastructure Pipeline, incentivize automated solutions for new equipment to maximize operational availability. The Delhi-NCR region sees significant pneumatic system adoption for heavy-duty construction, valuing robustness and ease of maintenance.
Germany
Germany's industrial landscape drives demand for automatic lubrication in precision metalworking facilities and diverse industrial plants. The EU's Machinery Directive and CE marking standards influence system specifications for enhanced safety and regulatory compliance. Bavaria's automotive and machinery sectors specify progressive systems for complex operations, ensuring component longevity and performance.
China
China's construction machinery and mining equipment sectors fuel substantial demand for automated lubrication solutions across vast industrial operations. MEE environmental standards and GB standards for machinery encourage the integration of contained, automated systems to prevent leakage. The Yangtze River Delta region integrates electro-mechanical solutions into advanced manufacturing, boosting operational efficiency and data visibility.
Australia
Australia's extensive mining operations create a significant need for automated lubrication systems on haul trucks and excavators working in remote areas. State-level mining safety regulations and environmental protection acts mandate reliable equipment operation and strict spill prevention. Western Australia's iron ore mines deploy dual-line systems to ensure continuous operation in challenging environments, minimizing costly downtime.
Global Automatic Lubrication System Market Key Industry Players
Player mix skews toward specialized component manufacturers and integrated solution providers, creating a tiered market structure. This differentiation arises between offerings for cost-sensitive applications and those demanding advanced, performance-driven systems with telematics capabilities. Strategic archetypes include fluid-handling specialists, OEM partners, and comprehensive lubrication system integrators focusing on end-to-end solutions for operational efficiency. Dominant competitive moves involve portfolio diversification, strategic partnerships, and deep integration with IIoT platforms to enhance value propositions and prove return on investment.
Within the integrated solution provider segment, SKF Lubrication Systems leverages its extensive bearing and industrial portfolio, anchoring the premium end for comprehensive offerings that span mechanical and digital interfaces. Graco Inc. occupies a position as a specialist in robust fluid-handling components, particularly for heavy-duty construction and mining equipment, emphasizing durability and reliability in challenging environments. Groeneveld-BEKA further exemplifies the OEM partnership archetype, positioning its systems as factory-fit options with major vehicle manufacturers to ensure seamless integration and immediate operational efficiency upon deployment.
| Leading Market Players |
|---|
| Bijur Delimon International |
| DropsA USA, Inc. |
| SKF Lubrication Systems |
| Cenlub Systems |
| Trico Corporation |
| Lincoln Industrial |
| Groeneveld-BEKA |
| H-T-L perma |
| Graco Inc. |
| Others |
Cost & Logistics Intelligence
The increasing adoption of synthetic lubricants over conventional mineral oils reshapes supply geography and pricing economics simultaneously. This shift drives demand for specialized formulation inputs while enabling longer service intervals for automated systems.
Pricing Analysis
The technology-generation pricing gap between basic single-line systems and advanced IIoT-integrated solutions defines market pricing. Value-based pricing dominates for complex, telematics-enabled systems, while per-unit transactional models prevail for simpler components. Brand premium from established players like SKF and enhanced after-sales service drive differentiation. Pricing pressure stems from the availability of low-cost manual greasing methods, making smaller operators highly price-sensitive compared to large equipment operators prioritizing total cost of ownership.
Supply Chain Analysis
Inbound logistics costs, particularly across key Asia-Europe trade lanes, influence component sourcing for automatic lubrication systems. Geographic supply concentrates in industrial hubs like Germany for precision components and China for cost-effective manufacturing. The market relies on specialized pumps, sensors, and control units as key dependencies; single-source vulnerability for advanced electronic components poses a structural risk. Distribution runs through direct sales channels to OEMs and a robust aftermarket network of distributors and service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic lubrication system market is at a platform-economics inflection, driven by the increasing interoperability requirements with OEM telematics platforms. This shift transforms standalone devices into integral components of broader asset management ecosystems.
For Market Incumbents: Compound existing channel strengths by investing in IIoT integration capabilities to counter emerging digital-first competitors. Diversify portfolio offerings to include tailored solutions for underpenetrated segments like agricultural machinery. The threat of commoditization for basic systems necessitates a focus on high-margin, value-added services. R&D in AI-driven predictive maintenance algorithms serves as a critical lever.
For New Entrants and Emerging Players: Certification fast-track programs, particularly for adherence to EU's Machinery Directive or OSHA standards, offer a market entry point. Target the agricultural mechanization segment in markets like Brazil with cost-effective, battery-operated solutions. Focus on developing modular retrofit kits for legacy equipment lacking native digital interfaces. A direct-to-operator sales model emphasizing rapid ROI through uptime improvements can gain traction.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors technology-agnostic integrators capable of bridging mechanical hardware with digital platforms. Long-term viability depends on solutions that reduce total cost of ownership for large equipment operators. Acquisition targets should include software firms specializing in predictive analytics or sensor manufacturers. Watch for the widespread adoption of universal communication protocols as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| IIoT Platform Integration | Connects lubrication systems with broader asset management platforms for predictive maintenance. |
| OEM Partnership Expansion | Secures factory-fit positions with major construction and mining equipment manufacturers globally. |
| Aftermarket Service Network Buildout | Provides installation and maintenance support for retrofit solutions across diverse industrial fleets. |
| Specialized Sensor Development | Enhances precision and data collection for single-point lubricators in critical space-constrained applications. |
| Renewable Energy Sector Focus | Tailors automated systems for wind turbine pitch and yaw bearings in remote and challenging environments. |
Research Approach
A standing panel of maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads provided ongoing calibration for market trends. This approach combined in-depth primary interviews with industry stakeholders and rigorous secondary validation. Secondary data sources included equipment manufacturer reports, industry association publications, and regulatory body guidelines. Both bottom-up market sizing and top-down revenue analysis were triangulated for accuracy.
Outputs were validated against external benchmarks, ensuring consistency across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional deployment. Compound annual growth rates were derived from historical trends and projected market drivers. Key forecast inputs included infrastructure spending projections and heavy equipment sales volumes.
Decision-makers should treat outputs as directional under base assumptions regarding global economic stability and regulatory continuity; material deviation would warrant model refresh. Forecasts reflect these assumptions, but significant shifts in infrastructure investment or environmental mandates could alter projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Asia Pacific Automotive AHSS Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
Australia Automotive Pneumatic Actuators Market
Automotive Components
Automotive Brake System and Components Market
Automotive Components
Automotive Towbar Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
United States Automotive Pneumatic Actuators Market
Automotive Components
Global Automotive Condenser Market
Automotive Components
Automotive Cast Iron Cylinder Head Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Europe Automotive Glass Market
Automotive Components
Automotive Hubcaps Market