
 Automotive Gudgeon Pin Market | 2026-2036
Automotive Gudgeon Pin Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Gudgeon Pin Market Outlook
Aftermarket distribution for automotive gudgeon pins is fragmenting as regional distributors lose ground to direct OEM procurement platforms and specialized engine-component e-commerce channels. MAHLE GmbH leverages its integrated forging and machining footprint to sustain supply agreements with European and Asian OEM powertrain divisions. Rheinmetall Automotive competes through precision surface-treatment capabilities that extend pin fatigue life under high-combustion-pressure regimes. Shriram Pistons & Rings Ltd. anchors South Asian demand with localized steel sourcing and heat-treatment facilities serving domestic motorcycle and three-wheeler engine builders.
An automotive gudgeon pin is a hardened cylindrical steel or alloy component, typically 15–60 mm in diameter, that links the piston to the connecting rod via a floating or semi-floating interface within the piston boss. Its primary function is to transmit combustion force from the piston crown to the crankshaft while maintaining positional stability under cyclic thermal and mechanical loads exceeding 200 MPa. Steel piston pins occupy the dominant share of value given their tensile strength suitability for heavy-duty diesel and turbocharged gasoline engines, though titanium variants are gaining traction in motorsport and premium lightweight powertrains where reciprocating mass reduction yields measurable efficiency gains. Engine Manufacturers represent a concentrated demand node, as captive pin procurement within integrated powertrain assembly operations limits third-party supplier access.
EPA emission standards in the United States and Euro 7 preparatory frameworks advanced by EMA and national type-approval authorities in Europe are tightening allowable tolerances on piston-to-pin clearance, directly elevating precision grinding and surface-finish requirements. India's BIS and ARAI certification pathways for Bharat Stage VI Phase II compliance are similarly pressuring domestic suppliers to adopt case-hardened alloy grades with documented fatigue-life traceability. Stakeholders must monitor diverging regional test-cycle protocols and alloy-recyclability mandates to determine whether regional forging investments or cross-border premium-grade exports offer superior returns.
Market Dynamics
Emission standard convergence across Bharat Stage VI, Euro 7 preparatory frameworks, and EPA Tier 3 is compressing piston-to-pin clearance tolerances, forcing simultaneous upgrades in forging precision, surface treatment, and alloy traceability across supplier bases.
Growth Catalysts
- Hardened Steel Alloy Adoption:Case-hardened chromium-molybdenum grades with documented fatigue-life certification are displacing through-hardened alternatives in turbocharged gasoline and heavy-duty diesel applications as Bharat Stage VI Phase II and Euro 7 frameworks elevate durability requirements.
- Light Commercial Vehicle Expansion:Indian and Southeast Asian OEM powertrain divisions are scaling orders for precision-ground piston pins to meet commercial fleet uptime demands under tightening emission enforcement by ARAI and national type-approval authorities.
- Titanium Lightweighting:Motorsport and premium passenger vehicle engine builders are specifying titanium gudgeon pin variants to reduce reciprocating mass, yielding measurable thermal efficiency gains in high-RPM powertrains.
Market Restraints
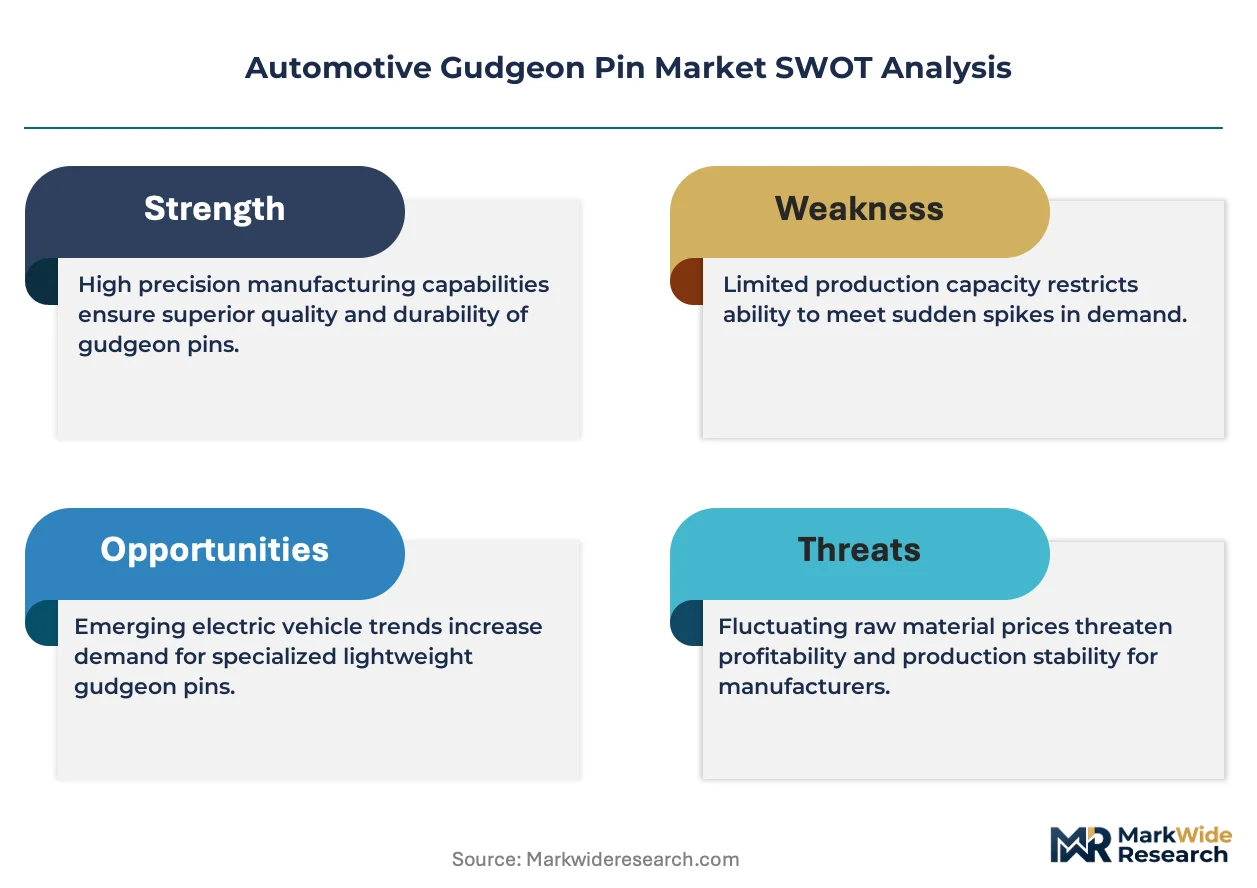
- Alloy Scrap Volatility:Secondary steel and specialty alloy scrap pricing fluctuations compress margin predictability for forging operations dependent on virgin and recycled feedstock blends.
- Supply Concentration Risk:Premium vacuum-melted steel billet availability clusters among German and Japanese metallurgical suppliers, exposing downstream precision machiners to single-source vulnerability.
- Technical Substitution Ceiling:Carbon fiber composite connecting rod technologies under development by aerospace-adjacent materials firms threaten long-term displacement of steel-intensive small-bore engine architectures.
Strategic Opportunities
- Indonesian Motorcycle OEM Penetration:Domestic two-wheeler and three-wheeler engine builders lack captive forging capacity, creating white space for precision pin suppliers with localized heat-treatment and grinding investments.
- E-Commerce Component Platforms:Specialized engine-part marketplaces are disintermediating traditional aftermarket distributors, enabling direct supplier-to-rebuilder relationships with documented batch traceability.
- EU Green Deal Material Passport Mandates:Alloy recyclability documentation requirements will favor suppliers with closed-loop scrap recovery and certified carbon-footprint accounting, penalizing opaque Asian import streams.
Industry Challenges
- Precision Grinding Talent Scarcity:CNC surface-finish specialists capable of maintaining sub-micron cylindricity on hardened steel are concentrated among aging workforces in Stuttgart and Nagoya manufacturing clusters.
- Multi-Standard Certification Burden:Simultaneous BIS, ARAI, and EPA compliance timelines force redundant testing protocols on alloy grades, extending product qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Gudgeon Pin Market |
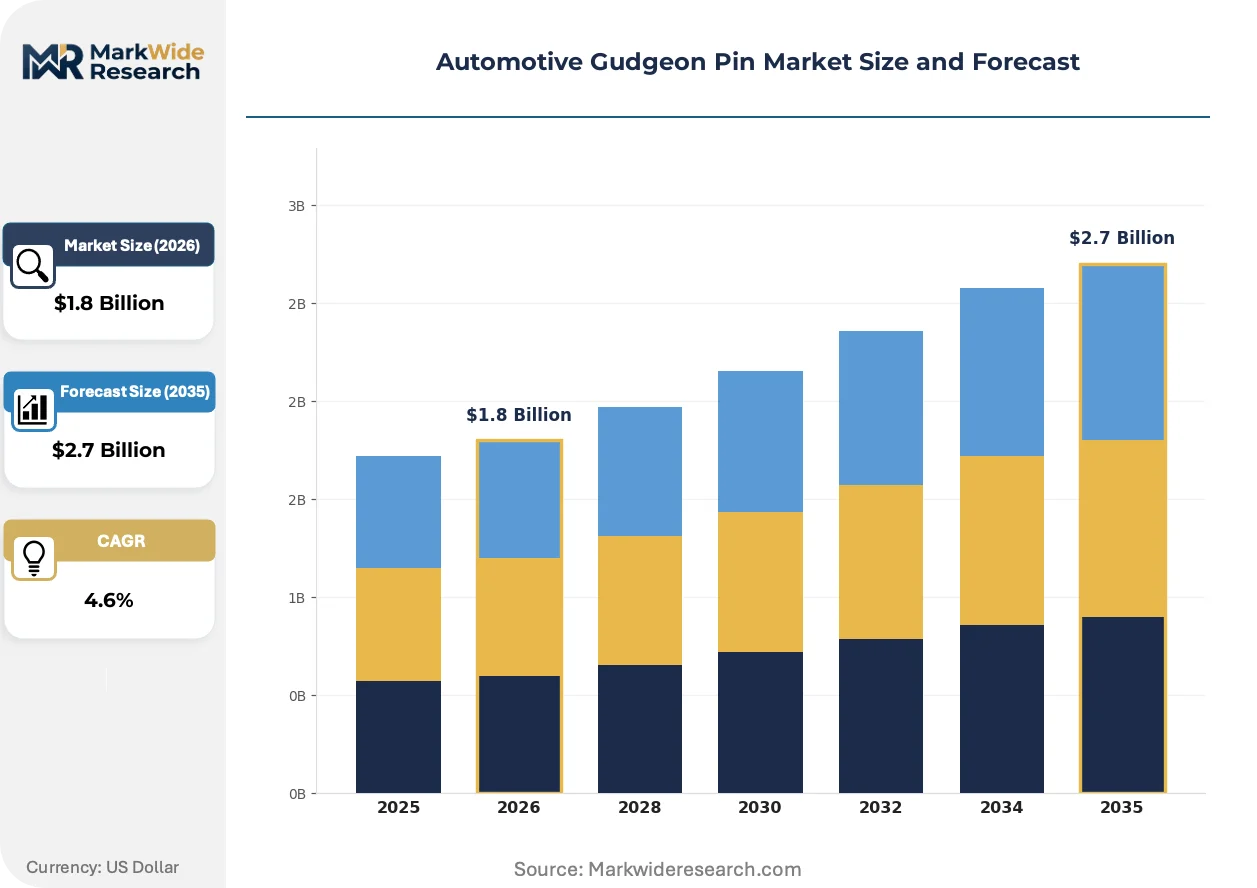
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston Pins, Connecting Rod Pins, Engine Assembly Pins, Others Material: Steel, Aluminum, Titanium, Composite End User: OEMs, Aftermarket Providers, Engine Manufacturers, Vehicle Assemblers Size: Small, Medium, Large, Extra Large |
| Companies Covered | Shriram Pistons & Rings Ltd., Hitachi Astemo, MAHLE GmbH, Art Metal, Bohai Piston, Rheinmetall Automotive, Aisin Seiki, Burgess-Norton, Tenneco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Gudgeon Pin Market Strategic Shifts
Surface metrology and alloy traceability systems are digitizing quality assurance workflows, compressing the gap between forging floor data and OEM procurement specifications while enabling predictive maintenance integration.
Laser-induced breakdown spectroscopy (LIBS) is digitizing real-time alloy composition verification at forging lines, replacing offline laboratory spectrometry. Tier-1 suppliers in Stuttgart and Shanghai are deploying LIBS inline to eliminate batch quarantine delays. This technology is digitizing supplier-OEM data exchange, enabling immediate certificate-of-analysis transmission and reducing incoming inspection overhead.
EPA Tier 3 and Euro 7 preparatory frameworks are mandating documented piston-pin fatigue-life traceability from melt to installation. OEM powertrain divisions now require ISO 9001 and IATF 16949-aligned material passports with carbon-intensity disclosures. Heavy-duty diesel engine manufacturers in Germany and the United States are consolidating supplier lists to those with integrated forging-machining-metrology footprints capable of automated compliance reporting.
Direct OEM procurement platforms are displacing traditional aftermarket distributors for replacement piston pins in commercial vehicle segments. Fleet maintenance operators in India and Brazil are sourcing through manufacturer-direct portals with VIN-matched specification lookup, bypassing regional parts wholesalers. This channel migration is most visible among long-haul trucking operators requiring documented warranty compliance for emission system integrity.
Automotive Gudgeon Pin Market Segmentation
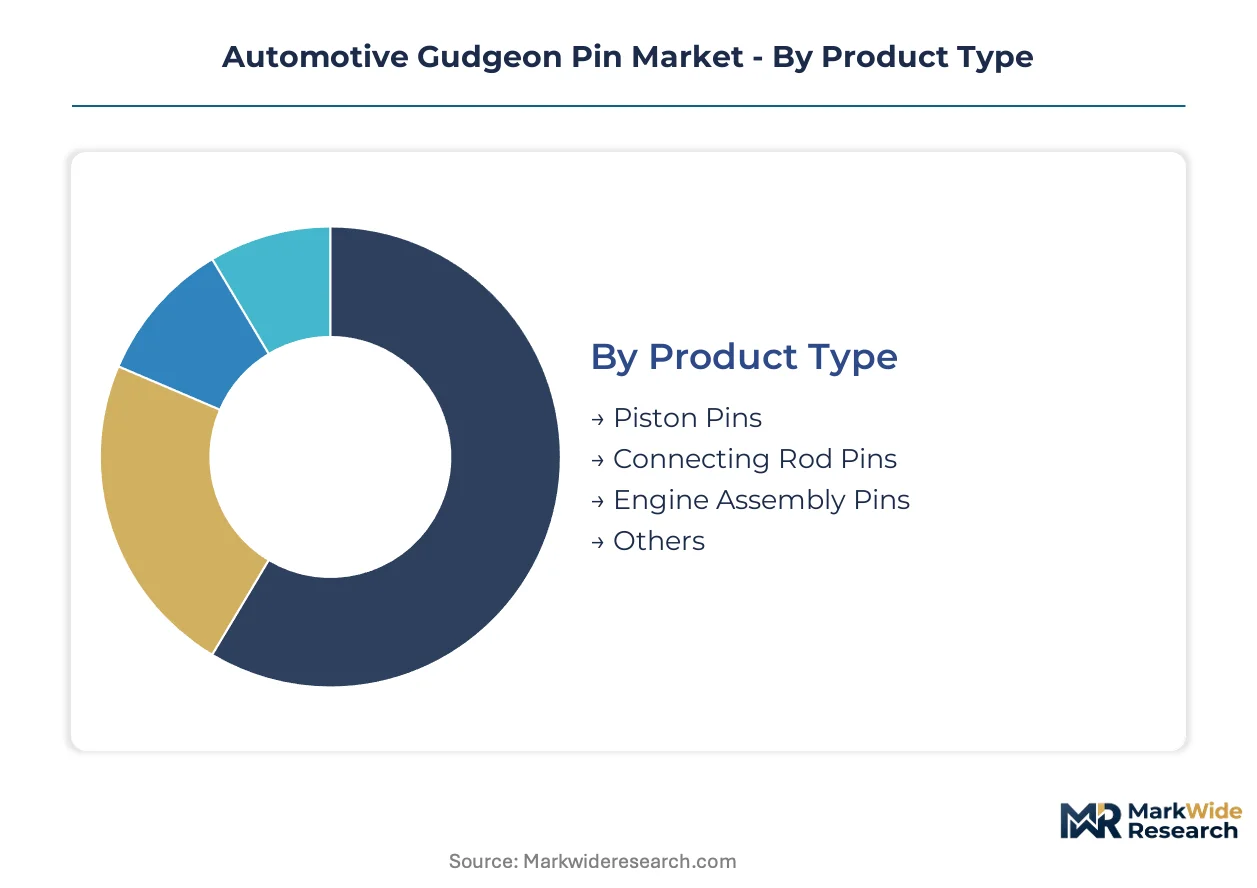
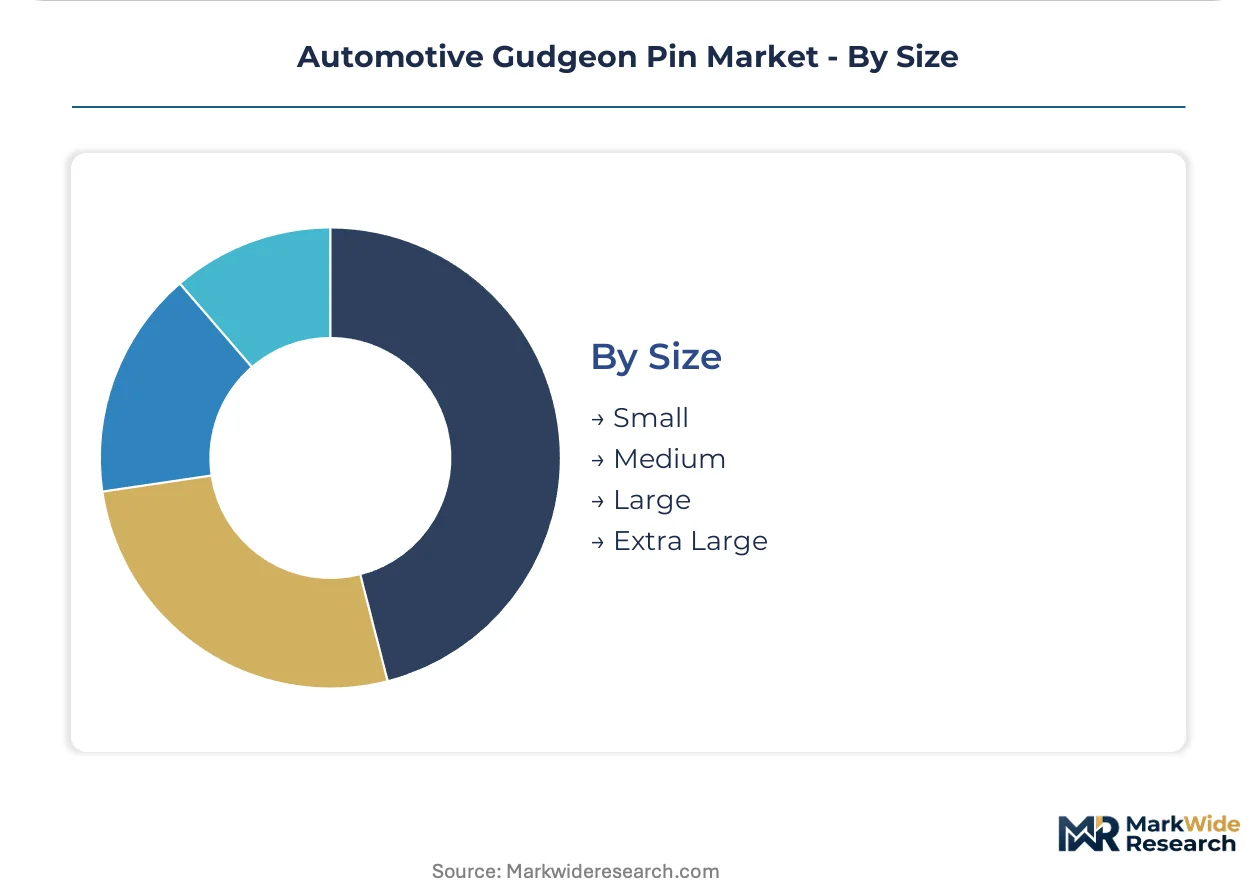
Segmentation in the automotive gudgeon pin market reveals divergent service intensity and margin profiles across material grades and procurement channels. Suppliers must align forging investments and inventory strategies to the distinct technical certification burdens and replacement cycle dynamics of each segment.
Product Type:
After-sales-service intensity varies sharply across pin categories, with replacement frequency and technical support demands dictating distributor versus direct-channel economics.
- Piston Pins:These hardened cylindrical components, typically 15–60 mm in diameter, transmit combustion force from piston crown to crankshaft under cyclic loads exceeding 200 MPa. Indian and Southeast Asian light commercial vehicle OEMs are scaling orders for precision-ground variants as Bharat Stage VI enforcement tightens durability tolerances.
- Connecting Rod Pins:Interface components linking the connecting rod small end to the gudgeon pin bore, engineered for floating or semi-floating fitment. German powertrain divisions specify vacuum-melted alloy grades with documented fatigue-life traceability under Euro 7 preparatory frameworks.
- Engine Assembly Pins:Specialized fasteners used during powertrain build processes rather than in-service operation. Captive procurement by integrated engine manufacturers limits third-party supplier access to this segment.
- Others:Niche variants including timing gear pins and auxiliary shaft connectors serving specific engine architectures.
By volume, Piston Pins leads. By growth pace, Connecting Rod Pins is ahead.
Material:
Cost tier stratification separates commodity steel grades from premium alloys, with certification documentation requirements widening the pricing spread.
- Steel:Case-hardened chromium-molybdenum grades dominate heavy-duty diesel and turbocharged gasoline applications. Chinese engine manufacturers drive volume demand while German suppliers anchor premium alloy specifications with integrated forging-machining footprints.
- Titanium:Motorsport and premium passenger vehicle builders specify these variants to reduce reciprocating mass, yielding measurable thermal efficiency gains in high-RPM powertrains where mass reduction translates directly to fuel economy improvement.
- Aluminum:Lightweight alternatives for small-bore gasoline engines in cost-sensitive motorcycle and three-wheeler segments across South Asia.
- Composite:Experimental carbon-fiber-reinforced formulations under evaluation by aerospace-adjacent materials firms for potential long-term displacement of metal-intensive architectures.
Steel commands the revenue base. Titanium is expanding most quickly.
End User:
Customer type determines procurement modality, with integrated powertrain operations contrasting against fragmented aftermarket rebuild channels.
- OEMs:Original equipment manufacturers specify pins during new vehicle powertrain design, requiring IATF 16949-aligned material passports with carbon-intensity disclosures. EPA Tier 3 and Euro 7 frameworks are consolidating supplier lists to those with automated compliance reporting capabilities.
- Engine Manufacturers:Captive forging operations at integrated powertrain assemblers limit external supplier penetration. Bharat Stage VI Phase II compliance is pressuring Indian domestic suppliers to adopt case-hardened alloy grades with documented fatigue-life traceability.
- Aftermarket Providers:Distributors and rebuilders serving commercial fleet maintenance, increasingly disintermediated by direct OEM procurement platforms with VIN-matched specification lookup.
- Vehicle Assemblers:Final assembly operations sourcing pins for engine installation lines, typically under long-term supply agreements with metallurgical certification requirements.
OEMs dominate order value. Aftermarket Providers are gaining share fastest through e-commerce channel migration.
Size:
Application scale drives dimensional requirements, with commercial vehicle duty cycles demanding larger bore configurations and correspondingly higher alloy specifications.
- Small:Motorcycle and small-displacement passenger car engines, typically 15–25 mm diameter. Indonesian two-wheeler OEMs lack captive forging capacity, creating white space for localized heat-treatment investments.
- Medium:Light commercial vehicle and mid-size passenger car applications, 25–40 mm range. Indian OEM powertrain divisions are scaling orders to meet commercial fleet uptime demands under ARAI enforcement tightening.
- Large:Heavy-duty diesel engines for long-haul trucking and construction equipment, 40–55 mm diameter. Fleet operators in Brazil are sourcing through manufacturer-direct portals requiring documented warranty compliance.
- Extra Large:Marine, locomotive, and stationary power applications exceeding 55 mm, often with custom alloy specifications and extended qualification cycles.
Medium size leads in unit volume. Extra Large shows the steepest expansion trajectory on a value-per-unit basis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through dual carbon goals and GB standards enforcement that compress piston-to-pin tolerances. German KBA type-approval pathways under Euro 7 preparatory frameworks elevate alloy traceability requirements. Indian ARAI certification for Bharat Stage VI Phase II compliance is pressuring domestic suppliers toward case-hardened grades.
China
Engine manufacturers in Shanghai and Shenyang drive volume demand for precision-ground steel pins. MIIT's GB standards for emission compliance tighten surface-finish specifications on turbocharged gasoline architectures. Yangtze River Delta forging clusters are scaling vacuum-melted billet processing to meet OEM material passport requirements.
Germany
Stuttgart and Munich powertrain divisions specify premium chromium-molybdenum grades with documented fatigue-life certification. KBA's Euro 7 preparatory frameworks mandate automated compliance reporting from integrated forging-machining suppliers. Baden-Württemberg metallurgical facilities anchor European vacuum-melted steel billet availability.
India
Maharashtra and Tamil Nadu light commercial vehicle OEMs are scaling orders for hardened steel piston pins. ARAI's Bharat Stage VI Phase II enforcement tightens durability tolerances on commercial fleet components. Pune-based heat-treatment facilities serve domestic motorcycle and three-wheeler engine builders lacking captive forging capacity.
United States
EPA Tier 3 standards compress piston-to-pin clearance tolerances for heavy-duty diesel applications. Long-haul trucking operators source replacement pins through manufacturer-direct portals requiring documented warranty compliance. Detroit powertrain engineering clusters consolidate supplier lists to those with automated fatigue-life traceability systems.
Indonesia
Domestic two-wheeler and three-wheeler engine builders lack captive forging capacity, creating procurement gaps. The country's national type-approval authority tightens emission enforcement on motorcycle powertrains. Jababeka industrial estates near Jakarta attract precision pin suppliers with localized heat-treatment investment incentives.
Automotive Gudgeon Pin Market Competitive Environment
Integrated metallurgical specialists and precision machining houses split the market along capability lines. The supplier base concentrates among tier-1 forging operations with in-house surface treatment and captive vacuum-melted billet sourcing. Three archetypes dominate: German-Japanese premium alloy specialists, Chinese volume-scale fabricators, and South Asian localized heat-treatment providers. Competitive moves center on backward integration into steel billet supply and cross-border certification investments for multi-standard compliance.
Among German-based GmbH-structured suppliers, MAHLE GmbH and Rheinmetall Automotive exemplify the premium-alloy archetype with integrated forging-machining footprints. Hitachi Astemo and Aisin Seiki represent Japanese precision-component specialists with established OEM powertrain relationships. Shriram Pistons & Rings Ltd. anchors the South Asian localized-supply archetype serving domestic motorcycle and commercial vehicle engine builders.
| Leading Market Players |
|---|
| Shriram Pistons & Rings Ltd. |
| Hitachi Astemo |
| MAHLE GmbH |
| Art Metal |
| Bohai Piston |
| Rheinmetall Automotive |
| Aisin Seiki |
| Burgess-Norton |
| Tenneco Inc. |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta freight corridors connecting Shanghai forging clusters to Stuttgart powertrain divisions transmit alloy scrap volatility directly into downstream price differentiation. Cost compression in vacuum-melted billet procurement is forcing German suppliers to widen spreads between configured-to-order premium grades and standard case-hardened alternatives.
Pricing Analysis
The customization-premium spread separates IATF 16949-certified material passport grades from commodity through-hardened alternatives. Pricing stratifies across fatigue-life documentation tiers, with Euro 7-aligned traceability commanding substantial premia over Bharat Stage VI baseline certification. Cost compression in chromium-molybdenum scrap feeds is intensifying margin pressure on mid-tier forging operations. Fleet operators in long-haul trucking segments exhibit highest price sensitivity, while motorsport engine builders show minimal elasticity for titanium lightweighting variants.
Supply Chain Analysis
Upstream vacuum-melted steel billet availability clusters among German and Japanese metallurgical suppliers, with Chinese Yangtze River Delta forging operations scaling secondary processing capacity. The supply chain draws from specialty alloy scrap streams, virgin chromium-molybdenum feedstock, and precision grinding consumables. Single-source vulnerability in premium billet procurement exposes downstream machiners to disruption. Distribution runs through direct OEM procurement platforms disintermediating traditional aftermarket wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber composite connecting rod technologies threaten long-term displacement of steel-intensive architectures, forcing incumbents to fortify positions through certification depth and captive metallurgical capabilities.
For Market Incumbents: Build fatigue-life documentation moats through integrated LIBS-enabled alloy verification and automated material passport generation. Secure backward integration into vacuum-melted billet supply through offtake agreements with Baden-Württemberg metallurgical facilities. Carbon fiber substitution risk demands accelerated case-hardening process R&D to extend steel durability thresholds. For New Entrants and Emerging Players: Indonesian two-wheeler and three-wheeler engine manufacturing presents accessible white space given absent captive forging capacity among domestic OEMs. Target Jababeka industrial estate localization incentives for heat-treatment and precision grinding investments. E-commerce component platforms enable direct supplier-to-rebuilder relationships bypassing established distribution hierarchies. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized precision machining divisions capable of IATF 16949 pivot. Long-term viability hinges on emission standard durability rather than commodity volume exposure. Monitor carbon fiber composite connecting rod development milestones as inflection indicator for steel displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum-Melted Billet Supply | Captive metallurgical sourcing insulates German suppliers from Japanese single-source vulnerability. |
| LIBS-Enabled Inline Alloy Verification Deployment | Real-time spectroscopy eliminates batch quarantine delays for Euro 7 material passport compliance. |
| Indonesian Heat-Treatment Facility Localization | Jababeka estate incentives capture motorcycle OEM demand lacking captive forging capacity. |
| Direct OEM Procurement Platform Development | VIN-matched specification lookup displaces aftermarket distributors for commercial fleet segments. |
| Carbon Fiber Substitution R&D Partnership | Aerospace materials firm collaboration monitors displacement threat to small-bore steel architectures. |
Study Parameters
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and heat-treatment facility managers anchored the qualitative base. Secondary validation drew from MIIT GB standards documentation, KBA type-approval filings, ARAI certification pathways, EPA Tier 3 regulatory texts, and vehicle production databases. Bottom-up forging capacity assessments and top-down emission standard compliance timelines were triangulated to constrain demand estimates.
Scenario-bracketing framed low, baseline, and high emission enforcement trajectories across the projection horizon. Segmentation dimensions modeled encompass material grade tier, end-use application, procurement channel structure, and regional regulatory cluster. CAGRs were derived from alloy intensity per powertrain architecture and fleet replacement cycle dynamics. Forecast inputs incorporated Bharat Stage VI Phase II rollout pacing and Euro 7 preparatory framework advancement.
Macroeconomic conditions sit as an overlay; deviation in alloy scrap pricing volatility and commercial vehicle production schedules would shift the trajectory. Forecasts reflect assumptions regarding emission standard enforcement continuity and vacuum-melted billet supply stability. Material shifts in carbon fiber composite connecting rod commercialization timelines or EPA Tier 4 pre-emptive advancement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
Automotive Wiper Blades Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Automated Lubrication Systems Market
Automotive Components
Automotive Transaxle Market
Automotive Components
Automotive Tie Rod Market
Automotive Components
Automotive Resonator Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
Global Automotive Sun Visor Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Automotive Connecting Rod Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Automotive Carbon Fiber Components Market