
 Torque Vectoring Market | 2026-2036
Torque Vectoring Market Size, Share, and Industry Trends Forecast 2026-2036
Torque Vectoring Market Outlook
Aftermarket service revenue is reconfiguring toward software-enabled calibration and predictive maintenance contracts as active torque vectoring systems proliferate. Continental AG leverages its integrated brake-and-driveline portfolio to anchor high-margin service agreements across European passenger vehicle platforms. Robert Bosch GmbH sustains technology leadership in sensor fusion architectures that enable real-time torque redistribution. GKN Automotive specializes in eDrive torque vectoring units, positioning its manufacturing scale to capture fleet electrification programs.
Torque vectoring denotes the active differential distribution of torque between individual wheels to enhance traction, stability, and cornering performance through electronically controlled clutch packs or motor torque modulation. The technology operates via wheel-speed sensors, yaw-rate sensors, and powertrain control modules that calculate optimal torque split in milliseconds, primarily serving passenger vehicle dynamics and commercial vehicle traction management. Active torque vectoring commands premium positioning as automakers integrate it with ADAS and electric powertrains, while electronic differential architectures gain share as rear-wheel drive performance vehicles adopt motor-based torque biasing. All-wheel drive technology retains volume dominance across snow-belt and premium segments, though hybrid drive configurations represent the fastest-expanding category as plug-in hybrids demand seamless front-rear torque coordination.
NHTSA vehicle stability requirements and the EU's General Safety Regulation mandate advanced chassis control systems, directly expanding addressable volume for electronic torque vectoring in new vehicle certifications. EPA corporate average fuel economy standards and China's MIIT new energy vehicle mandates favor electrified drivelines where motor-based torque vectoring replaces mechanical losses with software-defined control. Stakeholders must monitor regulatory harmonization between NHTSA, ECHA, and SAMR on functional safety standards for steer-by-wire and brake-by-wire integration, as these interfaces determine torque vectoring system architecture decisions.
Market Dynamics
Electrification of driveline architectures is compressing mechanical component counts while expanding software-defined control surfaces, forcing suppliers to reconstitute around firmware competencies and motor integration capabilities rather than precision machining heritage.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Stringent efficiency mandates favor electrified drivelines where motor-based torque vectoring eliminates mechanical losses inherent in clutch-pack differentials.
- China's MIIT new energy vehicle mandates:Production quotas for battery-electric and plug-in hybrid platforms accelerate adoption of eDrive torque vectoring units across domestic OEM portfolios.
- Wheel-speed sensor fusion architectures:Advances in yaw-rate sensing and powertrain control module processing speeds enable millisecond-level torque redistribution calculations that outperform hydraulic systems.
Market Restraints
- Semiconductor supply concentration:Dependence on Taiwan and South Korea for automotive-grade microcontrollers creates vulnerability in electronic torque vectoring module production schedules.
- Copper and rare earth magnet cost volatility:Permanent magnet synchronous motors in eDrive torque vectoring units face input price swings that compress module margins.
- Functional safety certification complexity:ISO 26262 ASIL-D requirements for steer-by-wire and brake-by-wire interfaces extend development timelines and qualification costs.
Strategic Opportunities
- India's PLI scheme for automotive manufacturing:Incentive structures for advanced automotive technology components attract torque vectoring system localization for export-oriented production.
- ADAS convergence with chassis control:Integration of torque vectoring with automated emergency steering and lane-keeping systems creates unified platform opportunities for Tier 1 suppliers.
- Predictive maintenance service contracts:Over-the-air calibration updates and prognostic algorithms enable recurring revenue streams that displace traditional component replacement cycles.
Industry Challenges
- Embedded software engineering scarcity:Shortage of engineers proficient in real-time control systems and motor control algorithms constrains development velocity for active torque vectoring programs.
- Legacy powertrain integration friction:Retrofitting electronic torque vectoring into existing internal combustion vehicle platforms requires extensive recalibration of stability control and ABS interfaces.
- Homologation timeline compression:Divergent NHTSA, ECHA, and SAMR functional safety interpretations force parallel certification tracks that duplicate validation expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Torque Vectoring Market |
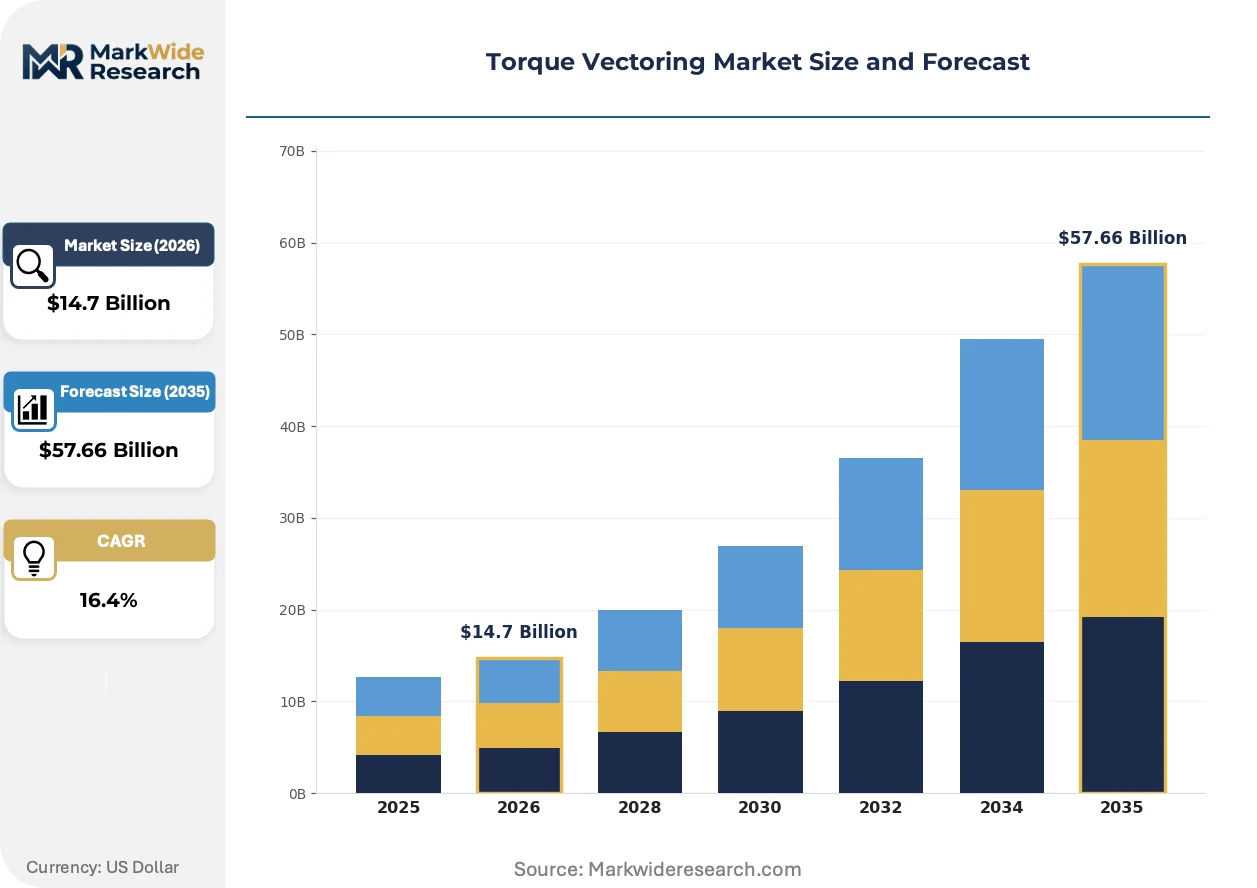
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $57.66 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Torque Vectoring, Passive Torque Vectoring, Electronic Differential, Mechanical Differential Technology: All-Wheel Drive, Rear-Wheel Drive, Front-Wheel Drive, Hybrid Drive End User: Automotive OEMs, Aftermarket Retailers, Fleet Operators, Racing Teams Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Performance Vehicles |
| Companies Covered | Continental AG, Robert Bosch GmbH, GKN Automotive, Magna International Inc., JTEKT Corporation, BorgWarner Inc., Dana Incorporated, Schaeffler AG, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Torque Vectoring Market Strategic Shifts
Software-defined vehicle architectures are dissolving traditional boundaries between powertrain, braking, and steering domains, creating unified chassis control platforms where torque vectoring functions migrate from discrete hardware modules to centralized compute stacks.
Dual-motor electric axle architectures are virtualizing the mechanical limited-slip differential by commanding independent torque outputs to left and right wheels through inverter-controlled permanent magnet motors. Premium electric vehicle platforms from Germany and China are adopting this topology at accelerating rates. The shift is virtualizing hardware supplier value toward motor-inverter software calibration capabilities.
The EU General Safety Regulation mandates advanced emergency lane-keeping and automated emergency steering systems that require precise yaw moment control through torque biasing. Vehicle manufacturers must certify chassis control systems under UN ECE R79 and R152 frameworks. European passenger vehicle platforms are responding by integrating torque vectoring with steer-by-wire actuators to satisfy combined stability and automation requirements.
Fleet procurement of electric commercial vehicles is compressing specification cycles as logistics operators prioritize total cost of ownership over upfront capital expenditure. Torque vectoring system vendors are adapting by unbundling hardware from software licensing and offering per-mile service agreements. This pattern is most visible in last-mile delivery electrification programs across Germany and the United States.
Torque Vectoring Market Segmentation
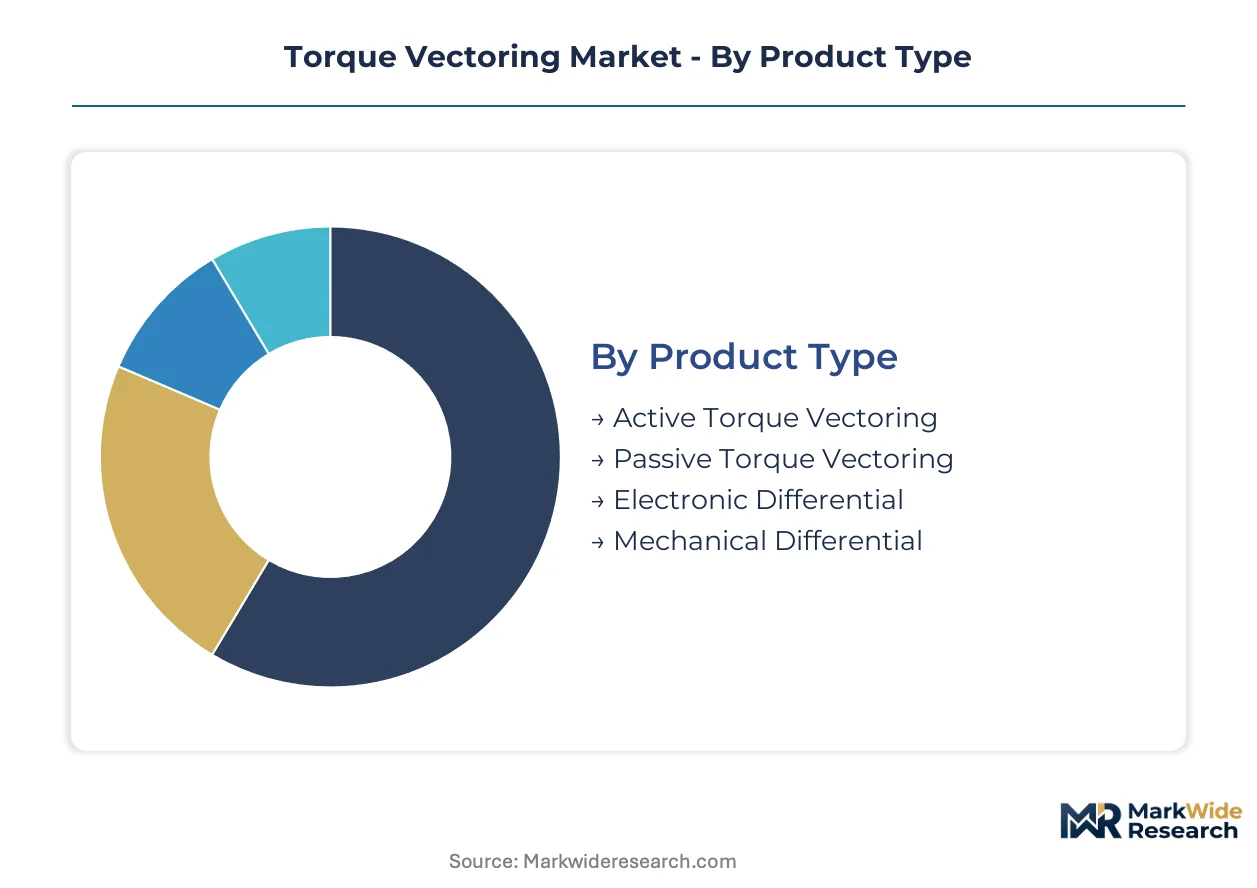
Torque vectoring architectures diverge sharply across cost tiers and electrification pathways, with electronic control systems displacing mechanical differentials in premium platforms while passive systems retain volume positions in cost-sensitive segments. Technology choices cascade through OEM procurement decisions, fleet electrification timelines, and regulatory compliance frameworks.
Product Type:
Cost tier stratification separates premium electronic architectures from legacy mechanical systems, with mid-market vehicles driving hybrid adoption curves.
- Active Torque Vectoring:Electronically controlled clutch packs or motor torque modulation enable millisecond-level torque redistribution between individual wheels. Demand concentrates in German and Chinese premium electric vehicle platforms where NHTSA stability mandates and EU General Safety Regulation compliance require precise yaw moment control.
- Electronic Differential:Software-defined torque biasing through integrated brake-and-driveline modules eliminates mechanical losses inherent in clutch-pack systems. Adoption accelerates across rear-wheel drive performance vehicles from United States and German OEMs seeking EPA fuel economy credits through driveline electrification.
- Passive Torque Vectoring:Mechanical limited-slip differentials with fixed torque bias ratios serve cost-sensitive vehicle segments.
- Mechanical Differential:Open or limited-slip designs without electronic intervention retain presence in emerging market vehicle platforms.
Active Torque Vectoring commands the established base. The steepest expansion runs through Electronic Differential.
Technology:
Application context determines driveline configuration, with snow-belt climates and performance positioning driving divergent technology selections.
- All-Wheel Drive:Full-time or on-demand torque distribution across all four wheels serves snow-belt United States markets and European premium segments. United States Great Lakes and Northeast corridor vehicle registrations sustain volume leadership, though hybrid drive architectures are gaining share fastest in China MIIT compliance-driven procurement.
- Hybrid Drive:Plug-in hybrid platforms demand seamless front-rear torque coordination through dual-motor eAxle configurations. China domestic OEM portfolios and German premium electrification programs concentrate demand, with MIIT production quotas and EU Green Deal tailpipe standards accelerating specification.
- Rear-Wheel Drive:Motor-based torque biasing through independent left-right motor control dominates performance vehicle development.
- Front-Wheel Drive:Transverse engine layouts with integrated torque vectoring differentials serve compact and mid-size vehicle segments.
All-Wheel Drive retains volume dominance. Hybrid Drive climbs the fastest as electrification mandates tighten.
End User:
Customer type segmentation reveals divergent procurement patterns, with fleet electrification compressing specification cycles and aftermarket revenue shifting toward software services.
- Automotive OEMs:Integrated chassis control procurement spans powertrain, braking, and steering domains as software-defined vehicle architectures consolidate compute stacks. German, Chinese, and United States production bases concentrate demand, with EPA corporate average fuel economy standards and China MIIT mandates dictating electrified driveline specifications.
- Fleet Operators:Last-mile delivery electrification programs across Germany and United States prioritize total cost of ownership over upfront capital expenditure. Per-mile service agreements and predictive maintenance contracts displace traditional component replacement cycles.
- Aftermarket Retailers:Software-enabled calibration and over-the-air update capabilities reconfigure service revenue models.
- Racing Teams:Motorsport homologation programs validate torque vectoring algorithms for production vehicle transfer.
Automotive OEMs anchor procurement volume. Fleet Operators represent the fastest-expanding customer category.
Application:
Vehicle category determines performance requirements, with passenger dynamics and commercial traction management imposing distinct control strategies.
- Passenger Vehicles:ADAS convergence with chassis control integrates torque vectoring with automated emergency steering and lane-keeping systems. European UN ECE R79 and R152 certification requirements mandate yaw moment control precision, driving integration with steer-by-wire actuators.
- Performance Vehicles:Dual-motor electric axle architectures virtualize mechanical limited-slip differentials through independent left-right torque commands. German and Chinese premium electric platforms adopt this topology at accelerating rates, with motor-inverter software calibration capabilities displacing hardware supplier value.
- Commercial Vehicles:Electric truck and bus platforms require traction management for variable load conditions.
- Off-Road Vehicles:Terrain-adaptive torque distribution serves construction, agriculture, and recreational segments.
Passenger Vehicles command the established base. Performance Vehicles gain share fastest through electrification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across production bases. Chinese OEMs prioritize cost-optimized eDrive modules for mass-market electrification, while German manufacturers absorb premium positioning for performance calibration. United States demand splits between EPA compliance-driven fleet procurement and snow-belt consumer preference for all-wheel traction.
China
Domestic OEMs dominate procurement volume through MIIT production quotas for battery-electric platforms. The country's dual carbon goals accelerate eDrive torque vectoring adoption across BYD, NIO, and XPeng vehicle lines. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou concentrate GKN Automotive and ZF Friedrichshafen joint venture production for export-oriented supply.
Germany
Premium electrification programs from BMW, Mercedes-Benz, and Porsche drive specification for active torque vectoring with steer-by-wire integration. EU Green Deal tailpipe standards and UN ECE R79 certification requirements mandate yaw moment control precision. Baden-Württemberg and Bavaria host Continental AG and Robert Bosch GmbH development centers for chassis control firmware.
United States
EPA corporate average fuel economy standards push Detroit Three OEMs toward electrified drivelines with motor-based torque biasing. NHTSA vehicle stability mandates expand addressable volume for electronic architectures. Michigan and Ohio manufacturing corridors anchor Magna International and BorgWarner production for domestic light truck and performance vehicle platforms.
Japan
Keiretsu procurement patterns favor JTEKT Corporation and Denso integrated chassis systems for Toyota and Nissan electrification roadmaps. METI carbon neutrality targets accelerate hybrid drive torque coordination specifications. Aichi Prefecture and Kanagawa manufacturing belts concentrate motor-inverter calibration capabilities for export to Southeast Asian assembly plants.
South Korea
Hyundai-Kia electrification platforms specify dual-motor eAxle architectures with independent left-right torque control. Ministry of Trade, Industry and Energy battery-electric subsidies expand addressable volume for domestic suppliers. Gyeonggi-do and Ulsan production complexes host Samsung SDI and LG Energy Solution battery integration with torque vectoring module packaging.
Torque Vectoring Market Competitive Environment
Capability concentration sits with Tier 1 chassis integrators possessing brake-driveline portfolios and firmware competencies; scale advantage sits with diversified automotive suppliers with multi-OEM contract coverage. The structure tiers between premium calibration specialists and volume module fabricators. Dominant archetypes include integrated brake-system vendors, eDrive unit specialists, and sensor fusion architects. Competitive moves center on strategic partnerships for software-defined vehicle architectures and geographic expansion through joint ventures in Chinese production clusters.
Within the integrated chassis control tier, Continental AG and Robert Bosch GmbH anchor European premium positioning through brake-driveline convergence. GKN Automotive exemplifies the eDrive specialization archetype with manufacturing scale oriented toward fleet electrification programs. These three entities occupy positions that straddle capability depth and production volume across German, Chinese, and United States demand centers.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| GKN Automotive |
| Magna International Inc. |
| JTEKT Corporation |
| BorgWarner Inc. |
| Dana Incorporated |
| Schaeffler AG |
| ZF Friedrichshafen AG |
| Others |
Value Chain & Pricing Dynamics
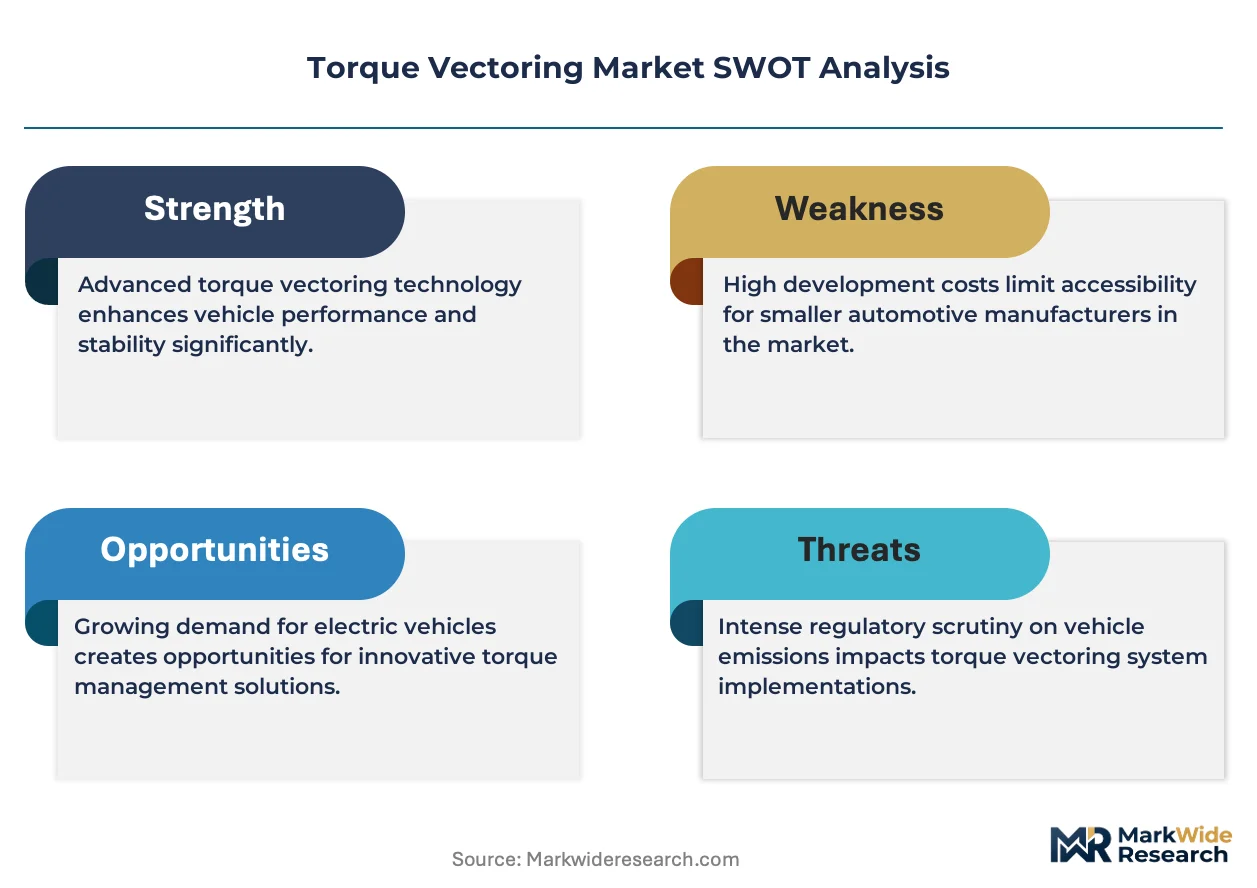
Semiconductor supply concentration in Taiwan and South Korea determines both tiered pricing spreads across active torque vectoring modules and the geographic shape of supplier manufacturing footprints, compressing margins for electronic architectures while elevating service-contract premiums for predictive maintenance capabilities.
Pricing Analysis
After-sales service contracts and over-the-air calibration subscriptions now drive lifetime value capture for torque vectoring system vendors. Three-tier pricing structure across premium, standard, and economy levels separates steer-by-wire integrated active systems from brake-based electronic differentials and passive mechanical units. Price differentiation rests on ISO 26262 ASIL-D certification grade and motor-inverter software calibration depth. Cost compression in economy-tier passive systems is intensifying because Chinese domestic OEMs prioritize cost-optimized eDrive modules for mass-market electrification. Fleet operators exhibit highest price sensitivity through total cost of ownership procurement models, while German premium OEMs absorb calibration premiums for ADAS-integrated chassis control.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supplier location decisions for torque vectoring module production. Manufacturing concentrates in Germany, China, and the United States as these countries host the largest EV production bases and performance vehicle development centers. Raw material dependencies draw from copper winding stock, rare earth permanent magnets, and automotive-grade silicon carbide semiconductors. Single-source vulnerability in Taiwan-based microcontroller foundries creates qualification delays for electronic torque vectoring programs. Distribution runs through Tier 1 chassis integrators possessing brake-driveline portfolios that consolidate procurement across OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Torque vectoring system vendors operate within a defensive-moat market structure where regulatory entrenchment through ISO 26262 functional safety certification creates substantial switching costs for OEM platform engineering teams.
For Market Incumbents: Build switching-cost moats through embedded firmware calibration libraries that lock OEM platform engineering teams into multi-year service agreements. Deepen backward integration into automotive-grade semiconductor sourcing to mitigate Taiwan foundry concentration risk. Expand capacity addition in Yangtze River Delta manufacturing clusters to capture China MIIT compliance-driven procurement volume from domestic OEM electrification roadmaps. For New Entrants and Emerging Players: India's underpenetrated torque vectoring market offers white-space entry through PLI scheme incentives for advanced automotive technology component localization. Target last-mile delivery fleet electrification programs across Germany and the United States with per-mile service agreement business models that displace upfront capital expenditure procurement. Pursue motorsport homologation partnerships as credibility transfer mechanisms for production vehicle algorithm certification. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors eDrive unit specialists with manufacturing scale and firmware competency depth. Long-term viability across the analysis window hinges on motor-inverter software calibration capabilities displacing hardware supplier value in dual-motor electric axle architectures. Acquisition target archetype: mid-tier suppliers with ISO 26262 ASIL-D certification progress and existing joint venture relationships in Chinese production clusters. Monitor NHTSA steer-by-wire regulatory harmonization progress with ECHA and SAMR as inflection indicator for unified chassis control platform standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Unified chassis control platforms migrate torque vectoring from discrete hardware to centralized compute stacks. |
| Battery Supply Agreement | Dual-motor eAxle architectures require seamless integration with cell suppliers for thermal management coordination. |
| Platform Standardization | OEM procurement consolidation across vehicle classes reduces qualification costs for Tier 1 suppliers. |
| Geographic Manufacturing Footprint | Joint ventures in Shanghai-Suzhou clusters capture China MIIT production quota-driven demand. |
| Charging Infrastructure Partnership | Commercial fleet electrification programs require coordinated traction management for variable load conditions. |
Study Parameters
Initial hypotheses were tested against primary input from Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers and refined through secondary validation across vehicle production databases, IHS Markit registration data, EPA corporate average fuel economy filings, and China MIIT new energy vehicle production disclosures. Bottom-up unit economics modeling triangulated against top-down regulatory mandate impact assessments across the analysis window.
Demand-supply balance framing anchored the forecast framework, with segmentation dimensions spanning torque vectoring architecture type, driveline technology configuration, vehicle application category, and regional production cluster. CAGRs were derived through S-curve adoption modeling for electrified driveline penetration rates and motor-based torque biasing specification trends. Industry-specific forecast inputs incorporated EPA fuel economy credit valuations and EU Green Deal tailpipe standard compliance timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion moves by Chinese domestic eDrive specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
UAE Automotive Composites Market
Automotive Components
Asia-Pacific Automotive Plastics Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
China Automotive Composites Market
Automotive Components
Auto Fender Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Automotive Cast Iron Cylinder Head Market
Automotive Components
Automotive Actuators Market
Automotive Components
Automotive Backing Plate Market
Automotive Components
Automotive Emblem Market
Automotive Components
Africa Automotive Lubricants Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
Europe Torque Vectoring Market
Automotive Components
Automotive Light Bars Market
Automotive Components
Automotive Radiator Fan Market