
 Italy Automotive Sunroof Market | 2026-2036
Italy Automotive Sunroof Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Automotive Sunroof Market Foresight
Lombardy-based glass laminators is rebalancing capacity toward larger-format panoramic panels as Italian OEMs expand SUV derivatives. Webasto Group leverages its European glazing footprint to supply premium hatchback programs from Stuttgart-aligned plants in northern Italy. CIE Automotive anchors regional metal-forming networks for aluminum rail systems serving domestic sedan platforms. BOS GmbH & Co. KG differentiates through electric-drive sunroof motors calibrated for Italy's expanding battery-electric vehicle pipeline.
An automotive sunroof is a movable or fixed transparent panel integrated into a vehicle roof structure, typically comprising tempered or laminated glass bonded to aluminum or composite reinforcement frames, engineered to provide cabin ventilation, natural illumination, and spatial perception enhancement. Italian assembly plants specify these modules to reduce perceived cabin confinement while maintaining rollover structural integrity through reinforced perimeter rings. Panoramic sunroof configurations command the dominant share of value given their multi-panel complexity and premium vehicle fitment concentration. Glass material segments sustain higher margin pools than plastic alternatives due to scratch resistance and acoustic damping requirements in Autostrada cruising conditions. Electric drive mechanisms represent the fastest-growing sub-category as Italian manufacturers phase manual crank systems from new vehicle architectures.
EU Green Deal emission benchmarks and Italy's National Recovery and Resilience Plan vehicle-transition incentives jointly pressure suppliers to lightweight sunroof assemblies through composite material substitution. ECE R43 safety glazing standards and CE marking protocols govern optical clarity and fragmentation behavior for all roof-panel installations sold within Italian territory. Stakeholders must monitor Turin-Milan corridor logistics costs and EU Battery Regulation upstream material tracing rules as determinants of sunroof subsystem sourcing economics.
Market Dynamics
Italian OEMs are reconfiguring roofline architectures to accommodate panoramic glass assemblies demanded by premium SUV buyers in Milan and Turin, compressing traditional metal-roof supply chains while expanding glazing subcontractor networks across the Po Valley.
Growth Catalysts
- EU Green Deal vehicle-weight mandates:Italy's National Recovery and Resilience Plan incentivizes lightweight composite frame materials, accelerating aluminum substitution in sunroof rail systems.
- Panoramic glass preference:Premium hatchback and SUV buyers in northern industrial corridors specify multi-panel configurations for cabin illumination.
- Battery-electric vehicle pipeline:Electric-drive sunroof mechanisms displace manual crank systems as Italian manufacturers phase traditional architectures.
Market Restraints
- Aluminum price volatility:Frame material cost fluctuations compress margin pools for rail system suppliers serving domestic sedan platforms.
- Glass laminator concentration:Lombardy-based capacity rebalancing toward larger-format panels creates bottleneck risk for panoramic panel supply.
- ECE R43 compliance friction:Optical clarity and fragmentation testing protocols extend certification timelines for new roof-panel designs.
Strategic Opportunities
- Modena-Bologna luxury cluster expansion:Underpenetrated sports car derivative programs offer fitment growth for fixed glass roof assemblies.
- EU Battery Regulation upstream tracing:Material provenance requirements favor regional suppliers with transparent aluminum and composite sourcing.
- Electric motor convergence:Integration of sunroof actuation with vehicle-wide mechatronics platforms creates bundled subsystem opportunities.
Industry Challenges
- Specialized glazing technician scarcity:Large-format laminated panel installation requires skills concentrated among Lombardy laminators, constraining capacity expansion.
- Legacy platform integration complexity:Retrofitting electric-drive mechanisms into existing sedan roof structures demands redesign of peripheral sealing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Automotive Sunroof Market |
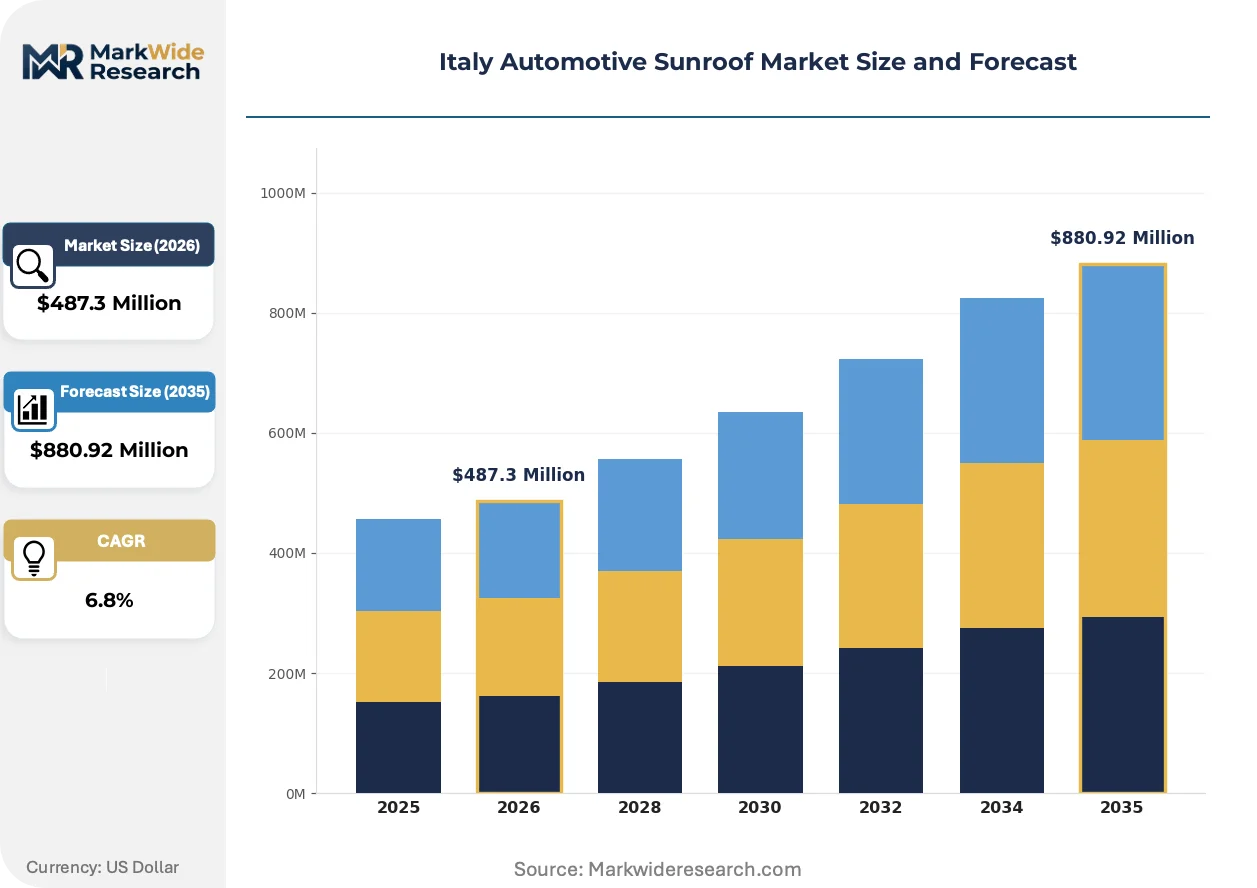
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panoramic Sunroof, Conventional Sunroof, T-Tops, Solar Sunroof Drive Type: Front-Wheel Drive, Rear-Wheel Drive, All-Wheel Drive, Electric Drive Material: Glass, Plastic, Aluminum, Composite Vehicle Type: SUV, Sedan, Coupe, Hatchback |
| Companies Covered | Magna International Inc., Inteva Products LLC, Webasto Group, Johnan Manufacturing Inc., Yachiyo Industry Co., Ltd., Inalfa Roof Systems Group B.V., Aisin Seiki Co., Ltd., BOS GmbH & Co. KG, CIE Automotive, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Automotive Sunroof Market Shifts & Advancements
Glass-to-metal bonding technologies and electric actuation systems are displacing traditional mechanical assemblies across Italian vehicle programs, while regulatory pressure on vehicle weight accelerates material substitution in roof structures.
Polymer-interlayer laminated glass is modularizing sunroof construction by enabling larger continuous panels without structural metal cross-members. Premium SUV assemblers in Turin adopt these assemblies for panoramic configurations. The technology is modularizing supplier relationships, allowing glazing specialists to deliver complete roof modules rather than components to OEM final assembly lines.
EU Green Deal emission benchmarks are tightening embodied carbon accounting for automotive subsystems. Italian suppliers must document aluminum smelting energy sources and composite resin chemistries. Battery-electric vehicle programs face the strictest material provenance requirements, pushing procurement toward regional European metal formers with ISO 14001-certified facilities.
Fleet procurement managers at Milan-based luxury leasing operators now specify sunroof content as a residual value determinant. Direct OEM-to-fleet contracting is displacing traditional dealer-channel configuration for executive vehicle categories. This concentration is most visible in Lombardy, where corporate fleet density drives standardized panoramic fitment across mid-size SUV segments.
Italy Automotive Sunroof Market Segmentation
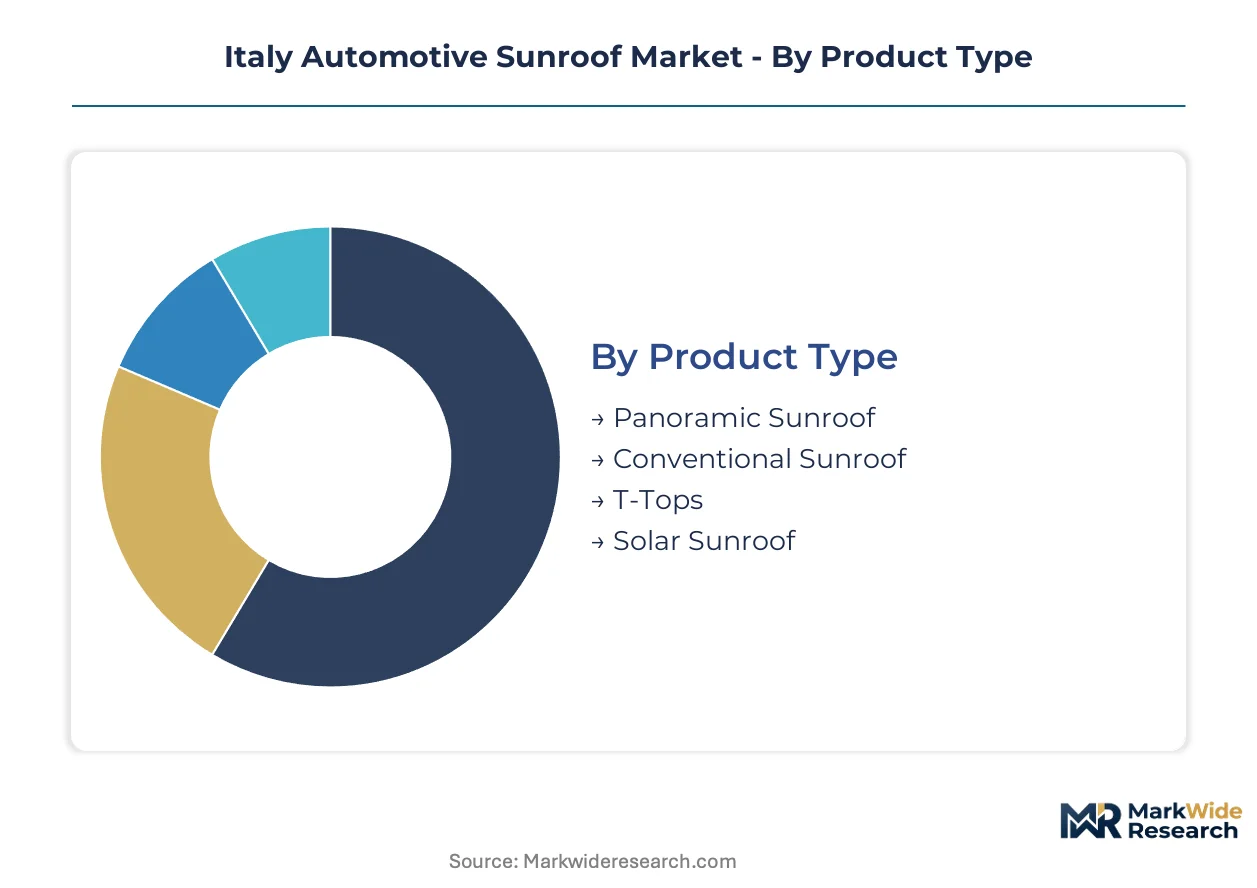
Italian OEM procurement patterns reveal a clear trade-off between premium customization and platform standardization. Segmentation choices directly determine supplier qualification requirements, tooling amortization, and residual value positioning in Milan-Turin fleet channels.
Product Type:
Customization intensity spans from mass-market standardized units to coachbuilt specialty configurations, with glazing complexity driving the segmentation logic.
- Panoramic Sunroof:Multi-panel laminated glass assemblies bonded to aluminum perimeter frames, extending across 70-90% of roof surface area. Turin-based premium SUV assemblers specify these for cabin spatial perception enhancement, though Lombardy laminator capacity constraints create supply bottlenecks for large-format panels.
- Conventional Sunroof:Single-panel pop-up or spoiler designs with manual or electric actuation, historically dominant in domestic sedan platforms. Demand concentrates in Bologna-Modena corridor entry-luxury segments where cost engineering preserves margin pools.
- T-Tops:Dual removable glass or composite panels with center roof bar retention, serving niche sports car derivatives from Modena-based specialty assemblers.
- Solar Sunroof:Photovoltaic-integrated glass with embedded silicon cells for auxiliary battery charging, emerging in battery-electric vehicle programs with strict EU Green Deal embodied carbon accounting.
Leading the category by volume: Panoramic Sunroof. Expanding most quickly: Solar Sunroof.
Drive Type:
Actuation technology choices map directly to vehicle electrification architecture decisions, with integration depth separating premium from value tiers.
- Electric Drive:Brushless DC motors with CAN bus integration and anti-pinch sensing, displacing mechanical systems across Italian BEV and PHEV pipelines. BOS GmbH calibrates these for seamless mechatronic platform convergence.
- Front-Wheel Drive:Legacy mechanical routing through dashboard switchgear, persisting in cost-optimized hatchback programs from southern Italian assembly plants.
- Rear-Wheel Drive:Cable-actuated or motor-driven systems for longitudinal engine architectures, common in Modena sports car platforms.
- All-Wheel Drive:Heavy-duty sealing and reinforcement specifications for off-road capable SUVs, with reinforced drain channels for Alpine climate exposure.
Dominant by installation share: Electric Drive. Steepest expansion trajectory: Electric Drive.
Material:
Weight reduction mandates from EU Green Deal vehicle targets are compressing traditional material hierarchies toward hybrid constructions.
- Glass:Tempered or polymer-interlayer laminated configurations with acoustic damping interlayers for Autostrada cruising conditions. Lombardy laminators command premium positioning for optical-grade specifications.
- Composite:Carbon-fiber or glass-fiber reinforced polymer frames substituting aluminum in weight-critical BEV applications, with ISO 14001-certified resin sourcing required for EU Battery Regulation compliance.
- Aluminum:Extruded rail systems and stamped reinforcement rings, facing margin pressure from LME price volatility and energy-intensive smelting scrutiny.
- Plastic:Polycarbonate or acrylic panels for economy segments, limited by scratch resistance and UV degradation performance in Mediterranean solar exposure.
Highest value concentration: Glass. Gaining share fastest: Composite.
Vehicle Type:
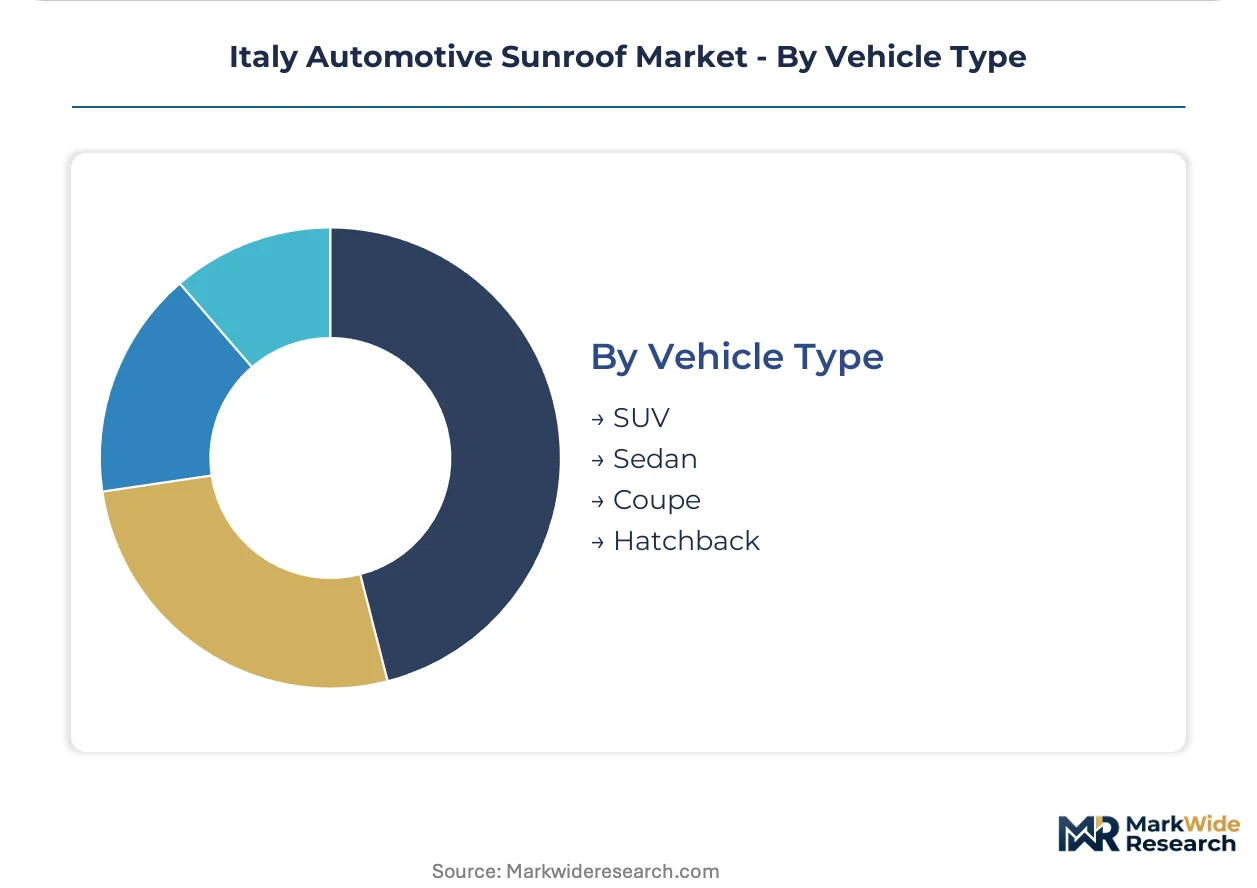
Body style segmentation aligns with regional assembly cluster specializations and fleet procurement concentration patterns.
- SUV:Panoramic glass specification rates exceed 80% in Milan-based corporate fleet channels, with roofline height enabling larger panel formats without headroom compromise.
- Sedan:Conventional sunroof persistence in executive chauffeur segments, though electric-drive retrofit complexity challenges legacy platform integration.
- Coupe:Fixed glass roof assemblies and T-top configurations from Modena specialty builders, with carbon fiber frame options at premium tiers.
- Hatchback:Cost-optimized manual or basic electric units, with Webasto supplying Stuttgart-aligned premium variants from northern Italian plants.
Primary volume anchor: SUV. Fastest-growing fitment rate: Hatchback.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelting capacity in the Po Valley underpins Italy's sunroof manufacturing density. Regional procurement clusters concentrate where glass laminators and metal formers co-locate near premium vehicle assembly.
Lombardy
Milan-based corporate fleet operators specify panoramic glass fitment rates exceeding 80% in mid-size SUV segments. EU Green Deal embodied carbon accounting pressures procurement toward ISO 14001-certified glazing subcontractors. Bergamo-Brescia industrial zones host polymer-interlayer laminators rebalancing capacity toward larger-format panels.
Piedmont
Turin anchors premium SUV assembly lines demanding multi-panel panoramic configurations for cabin spatial perception. CE marking protocols and ECE R43 safety glazing standards govern optical clarity specifications for all roof-panel installations. Local supply chains integrate Stuttgart-aligned component flows from cross-border Alpine logistics corridors.
Emilia-Romagna
Modena-Bologna specialty sports car builders sustain demand for fixed glass roof assemblies and T-top configurations. Italy's National Recovery and Resilience Plan vehicle-transition incentives channel investment toward battery-electric derivative programs. Maranello-area carbon fiber frame suppliers serve weight-critical BEV applications with composite rail systems.
Veneto
Verona-Padua glass processing clusters supply acoustic-damping interlayers for Autostrada cruising conditions. REACH compliance documentation requirements shape resin chemistry selection in polymer-interlayer formulations. Regional logistics nodes connect Lombardy laminators to Adriatic port export channels.
Italy Automotive Sunroof Market Competitive Landscape
Global majors compete with regional champions across glazing and actuation subsystems, producing a tiered structure where scale-driven system integrators coexist with specialized component fabricators. Market concentration reflects automotive OEM procurement consolidation rather than fragmented vendor proliferation. Three archetypes dominate: European-headquartered full-system suppliers, Asia-Pacific electric-component specialists, and Southern European metal-forming regionalists. Competitive dynamics center on M&A-driven technology convergence and capacity rebalancing toward BEV-aligned electric-drive architectures.
Among Germany-anchored system integrators, Webasto Group and BOS GmbH & Co. KG occupy positions spanning full-module supply and electric-actuation specialization respectively. CIE Automotive represents the Southern European metal-forming archetype with regional aluminum rail system capabilities. These three entities exemplify the geographic and functional segmentation that structures procurement relationships across Turin-Milan corridor OEM programs.
| Leading Market Players |
|---|
| Magna International Inc. |
| Inteva Products LLC |
| Webasto Group |
| Johnan Manufacturing Inc. |
| Yachiyo Industry Co., Ltd. |
| Inalfa Roof Systems Group B.V. |
| Aisin Seiki Co., Ltd. |
| BOS GmbH & Co. KG |
| CIE Automotive |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ECE R43-compliant panoramic assemblies and uncertified aftermarket alternatives manifests in both margin structures and supplier qualification hierarchies across Lombardy glazing networks. Premium OEM procurement bundles extended warranty coverage and technical service into module pricing, while independent repair channels absorb unbundled installation risk at compressed rates.
Pricing Analysis
Warranty and service bundling separates OEM-direct contracting from aftermarket channels, with Italian fleet operators demanding multi-year coverage as standard. Three-tier pricing structure across premium panoramic, standard conventional, and economy plastic-panel levels reflects optical-grade certification and acoustic interlayer complexity. Cost compression in aluminum rail systems intensifies because LME price volatility feeds directly into frame supplier margins. Volume fleet buyers at Milan-based leasing operators exhibit lowest price sensitivity, while southern Italian independent dealerships face acute margin pressure from manual-crank inventory liquidation.
Supply Chain Analysis
CE marking and ECE R43 qualification gating restricts viable suppliers to ISO-certified laminators and metal-formers with documented optical testing capabilities. Manufacturing concentrates in Germany, Italy, and Czech Republic, with Alpine logistics corridors feeding Turin-Milan assembly clusters. Raw material dependencies span polymer interlayers from Belgium, aluminum extrusions from Germany, and electric motors from China. Single-source vulnerability concentrates in large-format glass laminator capacity around Bergamo-Brescia zones. Distribution runs through Tier 1 system integrators delivering complete roof modules rather than component flows to OEM lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
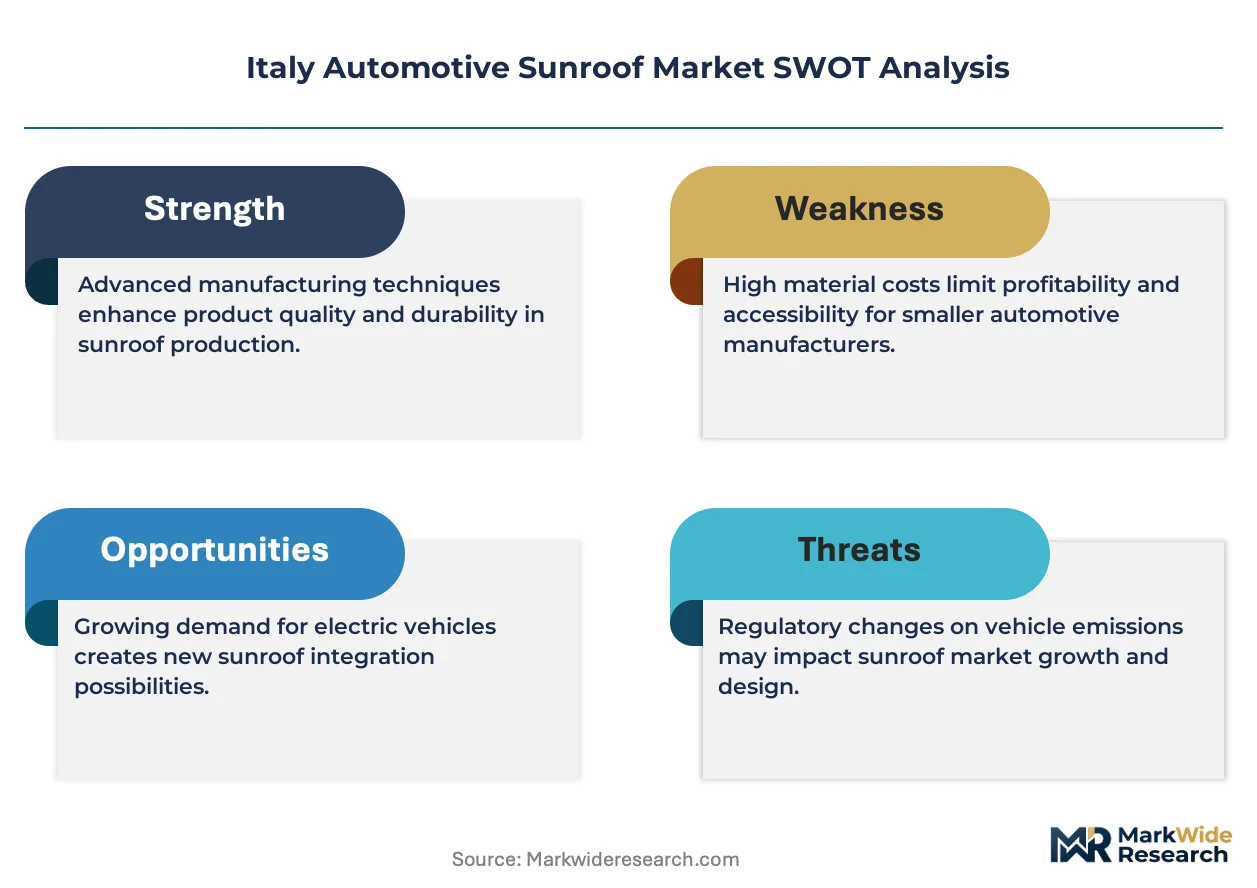
EU Battery Regulation material provenance requirements erect a compliance-cost moat favoring regional suppliers with transparent aluminum and composite sourcing, marginalizing non-certified competitors.
For Market Incumbents: Extend certification coverage across ISO 14001 environmental management and ECE R43 testing protocols to defend against Asian electric-motor specialists entering through BEV platform convergence. Deepen backward integration into polymer-interlayer resin sourcing to secure margin pools threatened by REACH compliance documentation costs. Prioritize capacity retention in Lombardy laminator networks where specialized glazing technician scarcity constrains competitor expansion.
For New Entrants and Emerging Players: Capture white-space in Modena-Bologna sports car fixed-glass roof assemblies where carbon fiber frame expertise differentiates from mass-market metal-forming incumbents. Target solar sunroof photovoltaic integration for battery-electric vehicle programs with strict EU Green Deal embodied carbon accounting. Lead with transparent material provenance documentation as procurement gate-opener against legacy suppliers with opaque upstream sourcing.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap glazing specialists with ECE R43 certification and Lombardy geographic positioning. Long-term viability hinges on electric-drive actuation capability convergence with vehicle-wide mechatronics platforms. Acquisition target archetype: ISO 14001-certified composite frame suppliers serving Maranello-area BEV programs. The signal to watch is EU Battery Regulation enforcement intensity accelerating procurement preference for regional European metal-formers.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Frame Material Transition | Carbon fiber substitution in BEV rail systems satisfies EU Green Deal weight mandates from Turin assemblers. |
| Electric Drive Actuation Integration | CAN bus-connected motors displace mechanical systems across Italian battery-electric vehicle pipelines. |
| Large-Format Glass Laminator Capacity Expansion | Bergamo-Brescia zone investments relieve bottleneck risk for panoramic panel supply to Milan fleet channels. |
| Material Provenance Documentation Systems | Upstream aluminum smelting energy tracing secures qualification for EU Battery Regulation-compliant procurement. |
| Glazing Technician Training Pipeline Development | Lombardy-based skills concentration constraints limit industry-wide capacity expansion without intervention. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and Lombardy glazing subcontractor operations managers. Bottom-up vehicle production database triangulation against top-down component value chain estimates validated market sizing. Secondary sources encompassed ECE R43 testing protocols, EU Battery Regulation implementation guidance, and Italian National Recovery and Resilience Plan vehicle-transition incentive disclosures.
Segment-level granularity modeled product type, drive architecture, material composition, and vehicle class across the projection horizon, with regional production cluster overlays for Turin-Milan-Modena corridor specialization. CAGRs derived from fitted trend extrapolation against policy-mandated BEV penetration scenarios and fleet procurement concentration patterns. Industry-specific forecast inputs incorporated aluminum LME price trajectory assumptions and laminator capacity utilization rates from Bergamo-Brescia industrial zones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Battery Regulation enforcement timing and Alpine logistics corridor disruption risk. Model outputs reflect assumptions around electric-drive mechanism phase-out of manual systems and panoramic glass preference persistence in corporate fleet channels. A model refresh is warranted upon material change in EU Green Deal vehicle-weight mandate stringency or Lombardy laminator capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Global Automotive Aluminum Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Automotive Resonator Market
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
Europe Automotive Glass Market
Automotive Components
Automotive Towbar Market
Automotive Components
North America Automotive Heat Shield Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Automotive Comfort Actuators Market
Automotive Components
Italy Automotive Actuators Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
Automotive Seat Frame Market