
 Australia Automotive Composites Market | 2026-2036
Australia Automotive Composites Market Size, Share, and Industry Trends Forecast 2026-2036
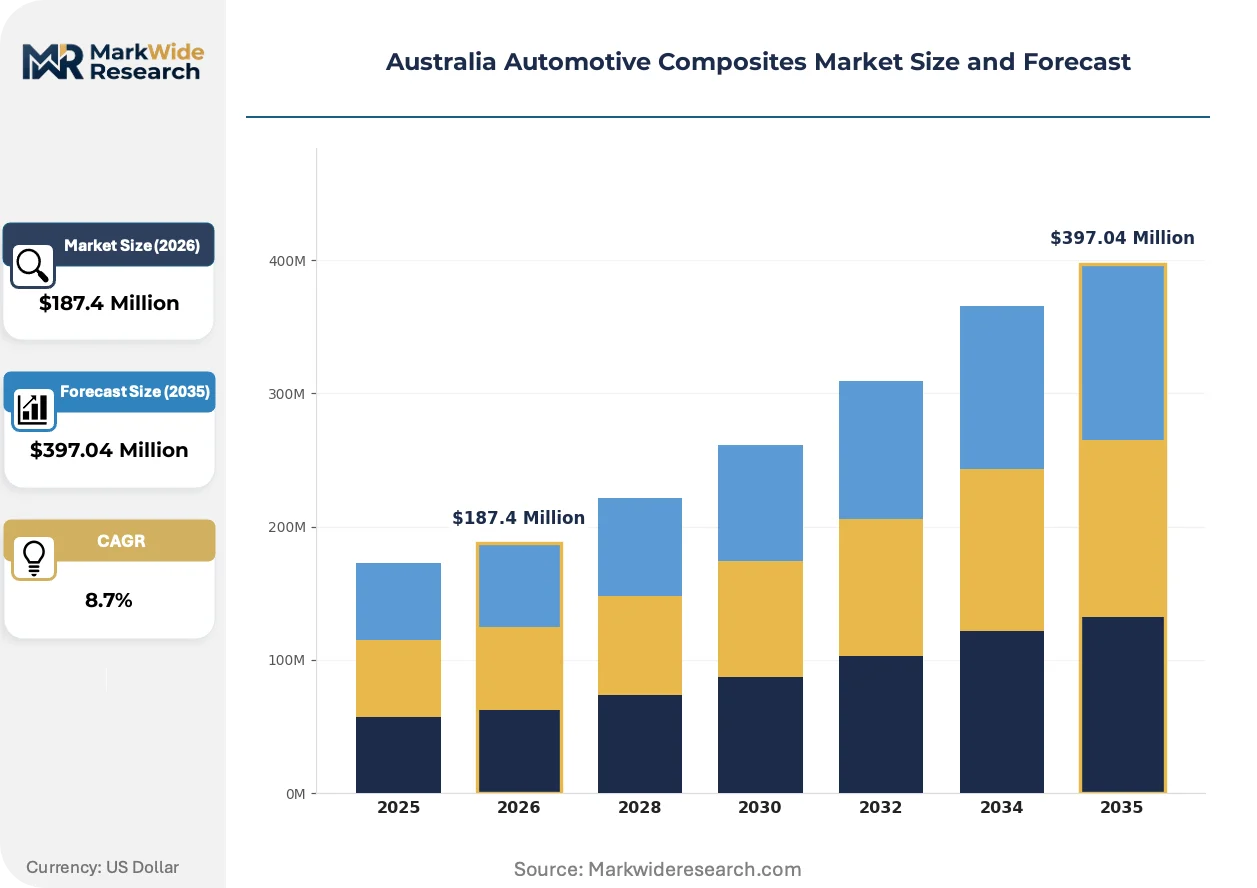
Australia Automotive Composites Market Outlook
Tier-1 suppliers is rotating toward OEM direct partnerships as vehicle assemblers seek greater control over lightweighting specifications. Toray Industries leverages its carbon fiber precursor technology to dominate high-performance structural applications. APR Composites anchors local production capacity with specialized compression molding expertise for Australian defense and commercial vehicle programs. Solvay S.A. differentiates through resin formulation leadership that sustains thermal performance under Australian operating conditions.
Automotive composites encompass fiber-reinforced polymer matrices combining carbon, glass, or natural fibers with thermoset or thermoplastic resins, manufactured through processes achieving specific strength-to-weight ratios exceeding 200 MPa per gram per cubic centimeter. These materials primarily reduce vehicle mass to improve energy efficiency and crashworthiness in passenger and commercial transport. Glass fiber products occupy the volume lead across exterior panel applications, while carbon fiber commands premium positioning in structural chassis components where performance thresholds justify material cost. Compression molding technology leads Australian production throughput due to its compatibility with medium-volume automotive programs, whereas resin transfer molding captures growth in electric vehicle battery enclosure fabrication.
Australia's Department of Infrastructure and Transport administers the Australian Design Rules (ADR) that mandate crashworthiness and emissions performance standards directly influencing composite material qualification timelines. The Australian Competition and Consumer Commission monitors supply chain conduct affecting Tier-1 supplier and aftermarket provider market access. Stakeholders must monitor evolving ADR amendments for electric vehicle-specific structural requirements and assess localized resin supply security against import dependency risks.
Market Dynamics
Electric vehicle battery enclosure fabrication is compressing traditional metal-stamping supply chains while forcing Tier-1 suppliers to requalify compression-molded composite architectures under ADR crashworthiness protocols.
Growth Catalysts
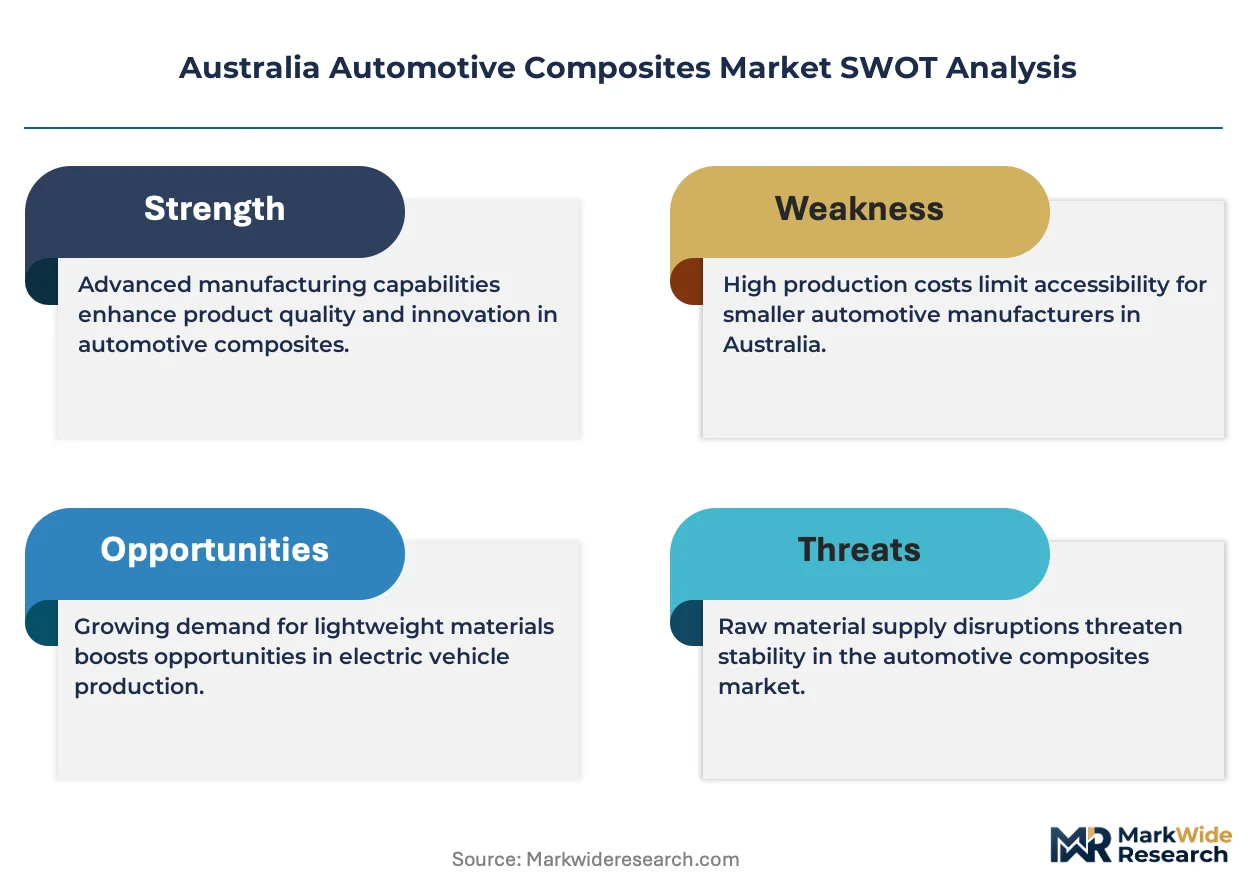
- ADR Amendment Trajectory:Pending electric vehicle-specific structural requirements under Australian Design Rules are accelerating material qualification timelines for fiber-reinforced polymer chassis components.
- Victoria Manufacturing Corridor:Concentrated R&D activity around Melbourne is pulling specialized compression molding expertise into localized production networks.
- Carbon Fiber Precursor Availability:Domestic precursor manufacturing investments are reducing import dependency for high-performance structural applications.
Market Restraints
- Petrochemical Resin Volatility:Thermoset epoxy and polyester resin prices fluctuate with crude oil derivatives, compressing margin stability for medium-volume automotive programs.
- Single-Source Carbon Fiber Concentration:Asian precursor suppliers dominate high-tensile fiber feedstock, exposing Australian converters to geopolitical supply interruptions.
- Recyclability Technical Ceiling:Thermoset cross-linked polymers resist mechanical or chemical reclamation, constraining circular economy compliance pathways.
Strategic Opportunities
- Defense Vehicle Programs:Australian defense procurement specifications for blast-resistant composite armor are creating adjacent demand for commercial vehicle structural expertise.
- Thermoplastic Resin Convergence:Polyamide and polypropylene matrix systems compatible with automated fiber placement are opening high-throughput production pathways previously locked to thermosets.
- Queensland Mining Fleet Retrofit:Heavy vehicle lightweighting mandates in resource extraction operations are generating aftermarket composite panel demand outside traditional OEM channels.
Industry Challenges
- ADR Certification Timeline Compression:Accelerated electric vehicle platform launches are squeezing composite crash-test validation cycles below 18-month thresholds.
- Multi-Material Joining Expertise Scarcity:Adhesive bonding and mechanical fastening between carbon fiber and aluminum substructures requires specialized technician training absent from vocational pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Automotive Composites Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Natural Fiber, Reinforced Plastics Application: Structure, Interior, Exterior, Underbody End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Injection Molding, Compression Molding, Resin Transfer Molding, Hand Layup |
| Companies Covered | Toray Industries, Inc., Solvay S.A., APR Composites, Evonik Industries AG, Scott Bader Company Ltd., Austeng, Mitsubishi Chemical Group Corporation, Huntsman Corporation, Advanced Composite Structures Australia Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Automotive Composites Market Strategic Shifts
Automated fiber placement systems are rewiring capital deployment patterns across Australian Tier-1 suppliers. Process automation, regulatory harmonization pressures, and procurement centralization are the three vectors compressing competitive timelines.
Automated fiber placement technology deposits continuous carbon fiber tows with precision placement accuracy below one millimeter. Electric vehicle battery enclosure manufacturers in Victoria and South Australia are adopting these systems at pilot scale. This capability is displacing manual layup operations in structural component fabrication, compressing labor cost structures and cycle times simultaneously.
Australian Design Rules administered by the Department of Infrastructure and Transport are tightening pedestrian impact and crashworthiness standards for composite-intensive vehicle architectures. Tier-1 suppliers must now submit fiber-reinforced polymer qualification data through extended thermal aging protocols. Battery enclosure programs face the steepest compliance burden, with some manufacturers adding six-month buffer periods to platform launch schedules.
Fleet procurement managers at mining and logistics operators are consolidating composite panel sourcing through direct OEM negotiations rather than aftermarket distributors. This channel compression is eliminating traditional Tier-2 distributor margins across Western Australia and Queensland heavy vehicle segments. Resource extraction companies with captive maintenance operations are driving the fastest adoption of this consolidated buying pattern.
Australia Automotive Composites Market Segmentation
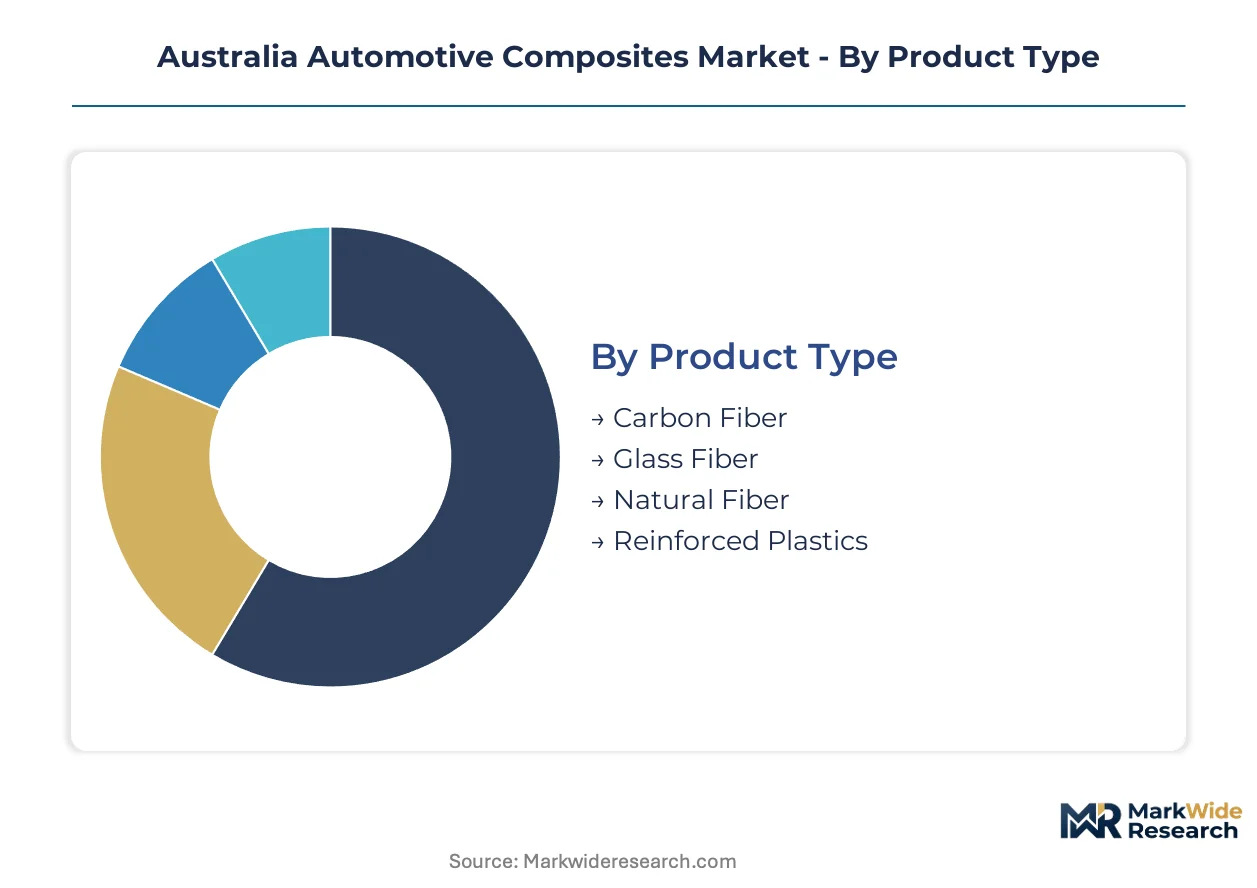
Segmentation in the Australia Automotive Composites Market reveals how substitution pressures from aluminum and high-strength steel reshape material selection across vehicle architectures. Understanding these divisions exposes where composite solutions defend their value proposition against incumbent metals.
Product Type:
Glass fiber faces the most acute substitution threat from stamped aluminum in exterior panels, while carbon fiber maintains defensive positioning in structural applications where specific stiffness requirements exclude metallic alternatives.
- Glass Fiber:E-glass and S-glass reinforcements in polyester or vinyl ester matrices deliver tensile strengths of 3,400-4,500 MPa at densities below aluminum. Exterior panel demand concentrates in Victoria's commercial vehicle programs, though price compression from Chinese glass roving imports erodes converter margins.
- Carbon Fiber:PAN-based and pitch-based carbon fibers achieve modulus values exceeding 230 GPa with densities one-quarter of steel. Structural chassis demand clusters around Melbourne's electric vehicle R&D corridor, where ADR crashworthiness requirements for battery enclosures sustain premium positioning despite precursor cost volatility.
- Natural Fiber:Jute, hemp, and flax reinforcements in polypropylene matrices serve interior trim applications with lower mechanical requirements.
- Reinforced Plastics:Short-fiber thermoplastic compounds fill non-structural brackets and housings where metal replacement drives cost reduction.
Glass fiber anchors the volume base while carbon fiber gains share at the steepest rate.
Application:
Cost tier differentiation separates commodity exterior panels from premium structural architectures, with margin structures widening between crash-critical and cosmetic applications.
- Structure:Load-bearing chassis components, subframes, and crash structures utilize carbon fiber prepregs or compression-molded SMC. Battery enclosure programs in South Australia specify these materials for ADR-compliant side-impact protection, with qualification timelines stretching 24 months.
- Exterior:Body panels, hoods, and fenders employ glass fiber SMC or thermoplastic composites. Queensland mining fleet retrofits drive aftermarket demand for impact-resistant exterior surfaces in heavy-duty operating conditions.
- Interior:Dashboard carriers, door modules, and seating structures favor natural fiber-thermoplastic hybrids for weight reduction and acoustic damping.
- Underbody:Aerodynamic shields, battery protection plates, and heat shields utilize glass mat thermoplastics with aluminum hybridization for thermal management.
Exterior applications generate the broadest revenue footprint while structural segments command the highest value per kilogram.
End User:
Procurement centralization is compressing traditional channel margins, with direct OEM engagement displacing Tier-1 intermediation in specification-heavy programs.
- OEMs:Vehicle manufacturers with captive design teams specify composite architectures directly for electric vehicle platforms. Ford Australia and Toyota Australia maintain internal composite engineering groups that qualify materials through proprietary test protocols.
- Tier-1 Suppliers:Exterior system integrators like Plastic Omnom and Magna face margin compression as OEMs internalize composite design competency. These suppliers pivot toward module assembly rather than material conversion.
- Aftermarket Providers:Independent distributors serve collision repair and performance upgrade segments with standardized panel catalogues.
- Vehicle Assemblers:Low-volume commercial and defense vehicle builders source directly from Australian converters like APR Composites for specialized armor and structural applications.
Tier-1 suppliers retain the largest transaction volume while OEM direct procurement expands most quickly.
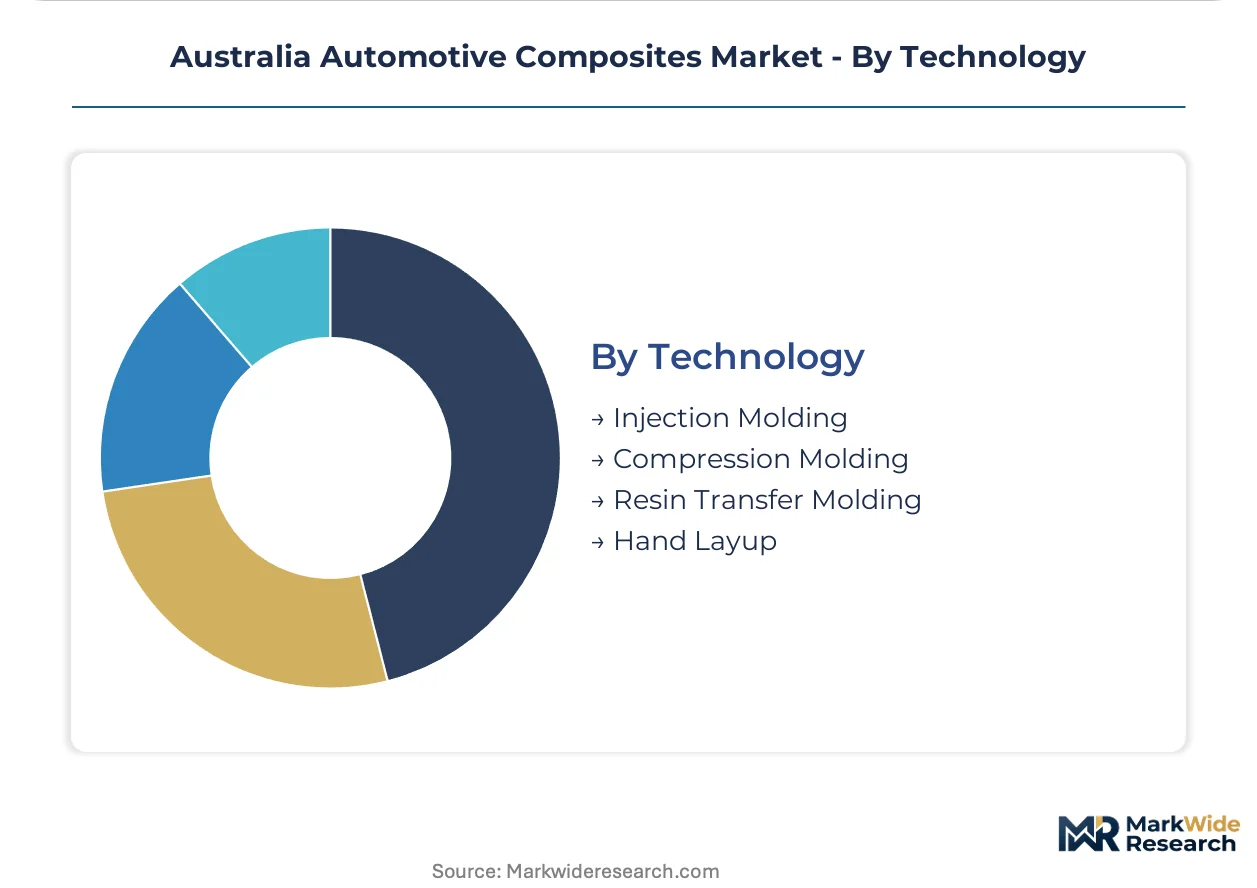
Technology:
Volume scalability separates automated processes from manual operations, with capital intensity determining market access thresholds for Australian converters.
- Compression Molding:Sheet molding compound and bulk molding compound processes achieve cycle times under three minutes for medium-volume automotive production. Victorian manufacturers deploy these systems for exterior panel programs serving domestic OEMs.
- Resin Transfer Molding:Closed-mold infusion of dry fiber preforms enables complex geometry fabrication with void content below 2%. Battery enclosure manufacturers in Adelaide adopt RTM for fire-resistant epoxy formulations meeting ADR thermal runaway protocols.
- Injection Molding:Short-fiber thermoplastic compounding serves high-volume interior components with glass loadings of 20-40% by weight.
- Hand Layup:Open-mold wet layup persists in prototype development and ultra-low-volume defense programs where tooling investment is prohibitive.
Compression molding dominates current throughput while resin transfer molding shows the steepest capacity expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Melbourne anchors Australia's automotive composites trade, handling carbon fiber precursor imports and finished component exports for domestic vehicle programs. This maritime infrastructure underwrites Victoria's manufacturing corridor dominance.
New South Wales
Defense vehicle programs drive composite armor demand through the Department of Defence's LAND 400 procurement. The Australian Design Rules administered by the Department of Infrastructure and Transport mandate blast-resistant structural standards. Western Sydney's advanced manufacturing precinct hosts Tier-1 suppliers qualifying compression-molded chassis components for military and commercial crossover applications.
Victoria
Electric vehicle battery enclosure fabrication concentrates demand for fire-resistant epoxy formulations. The Department of Infrastructure and Transport enforces ADR thermal runaway protocols extending qualification timelines. Melbourne's southeastern manufacturing belt hosts APR Composites and automated fiber placement pilot lines serving South Australian OEM programs.
Queensland
Mining fleet retrofit operations generate aftermarket composite panel demand outside traditional OEM channels. Workplace health and safety regulations mandate heavy vehicle lightweighting for fuel efficiency in resource extraction. Brisbane-Gladstone corridor maintenance depots source impact-resistant exterior surfaces directly from converters, bypassing distributor networks.
South Australia
Battery enclosure manufacturing for electric vehicle platforms anchors structural composite demand. The Department for Infrastructure and Transport administers state-level vehicle safety harmonization with federal ADR standards. Adelaide's northern suburbs host resin transfer molding capacity for complex geometry fabrication meeting side-impact protection requirements.
Western Australia
Remote mining operations drive demand for durable composite components in extreme operating conditions. Environmental protection regulations constrain thermoset waste disposal from maintenance operations. Perth-Kalgoorlie logistics networks facilitate direct procurement from eastern state converters for fleet operators with captive maintenance capabilities.
Australia Automotive Composites Market Competitive Environment
Concentration sits with multinational resin and fiber suppliers controlling precursor technology and formulation intellectual property. Domestic converters occupy specialized niches in defense and medium-volume commercial programs. Three archetypes define competitive positioning: integrated chemical conglomerates with captive carbon fiber capacity, regional fabrication specialists with ADR qualification expertise, and diversified materials suppliers pivoting from industrial to automotive grades. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as electric vehicle platforms compress procurement timelines.
Within the multinational chemical tier, Toray Industries, Inc. and Solvay S.A. exemplify integrated positioning through precursor and resin formulation control. APR Composites anchors the domestic specialist archetype with Victorian-based compression molding expertise. These three entities represent the spectrum from global feedstock dominance to localized ADR-compliant fabrication.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Solvay S.A. |
| APR Composites |
| Evonik Industries AG |
| Scott Bader Company Ltd. |
| Austeng |
| Mitsubishi Chemical Group Corporation |
| Huntsman Corporation |
| Advanced Composite Structures Australia Pty Ltd |
| Others |
Value Chain & Pricing Dynamics
Ninety-day carbon fiber precursor inventory cycles at Victorian converters compress pricing power for medium-volume automotive programs, while petrochemical resin volatility feeds directly into contract renegotiation leverage for Tier-1 suppliers. This lead-time exposure concentrates margin pressure on glass fiber exterior panel producers, whereas carbon fiber structural specialists defend premium positioning through ADR qualification lock-in.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs composite procurement, with carbon fiber prepregs commanding certification-grade premiums against commodity glass fiber SMC. Price differentiation hinges on ADR crash-test validation status and volume commitment scale, with battery enclosure programs showing least price sensitivity due to thermal runaway compliance requirements. Cost compression in glass fiber tiers is intensifying because Chinese roving import volumes erode domestic converter margins. Mining fleet operators in Queensland exhibit highest price sensitivity, sourcing aftermarket panels through direct converter negotiations that eliminate distributor markups.
Supply Chain Analysis
Inventory exposure runs through Asian precursor suppliers, with Japanese and South Korean carbon fiber feedstock dominating high-tensile fiber availability for Australian converters. Raw material dependencies center on PAN-based precursor, epoxy resin formulations, and glass roving imports from China and Southeast Asia. Single-source vulnerability concentrates in carbon fiber tow supply, where geopolitical interruption risks expose Victorian manufacturers to qualification timeline extensions. Distribution runs through Port of Melbourne consolidation hubs, with finished components flowing to South Australian battery enclosure plants and Queensland mining maintenance depots via captive logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where aftermarket technical support and ADR recertification services expand faster than base material throughput. Composite panel lifecycle management and crash-damage assessment consulting now generate recurring revenue streams that outpace commodity composite sales growth.
For Market Incumbents: Secure long-term precursor supply agreements with Japanese and South Korean fiber producers before qualification timeline compression accelerates. Defend margin position by backward integration into compression molding tooling fabrication, reducing reliance on European equipment imports. Invest in ADR thermal aging protocol expertise as electric vehicle battery enclosure requirements tighten, creating certification barriers for unqualified competitors.
For New Entrants and Emerging Players: Aftermarket technical training for multi-material joining represents the most penetrable service gap, where incumbent Tier-1 suppliers under-serve independent repair networks. Target Queensland mining fleet maintenance operations with rapid-turn composite panel replacement programs, bypassing traditional OEM channel structures. Establish go-to-market partnerships with Adelaide-based resin transfer molding specialists to access South Australian battery enclosure qualification pipelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming automotive composite divisions seeking portfolio rationalization. Long-term viability favors converters with captive ADR certification expertise and defense program diversification. Watch electric vehicle platform launch delays as the critical inflection signal, where schedule slippage would compress near-term composite demand while extending qualification investment recovery periods.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Japanese carbon fiber feedstock agreements reduce Victorian converter exposure to import volatility. |
| ADR Certification Infrastructure Investment | Thermal aging test capacity in Melbourne accelerates electric vehicle battery enclosure qualification timelines. |
| Defense Program Crossover Expansion | LAND 400 blast-resistant armor expertise transfers to commercial vehicle structural applications. |
| Automated Fiber Placement Deployment | South Australian OEMs adopt robotic tow placement to compress labor cost structures below manual layup. |
| Aftermarket Technical Service Development | Queensland mining fleet operators purchase composite damage assessment consulting alongside panel replacement. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the Australian automotive composites value chain, including Tier-1 supplier procurement directors, OEM platform engineers specializing in lightweighting, aftermarket distributors serving Queensland mining fleets, and resin formulation technical leads at multinational chemical suppliers. Secondary validation drew from Australian Design Rule amendment filings, Department of Infrastructure and Transport crashworthiness test protocols, customs import records for carbon fiber precursor volumes, and vehicle production databases tracking electric vehicle platform launches. Bottom-up demand modeling from end-use applications triangulated against top-down supply capacity assessments across Victorian and South Australian manufacturing clusters.
Across the analysis window, the forecasting framework segmented volume and value outputs by fiber type, application architecture, manufacturing technology, and end-user procurement channel, with vehicle propulsion architecture and ADR compliance tier serving as additional industry-specific dimensions. CAGRs were derived from production volume trajectories weighted against material substitution elasticity parameters. Key forecast inputs included electric vehicle battery enclosure content-per-vehicle assumptions and defense procurement program timelines.
Underlying assumptions cover sustained electric vehicle platform investment, stable petrochemical feedstock pricing, and ADR harmonization with international crashworthiness standards, with deviation risk concentrated in carbon fiber precursor supply interruptions and mining sector capital expenditure cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Buffers Market
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Global Automotive Aluminum Market
Automotive Components
Automotive Axle Market
Automotive Components
Automotive Chromium Market
Automotive Components
US Automotive Glass Fiber Composites Market
Automotive Components
Automotive Stabilizer Bar Link Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
Regenerative Suspension System Market
Automotive Components
Iran Automotive Lubricants Market
Automotive Components
Automotive Injector Nozzle Market
Automotive Components
Africa and Middle East Automotive Actuators Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
Automotive Spark Plug Market