
 Automotive Mufflers Market | 2026-2036
Automotive Mufflers Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Mufflers Market Analysis
Aftermarket service revenue is narrowing as OEMs extend powertrain warranty periods and captive dealer networks tighten parts distribution. Tenneco Inc. leverages its vertically integrated exhaust manufacturing footprint across North America and Europe. Faurecia anchors high-volume contracts with premium European automakers through acoustic engineering specialization. Eberspächer differentiates via thermal management integration that bundles mufflers with catalytic hardware.
An automotive muffler is a resonant chamber device, typically fabricated from aluminized or 409-grade stainless steel sheet, designed to attenuate pressure-wave noise from internal combustion exhaust pulses while maintaining engine backpressure within calibrated limits. Direct-fit muffler assemblies command premium positioning due to vehicle-specific acoustic tuning and regulatory certification burden, whereas universal-fit variants compete on price in the fragmented aftermarket. Stainless steel materials sustain margin pools in performance and heavy-duty segments where thermal cycling resistance determines replacement intervals.
EPA tailpipe noise limits under the Noise Control Act, Euro 7 emission frameworks advanced by the European Commission, and China's GB standards enforced by the Ministry of Ecology and Environment collectively dictate product design cycles and testing protocols. Compliance with these overlapping regimes forces manufacturers to maintain parallel certification laboratories and region-specific tooling investments. Stakeholders must weigh acoustic material innovation against the accelerating shift toward electric vehicle platforms that eliminate traditional exhaust architectures entirely.
Market Dynamics
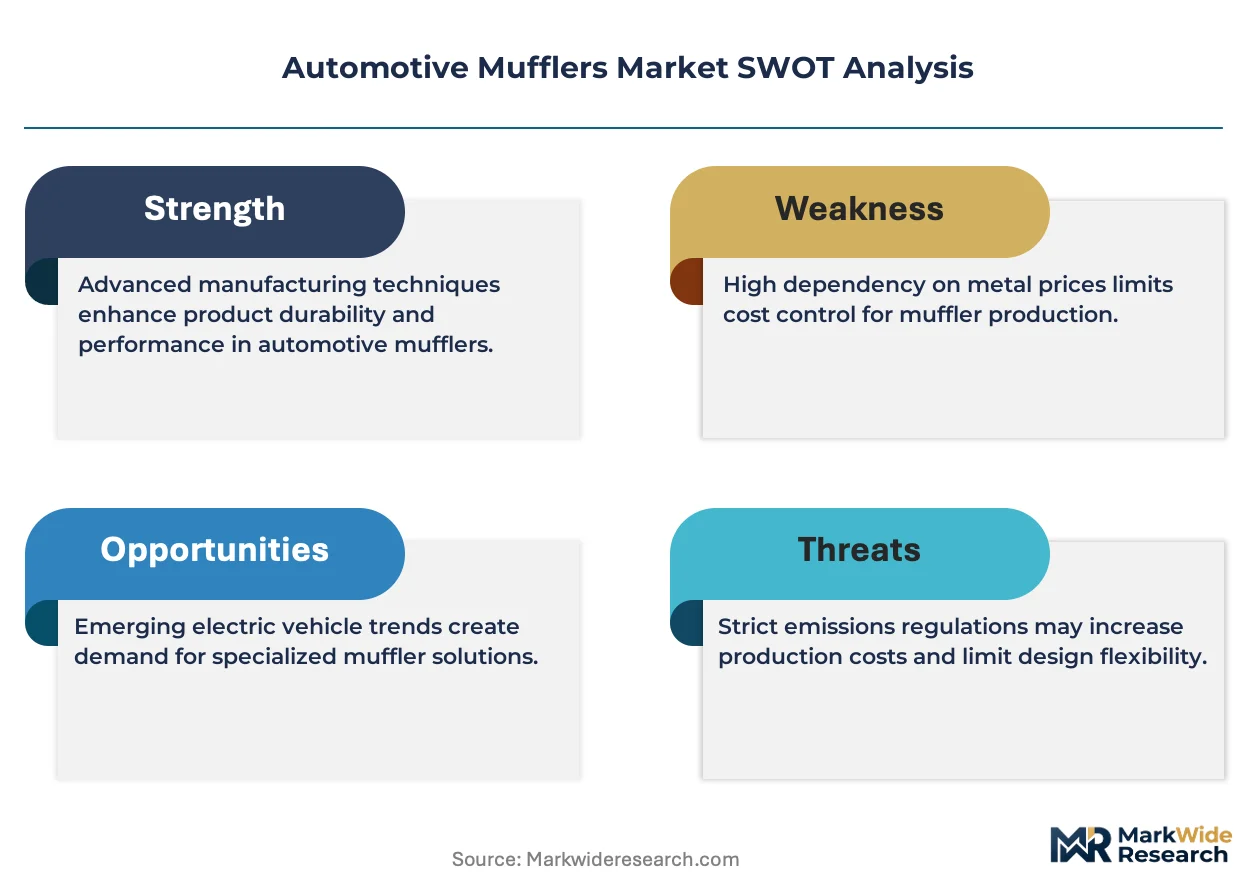
Electric vehicle adoption is systematically eliminating traditional exhaust architectures across passenger car platforms, forcing incumbent muffler manufacturers to restructure revenue models around residual ICE volumes and emerging thermal management applications.
Growth Catalysts
- Euro 7 acoustic mandates:Tighter noise limits from the European Commission are compelling vehicle manufacturers to upgrade muffler specifications across compact and mid-size platforms.
- China's eastern manufacturing corridor:Concentrated supplier ecosystems in Jiangsu and Zhejiang provinces serve both domestic OEMs and export programs with accelerated turnaround times.
- 409-grade stainless steel sheet:Enhanced thermal cycling resistance in heavy-duty applications extends replacement intervals and sustains premium positioning in commercial vehicle segments.
Market Restraints
- Aluminum and nickel price volatility:Raw material input costs for stainless steel substrates fluctuate with commodity markets, compressing margin pools on fixed-price OEM contracts.
- Single-source supply concentration:Tier 1 exhaust system integrators in Germany and Japan control access to vehicle-specific acoustic calibration data, limiting aftermarket competitor entry.
- Catalytic converter integration:Bundled aftertreatment hardware reduces discrete muffler procurement volumes as OEMs consolidate thermal management sourcing.
Strategic Opportunities
- India's commercial vehicle retrofit market:Stricter enforcement of BS VI emission norms by the country's automotive regulator creates demand for upgraded muffler assemblies in aging truck fleets.
- Active noise cancellation convergence:Integration of electronic acoustic management with passive resonant chambers opens premium positioning in luxury passenger car segments.
- EPA Tier 3 certification services:Third-party acoustic testing and regulatory documentation for export-bound manufacturers represents a high-margin service layer adjacent to hardware sales.
Industry Challenges
- Acoustic engineering talent scarcity:Specialized expertise in pressure-wave simulation and resonant chamber design concentrates at a handful of European and Japanese suppliers.
- Parallel certification laboratory requirements:Simultaneous compliance with EPA protocols, Euro 7 frameworks, and China's GB standards forces redundant testing infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Mufflers Market |
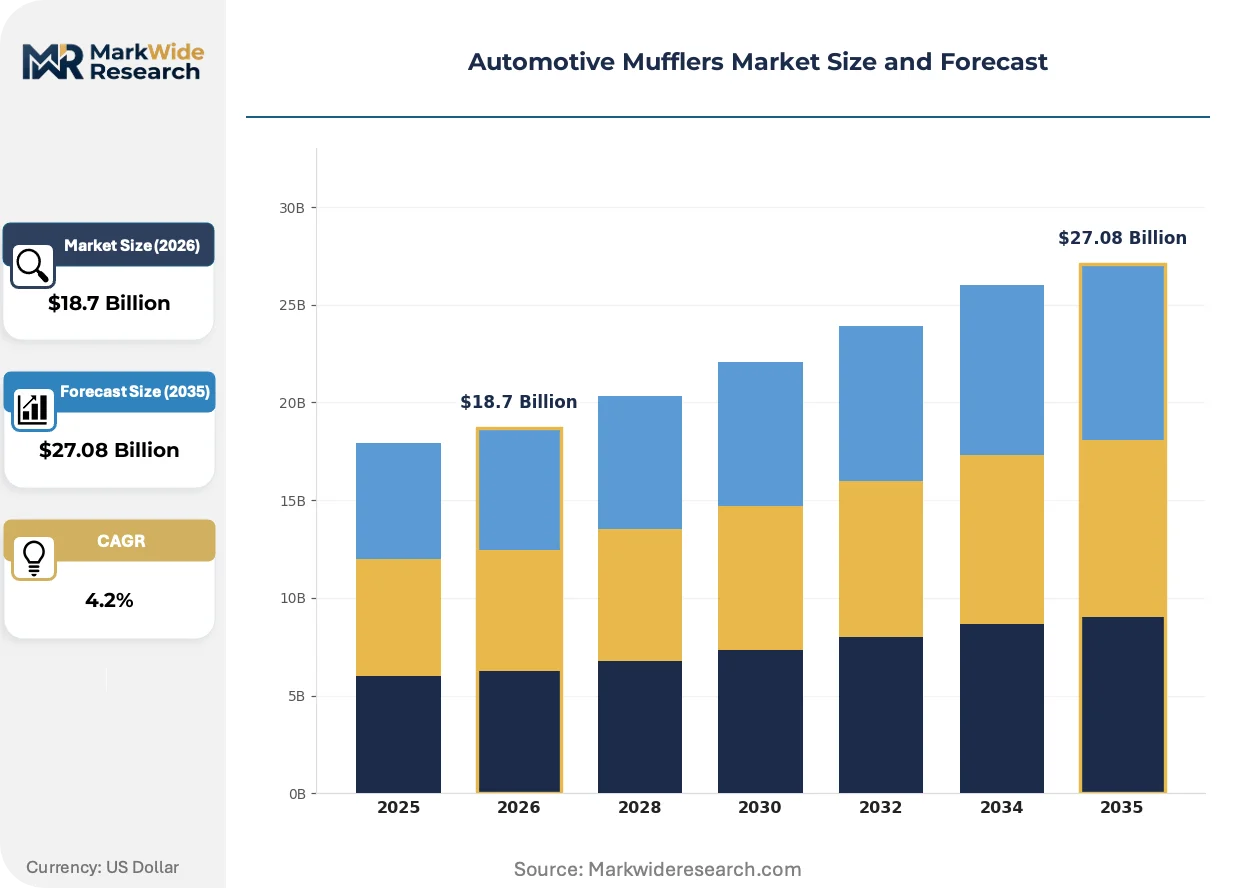
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Fit, Universal Fit, Performance, Heavy-Duty Material: Steel, Stainless Steel, Aluminum, Composite Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy Trucks Installation Type: OEM, Aftermarket, DIY, Professional |
| Companies Covered | Faurecia, Tenneco Inc., Eberspächer, Bosal, BENTELER International, Sango Co. Ltd., Yutaka Giken Co. Ltd., Dinex A/S, Futaba Industrial Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Mufflers Market Emerging Trajectories
Material substitution and electronic acoustic management are compressing traditional muffler architectures while regulatory fragmentation accelerates testing complexity across supplier bases.
Micro-perforated steel sheet technology is collapsing the distinction between passive and semi-active noise attenuation systems. Performance-oriented OEMs in Germany and Japan are specifying these substrates for sport variants where weight reduction trumps cost minimization. The structural consequence is collapsing demand for conventional multi-chamber baffle designs in premium segments.
EPA Tier 3 tailpipe noise enforcement is tightening acoustic measurement protocols for light-duty vehicles. Manufacturers must now document sound pressure levels across variable load conditions rather than steady-state testing. Heavy-duty pickup platforms in the United States face the steepest compliance burden, driving adoption of tunable resonator valves.
Fleet operators are unbundling after-sales service contracts from captive dealer networks. Independent service chains in China's coastal provinces now source direct-fit muffler assemblies through cross-border e-commerce channels, bypassing traditional tiered distribution. This pattern is most visible in the Yangtze River Delta, where logistics infrastructure supports rapid parts matching against vehicle identification databases.
Automotive Mufflers Market Segmentation
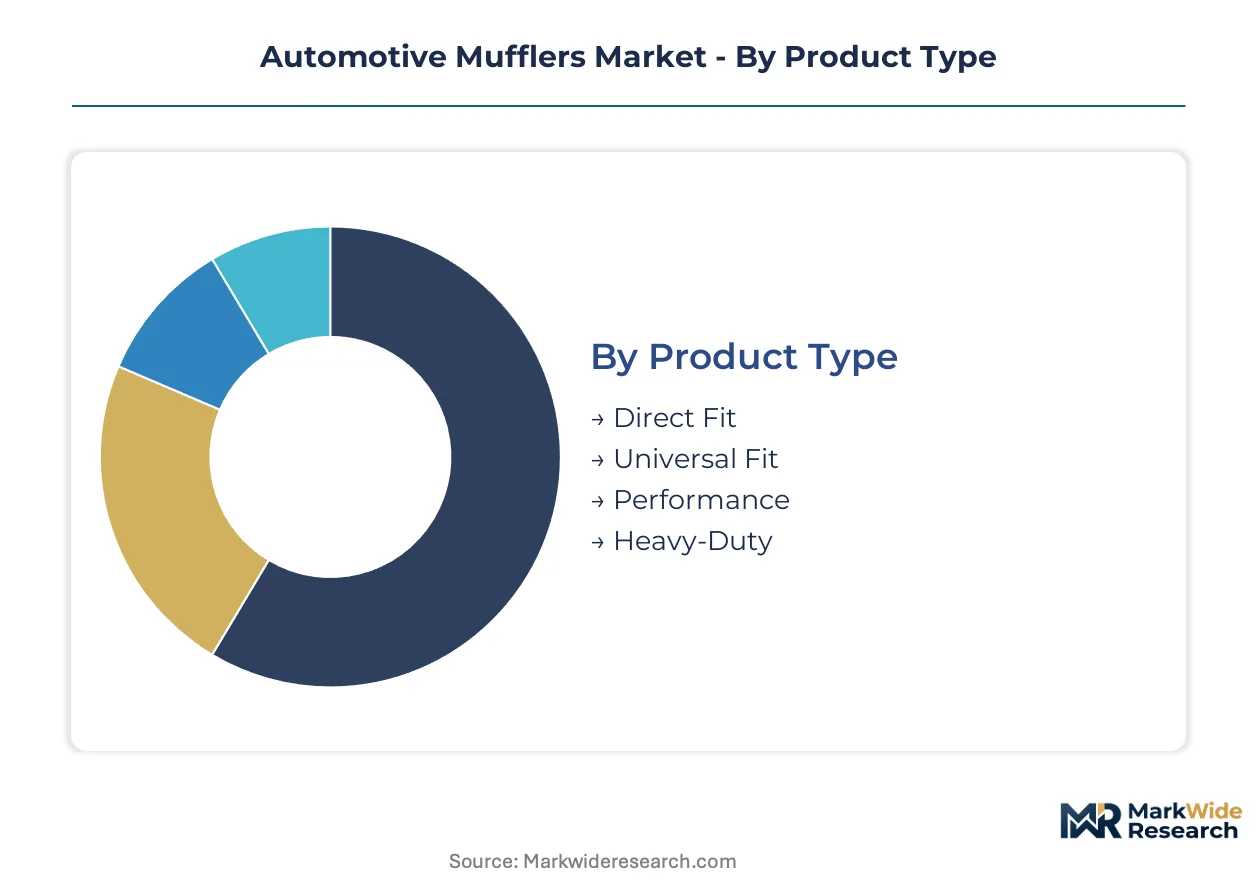
Muffler procurement patterns split sharply between vehicle-integrated systems and replacement channels, with material selection and installation economics determining margin architecture across each segment. Understanding these fault lines reveals where acoustic engineering investments concentrate versus where price competition dominates.
Product Type:
Mature direct-fit assemblies coexist with emerging active-valve configurations as OEMs balance regulatory compliance against electrification timelines.
- Direct Fit:Vehicle-specific acoustic calibration with certified backpressure tolerances commands premium positioning. Procurement concentrates with German and Japanese OEMs seeking Euro 7 pre-compliance ahead of enforcement deadlines.
- Universal Fit:Standardized inlet/outlet dimensions compete on price in fragmented aftermarket channels. Demand clusters in China's independent service networks where parts matching against VIN databases accelerates sourcing.
- Performance:Tunable resonator valves and straight-through designs target enthusiast segments.
- Heavy-Duty:409-grade stainless construction withstands thermal cycling in commercial applications.
Direct Fit handles the majority of throughput; Performance is the fastest mover on share.
Material:
Cost tiers separate commodity substrates from thermally engineered alloys where replacement intervals justify premium positioning.
- Stainless Steel:409-grade sheet dominates heavy-duty and performance segments with oxidation resistance extending service life. Jiangsu province mills supply both domestic Chinese OEMs and export programs to North American truck manufacturers.
- Steel:Aluminized mild steel serves economy passenger car platforms where first-owner replacement probability remains low.
- Aluminum:Weight-driven adoption in European compact cars faces nickel price volatility constraints.
- Composite:Glass-reinforced polymers penetrate motorcycle and niche electric range-extender applications.
Steel retains volume leadership; Stainless Steel climbs the fastest as warranty periods extend.
Vehicle Type:
Application-specific thermal loads and acoustic tolerances fragment engineering requirements across mobility categories.
- Passenger Cars:Compact and mid-size platforms drive Euro 7 upgrade cycles with integrated catalytic-muffler modules.
- Commercial Vehicles:Fleet operators in India's BS VI retrofit market generate replacement demand for aging truck exhaust systems.
- Heavy Trucks:Long-haul duty cycles prioritize 409-grade thermal durability.
- Motorcycles:Packaging constraints favor compact chamber designs with lightweight substrates.
Passenger Cars anchor procurement volumes; Commercial Vehicles show steepest expansion trajectory in retrofit channels.
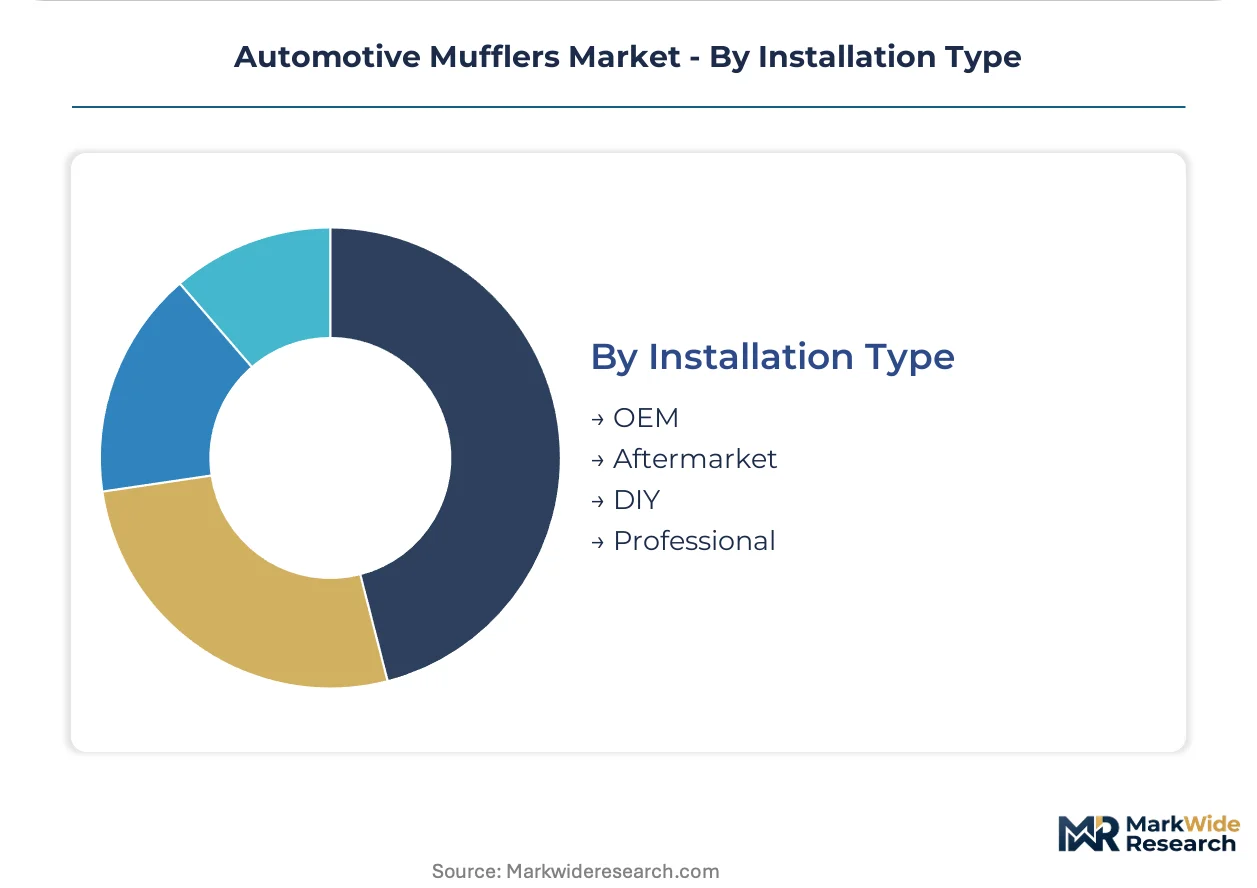
Installation Type:
Customer type determines margin capture with captive OEM networks defending position against independent service chains.
- OEM:Factory-integrated systems bundle acoustic calibration with powertrain warranty coverage. Tenneco and Faurecia anchor high-volume contracts through vertically controlled supply relationships.
- Aftermarket:Independent service chains in China's Yangtze River Delta bypass tiered distribution via cross-border e-commerce platforms.
- Professional:Dealer networks leverage diagnostic-linked parts matching to retain service revenue.
- DIY:Universal-fit price competition concentrates in online retail with minimal technical support.
OEM captures value share; Aftermarket is expanding most quickly as fleet operators unbundle from captive networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supplier ecosystems cluster in manufacturing corridors where steel mills, stamping facilities, and OEM assembly plants sit within 200-kilometer radii. This proximity shapes regional competitive dynamics more than consumer demand patterns.
China
Jiangsu and Zhejiang province mills supply 409-grade stainless sheet to domestic automakers and North American export programs. The Ministry of Ecology and Environment enforces GB standards that mandate acoustic testing across variable load conditions. Yangtze River Delta logistics infrastructure enables independent service chains to source direct-fit assemblies through cross-border e-commerce, bypassing traditional tiered distribution.
Germany
Premium European automakers anchor high-volume contracts requiring Euro 7 pre-compliance ahead of enforcement deadlines. The KBA mandates certification documentation that extends product development cycles. Baden-Württemberg acoustic engineering specialists concentrate pressure-wave simulation expertise at a handful of supplier headquarters.
United States
Heavy-duty pickup platforms face the steepest EPA Tier 3 compliance burden for tailpipe noise measurement. The EPA requires sound pressure documentation across variable load conditions rather than steady-state testing. Detroit-area vertically integrated exhaust manufacturers control access to vehicle-specific calibration data.
Japan
METI coordinates domestic OEM procurement of direct-fit muffler assemblies for compact and mid-size passenger car platforms. JIS standards govern thermal cycling resistance specifications that determine replacement intervals. Nagoya-area fabricators supply both domestic automakers and Southeast Asian export programs.
India
BS VI emission norm enforcement by the country's automotive regulator generates retrofit demand for aging commercial vehicle fleets. Central pollution control mandates drive replacement cycles in trucking corridors between Delhi and Mumbai. Gujarat-based stampers serve domestic OEMs while Maharashtra clusters focus on aftermarket distribution.
Automotive Mufflers Market Vendor Landscape
Vertically integrated system integrators and specialized acoustic engineering houses split the market along OEM-versus-aftermarket fault lines. The supplier base concentrates around three strategic archetypes: captive Tier 1 integrators controlling vehicle-specific calibration data, independent fabricators competing on price in fragmented service channels, and material specialists commanding premium positioning in thermal cycling applications. Dominant competitive moves include backward integration into steel sheet production and geographic expansion through licensing arrangements with regional stampers.
Among European-based acoustic specialists, Faurecia and Eberspächer exemplify the engineering-intensive tier where regulatory certification burdens create defensive moats. Tenneco Inc. represents the vertically integrated North American archetype with captive supply relationships across multiple OEM platforms. These three anchors occupy positions where Euro 7 and EPA Tier 3 compliance requirements favor incumbents with parallel laboratory infrastructure.
| Leading Market Players |
|---|
| Faurecia |
| Tenneco Inc. |
| Eberspächer |
| Bosal |
| BENTELER International |
| Sango Co. Ltd. |
| Yutaka Giken Co. Ltd. |
| Dinex A/S |
| Futaba Industrial Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Commodity volatility in nickel and aluminum sheet inputs compresses margin pools on fixed-price OEM contracts while simultaneously dictating three-tier pricing stratification across premium, standard, and economy levels. This cost pressure feeds directly into supply chain restructuring as manufacturers seek captive supply relationships or geographic diversification to buffer against raw material swings.
Pricing Analysis
Euro 7 and EPA Tier 3 dictate the pricing tier structure across direct-fit, universal-fit, and performance muffler categories. Certification-grade differentiation separates OEM-calibrated assemblies from aftermarket commodity variants, with acoustic engineering specialization commanding substantial premiums. Cost compression in the universal-fit tier is intensifying because Chinese cross-border e-commerce channels bypass traditional distribution markups. Fleet operators exhibit highest price sensitivity, while premium European automakers prioritize pre-compliance certification over unit cost.
Supply Chain Analysis
Vertically integrated exhaust manufacturers in Germany, China, and the United States hold dominant capacity positions across direct-fit muffler production. Raw material feeds draw from Jiangsu province stainless mills, Japanese specialty steel producers, and North American aluminized sheet suppliers. Single-source vulnerability concentrates in vehicle-specific acoustic calibration data controlled by Tier 1 integrators. Distribution runs through captive OEM networks, though China's Yangtze River Delta logistics infrastructure enables independent service chains to source direct-fit assemblies via cross-border platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive mufflers market sits at a late-cycle ICE phase where residual combustion platform volumes and thermal management pivot opportunities define strategic positioning. Recovery hinges on commercial vehicle retrofit demand and regulatory upgrade cycles rather than new passenger car growth.
For Market Incumbents: Insulate revenue streams by deepening backward integration into 409-grade stainless production and securing exclusive acoustic calibration data partnerships with German and Japanese OEMs ahead of Euro 7 enforcement. Thermal management bundling with catalytic hardware represents the priority defensive lever against discrete muffler volume erosion. For New Entrants and Emerging Players: India's BS VI retrofit corridor offers the most penetrable white-space for aging truck fleet upgrades, with Gujarat and Maharashtra distribution clusters supporting aftermarket entry. Independent service chains in China's coastal provinces present a second avenue through cross-border e-commerce sourcing relationships. A regulatory certification services play—offering EPA Tier 3 third-party acoustic testing—delivers high-margin entry without manufacturing scale requirements. For Investors and Strategic Acquirers: The market sits at a late-cycle contraction phase that favors acoustic engineering specialists with parallel laboratory infrastructure and captive OEM relationships. Long-term viability rests on thermal management pivot capabilities rather than pure-play muffler exposure. Watch India's enforcement velocity on commercial vehicle retrofit mandates as the primary inflection signal for aftermarket volume recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Production | Jiangsu province mill partnerships secure 409-grade supply against nickel price volatility. |
| Regulatory Certification Laboratory Expansion | Parallel EPA, Euro 7, and GB testing capability defends OEM contract access. |
| Active Noise Cancellation Technology Licensing | Electronic acoustic convergence opens premium positioning in German luxury segments. |
| India Commercial Vehicle Retrofit Channel Development | BS VI enforcement creates replacement demand in Delhi-Mumbai trucking corridors. |
| Thermal Management System Bundling | Catalytic-muffler integration captures consolidated aftertreatment sourcing from OEMs. |
Methodological Framework
Desk research of vehicle production databases, regulatory filing repositories, and steel trade flow records preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership service operations. Primary fieldwork across Germany's Baden-Württemberg engineering clusters, China's Jiangsu-Zhejiang manufacturing corridor, and Detroit-area vertically integrated suppliers was cross-validated against IHS Markit registration data and customs export statistics. Bottom-up volume builds triangulated against top-down OEM procurement estimates.
Assumptions held ICE platform volumes and regulatory enforcement timelines fixed while varying electric vehicle displacement velocity and commercial vehicle retrofit penetration rates. The analytical framework segmented by vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the analysis window. CAGRs were derived from regression against historical replacement intervals and regulatory upgrade cycle correlations, with thermal cycling resistance specifications and warranty period extensions serving as key volume inputs.
Practitioners should monitor nickel and aluminum commodity trajectories, Euro 7 enforcement delay signals, and India's BS VI retrofit compliance velocity for early forecast revision triggers. Quarterly review of OEM electrification announcements, heavy-duty fleet age distributions, and cross-border e-commerce parts flow data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Stainless Steel Tubes Market
Automotive Components
Global Automotive HUD Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
Automotive Key Market
Automotive Components
Australia Automotive Glass Fiber Composites Market
Automotive Components
Automotive Brake Pads Market
Automotive Components
Automotive Differential Market
Automotive Components
Automotive Spark Plug Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Automotive Brackets Market
Automotive Components
US Automotive Glass Fiber Composites Market
Automotive Components
Automotive Metal Stamping Market
Automotive Components
Automotive Air Deflector Market