
 Global Flexible Shaft Couplings Market | 2026-2036
Global Flexible Shaft Couplings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flexible Shaft Couplings Market Analysis
The EU Green Deal machinery efficiency framework is shifting procurement priorities across European industrial OEMs toward low-loss flexible couplings with verified energy performance. SKF leverages its integrated bearing-coupling portfolio to dominate aftermarket service contracts in Nordic process industries. Mayr GmbH + Co. KG anchors its position through specialized torque-limiting safety couplings for German automation lines. Nabeya Bi-tech Kaisha differentiates via ultra-precision disc couplings serving Japanese semiconductor equipment builders.
Flexible shaft couplings are mechanical devices that transmit torque between rotating shafts while accommodating angular misalignment, parallel offset, and axial displacement through elastomeric elements or metallic flexing members; typical specifications include torque ratings from fractions of a newton-meter to over one million newton-meter and operating speeds exceeding ten thousand RPM in precision applications. Grid couplings occupy the mature industrial maintenance segment where steel construction delivers durability in pulp and paper environments. Disc couplings lead growth in aerospace and high-speed turbomachinery where zero-backlash aluminum and stainless steel configurations satisfy critical alignment tolerances. Jaw couplings compete aggressively in automotive auxiliary drives where molded rubber spider elements enable cost-effective dampening of minor misalignment.
FDA equipment validation requirements for pharmaceutical processing machinery indirectly shape coupling specification in US hygienic applications, while REACH substance restrictions on elastomer formulations constrain rubber spider material selection across European supply chains. Japan's METI energy efficiency standards for industrial motors cascade into coupling procurement criteria through integrated system optimization mandates. Stakeholders must monitor evolving carbon border adjustment mechanisms and machinery-as-a-service contract structures that reframe coupling lifecycle accountability from capital purchase to performance guarantee.
Market Dynamics
EU Green Deal machinery efficiency mandates and METI energy conservation standards are cascading through industrial OEM procurement criteria, forcing coupling suppliers to verify energy loss coefficients and lifecycle carbon footprints alongside traditional torque ratings.
Growth Catalysts
- EU Green Deal machinery efficiency mandates:Industrial OEMs in Germany must document coupling energy losses, creating verified demand for low-hysteresis disc and diaphragm configurations in high-cycle automation.
- Semiconductor equipment builders:Japanese and Taiwanese fabs are specifying zero-backlash aluminum disc couplings for lithography and wafer handling stages, tightening alignment tolerances below 0.01 degrees.
- High-torque elastomeric formulations:Advanced hydrogenated nitrile rubber compounds now withstand 150°C continuous operation in steel mill auxiliary drives, extending jaw coupling service intervals.
Market Restraints
- Specialized alloy supply concentration:Precipitation-hardened stainless steel for high-speed disc couplings concentrates in Austrian and Swedish specialty mills, exposing aerospace suppliers to 18-month order backlogs.
- REACH substance restrictions:ECHA limitations on phthalate plasticizers in NBR spider elements force European manufacturers to reformulate at 15-20% higher compound cost.
- Magnetic couplings:Sealless pump and mixer applications in chemical processing are migrating to permanent-magnetic torque transmission, eliminating mechanical wear components entirely.
Strategic Opportunities
- Indian precision manufacturing clusters:Pune and Chennai automotive component hubs lack local high-speed disc coupling fabrication, creating white space for technical licensing partnerships.
- Integrated sensor-embedded couplings:Torque telemetry and misalignment monitoring via IoT strain gauges enables predictive maintenance contracts in Nordic pulp and paper mills.
- US pharmaceutical machinery:FDA equipment validation requirements for hygienic processing create specification pull for electropolished stainless steel couplings with full material traceability.
Industry Challenges
- Multi-axis alignment expertise:Precision turbomachinery installations require laser alignment technicians certified to ISO 21940 standards, a skill pool concentrated in German and Japanese service organizations.
- Legacy system interoperability:Retrofitting smart condition-monitoring couplings onto 1980s-era process equipment demands custom adapter flanges and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flexible Shaft Couplings Market |
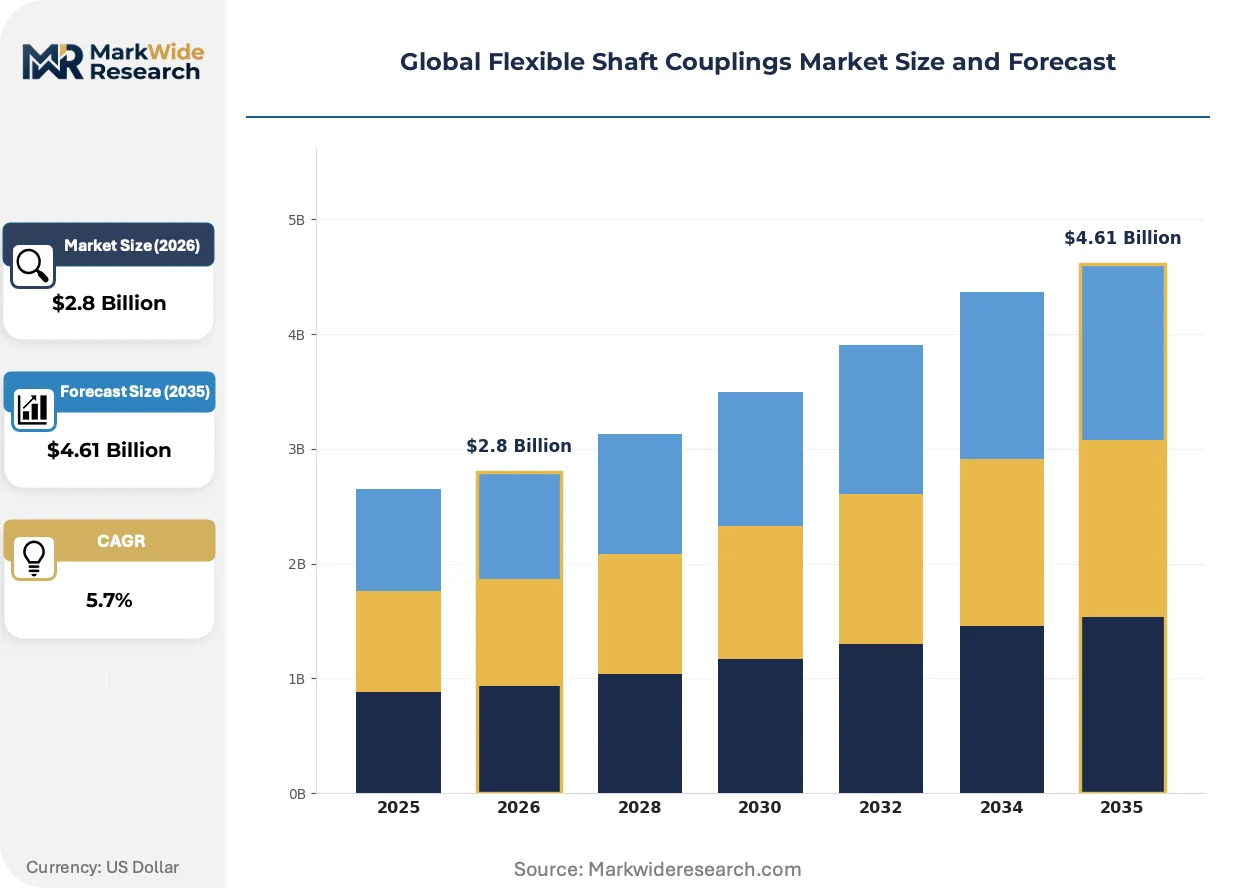
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grid Couplings, Jaw Couplings, Gear Couplings, Disc Couplings Material: Steel, Aluminum, Plastic, Rubber End User: Automotive, Aerospace, Industrial Machinery, Marine Installation Type: Onshore, Offshore, In-line, Direct Drive |
| Companies Covered | RENK Group AG, Mayr GmbH + Co. KG, SKF, Nabeya Bi-tech Kaisha, MW Industries, Regal Rexnord, Gates Corporation, KBK Antriebstechnik GmbH, Zero-Max, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flexible Shaft Couplings Market Emerging Trajectories
Active materials and embedded intelligence are redefining coupling functionality from passive torque transmission to predictive system components, while regulatory carbon accounting extends supplier accountability upstream.
Carbon fiber-reinforced polymer flex elements are expanding into high-speed test rig and aerospace ground support equipment where mass reduction directly improves acceleration response. Wind tunnel facilities at NASA Glenn and European transonic research centers specify these configurations for dynamometer drives. The shift is compressing traditional aluminum disc coupling specifications in rotational inertia-sensitive applications.
Japan's METI energy efficiency standards for industrial motors now cascade into integrated system optimization mandates, requiring coupling suppliers to document parasitic loss contributions. Japanese automation OEMs are demanding certified efficiency curves alongside torque-speed envelopes. High-volume servo motor applications in robotics and machine tools face the tightest compliance timelines.
Maintenance, repair, and overhaul procurement is consolidating through machinery-as-a-service contracts that transfer coupling lifecycle accountability from capital purchase to performance guarantees. Nordic process industries now specify availability-based service agreements where suppliers bear replacement cost risk. Paper mills in Finland and chemical processors in Rotterdam are piloting these structures for critical turbomachinery trains.
Global Flexible Shaft Couplings Market Segmentation
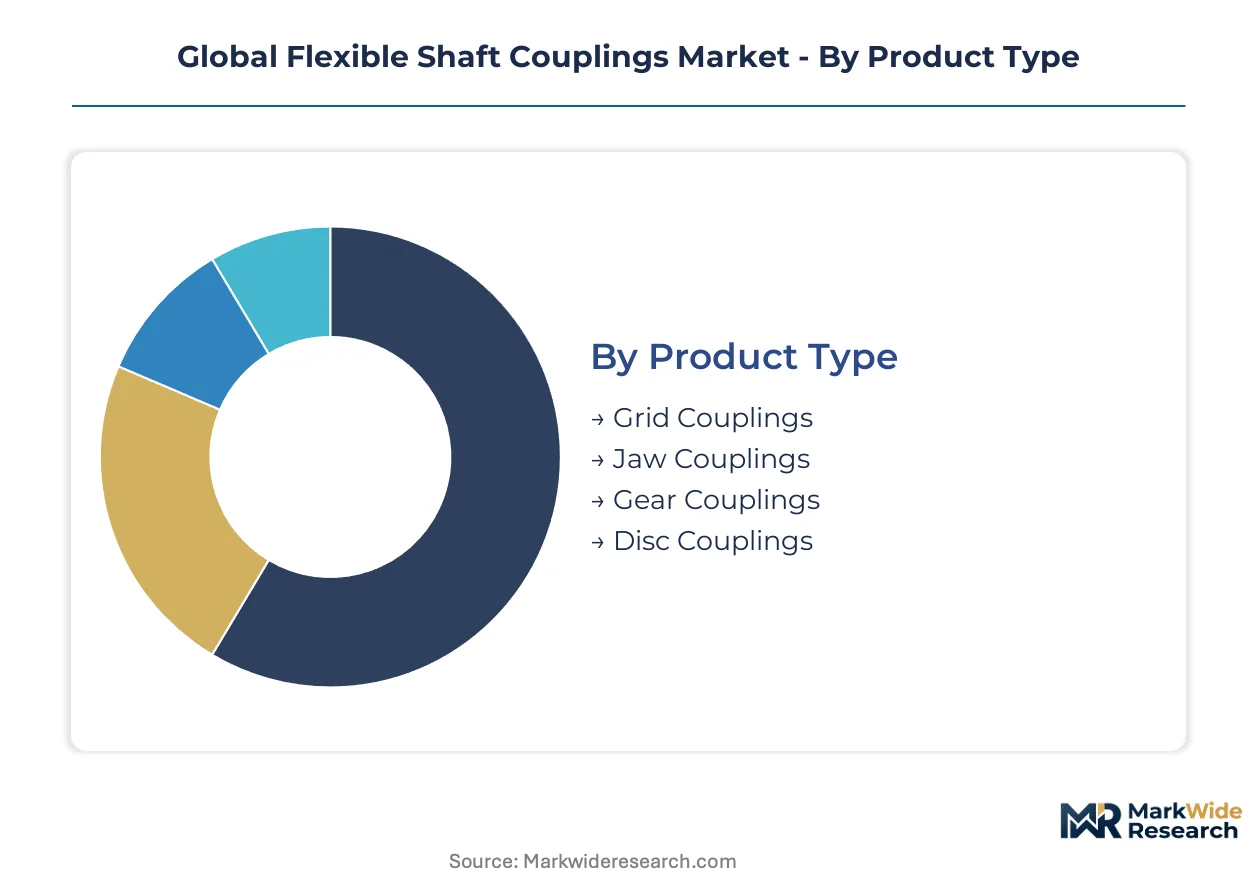
Segmentation in flexible shaft couplings reveals how capital allocation, material science, and installation constraints fragment procurement patterns across industrial verticals. Each dimension carries distinct margin profiles and technical barriers that shape supplier positioning.
Product Type:
Capital intensity escalates dramatically from elastomeric designs to precision metallic configurations, with aerospace-grade disc systems demanding 8-10x the tooling investment of standard jaw couplings.
- Grid Couplings:Laminated steel grid elements flex under torque load while maintaining mechanical durability in pulp mill dryer sections and mining conveyor drives. Demand concentrates in Nordic paper industry maintenance cycles where 20-year service life expectations dominate procurement specifications.
- Disc Couplings:Thin metallic diaphragms machined from precipitation-hardened stainless steel transmit torque with zero backlash in gas turbine and semiconductor stage applications. Japanese and Taiwanese lithography equipment builders specify these for alignment tolerances below 0.01 degrees.
- Jaw Couplings:Molded elastomer spiders dampen vibration in automotive auxiliary drives.
- Gear Couplings:Crowned tooth profiles accommodate angular misalignment in steel mill roughing stands.
Most installed capacity flows through Jaw Couplings. Expansion is steepest in Disc Couplings.
Material:
Raw material selection traces directly to thermal envelope and corrosion exposure, with specialty alloys commanding procurement priority in energy-critical systems.
- Steel:Alloy and carbon steel grades dominate heavy industrial applications where fatigue resistance outweighs mass considerations. German automotive press lines and US oilfield pumping units specify induction-hardened steel hubs for torque densities exceeding 10,000 Nm.
- Aluminum:7075-T6 and 6061-T6 aerospace alloys reduce rotational inertia in high-speed test rigs and robotic servo drives. NASA Glenn wind tunnel facilities specify carbon fiber-reinforced polymer alternatives for acceleration-sensitive dynamometer configurations.
- Rubber:Hydrogenated nitrile compounds extend temperature ratings to 150°C in steel mill auxiliary equipment.
- Plastic:Glass-reinforced polyamide serves light-duty packaging machinery where cost minimization drives specification.
Steel retains the dominant installed base. Aluminum is gaining share fastest in precision motion control.
End User:
End-use segmentation fragments by regulatory intensity, with FDA-validated pharmaceutical systems and FAA-certified aerospace drives imposing material traceability requirements absent in general industrial procurement.
- Industrial Machinery:Process pumps, compressors, and mixers in chemical and paper plants generate recurring aftermarket demand through wear-element replacement. EU Green Deal efficiency mandates now require documented energy loss coefficients for couplings in new German automation lines.
- Aerospace:Turbofan accessory drives and flight control actuators demand vacuum-melted superalloys with full lot traceability. Austrian and Swedish specialty steel mills concentrate supply for these precipitation-hardened grades, creating 18-month order backlogs.
- Automotive:Electric power steering and HVAC compressor drives specify molded rubber spiders for cost-effective misalignment accommodation.
- Marine:Propulsion shaft lines in commercial shipping favor torsionally flexible designs.
Industrial Machinery absorbs the majority of unit volume. Aerospace exhibits the steepest value-per-kilogram trajectory.
Installation Type:
Installation geometry determines accessibility for laser alignment procedures and condition monitoring integration, with offshore configurations imposing the most severe service logistics.
- In-line:Concentric shaft arrangements between motor and driven equipment dominate factory-floor installations. German and Japanese service organizations concentrate ISO 21940-certified laser alignment technicians for precision turbomachinery commissioning.
- Direct Drive:Elimination of intermediate bearings in servo motor and spindle applications demands ultra-low runout couplings. Japanese robotics OEMs face compressed compliance timelines under METI energy efficiency standards.
- Onshore:Land-based process equipment allows scheduled maintenance access.
- Offshore:Subsea pump and compressor trains require corrosion-resistant sealing and remote monitoring capability.
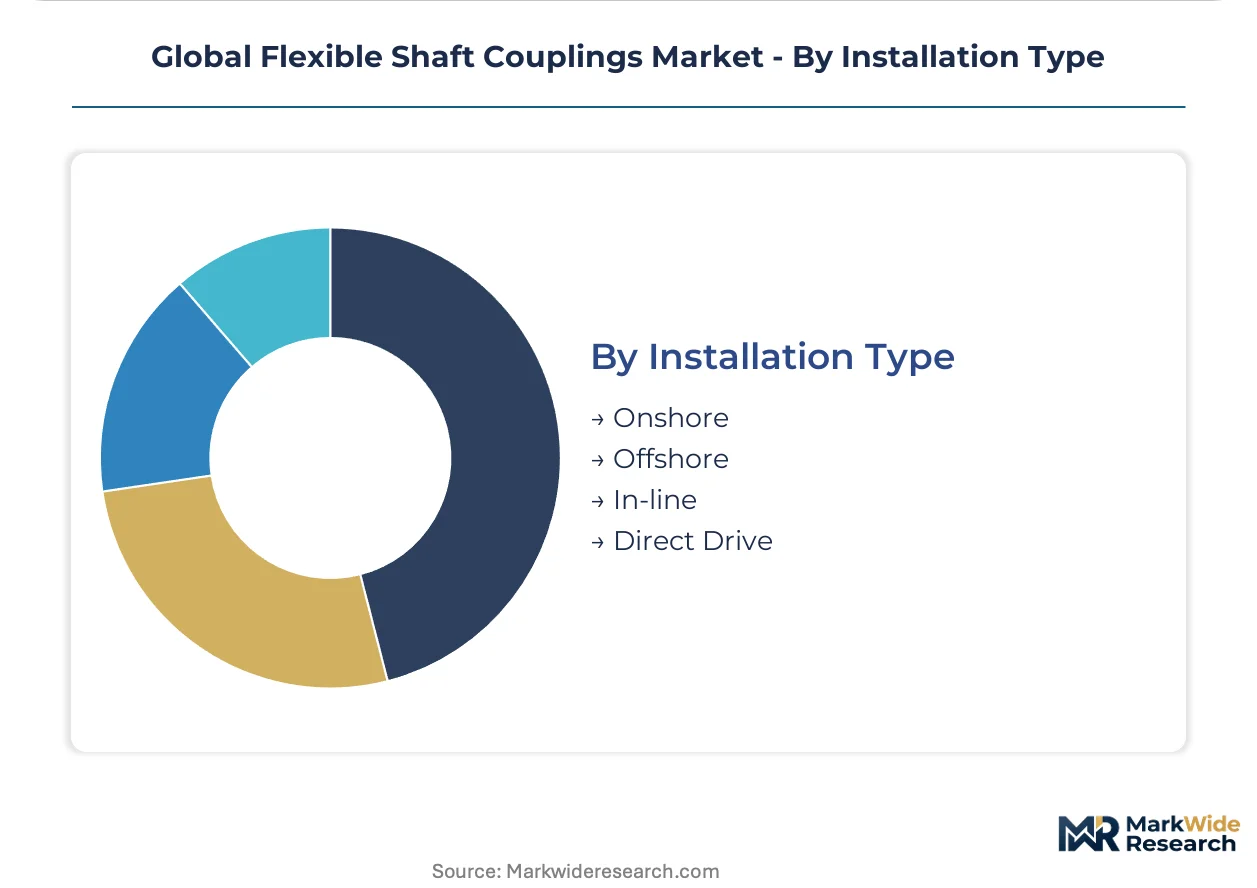
In-line configurations represent the dominant installed geometry. Direct Drive is expanding most quickly in precision automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision coupling manufacturing for heavy industrial applications during the post-war industrial expansion, establishing technical standards that continue to govern high-torque transmission design across European automation lines.
Germany
German automotive press lines and steel mill roughing stands drive sustained demand for crowned tooth gear couplings and induction-hardened steel hub configurations. The EU Green Deal machinery efficiency framework mandates documented energy loss coefficients for all new industrial equipment procurements. Bavarian automation OEMs now require verified low-hysteresis disc coupling specifications from suppliers seeking placement in next-generation production lines.
United States
US oilfield pumping units and pharmaceutical processing machinery generate divergent specification requirements spanning torque-dense steel constructions and electropolished stainless steel hygienic designs. FDA equipment validation protocols for aseptic processing create specification pull for full material traceability in Wisconsin and North Carolina biopharma clusters. NASA Glenn wind tunnel facilities in Ohio specify carbon fiber-reinforced polymer alternatives for acceleration-sensitive dynamometer configurations.
Japan
Japanese semiconductor equipment builders and robotics OEMs specify zero-backlash aluminum disc couplings for lithography stages and servo motor integration. METI energy efficiency standards for industrial motors cascade into coupling procurement criteria through integrated system optimization mandates. Nagoya-area machine tool manufacturers face compressed compliance timelines for documenting parasitic loss contributions in high-volume spindle applications.
China
Chinese precision manufacturing clusters in Yangtze River Delta and Pearl River Delta regions are expanding procurement of high-torque couplings for automotive component and electronics assembly automation. National dual carbon goals and provincial energy conservation directives reshape supplier qualification criteria toward documented lifecycle carbon footprints. Shenzhen and Suzhou semiconductor fabs are tightening alignment tolerance specifications below 0.01 degrees for wafer handling equipment.
India
Indian automotive component hubs in Pune and Chennai lack local fabrication capacity for high-speed disc couplings, creating technical licensing opportunities for precision coupling specialists. The Bureau of Indian Standards and state-level industrial policies encourage technology transfer partnerships in advanced manufacturing equipment. Maharashtra and Tamil Nadu precision manufacturing clusters currently import aerospace-grade coupling configurations for local automation line integration.
Global Flexible Shaft Couplings Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material certification and alignment precision tiers, with aerospace-grade vacuum-melted superalloy configurations commanding eight-to-tenfold tooling investment multiples over standard elastomeric designs. The vendor base organizes around three strategic archetypes: integrated bearing-coupling portfolio providers, specialized torque-limiting safety coupling fabricators, and ultra-precision disc coupling specialists. Competitive dynamics center on backward integration into specialty alloy supply and machinery-as-a-service contract structures that transfer lifecycle accountability from capital purchase to performance guarantees.
Within the integrated portfolio tier, SKF anchors aftermarket service positioning through combined bearing-coupling offerings. Mayr GmbH + Co. KG exemplifies the specialized safety coupling archetype with German GmbH structure. Nabeya Bi-tech Kaisha occupies a position among Japanese precision component specialists serving semiconductor equipment builders. These three entities represent distinct competitive vectors: aftermarket service consolidation, application-specific safety engineering, and sub-micron alignment tolerance fabrication.
| Leading Market Players |
|---|
| RENK Group AG |
| Mayr GmbH + Co. KG |
| SKF |
| Nabeya Bi-tech Kaisha |
| MW Industries |
| Regal Rexnord |
| Gates Corporation |
| KBK Antriebstechnik GmbH |
| Zero-Max, Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between aerospace vacuum-melted superalloys and commodity elastomeric designs manifests in eight-to-tenfold tooling investment spreads and captive supply arrangements for precipitation-hardened grades. This bifurcation concentrates procurement power among Austrian and Swedish specialty mills serving FAA-certified configurations while standard jaw coupling producers compete on compound reformulation costs under REACH phthalate restrictions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors the market, with aerospace-grade disc systems commanding superalloy premiums against automotive elastomeric commodities. Price differentiation rests on material certification tier and alignment precision grade, with ISO 21940-certified configurations capturing service bundling premiums. Cost compression in standard industrial tiers intensifies because of magnetic coupling substitution in chemical sealless applications. Automotive auxiliary drive OEMs exhibit highest price sensitivity, while semiconductor lithography equipment builders absorb premium positioning for sub-0.01-degree tolerance guarantees.
Supply Chain Analysis
Refurbishment flows for grid coupling elements in Nordic paper mills and remanufacturing programs for steel mill gear couplings extend service life expectations against new unit procurement. Geographic supply concentration centers on Germany, Japan, and Austria for precision metallic configurations, with China and India hosting expanding elastomeric spider production. Raw material dependencies draw from precipitation-hardened stainless steel, hydrogenated nitrile rubber compounds, and aerospace aluminum grades. Single-source vulnerability persists in vacuum-melted superalloy supply from Swedish specialty mills. Distribution runs through machinery OEM direct procurement and industrial aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible shaft couplings represent a late-cycle quality story as EU Green Deal efficiency mandates and METI energy conservation standards shift procurement toward verified low-hysteresis configurations with documented lifecycle accountability. Demand is concentrating in premium specifications that bundle predictive maintenance telemetry and carbon footprint certification.
For Market Incumbents: Deepen backward integration into specialty alloy supply to secure precipitation-hardened stainless steel allocations against 18-month order backlogs at Austrian and Swedish mills. Expand machinery-as-a-service contract structures in Nordic pulp and paper mills to capture lifecycle value from availability-based agreements. Magnetic coupling substitution in chemical processing presents the most acute substitution threat requiring defensive positioning through integrated sensor-embedded offerings. For New Entrants and Emerging Players: Begin with technical licensing partnerships in Pune and Chennai automotive component hubs where local high-speed disc coupling fabrication capacity remains absent. Indian precision manufacturing clusters offer the most penetrable white space given import dependence for aerospace-grade configurations. Target Bureau of Indian Standards compliance pathways and state-level technology transfer incentives as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where machinery-as-a-service contract capabilities separate premium-margin players from commodity producers in aftermarket service consolidation. Long-term viability favors integrated bearing-coupling portfolio providers and ultra-precision disc specialists with captive alloy supply. Watch for carbon border adjustment mechanism implementation as the signal indicating accelerated lifecycle accountability reframing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Captive access to precipitation-hardened grades from Austrian mills eliminates 18-month backlog exposure. |
| Integrated Sensor-Embedded Coupling Development | Torque telemetry via IoT strain gauges enables predictive maintenance contracts in Finnish paper mills. |
| Machinery-as-a-Service Contract Expansion | Availability-based agreements transfer replacement cost risk to suppliers in Rotterdam chemical processing. |
| Technical Licensing in Indian Manufacturing Clusters | Pune and Chennai hubs lack local fabrication capacity for high-speed disc coupling production. |
| EU Green Deal Compliance Certification Investment | Documented energy loss coefficients become mandatory for German automation OEM procurement qualification. |
Methodological Framework
Multiple input streams — primary interviews with maintenance directors and OEM procurement teams, secondary validation through customs data and industrial equipment filings, and technical specification analysis — were reconciled to construct segment-level demand estimates. Plant engineers at German automotive press lines, aftermarket service heads at Nordic pulp mills, and semiconductor equipment builders in Japan provided operational context. SEC filings, trade association reports, and national energy efficiency regulatory databases supplied secondary benchmarks. Bottom-up unit demand modeling and top-down industrial machinery investment flows were cross-referenced for triangulation.
Historical shipment patterns were cross-referenced against panel input from procurement executives to anchor growth trajectory assumptions across the analysis window. Segmentation dimensions modeled include product type, material grade, end-use industry, and installation geometry. CAGRs were derived from elasticity-adjusted industrial machinery capital expenditure forecasts and regulatory compliance timeline analysis. METI energy efficiency standard implementation schedules and EU Green Deal machinery efficiency mandate rollout provided industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced magnetic coupling technology breakthroughs, abrupt REACH substance restriction expansions, and geopolitical disruptions to specialty alloy trade flows. Forecasts reflect documented assumptions regarding regulatory compliance timelines and industrial OEM procurement cycle stability. Practitioners should monitor carbon border adjustment mechanism proposals and machinery-as-a-service contract penetration rates for early signals of pricing power redistribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Rear End Module Market
Automotive Components
Global Automotive Plastic Bumper Market
Automotive Components
Asia-Pacific Automotive Composites Market
Automotive Components
Aftermarket Automotive Parts & Components Market
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Australia Automotive Pneumatic Actuators Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
China Automotive Actuators Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
Automotive Polycarbonate Glazing Market
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
Electronic Clutch Actuators Market
Automotive Components
Automotive Engine Encapsulation Market