
 Automotive Stamped Component Market | 2026-2036
Automotive Stamped Component Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Stamped Component Market Analysis
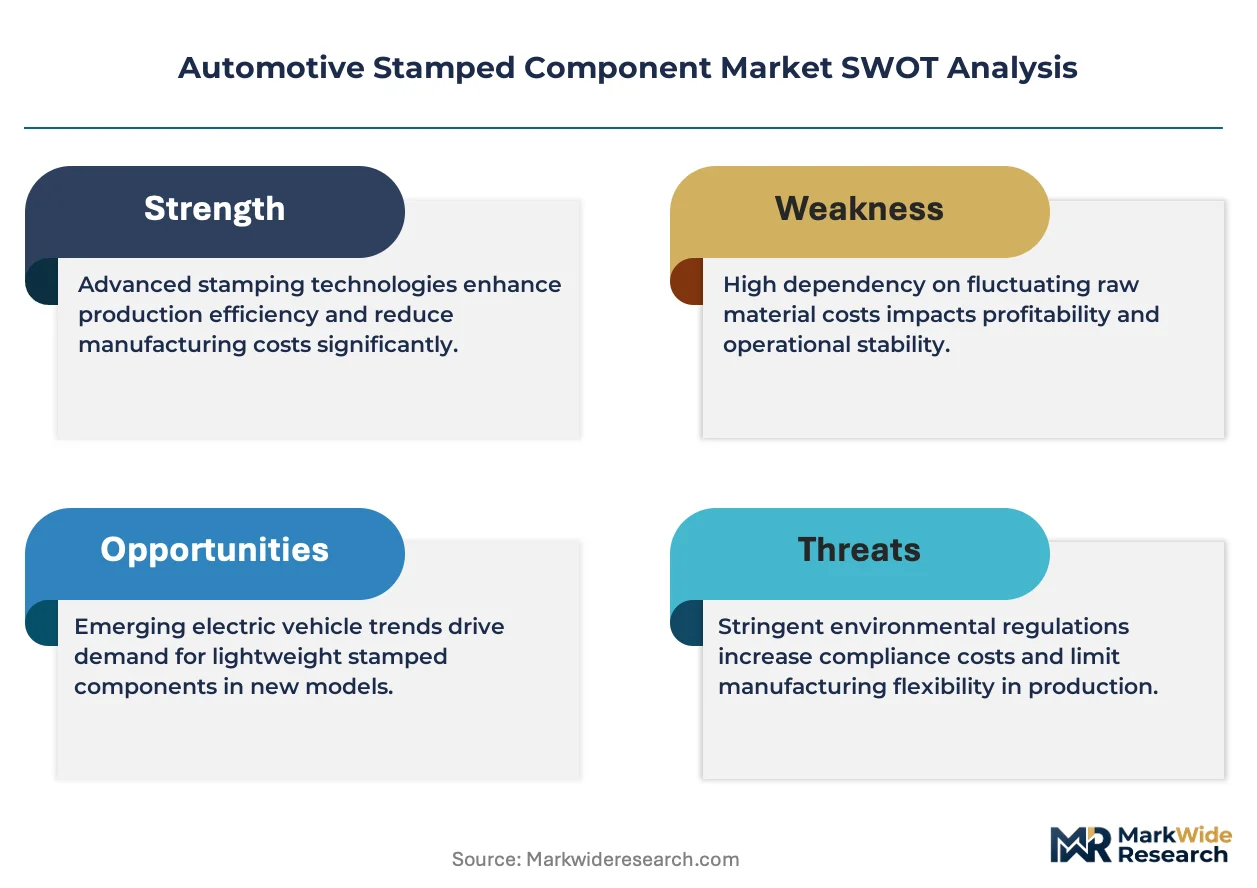
Electric vehicle chassis demand is restructuring the traditional stamped component procurement mix as battery-electric platforms require fundamentally different structural geometries than internal combustion architectures. Magna International leverages its modular platform expertise to anchor large-scale stamping contracts with EV-native OEMs across multiple continents. Gestamp Automoción sustains competitive positioning through advanced hot-forming capabilities that serve both legacy and electric vehicle programs. Benteler Automotive specializes in lightweight chassis subsystems, allowing it to differentiate where mass reduction directly correlates with battery range extension.
Automotive stamped components are metal parts produced through mechanical or hydraulic pressing operations, typically using cold-rolled steel or aluminum sheet stock ranging from 0.5 to 6.0 millimeters in thickness, designed to achieve precise dimensional tolerances for structural integrity and crash performance. These components serve as the skeletal framework of vehicles, transferring loads, maintaining occupant compartment geometry, and enabling assembly of powertrain, suspension, and closure systems. Body panels and structural parts represent the highest-value segments where OEMs concentrate direct sourcing relationships, while chassis components face margin compression as tier-1 suppliers compete on scale and steel procurement leverage. Aluminum stamping is gaining share within material categories as crashworthiness requirements and weight targets intensify, though steel retains dominance in high-volume A-segment and B-segment vehicle programs where cost sensitivity constrains material substitution.
The EPA's vehicle emissions standards and the EU's F-Gas Regulation are reshaping material specifications and supplier qualification requirements across the automotive stamping value chain. NHTSA crash safety protocols and China's GB standards mandate specific performance thresholds that dictate alloy selection, thickness optimization, and joining method investments. Stakeholders must monitor how battery-electric vehicle platform consolidation affects component commonality strategies and whether regional content rules under evolving trade frameworks alter stamping capacity placement decisions.
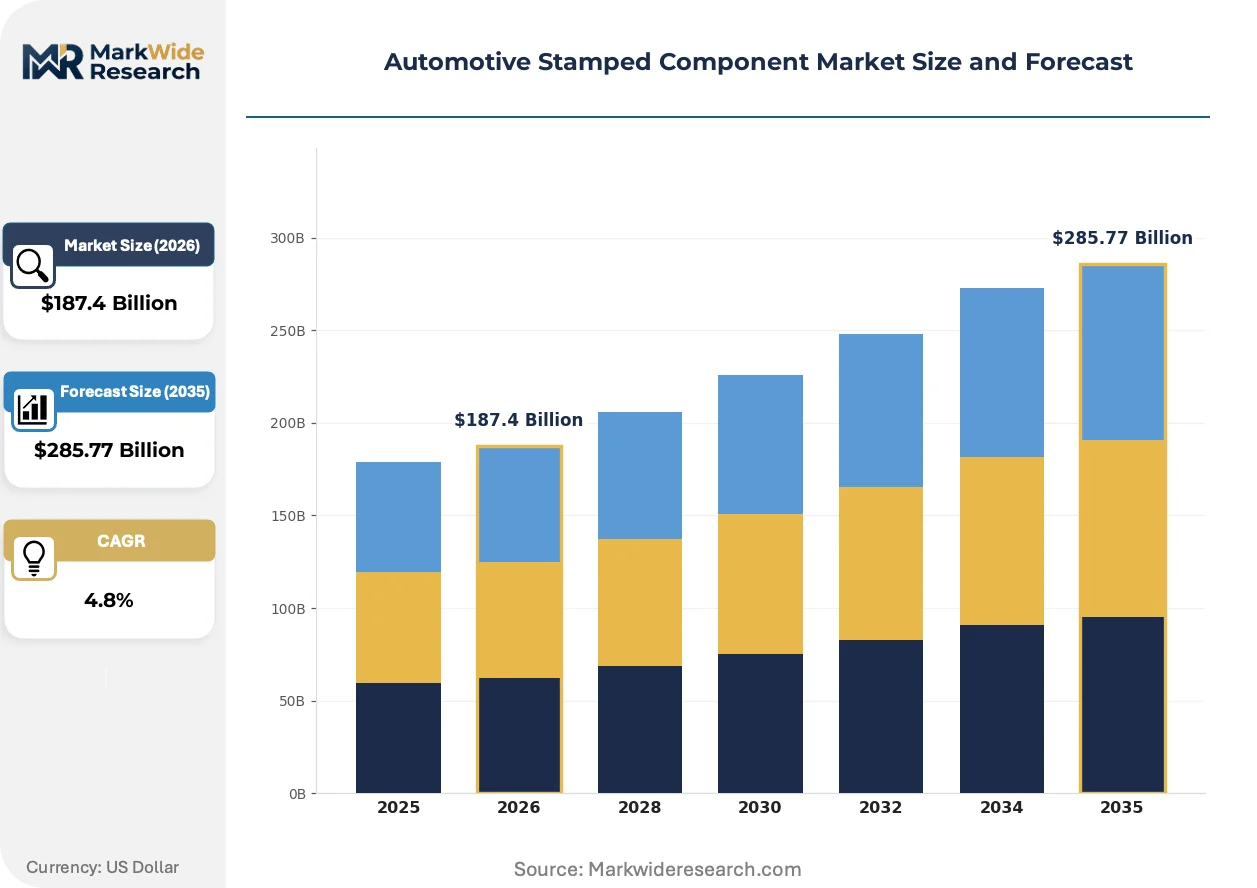
Market Dynamics
Battery-electric vehicle platform architectures are dismantling long-established component geometries and procurement hierarchies that governed stamped metal supply for internal combustion drivetrains. OEMs now specify entirely new chassis load paths, battery enclosure stampings, and structural assemblies that obsolete legacy tooling investments and supplier qualification frameworks.
Growth Catalysts
- EU Green Deal embodied carbon rules:Steel and aluminum suppliers face mandatory carbon intensity disclosures that favor low-carbon primary metal and recycled feedstock, redirecting procurement toward certified low-emission mills in Germany and Sweden.
- Hot-forming process advancement:Ultra-high-strength steel grades now achieve 1500 MPa tensile strength post-forming, enabling thinner gauge sections that satisfy NHTSA roof crush standards while trimming chassis mass for electric range extension.
- China's dual carbon goals:Domestic OEMs localize stamped component sourcing around battery-electric vehicle production clusters in Shanghai, Hefei, and Xi'an, concentrating demand for aluminum-intensive body-in-white assemblies.
Market Restraints
- Aluminum sheet price volatility:Primary aluminum ingot costs fluctuate with electricity pricing and smelter curtailments, compressing margins on lightweighting programs where material substitution was already cost-negative versus cold-rolled steel.
- Tooling lead time concentration:Large transfer press dies require 18-24 month design-to-production cycles, locking suppliers into volume commitments before final vehicle program approval and creating stranded asset risk if platforms are cancelled.
- Steel scrap quality fragmentation:Post-consumer automotive scrap contains copper contamination from wiring harnesses, degrading downstream stamping performance and forcing reliance on prime virgin material for visible body panels.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced automotive technology manufacturing attract stamping capacity investments serving domestic electric two-wheeler and passenger vehicle assembly.
- Aluminum-steel multi-material joining:Self-piercing rivets and flow-drill screws enable hybrid body structures that optimize crash performance per kilogram, opening new engineering service contracts for tier-1 integrators.
- Battery enclosure stampings:Floor pan and tunnel reinforcements for skateboard platforms represent a greenfield component category with no legacy supplier incumbency, rewarding early capital deployment in 6000-series aluminum forming.
Industry Challenges
- Die tryout technician scarcity:Experienced toolmakers capable of final die tuning on 4,000-ton mechanical presses are retiring faster than apprenticeship programs replenish the workforce, extending new program launch timelines.
- GB standard homologation complexity:China's type approval process for stamped structural components requires in-country testing and documentation in Mandarin, creating compliance overhead for foreign suppliers without established certification infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Stamped Component Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chassis Components, Body Panels, Structural Parts, Brackets Material: Steel, Aluminum, Composite, Magnesium End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Stage: Stamping, Finishing, Assembly, Supply Chain Management |
| Companies Covered | Magna International, Gestamp Automoción, Martinrea International, Autokiniton, Benteler Automotive, Aisin Corporation, Shiloh Industries, CIE Automotive, JBM Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Stamped Component Market Emerging Trajectories
Stamping operations are converging with in-line sensing and adaptive control systems that transform quality assurance from post-process inspection to real-time dimensional correction during forming cycles.
Hot stamping with press-hardened boron steel is integrating inline temperature monitoring and closed-loop cooling rate control to eliminate springback variability in A-pillar and B-pillar reinforcements. European OEMs specify these components for five-star Euro NCAP side-pole impact compliance. The technology is integrating quality assurance directly into the forming die, compressing traditional offline CMM verification cycles and reducing scrap rates on complex geometries.
EPA vehicle emissions standards and the EU F-Gas Regulation are mandating lower-global-warming-potential refrigerants and lighter vehicle mass to achieve fleet-average CO2 targets. Stamped aluminum HVAC housings and structural heat exchanger supports displace cast magnesium in electric thermal management systems. Suppliers in Germany and the United States are responding with dedicated aluminum servo press lines and laser-welded blank processing to meet tightened tolerance stacks.
Direct sourcing contracts are consolidating formerly fragmented tier-2 and tier-3 stamping volumes under tier-1 platform integrators who assume full subsystem responsibility. Battery-electric vehicle startups in California and Texas bypass traditional supply hierarchies, awarding complete chassis stamping and assembly programs to single-source partners. This concentration is most visible in North American electric truck programs where vertical integration of stamping and welding accelerates prototype-to-production timelines.
Automotive Stamped Component Market Segmentation
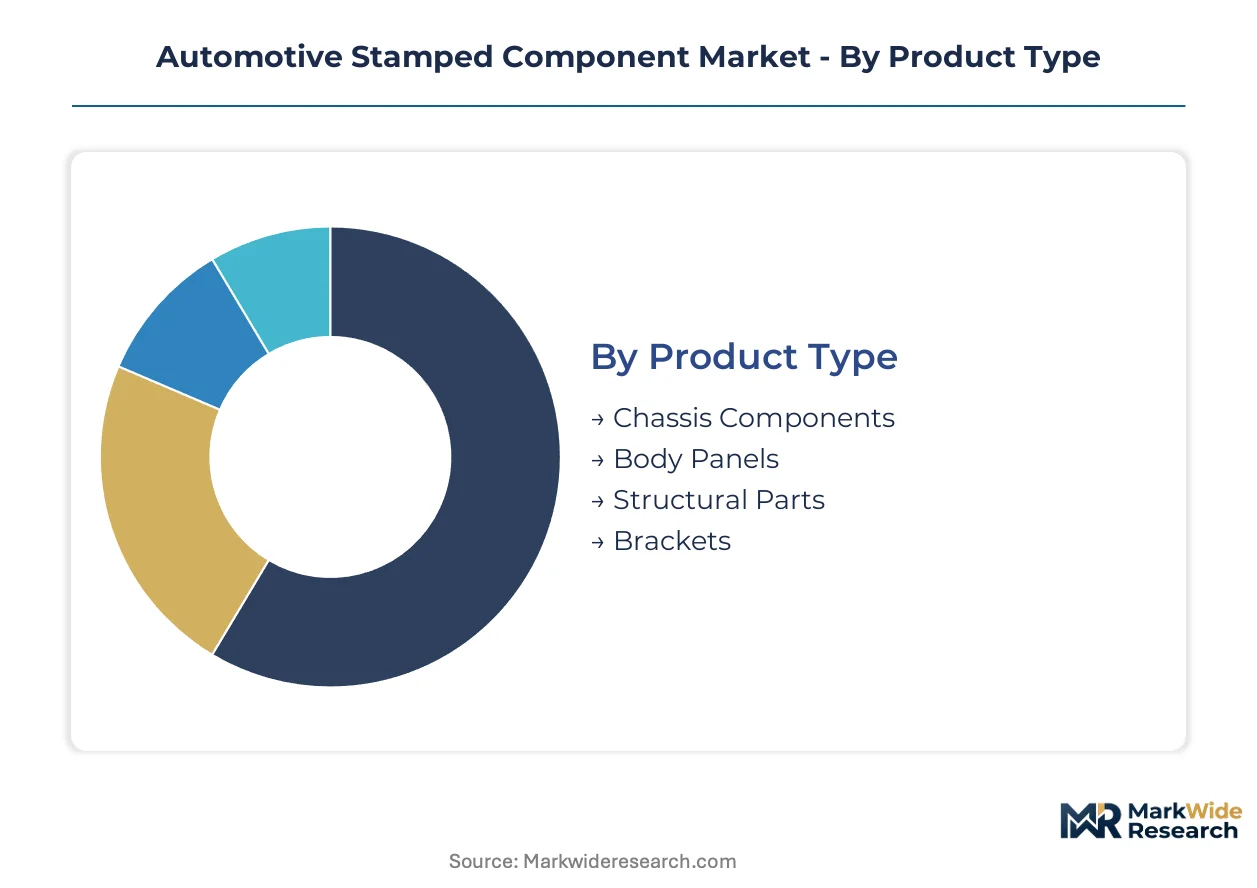
Stamped component procurement splits along program lifecycle stages and material certification tiers. OEM sourcing strategies diverge sharply between legacy internal combustion platforms and battery-electric architectures, reshaping volume allocation across traditional segment boundaries.
Product Type:
Customization intensity varies from mass-produced brackets to vehicle-specific body panels requiring dedicated die sets and surface quality protocols.
- Chassis Components:Suspension mounts, subframes, and crossmembers formed from high-strength steel grades. Battery-electric vehicle platforms in Germany and China are concentrating demand for aluminum-intensive chassis stampings as skateboard architectures displace traditional ladder-frame designs.
- Body Panels:Hoods, doors, fenders, and quarter panels where surface finish requirements dictate Class A surface tooling investments. OEMs in the United States maintain direct sourcing relationships for these highest-value stampings to control exterior quality and brand differentiation.
- Structural Parts:Pillars, rails, and reinforcements engineered for crash energy management. Hot-formed boron steel grades dominate A-pillar and B-pillar applications where NHTSA roof crush compliance mandates 1500 MPa tensile strength.
- Brackets:Small-gauge mounting hardware and attachment points produced on high-speed progressive dies. Tier-1 suppliers consolidate these volumes through multi-program tooling to amortize die costs across vehicle platforms.
Most installed capacity flows through Body Panels. Expansion is steepest in Structural Parts.
Material:
Cost tier stratification separates commodity steel from premium aluminum and experimental lightweight alloys.
- Steel:Cold-rolled and hot-rolled sheet stock from 0.5 to 6.0 millimeters thickness, comprising the majority of chassis and structural stampings. The EU Green Deal embodied carbon rules are redirecting procurement toward certified low-emission mills in Germany and Sweden.
- Aluminum:5000-series and 6000-series alloys specified for closure panels and battery enclosures where mass reduction extends electric range. Primary aluminum ingot price volatility in China is compressing margins on lightweighting programs.
- Composite:Fiber-reinforced thermoplastic stampings for non-structural applications. Limited adoption in high-volume programs due to cycle time constraints and recycling infrastructure gaps.
- Magnesium:Thixomolded and stamped alloys for instrument panel substrates and steering wheel cores. Niche applications face substitution pressure from aluminum in electric vehicle thermal management systems.
Steel commands the largest share of installed press tonnage. Aluminum is climbing the fastest as battery-electric vehicle production scales.
End User:
Supply chain position determines specification authority and volume commitment certainty.
- OEMs:Vehicle manufacturers with direct stamping contracts for body-in-white and closure panels. Volkswagen, Tesla, and BYD operate captive stamping capacity or award long-term exclusive supply agreements.
- Tier-1 Suppliers:Platform integrators like Magna International and Gestamp Automoción consolidating subsystem responsibility. These firms assume die ownership and weld assembly risk for complete chassis modules.
- Aftermarket Providers:Replacement panel and collision repair part producers. Quality variance is wider in this channel where reverse-engineered dies lack OEM surface finish calibration.
- Vehicle Assemblers:Contract manufacturers and startup EV brands without legacy stamping infrastructure. These buyers rely entirely on tier-1 partners for chassis and body component supply.
Tier-1 Suppliers absorb the majority of capital-intensive die investments. Vehicle Assemblers are expanding their procurement footprint fastest as EV startups proliferate.
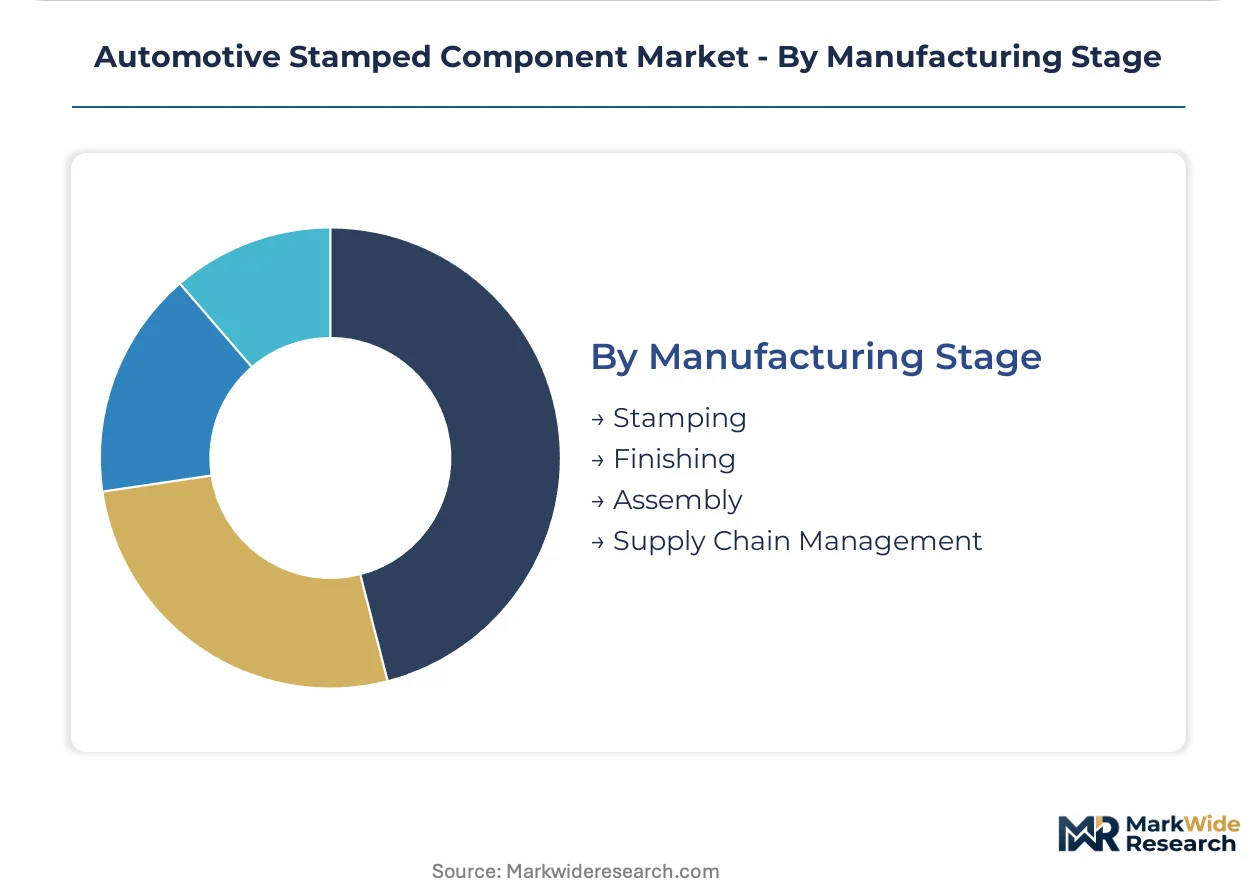
Manufacturing Stage:
Maturity gradients separate commoditized raw stamping from value-added assembly services.
- Stamping:Blanking, forming, and drawing operations on mechanical or hydraulic presses. Die tryout technician scarcity in Germany and Japan is extending new program launch timelines.
- Finishing:Edge trimming, hole piercing, and surface treatment processes. E-coat compatibility requirements for aluminum stampings add process complexity and capital intensity.
- Assembly:Welding, riveting, and adhesive bonding of stamped subcomponents. Battery enclosure assembly demands cleanroom conditions and leak-test protocols foreign to traditional chassis operations.
- Supply Chain Management:Logistics coordination and sequencing for just-in-time delivery to vehicle assembly plants. OEM consolidation around production hubs in Shanghai, Hefei, and Austin is concentrating supplier footprint decisions.
Stamping retains the largest share of industry employment and fixed assets. Assembly is gaining share fastest as tier-1 integrators expand subsystem scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting stamping capacity toward jurisdictions where embodied carbon compliance costs diverge sharply, with OEMs relocating supply contracts to exploit gaps between EU Green Deal enforcement and less stringent alternative frameworks.
United States
Domestic OEMs are consolidating chassis stamping contracts around Austin and Detroit battery-electric vehicle hubs. NHTSA crash safety protocols mandate specific alloy selection for structural stampings. Texas and Michigan production clusters absorb the majority of new 6000-series aluminum press line investments.
Germany
Volkswagen and BMW are redirecting procurement toward certified low-emission steel mills under EU Green Deal embodied carbon disclosure rules. KBA type approval requirements enforce strict dimensional tolerance verification. The Ruhr Valley and Bavaria retain concentration of hot-forming capacity for ultra-high-strength boron steel applications.
China
Domestic OEMs localize stamped component sourcing around Shanghai, Hefei, and Xi'an battery-electric production clusters. GB standards homologation requires in-country testing and Mandarin documentation. MIIT dual carbon goals are tightening embodied carbon thresholds for steel and aluminum inputs.
India
The PLI scheme for auto components is attracting stamping capacity investments serving electric two-wheeler and passenger vehicle assembly. BIS certification requirements govern structural component quality tiers. Maharashtra and Gujarat industrial corridors concentrate new progressive die installations for bracket and chassis hardware.
Japan
Japanese OEMs maintain captive stamping expertise for hybrid and battery-electric platform transitions. METI energy efficiency standards influence press line electrification and servo drive adoption. The Nagoya and Tokyo industrial basins preserve specialized die tryout technician training pipelines.
Automotive Stamped Component Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-1 integrators consolidating formerly fragmented tier-2 volumes while pure-play stampers defend niche positions. The structure tilts toward oligopoly in high-value body panels where OEMs maintain direct relationships, while chassis components face commoditization pressure. Three archetypes dominate: platform integrators with subsystem responsibility, material specialists leveraging aluminum or hot-forming capabilities, and regional contract manufacturers serving vehicle assemblers without captive capacity. Competitive moves center on die ownership consolidation and geographic proximity to battery-electric vehicle production hubs.
Among North American platform integrators, Magna International and Martinrea International exemplify the tier-1 consolidation archetype, anchoring large-scale stamping and assembly programs across multiple OEM customers. Gestamp Automoción occupies a position representing European hot-forming specialization, with capabilities spanning both legacy and electric vehicle structural programs. These three companies illustrate how scale and process technology differentiation separate market positions.
| Leading Market Players |
|---|
| Magna International |
| Gestamp Automoción |
| Martinrea International |
| Autokiniton |
| Benteler Automotive |
| Aisin Corporation |
| Shiloh Industries |
| CIE Automotive |
| JBM Group |
| Others |
Supply Flow & Price Mechanics
Aluminum ingot cost volatility feeds directly through tier-1 supplier margins into OEM contract renegotiation cycles, with battery-electric vehicle chassis programs bearing the steepest pass-through pressure as 6000-series alloy specifications displace conventional cold-rolled steel.
Pricing Analysis
Direct-to-OEM contract structures dominate high-volume body panel procurement, compressing distributor margins to single-digit percentages while tier-1 integrators capture assembly value-add. Price differentiation separates hot-formed boron steel structural grades from commodity cold-rolled specifications, with NHTSA roof crush compliance certification commanding measurable premiums. Pricing pressure intensifies in aluminum-intensive chassis components as Shanghai metal exchange volatility feeds into quarterly contract adjustments. Tier-2 bracket suppliers face the highest price sensitivity due to multi-program tooling amortization constraints and progressive die commoditization.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke patterns for just-in-time sequencing to battery-electric vehicle assembly plants. Raw material flows draw from Swedish low-carbon steel mills, Chinese primary aluminum smelters, and Japanese ultra-high-strength steel producers. Single-source vulnerability concentrates in large transfer press die manufacturing, where 18-24 month lead times lock suppliers before final vehicle program approval. Distribution runs through tier-1 platform integrators who assume die ownership and weld assembly risk for complete chassis modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automotive stamped components rests on aluminum substitution premiums and hot-forming technology differentiation that command pricing power above commodity steel benchmarks.
For Market Incumbents: Deepen captive supply relationships with certified low-emission steel mills in Germany and Sweden to preempt EU Green Deal carbon disclosure penalties. Secure die tryout technician pipelines through apprenticeship partnerships in Japan and Bavaria to compress new program launch timelines against emerging platform integrators. For New Entrants and Emerging Players: Begin with battery enclosure stampings for skateboard EV platforms, where no legacy supplier incumbency exists and 6000-series aluminum forming expertise commands first-mover premiums. Target vehicle assembler partnerships in Texas and Hefei that bypass traditional tier-1 hierarchies and award complete chassis programs to single-source partners. For Investors and Strategic Acquirers: Roll-up economics work for regional hot-forming specialists because die ownership concentration and OEM platform consolidation favor scaled operators with multi-continent qualification frameworks. Monitor aluminum-steel multi-material joining capability buildouts as the inflection signal for tier-1 integrator competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Forming Capacity Expansion | 1500 MPa boron steel capability secures Euro NCAP five-star structural contracts with Volkswagen and BMW. |
| Aluminum Servo Press Line Investment | 6000-series forming equipment captures battery enclosure demand from Tesla and BYD skateboard platforms. |
| Low-Carbon Steel Mill Partnership | Certified emission disclosures satisfy EU Green Deal procurement mandates for German OEM body-in-white programs. |
| Die Tryout Technician Apprenticeship | Workforce pipeline compression addresses 4,000-ton press calibration scarcity extending launch timelines. |
| Multi-Material Joining Capability | Self-piercing rivet and flow-drill screw integration enables hybrid aluminum-steel chassis engineering contracts. |
Methodological Framework
Bottom-up vehicle production modeling reconciled against top-down steel and aluminum consumption tracking forms the analytical core of this study. Primary interviews with tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and die manufacturing specialists combined with secondary validation from vehicle registration databases, IHS Markit production data, customs trade records, and SEC filings from listed automotive suppliers. Triangulation across these sources ensures volume and value estimates reflect actual stamping tonnage deployed across propulsion architectures.
Input-output matrices map raw material flows through press line utilization rates, die amortization schedules, and assembly value-add stages across the projection horizon. Segmentation dimensions include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from modeled press capacity expansion against battery-electric vehicle platform rollout schedules and aluminum substitution elasticity parameters.
Several conditions sit outside the modeled scope, including unannounced vehicle program cancellations, abrupt tariff regime shifts, and smelter curtailment events beyond historical volatility bands. Forecasts reflect documented assumptions about OEM localization decisions and embodied carbon compliance trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Pressure Plate Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
Automotive Emblem Market
Automotive Components
Iran Automotive Lubricants Market
Automotive Components
Automotive Steering Column Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Global Automotive Radiator Market
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
Automotive Commutator Market
Automotive Components
Automotive Stainless Steel Tubes Market