
 Material Buggy Market | 2026-2036
Material Buggy Market Size, Share, and Industry Trends Forecast 2026-2036
Material Buggy Market Insights
Aftermarket service revenue is narrowing toward predictive maintenance contracts and battery lifecycle management as fleet operators seek to lock in total cost of ownership. Wacker Neuson SE leverages its European service network to anchor long-term rental partnerships. Kubota Corporation competes through diesel-to-electric conversion programs that sustain dealer loyalty. The Toro Company specializes in compact electric architectures for confined construction zones.
A material buggy is a motorized or manually propelled wheeled carrier designed to transport bulk materials, tools, or debris across uneven terrain, typically featuring a dump hopper with 500–3,000 pound capacity and pneumatic or solid rubber tires for traction on loose surfaces. Its primary industrial purpose is to reduce manual handling injuries and accelerate material flow on job sites where full-size loaders cannot operate. Steel-framed gasoline-powered units still dominate rental fleets due to upfront cost advantages and field repair simplicity. Electric-powered buggies represent the fastest-expanding product category as lithium-ion pack costs decline and construction site noise ordinances proliferate. Composite chassis applications remain niche but command premium positioning in corrosive mining environments where aluminum fatigue limits service life.
OSHA workplace ergonomics guidelines and EPA non-road emissions standards directly shape engine specifications and hydraulic system designs for equipment sold in the United States. The EU Green Deal and F-Gas Regulation accelerate electric drivetrain penetration across European rental channels by restricting fossil-fuel equipment on publicly funded projects. Japan's METI energy efficiency benchmarks favor compact electric motors with regenerative braking for domestic manufacturers. Stakeholders must weigh battery supply chain concentration against the pace of charging infrastructure deployment on remote job sites.
Market Dynamics
Construction site electrification mandates are compressing the replacement cycle for diesel-powered material buggies as lithium-ion battery pack costs fall below the threshold where total cost of ownership inverts in favor of electric drivetrains.
Growth Catalysts
- EPA Non-Road Emissions Standards:Tier 4 Final compliance costs for small diesel engines are pushing rental fleet operators toward electric alternatives in the United States. Equipment lessors report accelerated trade-in cycles for gasoline-powered units.
- Lithium-Ion Energy Density Gains:Cell chemistry improvements are extending runtime per charge to full-shift capability. Site managers now specify electric buggies for 10-hour concrete pours without midday swapping.
- Germany:Public infrastructure tenders under the EU Green Deal now exclude fossil-fuel equipment from eligibility. Municipal contractors are pre-ordering electric fleets to maintain bidding qualification.
Market Restraints
- Cobalt Supply Concentration:Battery cathode material sourcing depends on refining capacity concentrated in the Democratic Republic of Congo and China. Geopolitical friction creates input cost volatility for domestic pack assemblers.
- Charging Infrastructure Gap:Remote job sites lack grid connectivity for high-amperage charging. Diesel generator backup defeats emissions compliance intent and extends payback periods.
- Steel Price Cyclicality:Chassis fabrication costs swing with hot-rolled coil futures. Fabricators struggle to pass through material spikes in fixed-price municipal contracts.
Strategic Opportunities
- India:Highway construction targets under the National Infrastructure Pipeline lack mechanized material handling penetration. Local assembly partnerships could capture cost-sensitive volume before import tariffs harden.
- Regenerative Braking Integration:METI efficiency benchmarks in Japan favor motor-controller combinations that recover downhill energy. Technology licensing to Southeast Asian manufacturers creates royalty streams.
- Rental Channel Digitization:Telematics-enabled predictive maintenance contracts are displacing break-fix service models. Fleet operators lock in multi-year total cost of ownership guarantees through sensor-based uptime commitments.
Industry Challenges
- Field Technician Shortage:High-voltage battery diagnostics require electrical engineering competencies absent from traditional small-engine mechanic pools. Training certification timelines stretch 18-24 months.
- UL 2580 Certification Burden:Battery pack safety testing for North American market entry demands 6-9 month validation cycles. Design iteration lag risks product obsolescence against faster-moving competitors.
- Legacy Fleet Integration:Mixed diesel-electric operations complicate site fueling and charging logistics. Superintendents resist operational complexity despite corporate sustainability mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Material Buggy Market |
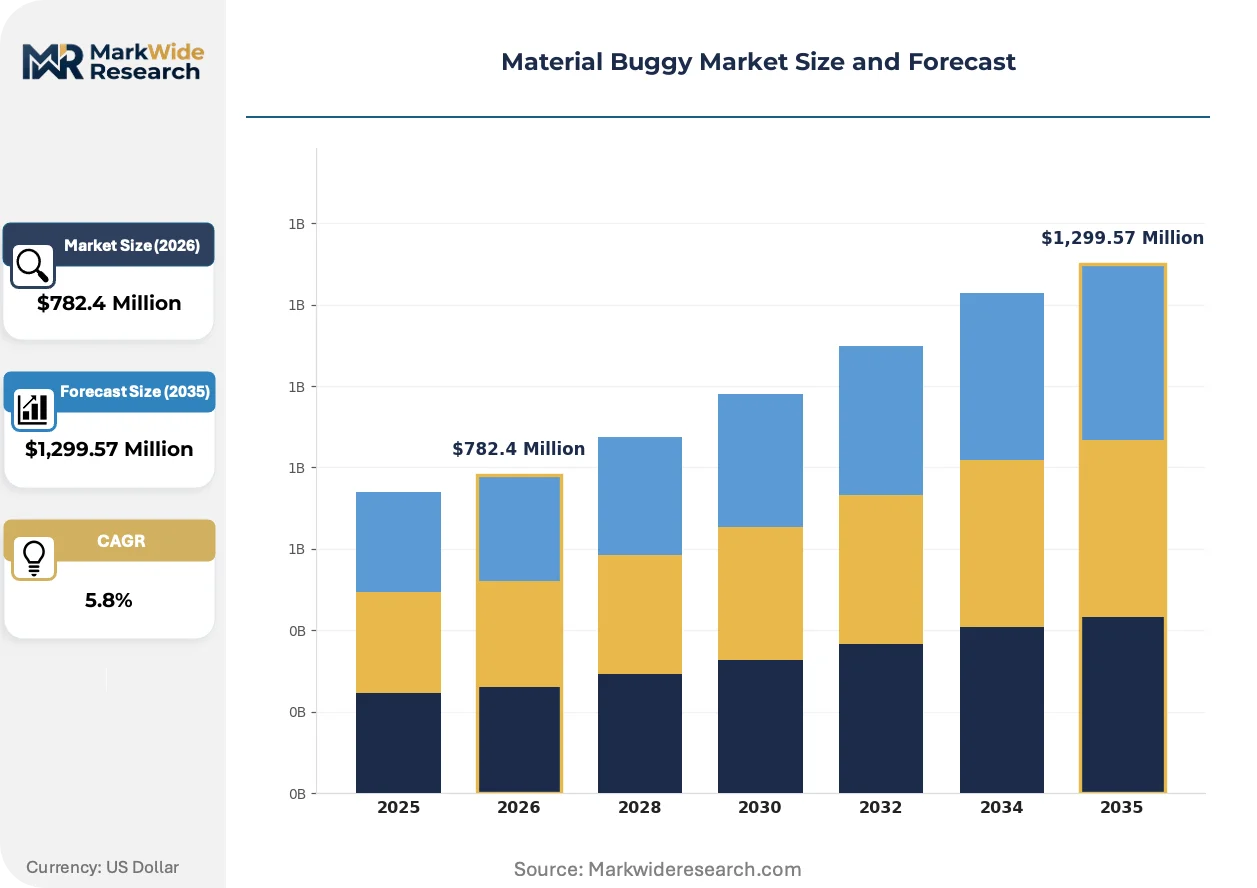
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,299.57 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Aluminum, Carbon Fiber, Plastic, Composite Application: Recreational Vehicles, Agricultural Use, Construction Sites, Military Logistics, Mining Operations End User: Equipment Manufacturers, Rental Companies, Facility Maintenance Teams, Outdoor Adventure Providers Product Type: Electric-Powered, Gasoline-Powered, Diesel-Powered, Hybrid Models, Manually Operated |
| Companies Covered | The Toro Company, Allen Engineering Corporation, Cormidi S.r.l., Kubota Corporation, Yanmar Co., Ltd., Messersi S.r.l., MQ Whiteman, Inc., Wacker Neuson SE, Multiquip Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Material Buggy Market Trends and Innovations
Material buggy design is converging on modular electric architectures that separate powertrain from chassis, enabling rapid battery swapping and platform reuse across capacity classes.
Composite honeycomb sandwich construction is collapsing the weight penalty historically associated with corrosion-resistant chassis designs. Mining contractors in Australia are adopting carbon-fiber-reinforced polymer tubs that withstand acidic leachate without the fatigue cracking that limits aluminum service life. The mass reduction permits smaller battery packs for equivalent range, compressing upfront capital requirements for electric conversion.
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are forcing hydraulic system redesigns toward sealed electric actuators. Equipment sold into European rental channels now favors electro-hydraulic dump mechanisms over open-circuit designs prone to fluid contamination. German fleet operators report 40% reduction in maintenance intervals as sealed systems eliminate filter changes and leak remediation.
Rental customers are unbundling equipment procurement from service contracts, selecting bare-metal lease rates and sourcing maintenance through third-party specialists. Independent service providers in Texas and Florida are capturing battery lifecycle management revenue that OEMs previously monopolized. This channel fragmentation compresses OEM margin capture and forces price transparency on spare parts pricing.
Material Buggy Market Segmentation
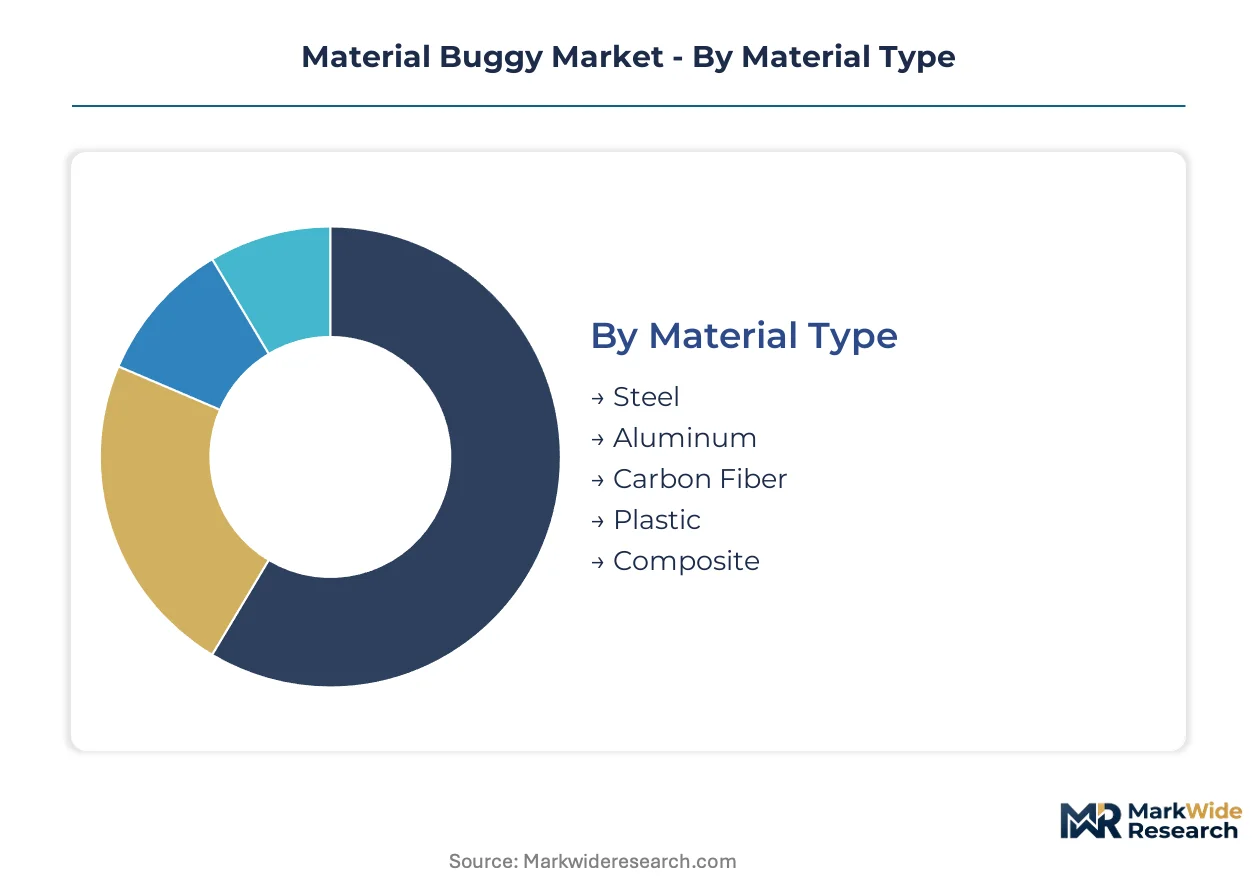
Material buggy procurement patterns diverge sharply across material specifications, powertrain architectures, and end-use contexts. Fleet operators prioritize segments with compressed replacement cycles and proven field reliability over experimental configurations.
Material Type:
Steel chassis dominate rental fleet turnover with 5-7 year depreciation schedules, while aluminum and composite alternatives stretch replacement decisions across 10-15 year windows depending on corrosion exposure.
- Steel:Hot-rolled coil construction withstands impact damage and permits field welding repairs. Construction site rental fleets in the United States specify steel tubs for concrete handling where abrasion resistance outweighs weight penalties.
- Aluminum:Extruded alloy frames reduce curb weight by 35-40% versus steel equivalents. Agricultural equipment distributors in Germany favor aluminum for orchard applications where soil compaction limits apply.
- Carbon Fiber:Prepreg layup manufacturing commands 3-4x steel pricing. Mining contractors in Australia specify carbon-fiber tubs for acid-leach environments where metal fatigue accelerates.
- Plastic:Rotomolded polyethylene bodies resist chemical corrosion in fertilizer handling. Facility maintenance teams specify plastic units for indoor warehousing where spark risks are regulated.
- Composite:Glass-reinforced polymer sandwich construction balances weight and durability. Military logistics procurement in Japan evaluates composite chassis for air-transportable equipment.
Steel dominates installed base. Carbon fiber is where expansion concentrates.
Application:
Construction sites generate the highest equipment utilization rates at 1,800-2,200 annual operating hours, while recreational and agricultural applications exhibit pronounced seasonal demand concentration.
- Recreational Vehicles:Low-speed electric architectures with 500-pound capacity serve campground and resort properties. Outdoor adventure providers in the United States specify these for guest transport on unpaved terrain.
- Agricultural Use:Pneumatic tire configurations navigate soft field conditions. Vineyard operators in Germany prioritize narrow-track designs for row-crop access.
- Construction Sites:Heavy-duty steel tubs with hydraulic dump mechanisms handle aggregate and debris. EPA Tier 4 Final compliance costs are accelerating electric conversion in this segment.
- Military Logistics:Air-transportable specifications with NATO pallet compatibility. Defense procurement channels in Japan evaluate modular designs for rapid deployment.
- Mining Operations:Corrosion-resistant construction for acidic leachate exposure. Australian contractors specify carbon-fiber or specialty alloy configurations.
Construction sites dominate fleet volume. Mining operations command the steepest expansion trajectory.
End User:
Rental companies compress procurement cycles through operating lease structures, while equipment manufacturers and facility teams extend ownership horizons through capital depreciation schedules.
- Equipment Manufacturers:OEM procurement for integration into larger material handling systems. These buyers specify custom mounting interfaces and control system compatibility.
- Rental Companies:Fleet standardization across multiple capacity classes drives volume procurement. United States lessors report 18-month payback thresholds for electric unit deployment.
- Facility Maintenance Teams:Indoor warehousing and campus applications favor electric-powered units. OSHA workplace ergonomics guidelines influence specifications for manual handling reduction.
- Outdoor Adventure Providers:Seasonal demand patterns and guest-experience aesthetics shape procurement. These operators prioritize low-noise electric architectures for nature-adjacent properties.
Rental companies dominate transaction volume. Facility maintenance teams are where specification evolution concentrates.
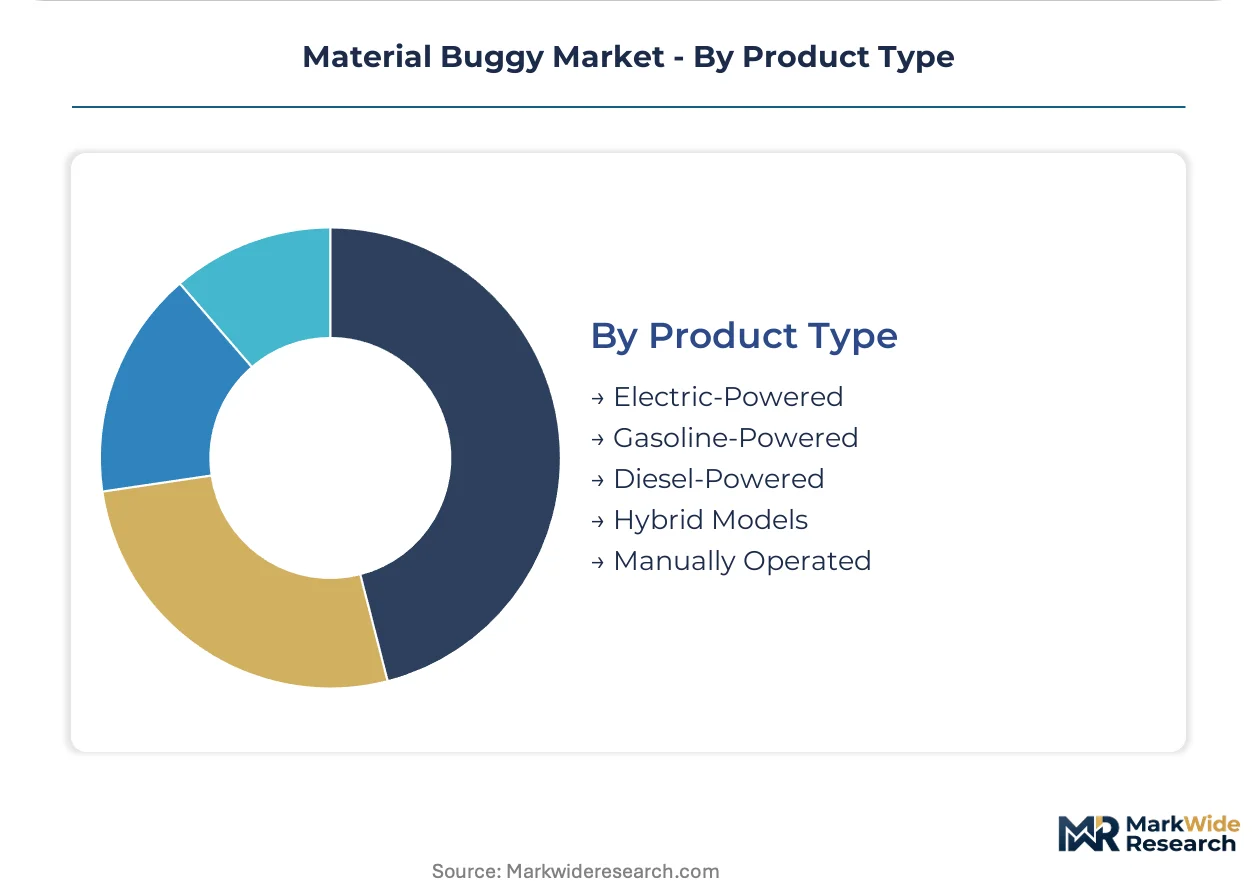
Product Type:
Powertrain selection determines total cost of ownership calculus, with electric architectures inverting lifetime economics against gasoline and diesel alternatives as battery pack costs decline.
- Electric-Powered:Lithium-ion pack configurations now deliver full-shift runtime. German municipal contractors pre-order electric fleets to maintain EU Green Deal bidding eligibility.
- Gasoline-Powered:Small-engine simplicity sustains field repair capability. Steel-framed gasoline units still dominate United States rental fleet composition.
- Diesel-Powered:Tier 4 Final compliance costs and emissions restrictions compress replacement demand. These units retain niche presence in remote mining applications lacking grid connectivity.
- Hybrid Models:Parallel electric-diesel architectures for range extension without charging infrastructure. METI efficiency benchmarks in Japan favor regenerative braking integration.
- Manually Operated:Human-powered designs for confined spaces and noise-restricted environments. Facility maintenance teams specify these for indoor applications where motorized transport is prohibited.
Gasoline-powered units dominate installed base. Electric-powered configurations are where procurement momentum concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement contexts. Municipal contractors in Germany absorb premium electric pricing to secure bidding eligibility, while cost-sensitive highway builders in India prioritize upfront acquisition costs over lifecycle economics. Rental fleet operators in the United States occupy a middle position, evaluating total cost of ownership over compressed depreciation schedules.
United States
Infrastructure renewal cycles and rental fleet modernization drive procurement volume. EPA Tier 4 Final compliance costs accelerate trade-in cycles for gasoline-powered units. Equipment lessors in Texas and Florida report 18-month payback thresholds for electric deployment.
Germany
Public infrastructure tenders under the EU Green Deal exclude fossil-fuel equipment from eligibility. Municipal contractors pre-order electric fleets to maintain bidding qualification. Industrial clusters in Bavaria and North Rhine-Westphalia anchor manufacturing and rental channel distribution.
Japan
METI energy efficiency benchmarks favor compact electric motors with regenerative braking. Domestic manufacturers optimize for these specifications. Defense procurement channels in Tokyo evaluate modular designs for rapid deployment and NATO pallet compatibility.
Australia
Mining contractors in Western Australia specify corrosion-resistant chassis for acidic leachate exposure. Carbon-fiber and specialty alloy configurations command premium positioning. Remote site logistics drive demand for air-transportable equipment specifications.
India
National Infrastructure Pipeline highway construction targets lack mechanized material handling penetration. Local assembly partnerships could capture volume before import tariffs harden. Maharashtra and Gujarat industrial corridors concentrate fabrication capacity and rental fleet operations.
Material Buggy Market Competitive Landscape
Integrated equipment conglomerates and specialized compact machinery fabricators split the market between scale-driven standardization and application-specific customization. The vendor base organizes around three strategic archetypes: rental-channel specialists with dense service networks, engine-to-electric converters leveraging existing dealer relationships, and lightweight materials innovators targeting premium mining applications. Competitive moves concentrate on strategic partnerships for battery supply security and geographic expansion through local assembly licensing.
Among European-integrated equipment groups, Wacker Neuson SE anchors the rental-channel specialist archetype with dense service network coverage. Kubota Corporation exemplifies the engine-to-electric conversion model, sustaining dealer loyalty through diesel displacement programs. The Toro Company occupies a position within the compact electric architecture segment, targeting confined construction zone applications. These three players represent distinct strategic postures without overlapping core competencies.
| Leading Market Players |
|---|
| The Toro Company |
| Allen Engineering Corporation |
| Cormidi S.r.l. |
| Kubota Corporation |
| Yanmar Co., Ltd. |
| Messersi S.r.l. |
| MQ Whiteman, Inc. |
| Wacker Neuson SE |
| Multiquip Inc. |
| Others |
Pricing and Supply Chain Analysis
Cobalt supply concentration in the Democratic Republic of Congo and China determines both the premium spread for electric-powered units and the geographic clustering of battery pack assembly. Tariff exposure on processed cathode materials forces tiered pricing structures that reward fleet operators with long-term service contracts.
Pricing Analysis
Predictive maintenance contracts now drive lifetime value capture in the material buggy market. Three-tier pricing structure across premium, standard, and economy levels separates carbon-fiber mining configurations from steel rental fleet units and plastic indoor models. Cost compression in the electric segment intensifies because lithium-ion pack prices decline faster than chassis fabrication costs stabilize. Rental companies exhibit the highest price sensitivity due to compressed payback thresholds, while mining contractors absorb premium positioning for corrosion-resistant specifications.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for battery component sourcing. Manufacturing concentration spans China for lithium-ion cells, Germany for precision hydraulic systems, and Japan for compact electric motors. Raw material dependencies center on cobalt cathodes, hot-rolled steel coil, and glass-reinforced polymer resins. Single-source vulnerability in refined cobalt supply creates input cost volatility that fabricators struggle to pass through fixed-price municipal contracts. Distribution runs through rental channel networks in Texas and Florida, with aftermarket service increasingly unbundled to independent specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Material buggy incumbents face substitution pressure from compact electric loaders and autonomous site vehicles that encroach on confined-zone applications. Defense requires building moats around service network density and battery lifecycle management capabilities.
For Market Incumbents: Build captive battery refurbishment capacity to lock in aftermarket revenue streams. Anchor long-term rental partnerships through predictive uptime guarantees that independent service providers cannot match. Consolidate dealer loyalty by underwriting diesel-to-electric conversion programs that preserve existing service relationships. Counter the autonomous loader threat by embedding telematics that prove human-operated efficiency in irregular terrain. For New Entrants and Emerging Players: Establish a beachhead in India's highway construction sector before import tariffs harden on fully assembled units. Local assembly partnerships in Maharashtra and Gujarat industrial corridors bypass duty exposure while capturing National Infrastructure Pipeline volume. Target the facility maintenance segment where OSHA ergonomics mandates accelerate electric specification without entrenched incumbent relationships. Lead with low-noise electric architectures for indoor warehousing applications where spark-risk regulations exclude gasoline alternatives. For Investors and Strategic Acquirers: The market sits at an electrification transition phase that favors rental-channel specialists with dense service footprints. Long-term viability hinges on battery supply security and charging infrastructure deployment pace rather than manufacturing scale alone. Acquisition targets should demonstrate established predictive maintenance contract revenue and UL 2580 certification progress. Monitor cobalt price volatility and EU Green Deal tender eligibility rules as inflection indicators for electric fleet conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode offtake contracts with DRC-China refiners secure input cost stability for electric conversion programs. |
| Local Assembly Licensing | Partnerships in Maharashtra and Gujarat industrial corridors preempt Indian import tariff escalation on finished equipment. |
| Regenerative Braking Licensing | Technology transfer to Southeast Asian manufacturers creates royalty streams under Japan METI efficiency benchmark compliance. |
| Telematics Platform Integration | Sensor-based uptime commitments displace break-fix service models and lock in multi-year rental fleet contracts. |
| Composite Chassis Scale-Up | Carbon-fiber and glass-reinforced polymer production expansion captures premium mining demand in Australian acid-leach environments. |
Research Methodology
Operator-level perspectives from fleet maintenance directors, rental company procurement heads, construction site superintendents, and aftermarket service technicians anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, customs trade data, EPA Tier 4 Final compliance records, and EU Green Deal tender documentation. Bottom-up unit economics modeling and top-down market sizing triangulated volume estimates across powertrain architectures and material specifications.
Scenario-bracketing around cobalt price volatility, charging infrastructure deployment pace, and steel futures cyclicality shaped the analytical framework. Segmentation dimensions modeled include powertrain type, chassis material, end-use application, and regional regulatory cluster across the projection horizon. CAGRs derived from replacement cycle compression rates and fleet electrification mandates. Industry-specific forecast inputs incorporated lithium-ion energy density improvement curves and EPA non-road emissions compliance cost trajectories.
Sensitivities concentrate around cobalt supply disruption, remote site charging logistics gaps, and steel price spike pass-through limitations. Forecasts reflect assumptions on battery cost decline velocity and rental fleet depreciation schedule compression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Teardrop Trailer Market
Recreational Vehicles
Snowmobile Trailer Axle Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Australia Recreational Vehicle Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Water Scooter Market
Recreational Vehicles
Light Car Trailer Market
Recreational Vehicles
Europe Motor Home Market
Recreational Vehicles
Towable Tubes Market
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market