
 Global Automotive Gearbox Market | 2026-2036
Global Automotive Gearbox Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Gearbox Market Analysis
The EU F-Gas Regulation is broadening the cost-of-entry calculus for thermal management in electrified transmissions. ZF Friedrichshafen leverages its integrated mechatronics portfolio to sustain engineering leadership across dual-clutch architectures. Aisin Corporation anchors its competitive stance through captive production of torque converters and control software for Asian OEM platforms.
An automotive gearbox is a mechanical assembly of gears, shafts, synchronizers, and bearings that transmits engine torque to the drive wheels while varying speed ratios through meshing gear pairs; modern units integrate electronic control modules managing shift timing within millisecond tolerances. The primary purpose is to optimize power delivery across vehicle operating conditions, balancing acceleration performance against energy efficiency. Automatic transmissions now lead value generation as torque-converter and dual-clutch variants capture premium vehicle segments, while CVT architectures specialize in compact passenger applications where fuel economy optimization dominates engineering priorities. Manual transmissions occupy declining but persistent niches in emerging-market commercial fleets and enthusiast vehicle categories.
The EPA and NHTSA in the United States enforce Corporate Average Fuel Economy standards that compel OEMs toward higher gear counts and optimized transmission efficiency, while China's MIIT administers parallel fuel-consumption mandates accelerating local supplier capability building. The EU Green Deal and associated CO2 fleet targets further tighten product requirements, pushing suppliers to integrate electrified elements into conventional gearbox architectures. Stakeholders must monitor how regulatory convergence on electrification timelines reshapes capital allocation between incremental transmission improvements and full powertrain electrification strategies.
Market Dynamics
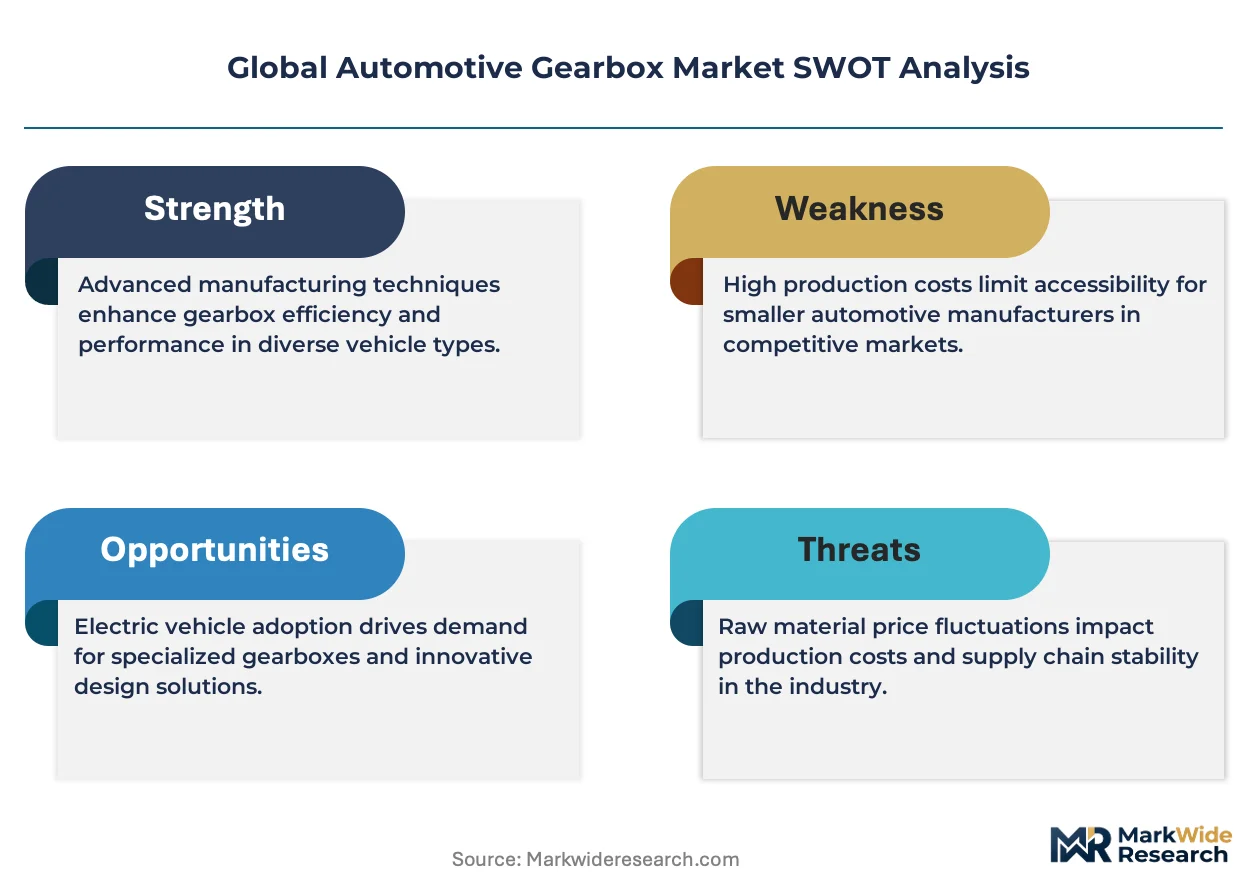
Electrification mandates across major automotive markets are forcing gearbox suppliers to reengineer mechanical architectures for hybrid compatibility while defending revenue from pure-electric powertrain substitution.
Growth Catalysts
- EPA CAFE Standards:The United States enforces Corporate Average Fuel Economy thresholds that compel OEMs toward eight-speed and higher automatic transmissions. Engineering departments prioritize gear-count expansion over platform redesign.
- Commercial Fleet Modernization:Brazilian logistics operators are replacing manual transmissions with automated manual variants to reduce driver fatigue and fuel consumption on long-haul corridors.
- Thermal Management Integration:The EU F-Gas Regulation is broadening engineering scope to include refrigerant-compatible transmission cooling circuits, creating new content per vehicle for European suppliers.
Market Restraints
- Rare Earth Magnet Dependency:Electrified dual-clutch and hybrid transmission actuator motors require neodymium-iron-boron magnets concentrated in Chinese processing facilities, exposing supply chains to export restriction risk.
- Powertrain Substitution:Battery-electric vehicles eliminate multi-speed gearboxes entirely, compressing addressable market scope as OEM electrification timelines accelerate.
- Tooling Amortization Burden:Conventional automatic transmission manufacturing lines require capital-intensive dedicated machining centers that resist rapid product-mix adaptation.
Strategic Opportunities
- India PLI Scheme:India's production-linked incentive scheme for automotive components is attracting gearbox suppliers to establish local manufacturing for domestic OEMs and export markets.
- Two-Speed E-Axle Development:Electric commercial vehicles are creating demand for compact multi-speed reduction gearboxes that optimize motor efficiency across load gradients.
- Software-Defined Calibration:Over-the-air update capability is enabling transmission control module refinement post-sale, opening recurring revenue streams through feature activation.
Industry Challenges
- Mechatronics Talent Scarcity:The convergence of mechanical gear design and embedded software engineering has created hiring competition for control algorithm specialists capable of millisecond-shift optimization.
- Homologation Timeline Compression:China's MIIT fuel consumption certification cycles are shortening, forcing suppliers to parallel-track development and validation to maintain platform launch schedules.
- Legacy System Integration:Hybrid transmission architectures must interface with existing internal combustion engine control networks, multiplying interface validation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Gearbox Market |
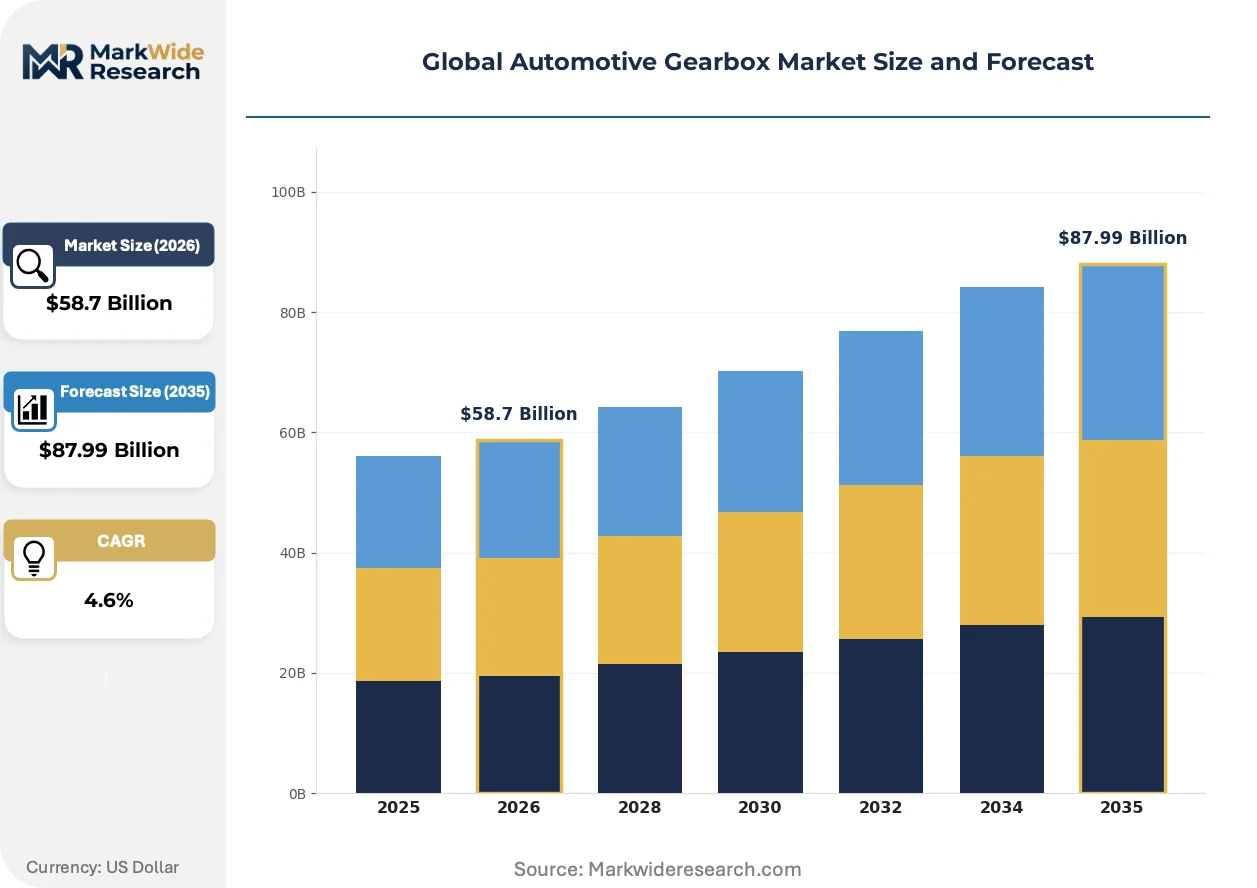
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $87.99 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Semi-Automatic, CVT End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Transmission Type: Sequential, Dual-Clutch, Continuously Variable, Planetary Size: Compact, Mid-Size, Full-Size, Heavy-Duty |
| Companies Covered | ZF Friedrichshafen AG, Aisin Corporation, BorgWarner Inc., JATCO Ltd., Magna International Inc., Allison Transmission, Hyundai Powertech, Eaton Corporation, Schaeffler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Gearbox Market Emerging Trajectories
Actuation electrification and thermal integration are converging to redefine gearbox architecture, while regulatory fuel-efficiency mandates accelerate control-system sophistication across all transmission categories.
Integrated electric actuation modules are replacing hydraulic shift mechanisms in dual-clutch transmissions. Tier 1 suppliers in Germany and Japan are adopting compact motor-driven selector forks that eliminate fluid circuits and reduce parasitic losses. This hardware simplification is automating calibration workflows and compressing development cycles for multi-platform deployment.
The EU F-Gas Regulation is mandating lower-global-warming-potential refrigerants in vehicle thermal systems. Gearbox oil coolers must now demonstrate compatibility with R-1234yf and CO2-based circuits, forcing suppliers to redesign heat exchanger materials and sealing architectures. European premium vehicle programs are experiencing the most intensive revalidation schedules as 2025 fleet targets approach.
Fleet procurement departments are consolidating transmission supplier relationships to secure volume pricing and unified service protocols. Large commercial operators in North America are negotiating direct sourcing agreements that bypass traditional distributor networks. This concentration is most pronounced in long-haul trucking corridors where total cost of ownership calculations dominate specification decisions.
Global Automotive Gearbox Market Segmentation
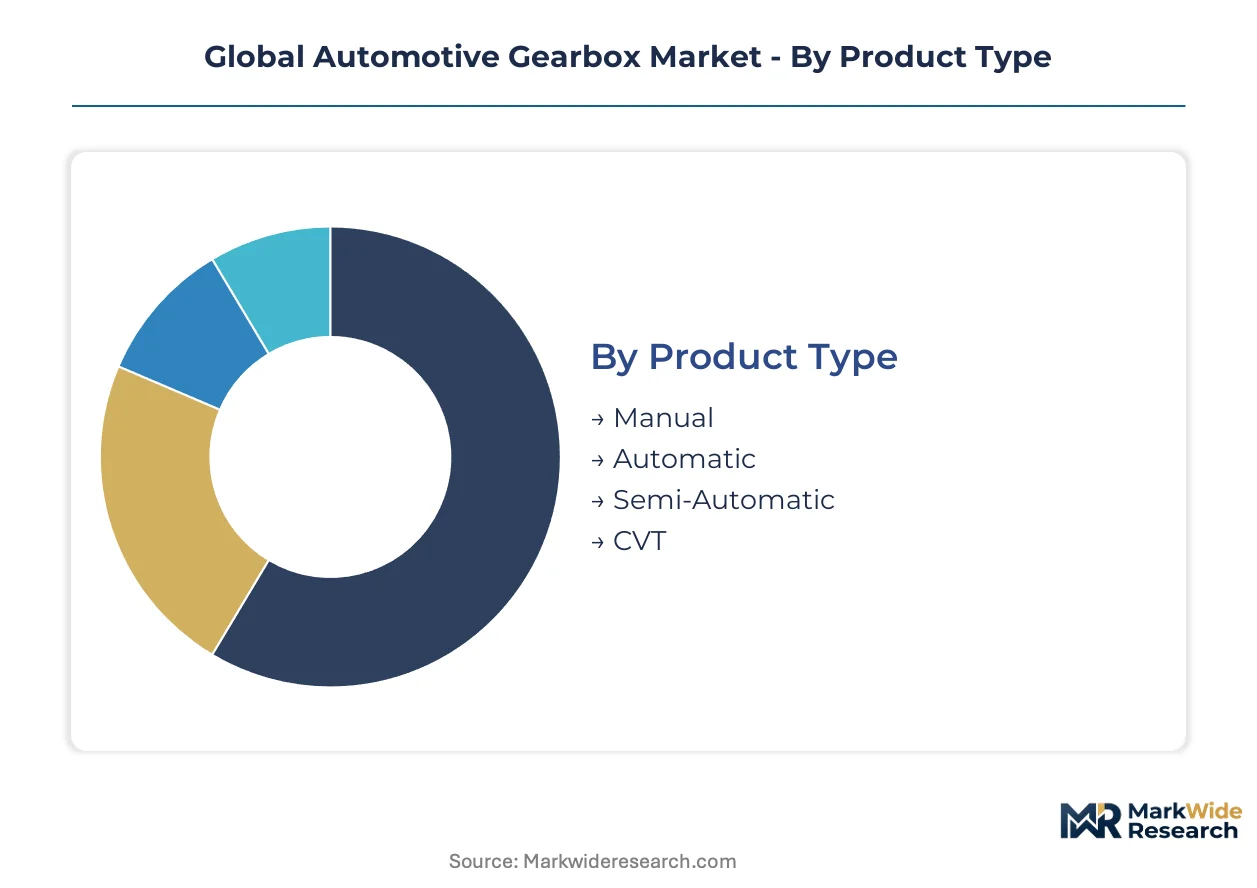
Gearbox procurement patterns diverge sharply across vehicle electrification timelines and fleet operating economics. Product architecture, end-user integration depth, and duty-cycle intensity create distinct commercial segments with asymmetric margin profiles and engineering requirements.
Product Type:
Buyers differentiate primarily by fuel-efficiency compliance burden and driver skill availability across fleet operations.
- Automatic:Torque-converter and dual-clutch architectures now dominate premium passenger vehicle specifications. ZF Friedrichshafen and Aisin Corporation supply eight-speed and higher configurations to German and Japanese OEMs facing EPA CAFE and EU CO2 fleet mandates. Engineering investment concentrates on electrified actuation modules that eliminate hydraulic circuits.
- CVT:Pulley-based continuous ratio variation serves compact passenger applications where urban fuel economy optimization outweighs acceleration performance. Japanese OEM platforms in the 1.0-1.5L displacement range specify CVT architectures from Jatco and Aisin for domestic and Southeast Asian markets. Belt durability under high-torque hybrid integration remains the critical engineering constraint.
- Manual:Synchronizer-equipped architectures persist in emerging-market commercial fleets and enthusiast vehicle categories. Brazilian long-haul operators specify automated manual variants to reduce driver fatigue while retaining mechanical simplicity for field serviceability.
- Semi-Automatic:Clutchless manual systems with electronic shift actuation occupy cost-sensitive segments between full automatic and conventional manual. Indian commercial vehicle OEMs source these architectures for intermediate-duty distribution trucks.
Volume sits with Automatic; growth tilts toward CVT in compact hybrid applications.
End User:
Integration complexity and validation liability separate procurement tiers by control over powertrain architecture.
- OEMs:Vehicle manufacturers with captive powertrain engineering specify transmission architectures at platform conception. Volkswagen Group and Toyota Motor Corporation maintain internal gearbox development for volume passenger programs, sourcing only specialized components from Tier-1 suppliers.
- Tier-1 Suppliers:Independent transmission specialists like ZF Friedrichshafen and Magna International design complete gearbox systems for OEMs without captive capability. These suppliers assume homologation responsibility and warranty liability across multiple vehicle programs.
- Vehicle Assemblers:Contract manufacturers and regional assemblers procure complete transmission modules rather than component systems. Operations in India and Brazil rely on imported gearbox assemblies for domestic vehicle production.
- Aftermarket Providers:Remanufacturing specialists and independent distributors serve replacement demand outside OEM service networks. North American fleet operators negotiate direct sourcing agreements for rebuilt transmissions to compress total cost of ownership.
Revenue concentrates with OEMs and Tier-1 suppliers; aftermarket channels are expanding most quickly in commercial vehicle segments.
Transmission Type:
Shift-speed requirements and thermal load characteristics determine architecture selection for specific duty cycles.
- Dual-Clutch:Two-shaft designs with alternating clutch packs enable sub-100-millisecond shifts for performance-oriented passenger vehicles. Porsche and Audi specify wet-clutch variants for high-torque applications; dry-clutch architectures serve compact front-wheel-drive platforms.
- Planetary:Epicyclic gear trains with multiple rotating carriers provide torque multiplication for conventional automatic transmissions. General Motors and Ford Motor Company specify ten-speed planetary architectures for full-size pickup trucks.
- Sequential:Dog-clutch engagement without synchronizers enables rapid ratio changes for motorsport and limited-production supercars. Ferrari and McLaren specify automated sequential systems for track-focused variants.
- Continuously Variable:Friction-drive and traction-drive architectures extend ratio spread beyond stepped-gear limitations. Nissan specifies Jatco-sourced CVTs for Rogue and Altima programs in the United States.
Planetary systems retain volume leadership; dual-clutch architectures gain share fastest in European premium segments.
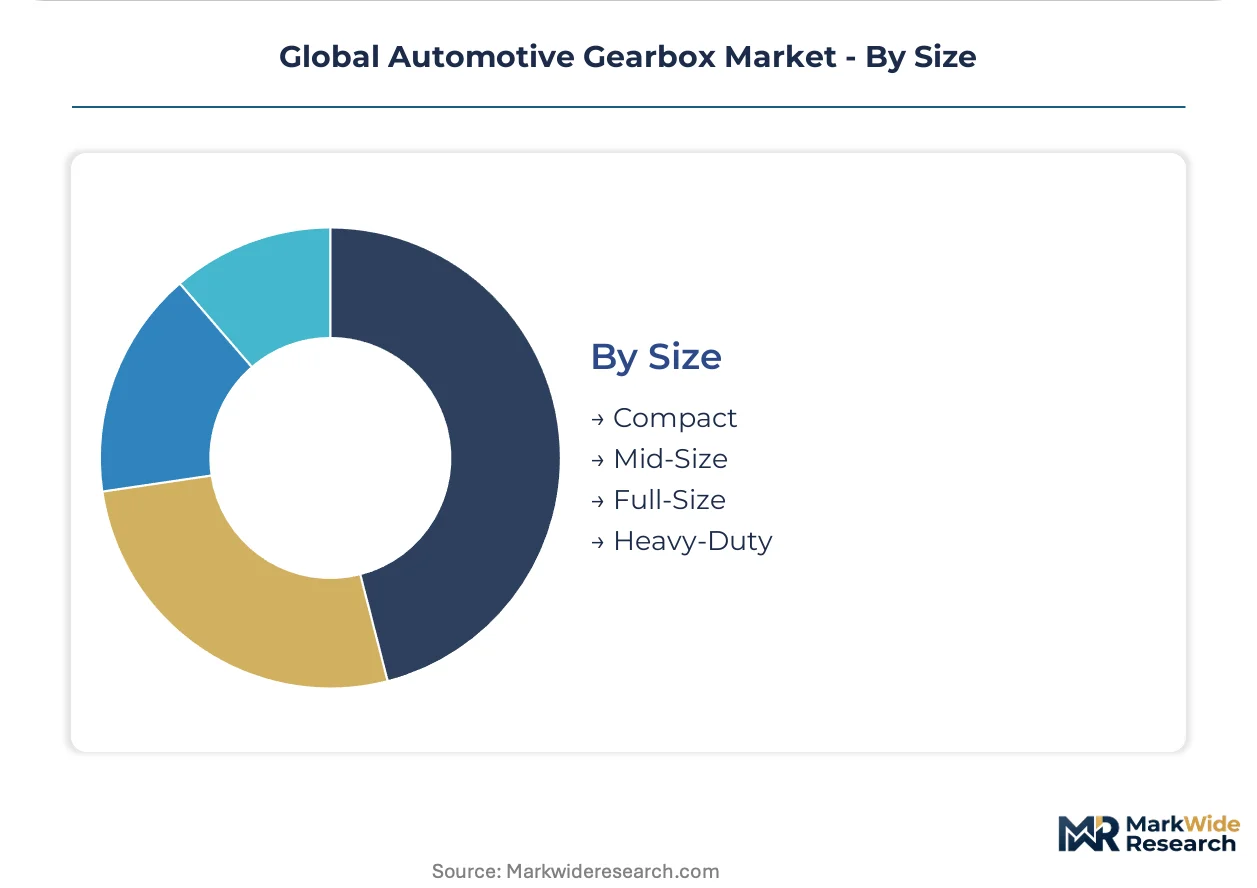
Size:
Torque capacity and packaging envelope constraints segment engineering requirements by vehicle mass class.
- Heavy-Duty:Cast-iron housings and multi-countershaft designs transmit 1000+ Nm for commercial vehicle and off-highway applications. Allison Transmission and Eaton Corporation supply these architectures for North American Class 8 trucks.
- Compact:Aluminum-intensive designs with integrated differential housings serve transverse-engine front-wheel-drive platforms. Honda and Hyundai specify these architectures for subcompact and compact passenger vehicles.
- Mid-Size:Intermediate torque capacity for C-segment sedans and compact SUVs. Toyota Camry and Honda Accord programs specify mid-size automatic transmissions with six to eight ratios.
- Full-Size:High-torque capacity for D-segment sedans, full-size SUVs, and light commercial vehicles. BMW and Mercedes-Benz specify these architectures for rear-wheel-drive luxury platforms.
Compact architectures generate highest unit volumes; heavy-duty applications command the steepest expansion trajectory in electric commercial vehicle two-speed e-axle development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's Special Investment Region anchors gearbox manufacturing concentration through subsidized land and power tariffs. Mexico's IMMEX maquiladora program draws transmission assembly for North American OEM supply chains. China's Lingang New Area in Shanghai accelerates electrified powertrain component localization.
United States
EPA CAFE standards compel eight-speed and higher automatic transmission adoption across Detroit Three lineups. NHTSA enforcement timelines compress supplier validation cycles for 2027 model-year compliance. Manufacturing clusters in Michigan and Ohio host machining centers serving Indiana and Kentucky assembly plants.
Germany
EU F-Gas Regulation mandates refrigerant-compatible thermal management integration into transmission cooling circuits. KBA type-approval protocols enforce stringent electromagnetic compatibility for electrified actuation modules. Stuttgart and Wolfsburg corridors concentrate ZF Friedrichshafen and captive Volkswagen Group engineering.
China
MIIT fuel consumption standards accelerate multi-speed gearbox development for domestic OEM platforms. Dual carbon goals under MEE jurisdiction push hybrid transmission architectures into volume production. Yangtze River Delta suppliers cluster around Shanghai Lingang for export logistics access.
India
PLI scheme for automotive components attracts gearbox suppliers to establish local manufacturing for Maruti Suzuki and Hyundai Motor India. BIS certification requirements standardize torque capacity ratings across commercial vehicle segments. Tamil Nadu and Gujarat host transmission machining operations serving Pune and Chennai assembly corridors.
Brazil
Commercial fleet operators specify automated manual transmissions to reduce driver fatigue on São Paulo-Rio de Janeiro haul routes. ANVISA automotive regulations align with Mercosur technical standards for cross-border component trade. Minas Gerais and São Paulo states concentrate remanufacturing operations for aftermarket service networks.
Global Automotive Gearbox Market Vendor Landscape
German producers anchor one tier; Japanese specialists hold torque-converter and CVT dominance. The market structure concentrates around five integrated transmission system suppliers with captive OEM relationships and three component specialists serving second-source requirements. Strategic archetypes include integrated mechatronics providers, torque converter captive producers, and planetary geartrain machining specialists. Competitive moves center on electrified actuation module development and two-speed e-axle capacity expansion for electric commercial vehicles.
Within the integrated systems tier, ZF Friedrichshafen AG and Aisin Corporation exemplify divergent geographic anchoring strategies. ZF Friedrichshafen AG represents European engineering-depth archetypes with in-house mechatronics portfolios. Aisin Corporation occupies the Japanese captive-supply position through torque converter and control software integration. BorgWarner Inc. sits within the North American technology-licensing archetype, enabling platform-scale deployment across multiple OEM customers.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Aisin Corporation |
| BorgWarner Inc. |
| JATCO Ltd. |
| Magna International Inc. |
| Allison Transmission |
| Hyundai Powertech |
| Eaton Corporation |
| Schaeffler |
| Others |
Supply Flow & Price Mechanics
Mechatronics engineering talent concentration in Stuttgart and Wolfsburg feeds labor-cost differentials that widen pricing-tier spreads between premium electrified actuation modules and economy-grade manual transmissions.
Pricing Analysis
Lead-time-driven pricing stratification rewards premium positioning for sub-100-millisecond shift actuators with compressed delivery schedules, while spot inventory of conventional planetary gear sets trades at discounts. Three-tier pricing structure across premium, standard, and economy levels segments by electrification content and thermal management integration. Cost compression in economy manual architectures intensifies because Brazilian and Indian commercial fleets prioritize total cost of ownership over shift-speed performance. Aftermarket remanufacturing channels exhibit highest price sensitivity; OEM captive supply arrangements demonstrate lowest.
Supply Chain Analysis
Rare earth magnet supply rests on Chinese neodymium-iron-boron processing facilities that feed electrified dual-clutch actuator motor production. Gear machining centers draw from German and Japanese precision tooling manufacturers; aluminum housing castings source from Mexican and Chinese foundries. Single-source vulnerability concentrates in rare earth magnet refining, exposing transmission suppliers to export restriction risk. Distribution runs through Tier 1 system integrators that assume homologation liability for OEM platform programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive gearbox manufacturing is becoming a vertical-integration race as suppliers pursue captive control over torque converter production and control software development to defend margin structures against electrification substitution.
For Market Incumbents: Acquire embedded software engineering capabilities to secure millisecond-shift optimization talent pools. Consolidate machining capacity in Gujarat and Tamil Nadu corridors to capture India PLI scheme benefits. Battery-electric powertrain substitution threatens addressable market scope; backward integration into rare earth magnet recycling mitigates supply disruption exposure. For New Entrants and Emerging Players: The mid-tier price gap between ZF Friedrichshafen premium dual-clutch systems and economy manual transmissions from regional assemblers creates white-space opportunity. Target two-speed e-axle development for electric commercial vehicles where established suppliers lack dedicated capacity. Pursue direct fleet procurement relationships in North American long-haul trucking corridors as entry channel. For Investors and Strategic Acquirers: Re-rating potential sits with mechatronics-integrated specialists given software-defined calibration revenue streams from over-the-air transmission control updates. Five-to-ten-year viability hinges on hybrid transmission architecture persistence against full electrification timelines. Watch MIIT fuel consumption certification cycle compression as inflection indicator for supplier validation cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Two-Speed E-Axle Capacity Expansion | Captures emerging demand from electric commercial vehicle load-gradient optimization requirements. |
| Software-Defined Calibration Investment | Enables recurring revenue through over-the-air transmission control module refinement post-sale. |
| Thermal Management Integration | Addresses EU F-Gas Regulation refrigerant compatibility mandates for transmission cooling circuits. |
| Rare Earth Magnet Recycling Partnership | Reduces dependency on Chinese neodymium-iron-boron processing facility concentration risk. |
| India Manufacturing Footprint Establishment | Secures PLI scheme benefits for Maruti Suzuki and Hyundai Motor India supply qualification. |
Methodological Framework
Multi-period observation of vehicle production volumes, transmission content per platform, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers. Secondary validation drew from IHS Markit vehicle registration databases, EPA CAFE compliance filings, MIIT fuel consumption certification records, and EU CO2 fleet target progress reports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrix modeling connected propulsion architecture adoption rates to gearbox demand by vehicle class, electrification tier, content per vehicle, OEM supply tier, and regional production cluster. CAGRs derived from segment-level volume trajectories calibrated to regulatory mandate enforcement schedules. Forecast inputs incorporated rare earth magnet supply elasticity and thermal management integration cost curves.
Inputs from regulatory filing databases and supplier financial disclosures were available through the study window; gaps in real-time electrification timeline announcements from OEMs introduce uncertainty bands around hybrid transmission persistence assumptions. Forecasts reflect documented assumptions regarding MIIT enforcement intensity and EU F-Gas Regulation implementation pace. Rare earth export policy shifts, battery-electric vehicle adoption acceleration, and mechatronics talent migration patterns warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Glass Film Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Automotive Sunroof Glass Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
Automotive Stainless Steel Tubes Market
Automotive Components
Electronic Clutch Actuators Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
France Automotive Market
Automotive Components
Automobile AC Condensers Market
Automotive Components
Automotive Tailgate Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Sheet Metal Components Market