
 Automotive Differential Market | 2026-2036
Automotive Differential Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Differential Market Intelligence
Software-enabled, on-demand traction control functionality is recalibrating the value proposition beyond purely mechanical hardware. ZF Friedrichshafen AG leverages its systems integration expertise to offer advanced active differentials for premium and electric vehicle platforms. BorgWarner Inc. specializes in clutch-based limited-slip and torque vectoring systems for a wide range of drivetrain architectures. Dana Incorporated sustains its market position through extensive manufacturing scale in axles and driveline components.
An automotive differential is a mechanical gear train that transmits engine torque to the wheels while allowing them to rotate at different speeds during turns. It primarily consists of a ring gear, pinion gear, and a set of planetary gears housed within a carrier, essential for vehicle stability and handling. Limited Slip Differentials and Torque Vectoring Differentials represent the fastest-growing product types, displacing traditional open differentials. Demand from the Electric Vehicles segment is driving development of specialized units, while the Passenger Cars segment remains the largest volume consumer.
Vehicle safety and emissions standards from regulators like the US National Highway Traffic Safety Administration (NHTSA) and the European Union influence differential design for stability control and efficiency. Concurrently, China's GB standards for vehicle components and the EU Green Deal objectives push for lighter, more efficient drivetrain technologies. OEM procurement decisions will increasingly hinge on a supplier's ability to integrate advanced electronic controls with robust mechanical systems.
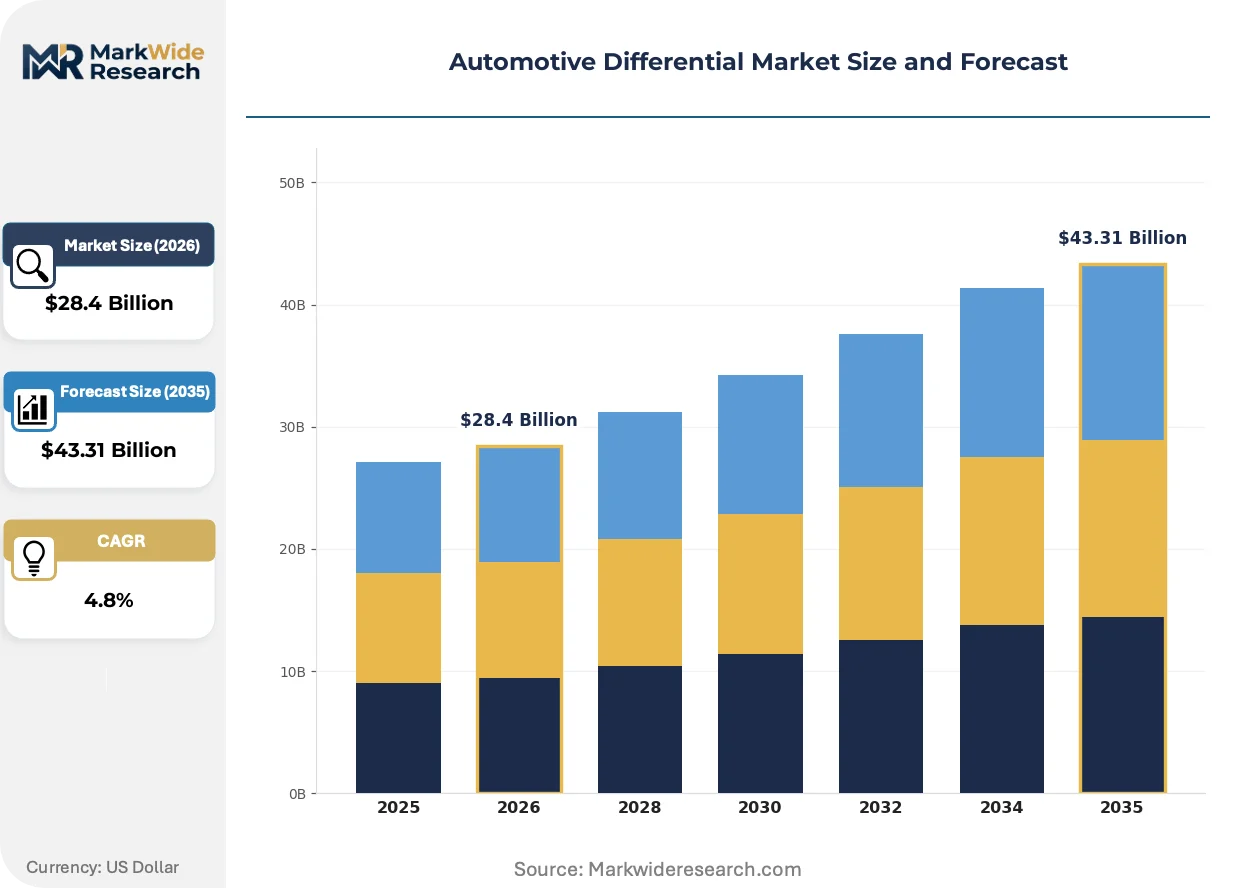
Market Dynamics
The transition to electric vehicles is the central force shaping the automotive differential market, demanding new designs optimized for instant torque delivery and regenerative braking, which fundamentally alters driveline architecture and supplier requirements.
Growth Catalysts
- EV Mandates:The European Union's Green Deal objectives and China's dual carbon goals accelerate the shift to electric powertrains, requiring specialized differentials designed for new driveline architectures.
- Performance Vehicle Demand:Consumer appetite for all-wheel-drive (AWD) in SUVs and passenger cars boosts adoption of advanced torque vectoring and limited-slip differentials for superior handling.
- Safety System Integration:NHTSA mandates for vehicle stability control indirectly drive demand for electronically controlled differentials that can integrate with and enhance these active safety systems.
Market Restraints
- High Integration Cost:The complexity of integrating electronic control units and sensors with mechanical differential hardware remains a significant cost barrier for the economy vehicle segment.
- Raw Material Volatility:Price fluctuations in high-strength steel alloys and rare earth magnets used in electronically actuated differentials expose manufacturers to input cost instability.
- Substitution by E-Axles:The rise of integrated e-axle systems in new EV platforms, which achieve torque vectoring via independent motor control, threatens the market for standalone differential units.
Strategic Opportunities
- Aftermarket Conversion Kits:A growing opportunity exists in the performance aftermarket and commercial vehicle segments for retrofittable electronic limited-slip differential conversion kits.
- Software as a Product:Developing on-demand, software-upgradable traction control features for existing differential hardware opens new recurring revenue streams for suppliers.
- Commercial Vehicle Electrification:The electrification of light commercial vehicles in markets like India and Southeast Asia creates a new volume segment for durable, efficient differential units.
Industry Challenges
- Software Engineering Talent Gap:A shortage of mechatronics and software engineers capable of developing and validating the complex control algorithms for active differentials presents a key operational bottleneck.
- Complex Validation Cycles:The need to validate differential performance across a vast range of vehicle platforms and driving conditions, both physically and through simulation, extends development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Differential Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $43.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Differential, Limited Slip Differential, Locking Differential, Torque Vectoring Differential, Torsen Differential Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy Duty Trucks, SUVs, Electric Vehicles Application: On-road Vehicles, Off-road Vehicles, Motorsport, Military Vehicles, Agricultural Machinery End User: OEMs, Aftermarket Suppliers, Fleet Operators, Vehicle Repair Workshops |
| Companies Covered | Dana Incorporated, ZF Friedrichshafen AG, American Axle & Manufacturing, Inc., Eaton Corporation plc, BorgWarner Inc., GKN Automotive Limited, JTEKT Corporation, Linamar Corporation, Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Differential Market Strategic Shifts & Innovations
The convergence of mechanical gearing with sophisticated software control is redefining the differential's role from a passive component to an active contributor to vehicle dynamics and efficiency. This shift prioritizes system integration and intelligent torque management.
Electronic limited-slip differentials use clutch packs and actuators to precisely control torque distribution between wheels. Premium and performance vehicle segments are rapidly adopting this technology for enhanced handling and traction. This innovation is unifying the previously separate functions of mechanical torque transfer and electronic stability control into a single, integrated mechatronic system.
The European Union's General Safety Regulation mandates advanced driver-assistance systems, including enhanced stability control, in all new vehicles. This rule directly influences differential design, pushing suppliers to develop active systems that respond to inputs from the vehicle's central safety controller. The passenger car segment is most affected, accelerating the phase-out of open differentials.
Automaker purchasing behavior is moving away from sourcing standalone mechanical components towards acquiring complete, pre-validated driveline modules. This change favors suppliers who can offer integrated systems combining differentials, axles, and control software. This trend is most prominent in the EV sector in China, where speed-to-market pressures OEMs to rely on system-level solutions from suppliers.
Automotive Differential Market Segmentation
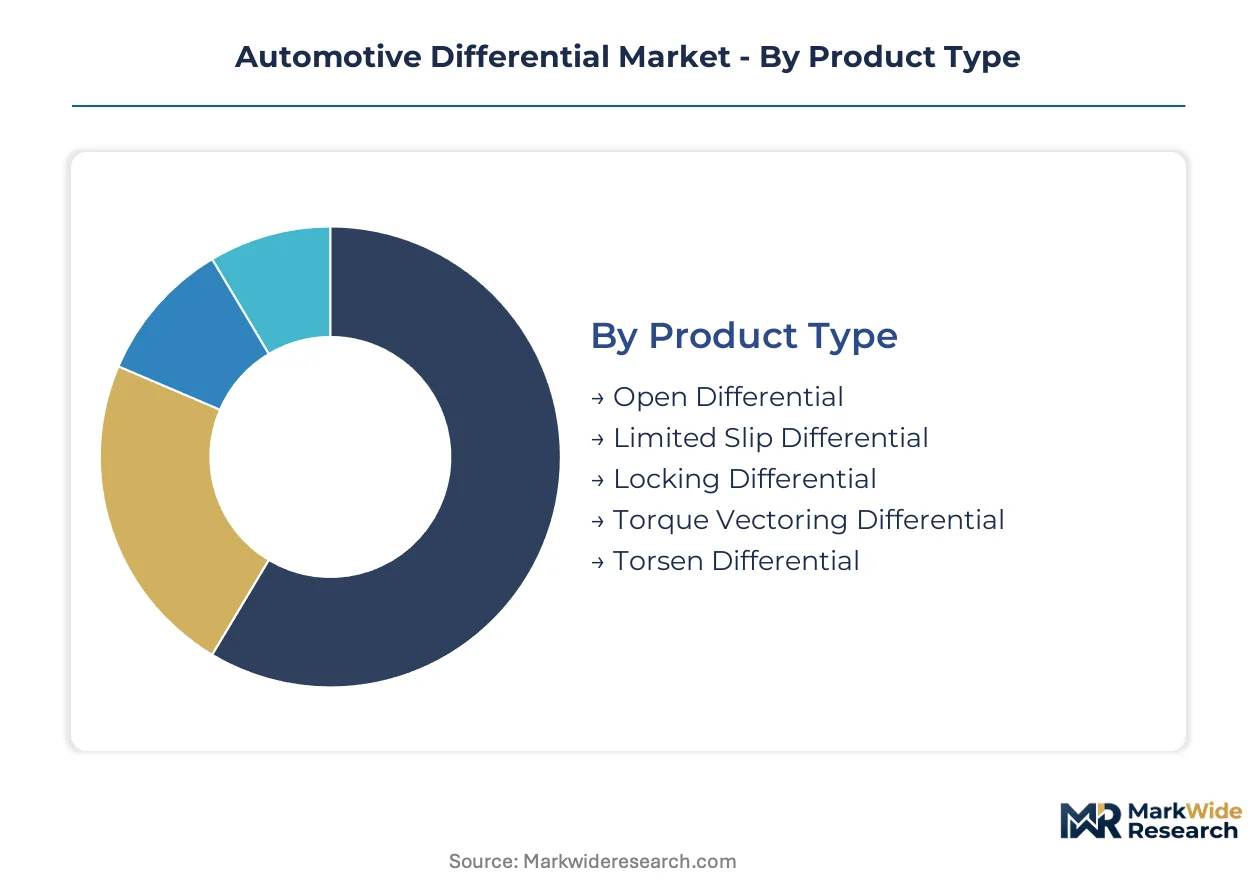
Market segmentation provides a granular view of the automotive differential landscape, revealing distinct demand patterns and technological requirements across various vehicle types and applications. Understanding these divisions helps suppliers align product development with specific industry needs and regulatory mandates. This detailed breakdown clarifies where innovation and investment are most critical for future market expansion.
Product Type:
The market is characterized by a clear distinction between high-volume, cost-sensitive components and specialized, performance-oriented systems.
- Open Differential:This traditional mechanical gear train allows wheels on the same axle to rotate at different speeds, primarily used in economy passenger cars. Demand for open differentials is declining due to safety regulations and consumer preference for enhanced stability.
- Limited Slip Differential:These units automatically transfer torque to the wheel with more traction, improving vehicle stability and performance in diverse driving conditions. Premium vehicle platforms and SUVs exhibit strong demand for limited slip differentials, especially with electronic control integration.
- Locking Differential:Designed for off-road or extreme conditions, these differentials mechanically lock the wheels together, ensuring maximum traction at low speeds. Off-road vehicles and heavy-duty trucks frequently incorporate locking differentials for challenging terrains.
- Torque Vectoring Differential:Advanced systems actively distribute torque between wheels, enhancing cornering performance and dynamic handling. High-performance cars and electric vehicles increasingly adopt torque vectoring differentials for superior agility and responsiveness.
- Torsen Differential:A type of limited-slip differential that uses worm gears and planetary gears to distribute torque based on resistance, offering smooth and progressive power transfer. Performance SUVs and sports cars utilize Torsen differentials for predictable handling characteristics.
Mature deployment sits with Open Differential. Newer deployment is concentrated in Torque Vectoring Differential.
Vehicle Type:
Differential design and specification vary significantly based on the vehicle's intended use and powertrain architecture.
- Passenger Cars:This segment represents the largest volume consumer of automotive differentials, covering a broad range from compact sedans to luxury vehicles. OEMs for passenger cars prioritize solutions that balance cost, efficiency, and integration with electronic stability systems.
- Light Commercial Vehicles:These vehicles, including vans and pickup trucks, require robust and durable differentials capable of handling varying loads and operational demands. Electrification trends in light commercial vehicles are creating new requirements for optimized differential units.
- Heavy Duty Trucks:Differentials for heavy-duty trucks are engineered for extreme durability, high torque capacity, and reliability over long distances. The segment focuses on maximizing uptime and operational efficiency for commercial fleet operators.
- SUVs:The sport utility vehicle segment drives demand for advanced all-wheel-drive and four-wheel-drive systems, often incorporating limited-slip or torque vectoring differentials. Consumer appetite for enhanced off-road capability and on-road stability fuels this demand.
- Electric Vehicles:The transition to electric powertrains fundamentally alters driveline architecture, necessitating specialized differentials optimized for instant torque delivery and regenerative braking. This segment drives innovation in compact, efficient differential designs.
The Passenger Cars segment accounts for the largest volume, while the Electric Vehicles segment exhibits the steepest expansion trajectory.
Application:
The operational environment and performance expectations dictate the specific differential technologies employed.
- On-road Vehicles:This broad category includes passenger cars, SUVs, and light commercial vehicles, where differentials balance stability, comfort, and fuel efficiency. Regulatory mandates for vehicle stability control heavily influence differential design in this application.
- Off-road Vehicles:Designed for challenging terrains, these vehicles demand differentials capable of providing maximum traction and durability. Locking differentials and robust limited-slip systems are critical for performance in off-road applications.
- Motorsport:High-performance differentials are crucial in motorsport for optimizing power delivery, handling, and lap times. Torque vectoring and highly customizable limited-slip differentials are common in racing applications.
- Military Vehicles:Durability, reliability, and extreme performance under harsh conditions are paramount for differentials in military applications. Specialized, heavy-duty locking differentials are frequently specified for these vehicles.
- Agricultural Machinery:Tractors and other agricultural equipment require robust differentials capable of operating in varied soil conditions and heavy loads. These applications prioritize high torque capacity and long operational life.
On-road Vehicles represent the most widespread application. Motorsport applications demand the highest performance differentials.
End User:
The procurement channels and value chain for automotive differentials are defined by the primary buyers and their specific requirements.
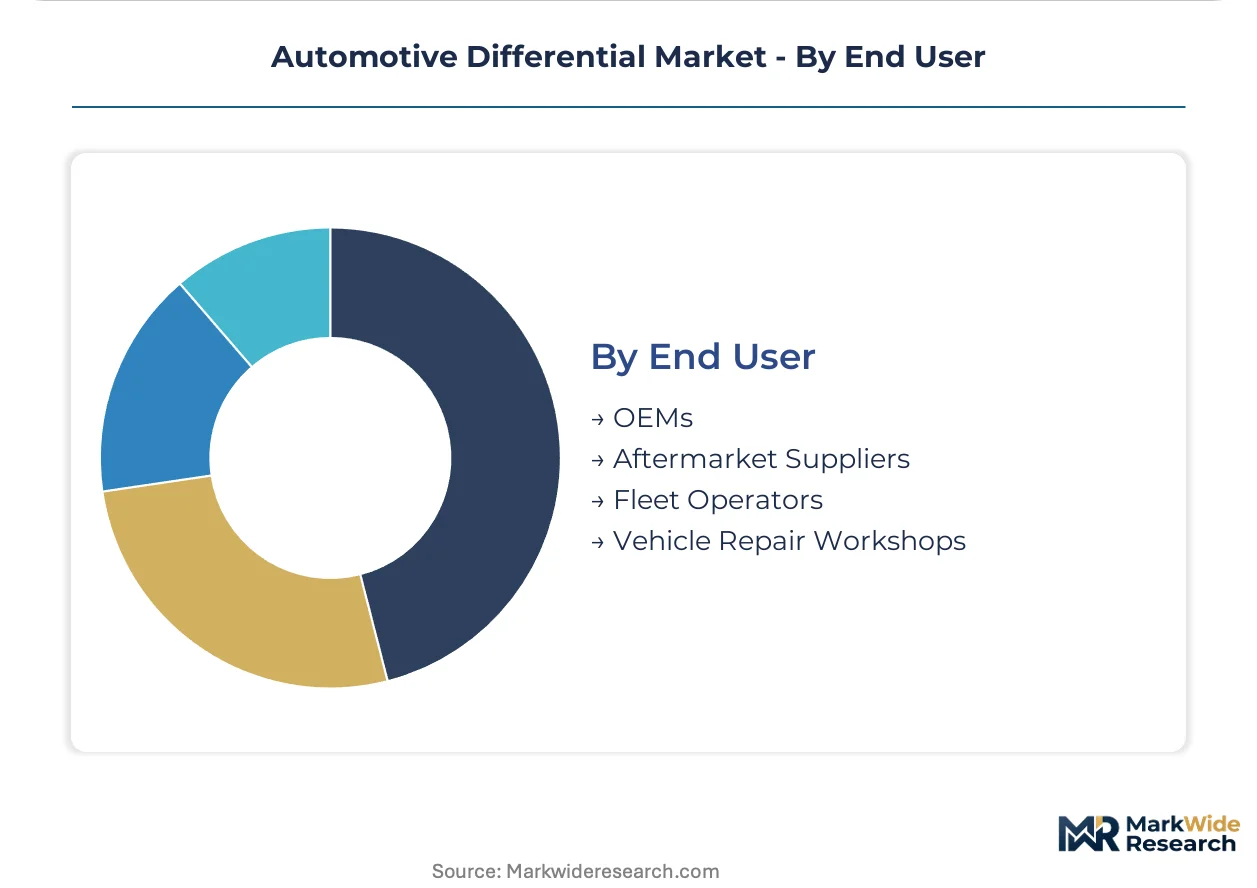
- OEMs:Original Equipment Manufacturers are the primary purchasers, integrating differentials directly into new vehicle production lines. OEM procurement decisions increasingly hinge on a supplier's ability to integrate advanced electronic controls with robust mechanical systems.
- Aftermarket Suppliers:This segment provides replacement differentials and performance upgrade kits for vehicles already in operation. A growing opportunity exists for retrofittable electronic limited-slip differential conversion kits in the aftermarket.
- Fleet Operators:Companies managing large fleets of commercial vehicles focus on durability, maintenance costs, and fuel efficiency in their differential choices. Fleet operators seek long-lasting components to minimize vehicle downtime.
- Vehicle Repair Workshops:These workshops primarily source replacement differentials for repairs and maintenance. Availability of parts and competitive pricing are key considerations for vehicle repair workshops.
OEMs drive the bulk of new differential demand. Aftermarket Suppliers are gaining share through customization and upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive differential market sees significant activity concentrated in manufacturing hubs such as Stuttgart, Germany. Global demand for advanced driveline components is influenced by diverse regulatory frameworks. Key regions drive innovation in both traditional and electric vehicle platforms.
China
China's expansive automotive manufacturing base drives substantial demand for differentials across all vehicle types. The country's GB standards for vehicle components and dual carbon goals accelerate the shift to efficient drivetrain technologies. Shanghai and Guangzhou represent major automotive production clusters, fostering innovation in EV differentials.
Germany
German automotive engineering emphasizes high-performance and premium vehicle platforms, boosting demand for sophisticated limited-slip and torque vectoring differentials. The EU Green Deal objectives push manufacturers towards lighter, more efficient drivetrain components. The Stuttgart region, home to major OEMs and suppliers, remains a hub for differential development.
United States
The United States market experiences strong demand from both the performance vehicle segment and the growing electric vehicle sector. NHTSA mandates for vehicle stability control indirectly influence the adoption of electronically controlled differentials. Automotive centers in Michigan and California's tech hubs contribute to advanced differential integration.
Japan
Japanese automotive manufacturers continue to innovate in driveline technologies, with a focus on reliability and efficiency. Companies like JTEKT Corporation contribute to advancements in torque distribution systems for a global market. Toyota City and other industrial zones remain critical for differential production and research.
India
India's automotive sector, particularly the light commercial vehicle segment, presents a growing volume opportunity for durable and efficient differentials. The country's push for vehicle electrification, supported by initiatives like the PLI scheme, creates new requirements for optimized units. Manufacturing clusters in Chennai and Pune are expanding their capabilities in driveline components.
Automotive Differential Market Key Industry Players
Capital-heavy producers compete with asset-light designers within the automotive differential market. The market structure blends established mechanical component suppliers with newer mechatronics specialists, creating a tiered landscape. Strategic archetypes include integrated system providers, specialized component manufacturers, and aftermarket solution providers. Competitive moves involve strategic partnerships for electronic integration and targeted M&A to acquire software capabilities.
On the premium-tier vector, ZF Friedrichshafen AG exemplifies advanced active differential systems for electric vehicles. BorgWarner Inc. represents a specialist in clutch-based limited-slip and torque vectoring systems across various drivetrain architectures. Dana Incorporated sustains its market position through extensive manufacturing scale in axles and driveline components, serving a broad customer base.
| Leading Market Players |
|---|
| Dana Incorporated |
| ZF Friedrichshafen AG |
| American Axle & Manufacturing, Inc. |
| Eaton Corporation plc |
| BorgWarner Inc. |
| GKN Automotive Limited |
| JTEKT Corporation |
| Linamar Corporation |
| Schaeffler AG |
Cost & Logistics Intelligence
Mechatronics engineering talent concentrated in Germany and Japan creates labor-cost differentials that influence premium differential pricing. This specialized expertise drives higher value propositions for advanced systems across various vehicle platforms.
Pricing Analysis
Value-based pricing anchors differential costs to enhanced vehicle performance and safety outcomes. Price differentiation stems from the complexity of electronic control integration and specialized material use in torque vectoring systems. Pricing softness runs through the traditional open differential segment due to declining demand and regulatory phase-outs. The economy vehicle segment exhibits high price sensitivity, while premium and performance car manufacturers prioritize advanced functionality over cost.
Supply Chain Analysis
Direct-to-OEM channels handle the bulk of automotive differential distribution, reflecting long-term procurement contracts. Geographic supply concentration resides in manufacturing hubs across China, Germany, and Japan. Production relies on critical inputs like high-strength steel alloys and rare earth magnets for electronically actuated units. Raw material volatility presents a significant structural risk for component manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive differential market presents a supply-constrained narrative, particularly for advanced electronic systems. A capacity bottleneck in specialized mechatronics component manufacturing currently props up pricing for high-performance units.
For Market Incumbents: To counter the threat of e-axle substitution, incumbents must deepen system integration capabilities. Expand offerings beyond mechanical hardware to include advanced electronic control units and software-defined functions. Invest in mechatronics R&D to develop next-generation active differentials. Strategic partnerships with software specialists will enhance competitive positioning against integrated e-powertrain solutions.
For New Entrants and Emerging Players: Enter via the performance aftermarket segment with retrofittable electronic limited-slip differential conversion kits. Target the light commercial vehicle electrification market in Asia for durable, efficient units. Develop software-as-a-product offerings for on-demand traction control features. Focus on agile development cycles to quickly integrate with diverse vehicle platforms.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized mechatronics component suppliers given the accelerating shift to active differentials. The long-term viability of companies offering integrated hardware-software solutions appears strong over the next decade. Target acquisition archetypes include firms with proven electronic control unit expertise and robust software IP. The signal to watch is the increasing OEM reliance on system-level driveline solutions from Tier 1 suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Software-Defined Driveline Controls | Enhances differential functionality and enables new recurring revenue streams through feature upgrades. |
| Expand Manufacturing Capacity for EV Differentials | Addresses demand from the rapidly growing electric vehicle segment and supports global production mandates. |
| Form Strategic Partnerships for Mechatronics Integration | Accelerates development of complex active differential systems and mitigates software engineering talent gaps. |
| Develop Aftermarket Electronic LSD Conversion Kits | Captures new revenue from performance enthusiasts and extends product lifecycle beyond OEM installations. |
| Diversify Raw Material Sourcing for Critical Alloys | Mitigates price volatility and supply chain risks associated with high-strength steel and rare earth magnets. |
Research Approach
Multi-period observation of vehicle production volumes and technology adoption rates anchored the trend analysis, supplemented by interviews with OEM platform engineers and Tier 1 procurement leads. Primary insights were gathered from aftermarket distributors and mechatronics R&D specialists. Secondary data sources included vehicle production databases, regulatory filings from NHTSA, and automotive trade association reports. This approach ensured robust bottom-up and top-down triangulation of market dynamics.
An input-output matrix facilitated quantitative modeling across the analysis window, projecting market evolution. Segmentation dimensions modeled included product type, vehicle type, application, end-user, and regional production clusters. Compound annual growth rates derived from regression models analyzed historical data and projected market shifts. Key forecast inputs included electric vehicle adoption rates and regulatory compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme raw material price shocks or accelerated e-axle substitution. All projections reflect assumptions about technological progression and regulatory stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Brackets Market
Automotive Components
Automotive Silencer Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Automotive Backing Plate Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Automotive Chromium Market
Automotive Components
Automotive Active Seat Headrests Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Automotive Brake Pads Market
Automotive Components
Germany Automotive Carbon Fiber Composites Market
Automotive Components
Automotive Commutator Market
Automotive Components
Africa and Middle East Automotive Actuators Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
Europe Torque Vectoring Market
Automotive Components
Regenerative Suspension System Market
Automotive Components
Automotive Wiper Blades Market