
 Automotive Metal Stamping Market | 2026-2036
Automotive Metal Stamping Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Metal Stamping Market Analysis
IATF 16949 certification is bifurcating the supplier base into qualified tier-1 participants and marginal operators. Magna International leverages its vertical manufacturing footprint to anchor North American OEM programs. Martinrea International specializes in lightweight chassis stamping, competing aggressively for electric vehicle platform awards.
Automotive metal stamping encompasses the cold-forming of sheet metal blanks into precise structural and functional components through die-based pressing operations, typically achieving tolerances within 0.1 millimeters for body-in-white panels. The process serves as the foundational manufacturing stage for vehicle crash structures, closures, and powertrain housings. Chassis components dominate current volume demand as OEMs prioritize structural rigidity for battery-electric architectures. Aluminum material adoption is accelerating fastest among material segments, driven by mass reduction imperatives, though steel retains margin depth through advanced high-strength grades. Progressive die technology leads capital deployment for high-volume programs, while transfer die systems capture complex multi-stage forming requirements.
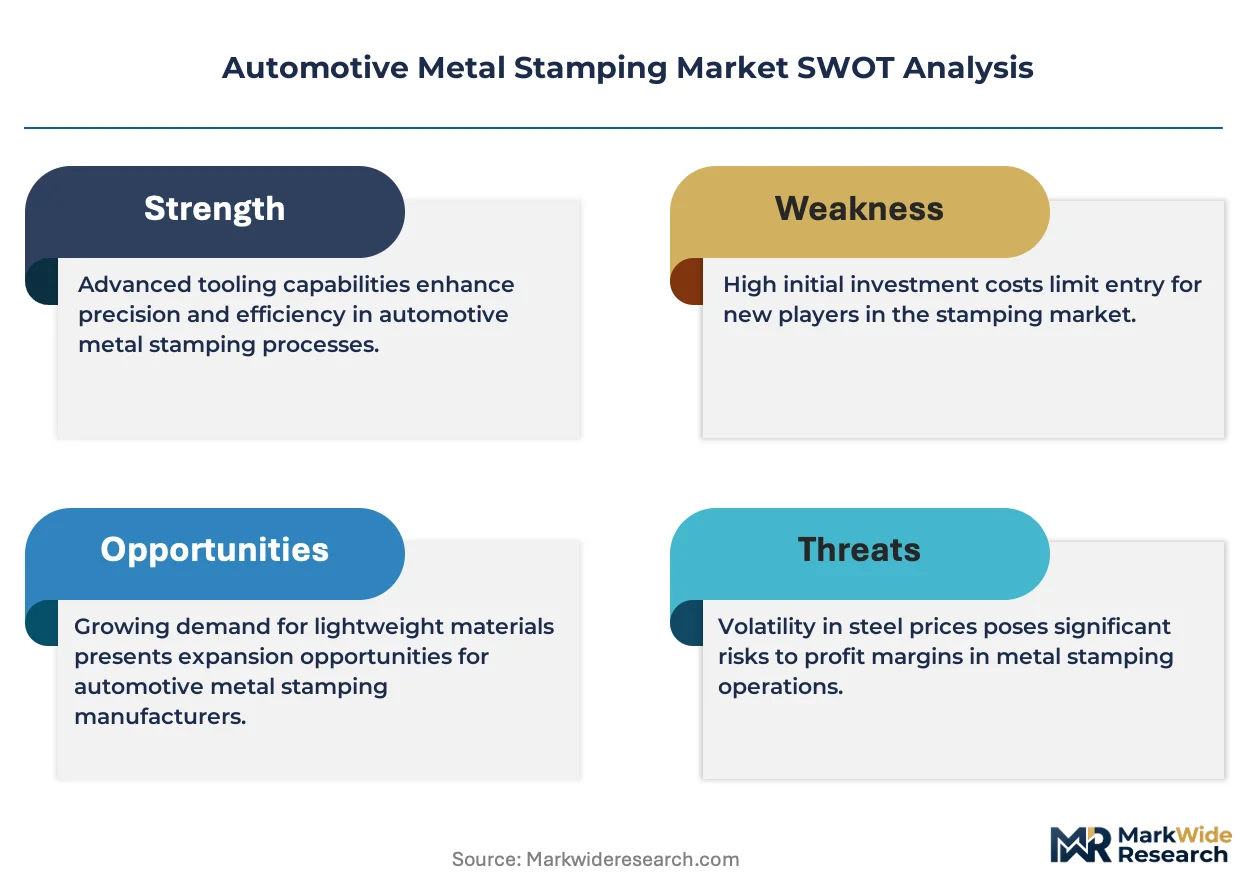
The U.S. EPA tailpipe standards and the EU Green Deal emissions framework are reshaping material specifications and lightweighting mandates across stamping supply chains. NHTSA crashworthiness protocols and ECE R94/R95 regulations further dictate high-strength forming requirements that constrain supplier qualification. Stakeholders must monitor evolving battery enclosure stamping standards as electric vehicle architectures redefine structural load paths and thermal management integration.
Market Dynamics
Electric vehicle platform architectures are fundamentally restructuring metal stamping demand, forcing suppliers to retool for aluminum-intensive battery enclosures and multi-material joining while maintaining legacy internal combustion programs.
Growth Catalysts
- EU Green Deal emissions framework:Binding carbon neutrality targets for 2050 mandate lightweight chassis components, accelerating aluminum stamping adoption across German and French OEM supply chains.
- High-strength steel grades:Third-generation advanced high-strength steels enable 25-40% mass reduction in crash structures without sacrificing forming feasibility, preserving steel's position in structural stampings.
- Battery enclosure stampings:Electric vehicle thermal management requirements create new demand categories for precision-formed aluminum trays and cooling channel integrations.
Market Restraints
- Aluminum price volatility:LME aluminum price swings compress margin predictability for long-term OEM contracts, particularly affecting North American suppliers without captive smelter arrangements.
- Tooling capex concentration:Progressive die systems for high-volume electric vehicle programs require 18-24 month lead times, locking capital before platform volumes materialize.
- Substitution by carbon fiber composites:Premium electric vehicle architectures in Germany and California increasingly specify composite body panels for non-structural applications, displacing aluminum stampings above $80/kg component cost thresholds.
Strategic Opportunities
- India electric vehicle localization:PLI scheme incentives for domestic manufacturing create first-mover advantages for stamping capacity near Chennai and Pune assembly clusters.
- Thermal runaway containment stampings:Emerging battery safety regulations require multi-layer aluminum shielding designs that integrate stamping with brazing and sealing processes.
- Digital die tryout convergence:Virtual stamping simulation combined with real-time press sensor feedback reduces physical prototype iterations by 40-60% for new platform launches.
Industry Challenges
- IATF 16949 certification backlog:Auditor capacity constraints delay supplier qualification timelines by 6-12 months, freezing tier-2 and tier-3 participants from new OEM program awards.
- Multi-material joining complexity:Dissimilar metal welding between aluminum stampings and steel substructures requires laser-arc hybrid processes that extend cycle times and defect rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Metal Stamping Market |
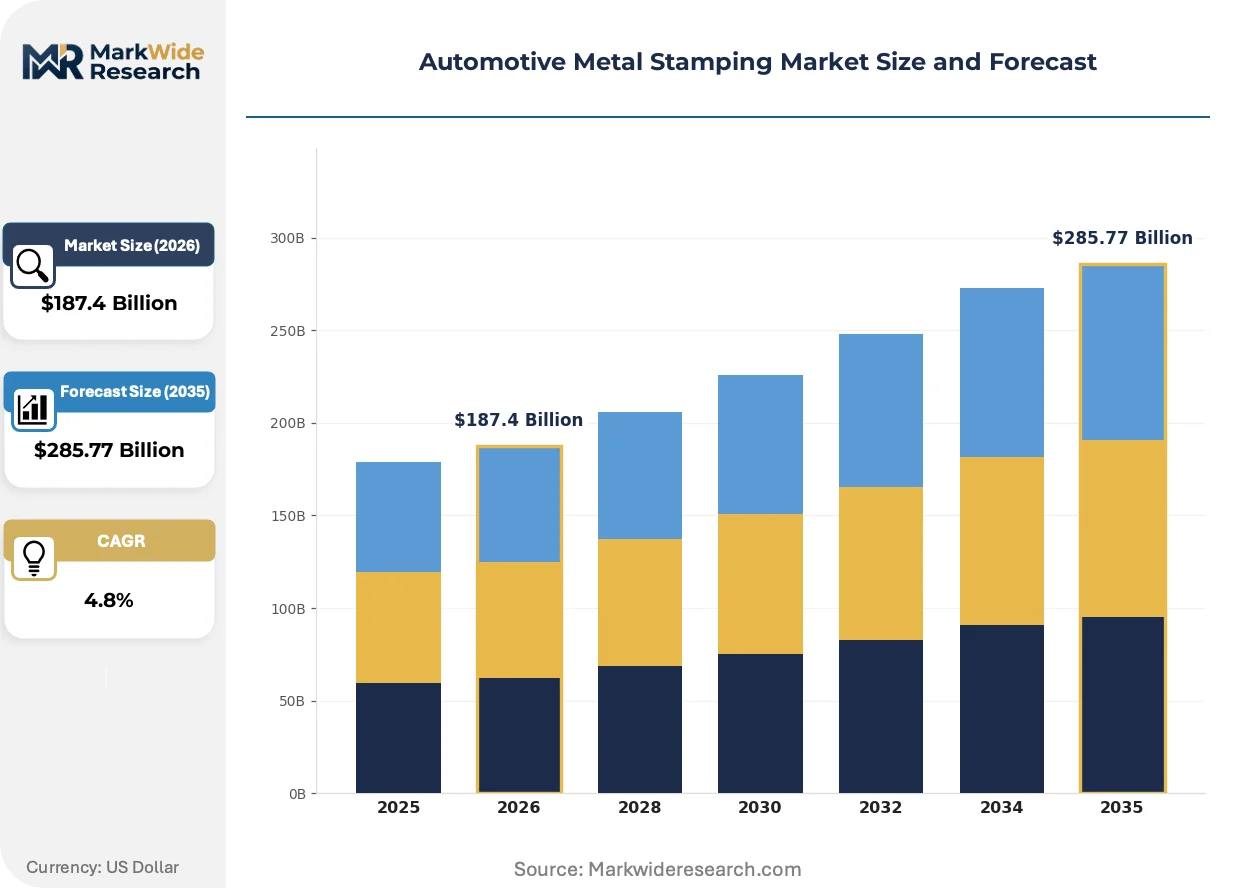
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stamping Parts, Chassis Components, Engine Components, Transmission Components Material: Steel, Aluminum, Copper, Composite Technology: Progressive Die, Transfer Die, Hydraulic Press, Mechanical Press End User: OEMs, Tier-1 Suppliers, Aftermarket Suppliers, Vehicle Assemblers |
| Companies Covered | Magna International Inc., LMC Industries, General Motors Company, Connor Manufacturing Services, Xometry, Ford Motor Company, Martinrea International Inc., Arconic, Stellantis N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Metal Stamping Market Emerging Trajectories
Stamping process digitization and material science advances are compressing development cycles while enabling geometries previously achievable only through casting or machining operations.
Hot stamping of boron-aluminum hybrid blanks is bifurcating the structural component market. OEMs in Germany and Japan adopt these blanks for A-pillar and roof rail reinforcements. The technology is bifurcating supplier capabilities into heat-treatment-equipped specialists and conventional cold-stamping operations.
REACH substance restrictions on hexavalent chromium coatings force conversion to trivalent chromium and zirconium-based pretreatments. Surface treatment suppliers in Belgium and the Netherlands scale capacity for compliant conversion coatings. European stamping exports to markets without equivalent bans face dual-process cost burdens.
OEM technical sourcing teams consolidate supplier panels from 8-12 stamping sources per region to 3-4 strategic partners capable of full chassis subsystem delivery. Tier-1 integrators in Michigan and Bavaria capture expanded scope through design-for-manufacturing engineering services. This concentration is most visible in battery-electric platform awards where single-source accountability reduces interface risk.
Automotive Metal Stamping Market Segmentation
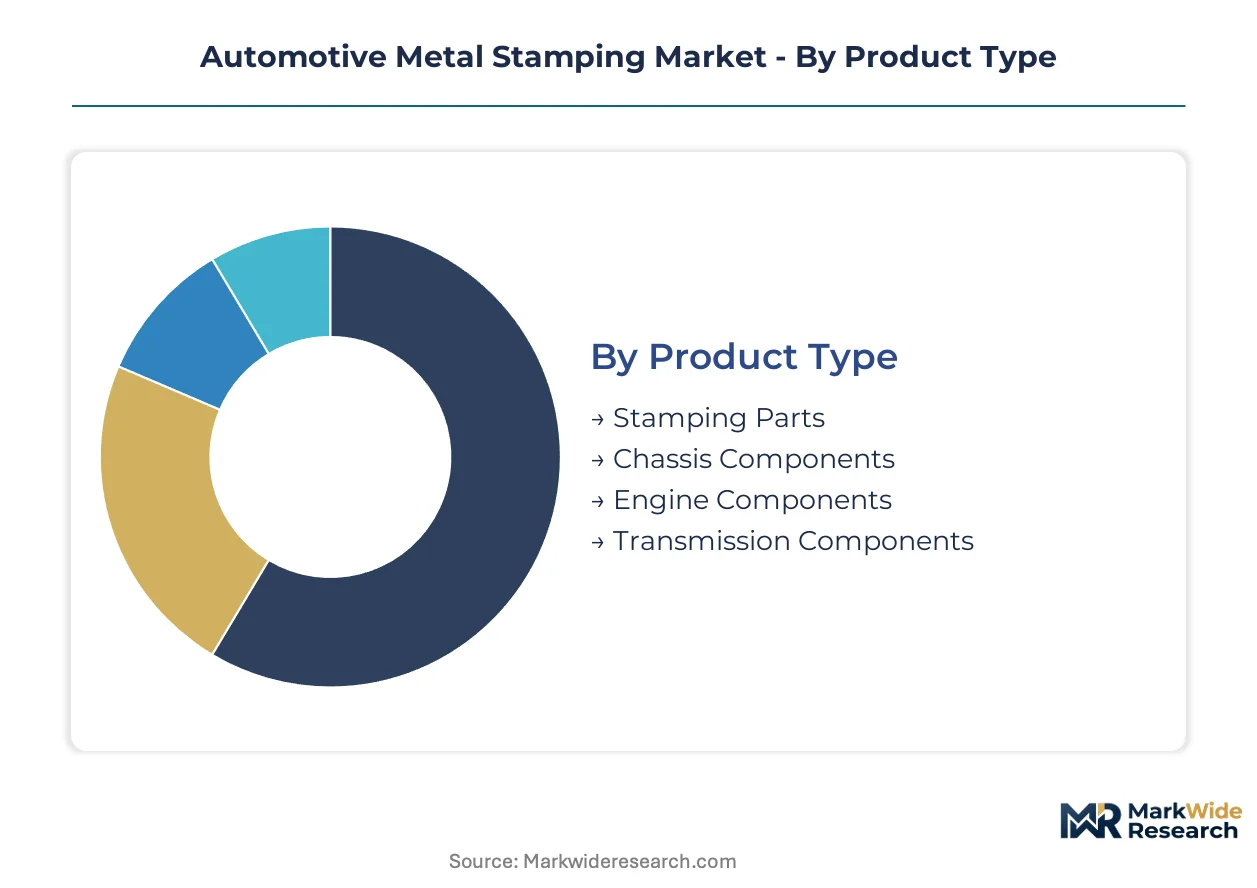
Automotive metal stamping segmentation reveals how technology choices and material specifications determine supplier profitability. OEM platform decisions cascade through each category, concentrating margin in aluminum-intensive and high-precision forming segments.
Product Type:
Margin pools concentrate in structural stampings where crash performance certification creates pricing power and multi-year program locks.
- Stamping Parts:Generic-formed components including brackets, clips, and reinforcement plates serve across vehicle architectures. Demand clusters in high-volume compact and mid-size segments where part commonality maximizes die utilization rates.
- Chassis Components:Structural stampings for subframes, control arms, and cradle assemblies require advanced high-strength steel forming. Battery-electric platforms in Germany and China are accelerating aluminum chassis adoption for mass reduction targets.
- Engine Components:Precision-formed oil pans, valve covers, and timing chain housings retain steel dominance in internal combustion programs. Thermal management stampings for electric motor housings represent the emerging substitution vector.
- Transmission Components:Clutch housings, gear separator plates, and torque converter shells face volume pressure as electrification reduces multi-speed gearbox complexity.
The dominant share belongs to Chassis Components, while Stamping Parts is closing the gap fastest through platform standardization across electric vehicle architectures.
Material:
Cost tiers separate commodity steel from premium aluminum and specialized alloys, with certification requirements determining supplier qualification barriers.
- Steel:Advanced high-strength grades including DP980 and CP800 enable 25-40% mass reduction in structural applications. German OEMs specify these grades for A-pillar and roof rail reinforcements under EU Green Deal lightweighting mandates.
- Aluminum:5xxx and 6xxx series alloys dominate battery enclosure stampings where thermal conductivity and corrosion resistance intersect. LME price volatility compresses margin predictability for North American suppliers without captive smelter arrangements.
- Copper:Limited to electrical busbar stampings and motor winding applications where conductivity specifications override cost considerations.
- Composite:Carbon fiber-reinforced thermoplastic stampings penetrate premium electric vehicle body panels above $80/kg component cost thresholds in California and German markets.
Steel retains volume leadership, though aluminum is expanding most quickly as battery-electric architectures redefine material specifications.
Technology:
Capital intensity and cycle time differentials create distinct competitive positions across forming methodologies.
- Progressive Die:Multi-station tooling achieves 600+ strokes per minute for high-volume body-in-white panels. Tier-1 suppliers in Michigan and Bavaria deploy these systems for single-source accountability on electric vehicle platform awards.
- Transfer Die:Robotic part transfer between discrete stations handles complex geometries including deep-drawn transmission housings. 18-24 month tooling lead times lock capital before platform volumes materialize.
- Hydraulic Press:Controlled forming speeds suit thick-gauge chassis components and hot stamping operations requiring precise temperature management.
- Mechanical Press:Crank-drive systems dominate legacy high-speed blanking operations where energy efficiency and maintenance simplicity outweigh flexibility requirements.
Progressive Die commands the largest installed base, yet Transfer Die is gaining share fastest through battery enclosure complexity requirements.
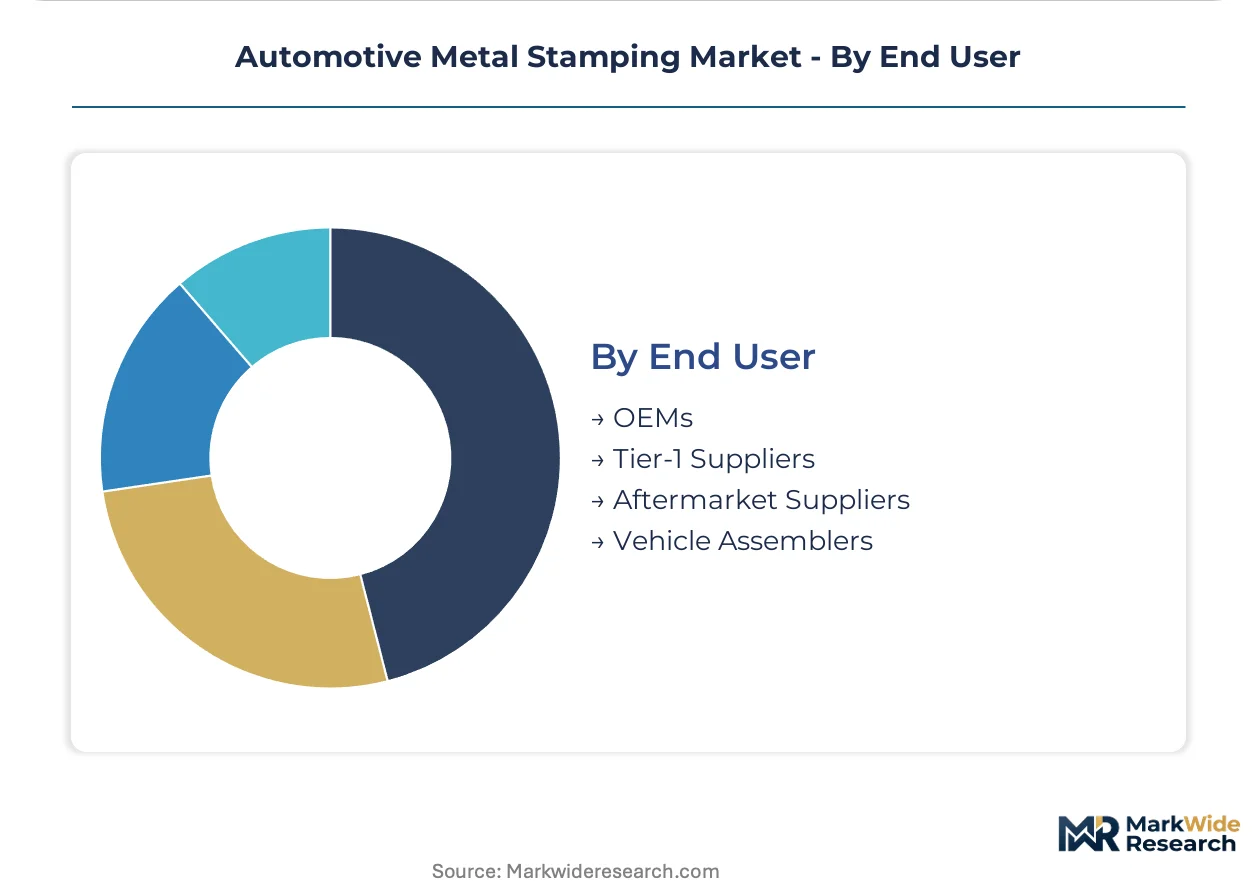
End User:
Customer type determines contract structure, with direct OEM relationships capturing design-phase engineering value.
- OEMs:In-house stamping operations at Volkswagen, Toyota, and Ford retain control over proprietary body-in-white architectures. Vertical manufacturing footprints anchor program awards for strategic chassis subsystems.
- Tier-1 Suppliers:Magna International and Martinrea International compete for electric vehicle platform awards through design-for-manufacturing services. IATF 16949 certification bifurcates qualified participants from marginal operators.
- Aftermarket Suppliers:Crash repair panels and replacement structural components serve aging vehicle populations with less stringent forming tolerance requirements.
- Vehicle Assemblers:Contract manufacturers including Magna Steyr and Valmet Automotive source stamped subsystems for low-volume specialty programs.
Tier-1 Suppliers hold the dominant procurement position, while OEMs are consolidating fastest through vertical integration into battery enclosure manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OEM procurement teams cluster stamping awards near final assembly plants, concentrating supplier investment in countries with dense vehicle production footprints. Tier-1 integrators prioritize co-location with German, Chinese, and American OEM engineering centers to capture design-phase influence.
United States
Detroit Three OEMs drive demand for aluminum-intensive battery enclosures and high-strength steel crash structures. NHTSA crashworthiness protocols mandate forming tolerances that disqualify marginal suppliers. Michigan and Ohio host the densest stamping supplier clusters, with Magna and Martinrea anchoring electric vehicle platform awards near Ford's Rouge Complex and GM's Factory ZERO.
Germany
EU Green Deal carbon neutrality targets force Volkswagen, BMW, and Mercedes-Benz to specify lightweight chassis stampings. KBA type-approval requirements for structural components create certification barriers for non-European suppliers. Bavaria and Baden-Württemberg concentrate heat-treatment-equipped specialists serving premium electric vehicle architectures.
China
MIIT dual carbon goals accelerate aluminum adoption for battery-electric platforms from BYD, NIO, and Xpeng. GB standards for vehicle structural integrity constrain forming process qualification. Yangtze River Delta and Pearl River Delta clusters dominate capacity, with Shenzhen and Shanghai suppliers capturing CATL and BYD battery enclosure programs.
Japan
METI automotive decarbonization roadmaps prioritize hot-stamped boron steel for collision safety. JIS standards for high-strength forming maintain domestic supplier preference. Toyota City and Nagoya industrial corridors concentrate progressive die specialists serving hybrid and solid-state battery vehicle architectures.
India
PLI scheme incentives for domestic electric vehicle manufacturing attract stamping capacity near Chennai and Pune assembly clusters. BIS automotive steel standards are tightening to match global crash performance benchmarks. Tamil Nadu and Maharashtra host emerging supplier parks serving Tata Motors and Mahindra electric platform localization.
Automotive Metal Stamping Market Vendor Landscape
Player mix skews toward vertically integrated tier-1 specialists with captive tooling design and heat-treatment capabilities. The supplier base bifurcates between IATF 16949-certified strategic partners and marginal operators frozen from new OEM awards. Two archetypes dominate: full-chassis subsystem integrators and aluminum-intensive battery enclosure specialists. Competitive moves concentrate on multi-material joining capability acquisition and digital die tryout technology deployment.
Within the tier-1 integrator tier, Magna International Inc. and Martinrea International Inc. exemplify full-chassis subsystem delivery models. Magna International Inc. anchors North American OEM relationships through vertical manufacturing footprints. Martinrea International Inc. occupies a position among lightweight chassis specialists competing for electric vehicle platform awards. Arconic represents the aluminum materials-to-components archetype with upstream smelter linkages that buffer LME price volatility.
| Leading Market Players |
|---|
| Magna International Inc. |
| LMC Industries |
| General Motors Company |
| Connor Manufacturing Services |
| Xometry |
| Ford Motor Company |
| Martinrea International Inc. |
| Arconic |
| Stellantis N.V. |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month tooling lead times for progressive die systems concentrate pricing power with tier-1 suppliers possessing captive heat-treatment capacity and IATF 16949 certification, while marginal operators face exclusion from long-term OEM contracts.
Pricing Analysis
Cost-plus contracts indexed to LME aluminum and HRC steel benchmarks dominate long-term OEM agreements, with price differentiation resting on IATF certification tier and multi-material joining capability. Premium-mid-economy pricing stratification separates heat-treatment-equipped specialists from conventional cold-stamping operations. Pricing pressure stems from aluminum price volatility compressing margin predictability for North American suppliers without captive smelter arrangements. Tier-1 integrators exhibit lowest price sensitivity due to design-phase engineering value capture, while tier-2 participants face acute cost compression.
Supply Chain Analysis
Just-in-time inventory strategies dominate high-volume body-in-white programs, though battery enclosure stampings increasingly require strategic aluminum stockpiles to buffer LME volatility. Supply concentrates in Germany, China, and the United States, with raw material dependencies on 5xxx/6xxx aluminum series, advanced high-strength steel grades, and specialized die steels. Single-source vulnerability for heat-treatment-equipped specialists creates structural risk. Distribution runs through tier-1 subsystem integrators co-located with OEM engineering centers in Michigan, Bavaria, and the Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified heat-treatment capacity and IATF 16949 certification have become scarce assets that bifurcate the supplier base, freezing marginal operators from electric vehicle platform awards while concentrating margin in vertically integrated tier-1 specialists.
For Market Incumbents: Shield program positions by deepening backward integration into captive aluminum smelter arrangements and acquiring laser-arc hybrid welding capability to address multi-material joining complexity. Carbon fiber composite substitution in premium German and California electric vehicle architectures threatens aluminum stamping volumes above cost thresholds. Certification investment represents the critical defensive lever. For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors near Chennai and Pune assembly clusters, where domestic electric vehicle localization creates first-mover advantages for stamping capacity without incumbent tooling lock-in. Battery enclosure thermal management stampings offer the most penetrable white-space, with digital die tryout technology as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because OEM technical sourcing teams are compressing supplier panels from 8-12 sources per region to 3-4 strategic partners capable of full chassis subsystem delivery. Target acquisition archetype: heat-treatment-equipped specialists with existing IATF certification and aluminum-intensive platform exposure. Watch for battery safety regulation evolution on thermal runaway containment as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Joining Capability Acquisition | Laser-arc hybrid welding addresses aluminum-steel dissimilar metal joining requirements for battery-electric architectures. |
| Digital Die Tryout Technology Deployment | Virtual stamping simulation with real-time press sensor feedback reduces physical prototype iterations for new platform launches. |
| Heat-Treatment Capacity Expansion | Hot stamping of boron-aluminum hybrid blanks enables A-pillar and roof rail reinforcements for EU Green Deal compliance. |
| Captive Aluminum Supply Arrangement | Upstream smelter linkages buffer LME price volatility and secure margin predictability for long-term OEM contracts. |
| IATF 16949 Certification Fast-Track | Auditor capacity constraints delay qualification timelines, creating competitive moat for certified participants in new program awards. |
Methodological Framework
A spread of perspectives from OEM platform engineers, tier-1 supplier procurement leads, heat-treatment equipment specialists, and aftermarket distributors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, vehicle production databases, IHS Markit registration data, and customs/trade records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled include propulsion architecture, material specification, forming technology, and regional production cluster across the analysis window. CAGRs derived from regression analysis of historical production volumes, platform mix shifts, and content-per-vehicle trajectories. Industry-specific forecast inputs incorporated battery-electric platform rollout schedules and EU Green Deal compliance timelines.
Material uncertainties — aluminum price volatility, auditor capacity constraints for IATF certification, and carbon fiber composite substitution thresholds — sit outside the modeled envelope. Forecasts reflect documented assumptions on OEM platform standardization and thermal management stamping adoption curves. Revision becomes warranted when battery enclosure safety regulation crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
North America Automotive Glass Market
Automotive Components
Automotive Brackets Market
Automotive Components
Europe Automotive Market
Automotive Components
Automotive Solar Control Glass Market
Automotive Components
Global Automotive Water Valve Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Europe Automotive Plastics Market
Automotive Components
Automotive Bearing Market
Automotive Components
Automotive Door Module Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Africa and Middle East Automotive Actuators Market
Automotive Components
Japan Automotive Actuators Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Global Automatic Lubrication System Market