
 Motorcycle Horns Market | 2026-2036
Motorcycle Horns Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Horns Market Insights
Electromagnetic-to-piezoelectric transducer migration is rewriting acoustic output architectures across motorcycle horn manufacturing. Robert Bosch GmbH leverages its automotive sensor heritage to anchor premium electric horn portfolios with integrated decibel modulation. HELLA GmbH & Co. KGaA sustains dual-tone system dominance through precision electromagnetic coil engineering. Uno Minda Ltd. competes aggressively on cost-optimized direct-current platforms tailored to Indian OEM specifications.
A motorcycle horn is an electromechanical or pneumatic signaling device engineered to emit audible warnings within specified decibel ranges, typically constructed from steel diaphragms, copper voice coils, and ABS or metal housings designed to withstand vibration, moisture, and temperature cycling between minus 40 and 85 degrees Celsius. Its primary commercial purpose is to satisfy vehicle type-approval safety mandates while providing rider-to-traffic hazard communication. Electric horns occupy the volume core due to OEM bundling economies and standardized 12-volt electrical architectures, yet air horns command aftermarket margin pools through displacement-seeking cruiser and touring segments. Dual tone configurations are gaining share as manufacturers integrate dual-frequency outputs to satisfy evolving pedestrian-alert regulations without adding discrete hardware.
India's Automotive Industry Standard AIS-014, the European Union's UNECE R28 type-approval framework, and the United States FMVSS 571.141 safety standard collectively dictate minimum sound-pressure thresholds, environmental durability testing, and electromagnetic compatibility requirements that determine market access across major motorcycle-producing jurisdictions. Non-compliant suppliers face exclusion from OEM procurement lists and aftermarket distribution channels in regulated economies. Stakeholders must monitor divergence between emerging-market self-certification regimes and advanced-economy third-party conformity assessment requirements when configuring regional product roadmaps and testing budgets.
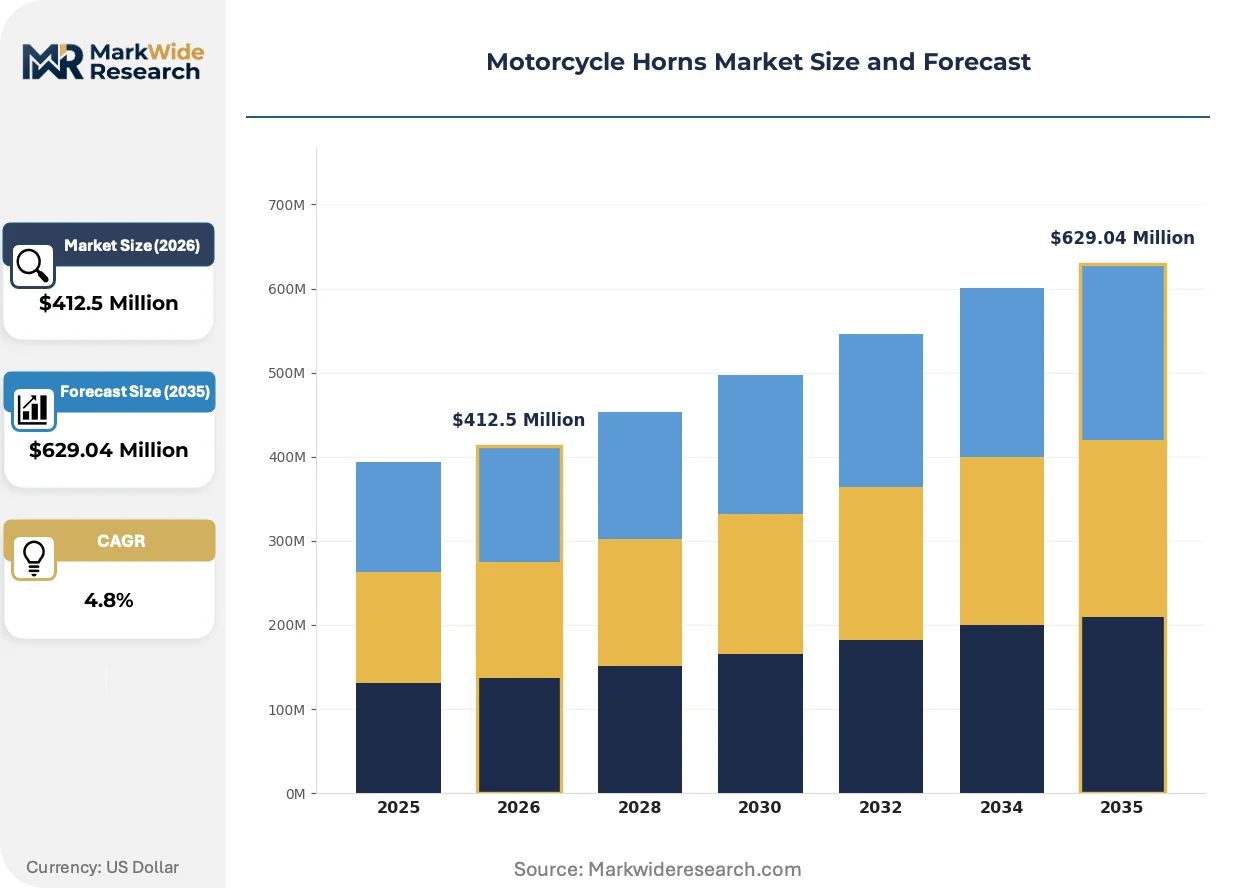
Market Dynamics
Electromagnetic-to-piezoelectric transducer migration is collapsing legacy acoustic architectures across motorcycle horn manufacturing, compressing component counts while elevating output precision for OEM and aftermarket channels alike.
Growth Catalysts
- AIS-014 Mandate:India's mandatory safety certification for two-wheeler horns is elevating product standards across South Asian supply chains and disqualifying non-compliant suppliers from OEM procurement lists.
- Aftermarket Customization:Touring and cruiser riders seeking displacement-seeking acoustic signatures are expanding the addressable consumer base for premium air horn configurations.
- Dual-Frequency Integration:Manufacturers are embedding dual-tone outputs within single-housing designs to satisfy evolving pedestrian-alert regulations without adding discrete hardware modules.
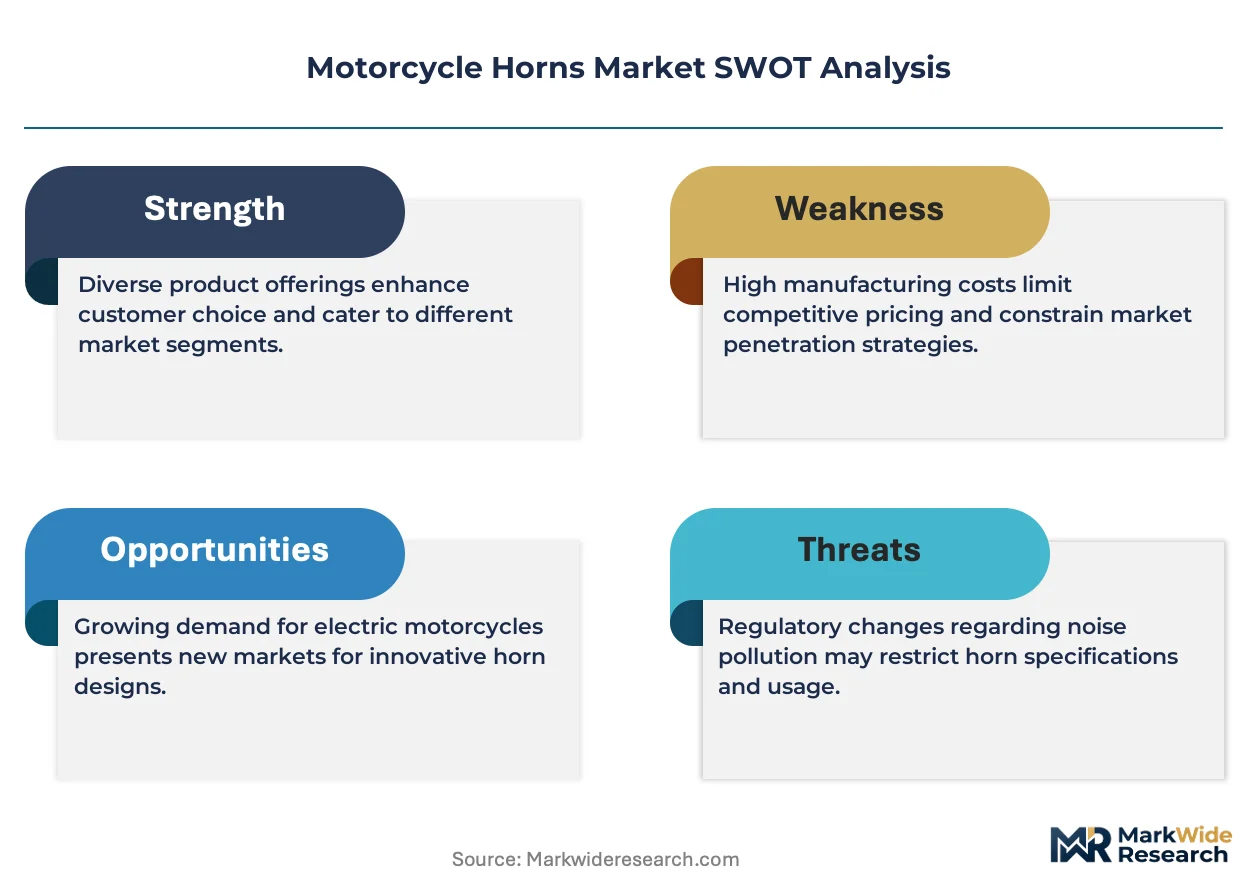
Market Restraints
- Copper Voice Coil Volatility:Raw material cost swings for copper windings compress margin stability for electromagnetic horn producers serving price-sensitive OEM segments.
- Supply Concentration Risk:Precision electromagnetic coil engineering capabilities concentrate among a limited set of European and East Asian specialist manufacturers.
- UNECE R28 Friction:Divergent type-approval testing protocols between the European framework and emerging-market self-certification regimes inflate regional product roadmapping costs.
Strategic Opportunities
- Indian Production Scaling:Domestic motorcycle manufacturing expansion creates captive demand for cost-optimized direct-current horn platforms certified to BIS-aligned specifications.
- Decibel Modulation Convergence:Integration of automotive sensor heritage with acoustic output control enables smart horn systems that adjust sound pressure to ambient traffic density.
- Digital Aftermarket Channels:E-commerce platforms specializing in cruiser and touring accessories are disintermediating traditional parts distributors for premium air horn sales.
Industry Challenges
- Electromagnetic Compatibility Testing:Validating horn systems against radiated emission standards requires specialized anechoic chamber investments that strain mid-tier supplier capex budgets.
- AIS-014 Certification Timelines:Indian laboratory queue congestion extends product validation cycles, delaying market entry for redesigned acoustic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Horns Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Horns, Air Horns, Mechnical Horns, Dual Tone Horns Installation Type: Handlebar Mount, Front Mount, Universal Mount, Custom Fit Power Source: Battery Powered, Direct Current, Alternating Current, Solar Powered Sound Level: 85 dB, 100 dB, 110 dB, 120 dB |
| Companies Covered | Robert Bosch GmbH, HELLA GmbH & Co. KGaA, Uno Minda Ltd., Mitsuba Corporation, FIAMM Components, Zhejiang Shengke Auto Parts Co., Ltd., Wolo Manufacturing Corp., Custom Dynamics, HornBlasters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Horns Market Trends and Innovations
Piezoelectric transducer architectures are actively rewiring competitive positioning across motorcycle horn manufacturing. Three convergent developments are compressing legacy electromagnetic dominance while opening new performance tiers.
Piezoelectric ceramic actuators are collapsing the traditional trade-off between acoustic output and housing mass. Aftermarket specialists serving touring segments are adopting these platforms for weight-critical applications. The technology is collapsing component counts from seven discrete parts to three integrated modules, enabling thinner form factors that fit within constrained handlebar mounting envelopes.
UNECE R28's updated pedestrian-alert provisions are forcing redesigns of frequency-sweep patterns across European-bound motorcycle models. Manufacturers must now demonstrate minimum sound-pressure levels across multiple approach angles rather than single-point measurement. The touring and commuter segments are responding by integrating dual-resonance chambers that satisfy the directive without external amplification hardware.
Certification-driven preference shifts are restructuring procurement relationships between Indian OEMs and their horn suppliers. Domestic manufacturers are disqualifying vendors lacking documented AIS-014 test reports, consolidating award volumes toward integrated component houses with captive testing facilities. This concentration is most visible in the Pune and Chennai manufacturing clusters, where tier-one suppliers have vertically integrated acoustic validation capabilities.
Motorcycle Horns Market Segmentation
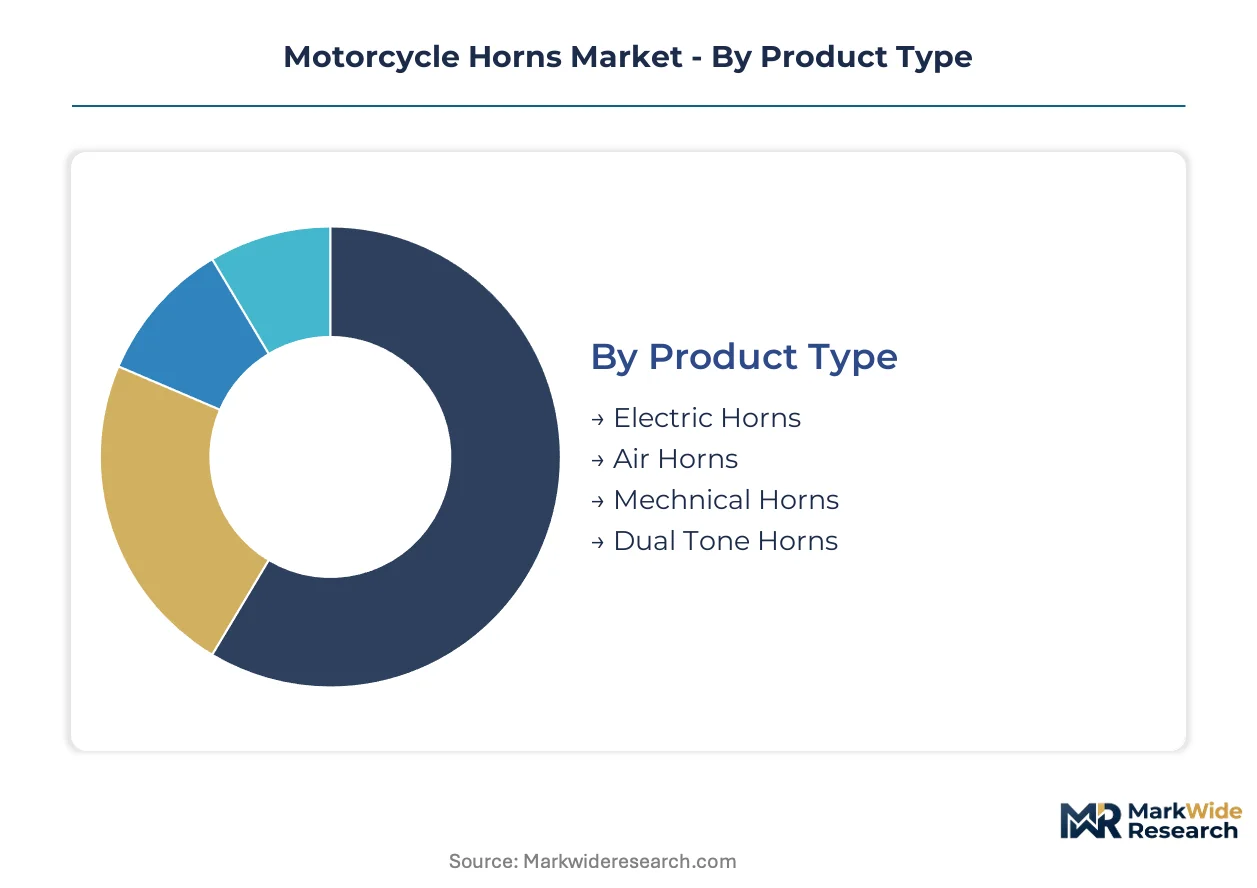
Segmentation in motorcycle horns reveals how acoustic engineering, mounting constraints, and electrical architectures split procurement decisions between OEM bundling economies and aftermarket customization premiums. Understanding these divides exposes where margin pools concentrate versus where volume throughput dominates.
Product Type:
Mature electromagnetic platforms dominate installed base volumes while emerging transducer technologies reshape premium positioning.
- Electric Horns:Electromagnetic diaphragm assemblies with copper voice coils and steel resonators constitute the default 12-volt architecture across mass-market motorcycles. OEM bundling contracts in India and Southeast Asia concentrate demand here, though copper price volatility compresses margin stability for suppliers serving price-sensitive manufacturers.
- Air Horns:Pneumatic compressors driving diaphragm horns deliver 120+ dB outputs through compressed air reservoirs. Displacement-seeking cruiser and touring riders in North America and Europe drive aftermarket premiums, with digital channels disintermediating traditional distributors for these configurations.
- Mechanical Horns:Spring-actuated diaphragm systems without electrical dependency serve vintage restoration segments and regulatory backup requirements.
- Dual Tone Horns:Integrated dual-frequency housings satisfy UNECE R28 pedestrian-alert provisions without discrete hardware additions.
Electric horns handle the majority of throughput; dual tone configurations are expanding most quickly on share.
Installation Type:
Mounting location determines acoustic projection geometry and regulatory compliance testing protocols across jurisdictions.
- Handlebar Mount:Compact electromagnetic units clamping to handlebar tubes dominate commuter and standard motorcycle OEM specifications. Indian manufacturers in Pune and Chennai clusters specify these for AIS-014 certification efficiency, with integrated wiring harnesses reducing assembly labor.
- Front Mount:Fork-mounted or fairing-integrated housings optimize forward acoustic projection for pedestrian-alert regulations. European touring models increasingly specify these to satisfy UNECE R28 multi-angle sound-pressure requirements without handlebar clutter.
- Universal Mount:Adjustable bracket systems accommodate aftermarket retrofit across multiple motorcycle architectures.
- Custom Fit:Bespoke fabrication for cruiser fairings and touring pannier integrations commands premium labor charges.
Handlebar mount configurations anchor volume procurement; front mount designs are climbing the fastest as pedestrian-alert regulations tighten.
Power Source:
Electrical architecture choices reflect the tension between standardized 12-volt economies and emerging efficiency mandates.
- Battery Powered:Self-contained lithium or alkaline units serve auxiliary and emergency backup applications where motorcycle electrical systems are inaccessible.
- Direct Current:12-volt DC platforms align with standardized motorcycle electrical systems across Indian, Japanese, and European manufacturers. Cost-optimized DC horn production concentrates in Indian supply chains serving domestic OEM scaling and export markets.
- Alternating Current:AC-compatible designs serve specialized electric motorcycle architectures with inverted powertrains.
- Solar Powered:Photovoltaic-integrated housings address ultra-low-power auxiliary signaling for off-grid touring applications.
Direct current platforms capture the dominant procurement share; solar powered variants show steepest expansion trajectory among niche adventure segments.
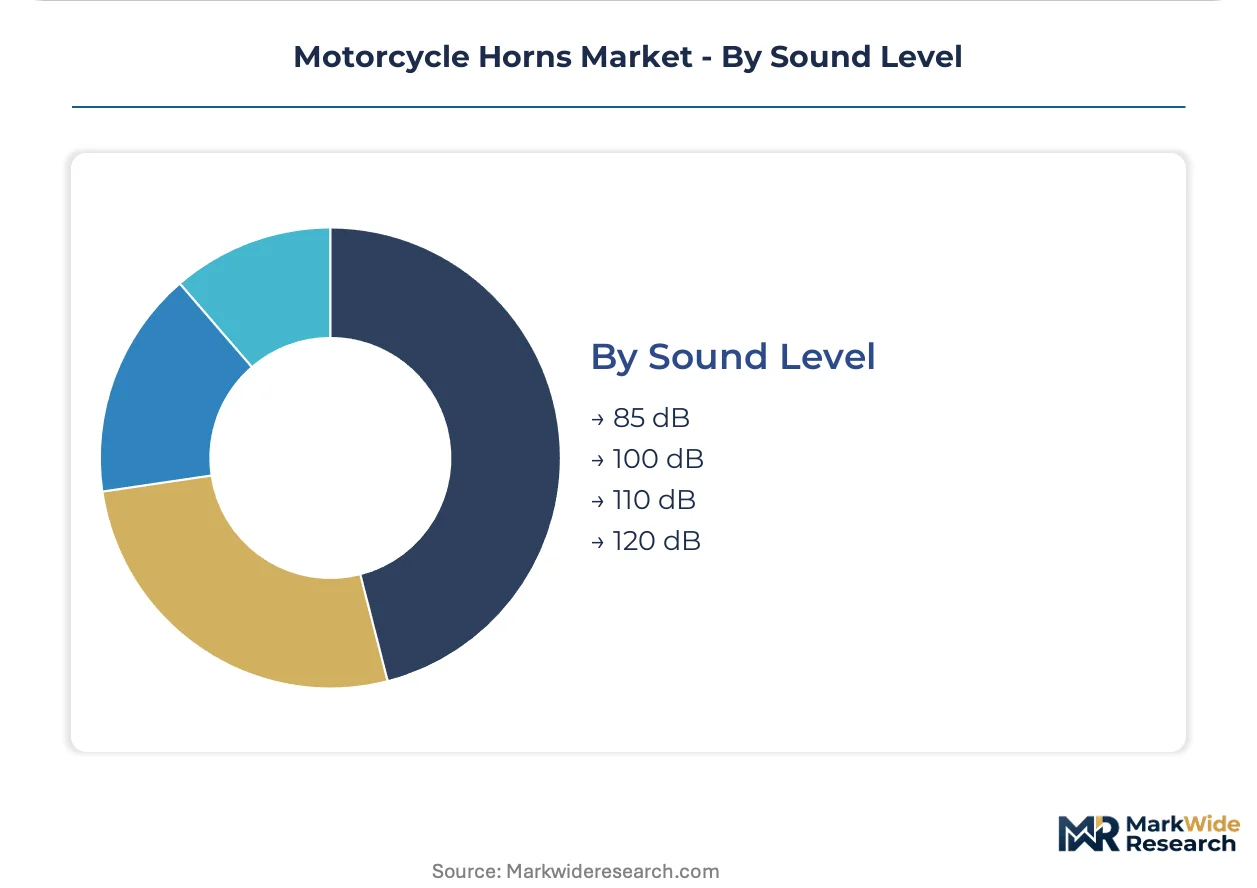
Sound Level:
Decibel tiering maps directly to regulatory minimums, with marginal increments commanding disproportionate pricing premiums.
- 85 dB:Baseline outputs meeting minimum UNECE R28 and FMVSS 571.141 thresholds for urban commuter motorcycles. These configurations face pricing pressure from regulatory floor effects where certification compliance is the sole differentiator.
- 100 dB:Mid-tier outputs satisfying Indian AIS-014 requirements with margin headroom for dual-tone integration. Domestic Indian OEMs specify these for standard models, with BIS-aligned testing facilities in Chennai and Pune validating production batches.
- 110 dB:Elevated outputs targeting highway visibility and touring safety margins.
- 120 dB:Maximum-pressure configurations for heavy cruiser and emergency vehicle applications.
100 dB specifications manage the highest throughput volumes; 110 dB tiers are gaining share fastest as highway safety awareness intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OEM procurement contracts concentrate in manufacturing clusters where motorcycle assembly scales fastest, while aftermarket customization premiums flow toward rider populations with displacement-seeking preferences.
India
Domestic motorcycle production scaling and tightening safety mandates drive horn demand toward integrated component suppliers. BIS-aligned AIS-014 certification requirements disqualify non-compliant vendors from OEM procurement lists. Pune and Chennai manufacturing clusters consolidate award volumes toward tier-one suppliers with captive acoustic validation facilities.
China
Export-oriented motorcycle assembly and domestic electric two-wheeler expansion create dual demand channels for DC horn platforms. MIIT-administered GB standards and UNECE R28 alignment requirements shape product roadmaps for European-bound shipments. Zhejiang and Guangdong supplier networks concentrate cost-optimized electromagnetic production for Southeast Asian and African export markets.
Germany
Premium motorcycle manufacturing and aftermarket accessory distribution anchor demand for precision-engineered acoustic systems. KBA-enforced UNECE R28 type-approval frameworks mandate multi-angle sound-pressure testing for pedestrian-alert compliance. Baden-Württemberg automotive supplier corridors host electromagnetic coil engineering specialists serving BMW and KTM assembly lines.
United States
Cruiser and touring rider populations seeking displacement-seeking acoustic signatures sustain aftermarket air horn premiums. NHTSA-administered FMVSS 571.141 safety standards establish minimum decibel thresholds for type-approval. Midwest and Southeast distribution hubs channel premium horn configurations through digital aftermarket platforms disintermediating traditional parts distributors.
Japan
Precision manufacturing heritage and keiretsu supplier relationships anchor OEM horn procurement for domestic and Southeast Asian motorcycle assembly. METI-coordinated JIS standards alignment ensures electromagnetic compatibility with standardized 12-volt electrical architectures. Chubu and Kansai industrial corridors concentrate diaphragm and voice coil fabrication for integrated supply to Honda and Yamaha production networks.
Motorcycle Horns Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement relationships. OEM bundling contracts concentrate volume awards toward integrated automotive component houses with captive testing infrastructure, while aftermarket specialists capture margin premiums through displacement-seeking configurations. Three archetypes dominate: automotive-tier suppliers leveraging sensor heritage, electromagnetic engineering specialists, and cost-optimized DC platform fabricators. Competitive moves center on vertical integration into acoustic validation capabilities and geographic expansion toward Indian and Southeast Asian manufacturing clusters.
Among Germany-based automotive-tier suppliers, Robert Bosch GmbH and HELLA GmbH & Co. KGaA exemplify channel-control strategies anchored in precision engineering heritage and regulatory compliance capabilities. Uno Minda Ltd. occupies a position within the cost-optimized tier, representing Indian supply chain concentration toward BIS-aligned certification efficiency. These three entities illustrate the structural divide between premium electromagnetic engineering and volume DC platform production.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| HELLA GmbH & Co. KGaA |
| Uno Minda Ltd. |
| Mitsuba Corporation |
| FIAMM Components |
| Zhejiang Shengke Auto Parts Co., Ltd. |
| Wolo Manufacturing Corp. |
| Custom Dynamics |
| HornBlasters |
| Others |
Pricing and Supply Chain Analysis
Copper voice coil volatility determines both the spread between electromagnetic and piezoelectric horn tiers and the geographic clustering of cost-optimized supply chains toward Indian and Chinese manufacturing basins. This commodity exposure compresses margin stability for legacy producers while accelerating transducer migration strategies among tier-one suppliers.
Pricing Analysis
Cost-plus contracts with copper LME indexation dominate OEM procurement relationships for electromagnetic horn platforms serving Indian and Southeast Asian motorcycle manufacturers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with AIS-014-certified configurations commanding modest premiums over self-certified alternatives. Pricing pressure stems from raw material cost swings compressing margin headroom for copper-dependent electromagnetic producers. Aftermarket air horn segments exhibit lowest price sensitivity among displacement-seeking cruiser riders, while commuter OEM specifications face intense cost compression from bundled procurement economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard procurement instruments for Indian tier-one suppliers serving domestic OEM scaling. Manufacturing concentrates in India, China, and Germany, with electromagnetic coil fabrication anchored in Baden-Württemberg automotive corridors and cost-optimized DC platform assembly clustering in Pune and Chennai. Raw material dependencies center on copper windings, steel diaphragms, and ABS housings. Single-source vulnerability concentrates in precision electromagnetic coil engineering capabilities held by limited European and East Asian specialists. Distribution runs through OEM bundling contracts for volume segments and digital aftermarket channels for premium cruiser configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Piezoelectric transducer migration represents a high-growth disruption as electromagnetic-to-ceramic actuator substitution rewrites acoustic output architectures and procurement specifications across motorcycle horn manufacturing.
For Market Incumbents: Pre-empt transducer substitution by accelerating backward integration into piezoelectric ceramic actuator fabrication capabilities before patent positions solidify. Consolidate acoustic validation infrastructure through captive testing facility investments in Indian manufacturing clusters to defend OEM bundling relationships against emerging component houses. Electromagnetic heritage players face displacement from ceramic actuator specialists unless they secure transducer technology licensing or acquisition pathways. For New Entrants and Emerging Players: Build out white-space positions in solar-powered auxiliary horn configurations for adventure touring segments where electrical system independence commands premium positioning. Target Indian aftermarket channels for cost-optimized DC platforms certified to BIS-aligned specifications as domestic production scaling creates captive demand. Digital-native go-to-market approaches disintermediate traditional parts distributors for premium air horn sales to cruiser and touring rider populations. For Investors and Strategic Acquirers: AIS-014 certification mandates reshape the acquisition landscape toward integrated component houses with captive acoustic validation capabilities in Pune and Chennai manufacturing clusters. Long-term viability favors suppliers with demonstrated regulatory compliance infrastructure across multiple jurisdictions rather than pure-play cost optimizers. Monitor laboratory queue congestion at Indian BIS-aligned testing facilities as an inflection indicator for certification-driven procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piezoelectric Actuator Fabrication | Ceramic transducer sourcing secures supply chain control against copper volatility and electromagnetic patent erosion. |
| Captive Acoustic Validation Facility Investment | In-house testing capabilities at Pune and Chennai clusters accelerate AIS-014 certification timelines for OEM procurement. |
| Dual-Resonance Chamber Product Launch | Integrated dual-frequency housings satisfy UNECE R28 pedestrian-alert provisions without discrete hardware additions. |
| Digital Aftermarket Channel Expansion | E-commerce platforms disintermediate traditional distributors for premium air horn sales to cruiser and touring segments. |
| Long-term OEM Bundling Contract Renewal | Volume commitments with Indian motorcycle manufacturers lock in cost-optimized DC platform demand amid production scaling. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with motorcycle OEM procurement managers, tier-one horn supplier engineering directors, aftermarket distributor category buyers, and acoustic testing laboratory technical leads. Secondary validation drew from BIS certification registries, UNECE R28 type-approval documentation, MIIT GB standard filings, customs trade data for electromagnetic component flows, and SEC disclosures from listed automotive component houses. Bottom-up unit shipment estimates triangulated against top-down motorcycle production forecasts across the analysis window.
Calibration against historical volume trajectories and regulatory implementation timelines anchored the projection framework. Segmentation modeling spanned product type, installation configuration, power source architecture, and sound level tier across regional production clusters. CAGRs were derived from regression analysis of motorcycle assembly growth, regulatory mandate adoption curves, and transducer technology substitution elasticities. Industry-specific forecast inputs included copper price volatility indices and AIS-014 certification queue data from Indian testing facilities.
Stress conditions across copper commodity swings, regulatory timeline slippage, and transducer technology adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding motorcycle production scaling and regulatory enforcement intensity. Macroeconomic contraction, trade policy disruption, or breakthrough solid-state transducer commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
India Two Wheeler Market
Bikes and Motorcycles
Motorcycle Boot Market
Bikes and Motorcycles
Motorcycle Drivetrain Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Global Carbon Fiber Bike Market
Bikes and Motorcycles
United States E-Bike Market
Bikes and Motorcycles
Shock Absorber Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Motorcycle Transmission Control Unit Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
Mountain Bike Suspension Market