
 Global Automotive HUD Market | 2026-2036
Global Automotive HUD Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive HUD Market Analysis
Aftermarket service revenue is rewriting value capture across the automotive HUD ecosystem. Continental AG leverages its integrated sensor-display software stack to sustain long-term service contracts with European OEMs. Bosch anchors its position through captive production of LCoS projection modules, while Visteon Corporation competes aggressively in the North American electric vehicle channel with open-architecture cockpit platforms.
An automotive head-up display projects critical driving information onto a transparent surface within the driver's forward field of view, typically employing waveguide optics or curved combiner mirrors with focal distances exceeding two meters to minimize accommodation shift. Windshield HUD configurations dominate current OEM fitment due to larger virtual image sizes, though laser-based technologies are gaining ground as automakers pursue augmented reality overlays with infinite focal depth. Passenger vehicles occupy the primary end-user segment, while safety alert features command premium pricing across luxury and mass-market trims alike.
The EU General Safety Regulation, NHTSA FMVSS guidelines, and Japan's JIS standards collectively shape product certification requirements and display luminance thresholds for automotive HUD systems. China's MIIT enforces GB standards for in-vehicle optical equipment that foreign suppliers must satisfy for market access. Stakeholders must monitor divergence between regional photometric standards and AR-HUD field-of-view specifications as next-generation platforms enter homologation cycles.
Market Dynamics
The convergence of augmented reality interfaces with EU General Safety Regulation mandates is compressing HUD development cycles. OEMs now specify field-of-view requirements exceeding 10 degrees horizontal before platform freeze dates.
Growth Catalysts
- EU General Safety Regulation:Mandates for advanced driver assistance visualizations compel European OEMs to standardize HUD fitment across vehicle classes.
- Waveguide optics:Thinner optical stacks enable dashboard integration in compact vehicle segments previously excluded from HUD availability.
- Germany-Japan engineering clusters:Proximity between Tier 1 R&D centers and automotive headquarters accelerates prototype-to-production timelines.
Market Restraints
- Indium tin oxide volatility:Transparent conductor pricing swings compress margins on windshield-integrated combiner elements.
- Single-source LCoS module supply:Captive production by dominant Japanese optical houses creates allocation risk during demand spikes.
- Accommodation-vergence conflict:Physiological limits on virtual image focal depth constrain AR-HUD information density.
Strategic Opportunities
- India:Underpenetrated luxury segment and rising ADAS content per vehicle create first-mover positioning for premium HUD suppliers.
- Commercial vehicle AR overlay:Route guidance and hazard projection for long-haul trucking fleets remains unserved by current passenger-optimized platforms.
- GB standards alignment:China's MIIT certification pathway for foreign optical equipment opens domestic OEM supply chains to compliant module vendors.
Industry Challenges
- Optomechanical engineering scarcity:Talent pools for freeform mirror design and holographic waveguide simulation remain concentrated in German and Japanese research institutes.
- Homologation timeline compression:Divergent photometric testing protocols across NHTSA, ECE R48, and JIS D 5507 extend certification cycles.
- Legacy CAN bus integration:Real-time AR rendering demands bandwidth exceeding the architecture of vehicles designed before 2020.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive HUD Market |
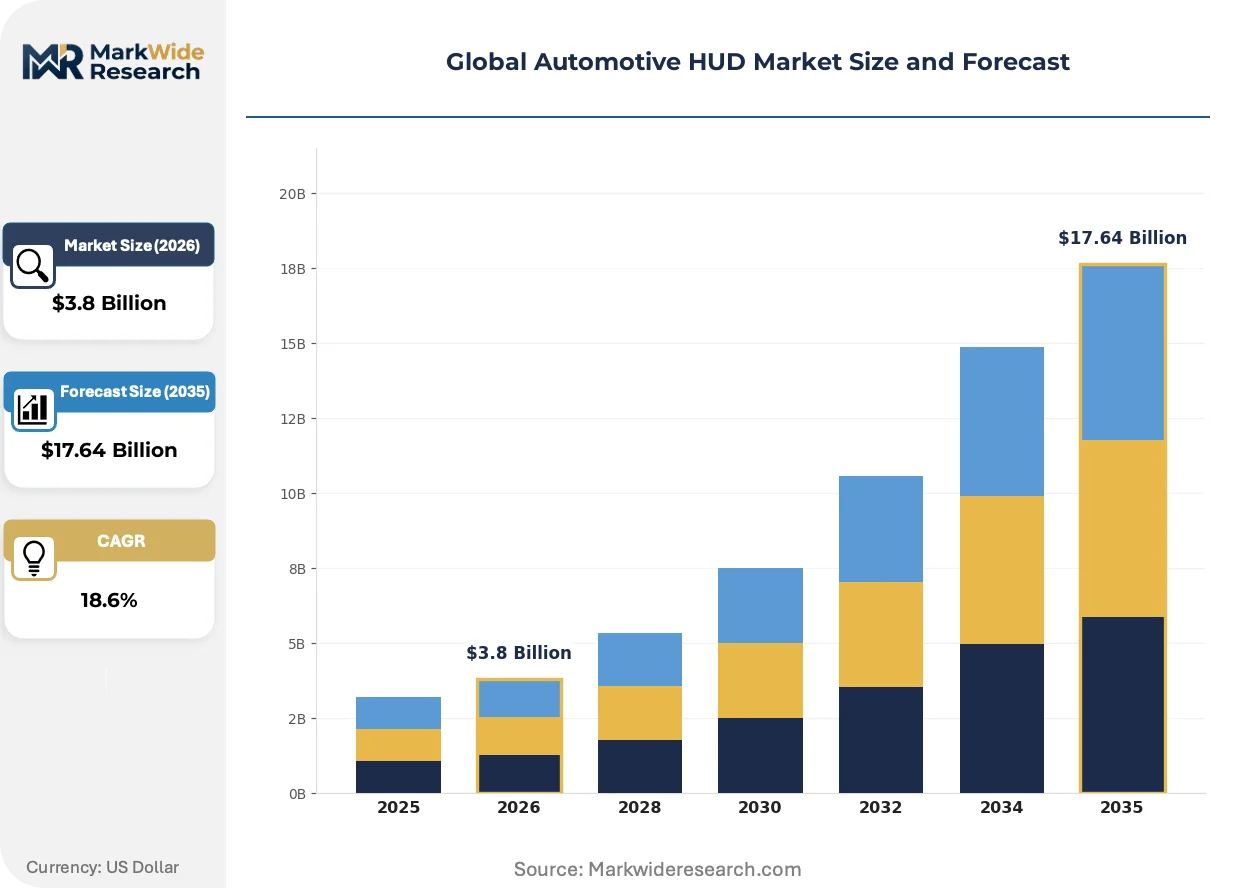
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windshield HUD, Combiner HUD, Full Glass HUD, Embedded HUD Technology: LCoS, DLP, Laser, OLED End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Cars Feature: Navigation, Speed Monitoring, Lane Assistance, Safety Alerts |
| Companies Covered | Continental AG, Denso Corporation, Nippon Seiki, Bosch, Yazaki Corporation, Panasonic Holdings Corporation, Visteon Corporation, Hyundai Mobis, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive HUD Market Emerging Trajectories
Software-defined display architectures are unbundling hardware from content pipelines. Tier 1 suppliers now compete on rendering stack performance rather than optical component specifications alone.
Digital light processing is digitizing the transition from static combiner mirrors to programmable pixel arrays. European luxury OEMs are adopting DLP-based systems for 2026 model year vehicles. This digitization collapses the distinction between instrument cluster and head-up display content domains.
REACH restrictions on halogenated flame retardants are forcing redesigns of HUD housing materials. Suppliers must qualify alternative thermally conductive polymers for LED heat sink applications. German OEMs have accelerated supplier audits to ensure compliance ahead of 2025 enforcement deadlines.
Fleet procurement departments now specify HUD content customization as a service requirement. Leasing companies demand over-the-air update capabilities for rental vehicle displays. This behavioral shift is most pronounced in North American corporate fleet channels where vehicle utilization rates drive technology amortization calculations.
Global Automotive HUD Market Segmentation
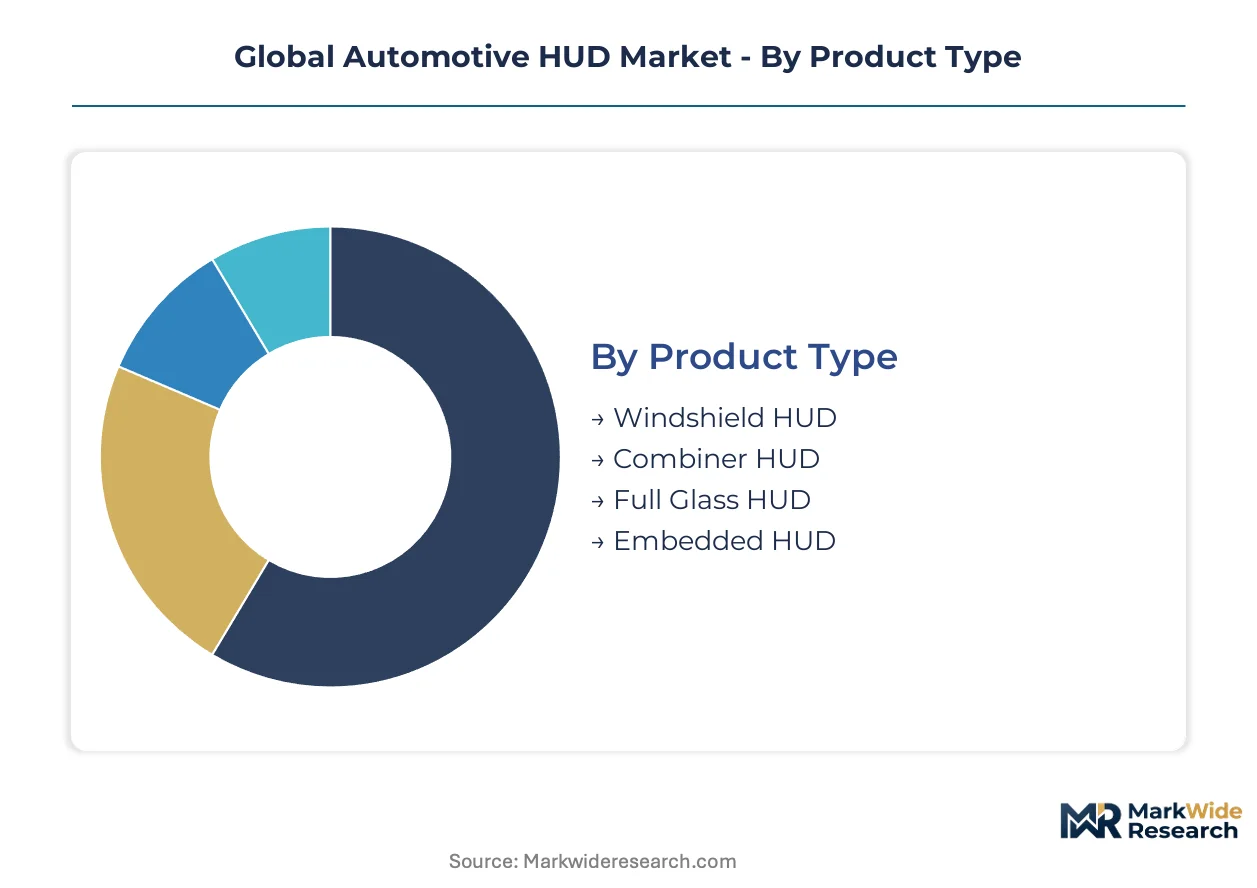
Automotive HUD segmentation reveals divergent technology maturities across optical architectures and vehicle classes. Product type configurations determine integration depth, while technology choices lock in focal depth capabilities and manufacturing cost structures.
Product Type:
Mature windshield configurations dominate OEM fitment, while embedded architectures represent the emerging frontier for cockpit integration.
- Windshield HUD:Projects virtual images through laminated glass with focal distances exceeding two meters, minimizing driver accommodation shift. German luxury OEMs in Stuttgart and Munich specify these for flagship sedans, constrained by indium tin oxide coating costs on combiner elements.
- Combiner HUD:Employs discrete curved mirrors mounted on the instrument panel, offering simpler retrofit pathways for compact vehicles. Japanese OEMs in Toyota City and Hiroshima deploy these in mass-market hybrids where windshield redesign cycles extend platform timelines.
- Full Glass HUD:Integrates projection across entire windshield surfaces for immersive AR overlays.
- Embedded HUD:Conceals optical stacks within dashboard structures, emerging in electric vehicle platforms from California-based manufacturers.
Windshield HUD retains volume leadership; embedded HUD holds the steepest expansion curve.
Technology:
Cost tiers separate captive LCoS production from outsourced DLP sourcing, with laser architectures commanding premium positioning.
- LCoS:Liquid crystal on silicon delivers high pixel density through reflective modulation, dominated by Japanese optical houses with captive wafer fabrication. Bosch secures allocation priority through backward integration into LCOS backplane manufacturing.
- DLP:Texas Instruments' digital micromirror devices enable programmable pixel arrays with faster refresh rates. European luxury OEMs specify DLP for 2026 model year vehicles requiring real-time AR rendering.
- Laser:Scanning laser projection achieves infinite focal depth for true augmented reality integration.
- OLED:Direct-emission microdisplays suit compact combiner applications with severe space constraints.
LCoS maintains installed base dominance; laser projection is climbing the fastest as AR-HUD specifications harden.
End User:
Application intensity varies sharply across vehicle electrification status and trim positioning.
- Passenger Vehicles:Mass-market fitment accelerates as EU General Safety Regulation mandates ADAS visualization. Continental AG supplies integrated sensor-display stacks to Volkswagen Group and BMW for standardized deployment across A-segment through D-segment platforms.
- Electric Vehicles:Native electrical architectures accommodate higher-bandwidth AR rendering without legacy CAN bus constraints. Visteon Corporation captures North American EV channel share through open-architecture cockpit platforms.
- Commercial Vehicles:Long-haul trucking fleets in the United States demand route guidance overlays unserved by passenger-optimized designs.
- Luxury Cars:Premium pricing tolerates waveguide optics and larger field-of-view specifications.
Passenger vehicles anchor current volume; electric vehicles are gaining share fastest as platform architectures refresh.
Feature:
Customer type stratification separates mandated safety content from discretionary navigation services.
- Safety Alerts:Collision warnings and pedestrian detection overlays command regulatory-driven fitment. NHTSA FMVSS guidelines and EU General Safety Regulation collectively mandate luminance thresholds and response latency standards.
- Navigation:Turn-by-turn projection competes with smartphone mirroring for driver attention. German OEMs bundle these in connected service subscriptions to sustain recurring revenue.
- Speed Monitoring:Digital speedometer replacement offers minimal differentiation.
- Lane Assistance:Lane departure graphics integrate with camera fusion systems for semi-autonomous operation.
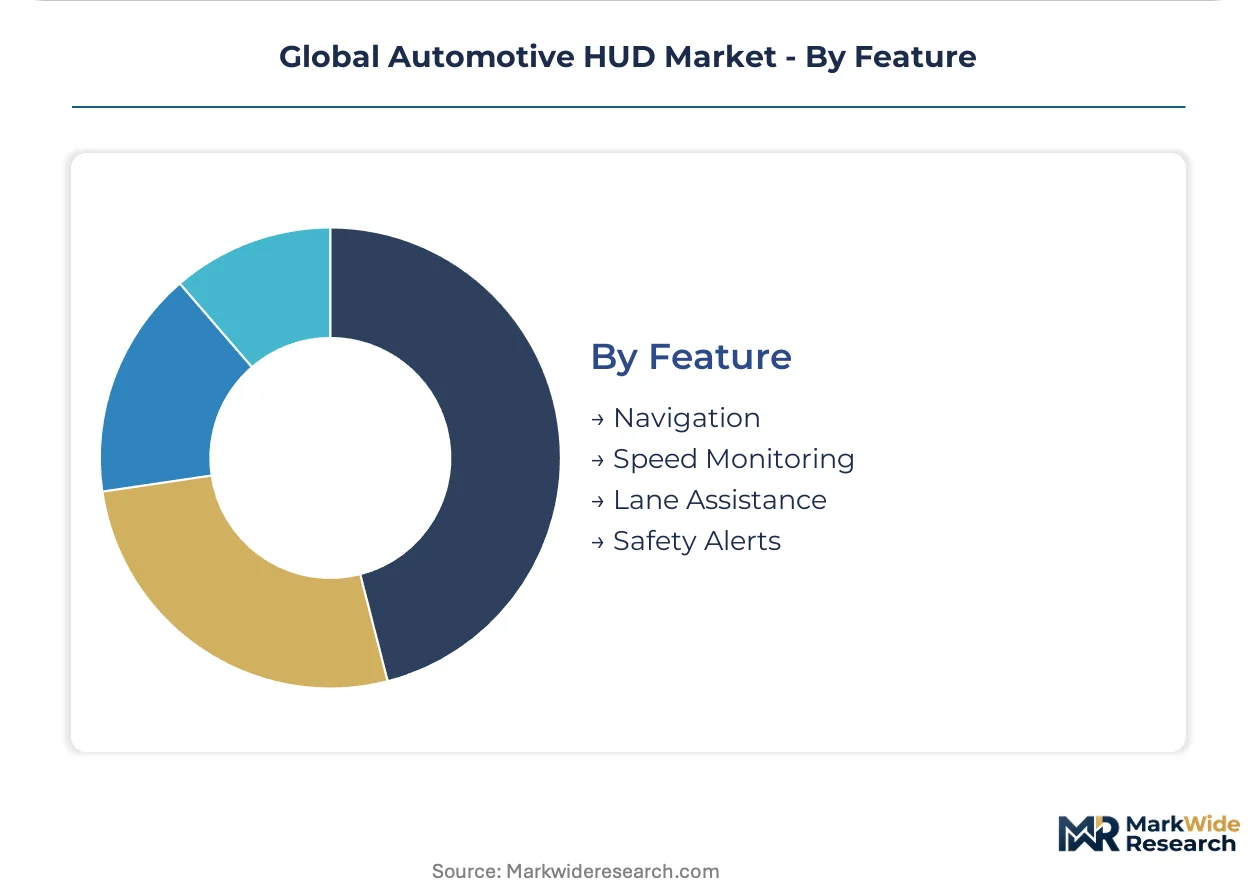
Safety alerts drive baseline adoption; navigation features sustain the steepest expansion trajectory as software-defined architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. German luxury buyers absorb waveguide premiums without volume contraction, while Indian mass-market procurement teams negotiate combiner HUD costs aggressively.
Germany
Stuttgart and Munich OEMs specify field-of-view requirements exceeding 10 degrees horizontal for 2026 platforms. EU General Safety Regulation mandates compel standardized HUD fitment across A-segment through D-segment vehicles. Continental AG maintains engineering co-location with Volkswagen Group and BMW headquarters in Bavaria and Baden-Württemberg.
United States
Corporate fleet channels in Michigan and California drive over-the-air update requirements for rental vehicle displays. NHTSA FMVSS guidelines shape luminance thresholds and response latency standards for safety alert features. Visteon Corporation anchors open-architecture cockpit development in Southeast Michigan for North American electric vehicle platforms.
Japan
Toyota City and Hiroshima deploy combiner HUD configurations in mass-market hybrids where windshield redesign cycles extend platform timelines. METI and JIS D 5507 standards govern photometric testing protocols for domestic homologation. Nippon Seiki and Denso Corporation concentrate LCoS module production in Nagoya engineering clusters with captive wafer fabrication.
China
MIIT enforces GB standards for in-vehicle optical equipment that foreign suppliers must satisfy for domestic OEM supply chain access. Dual carbon goals accelerate electric vehicle platform refreshes that accommodate higher-bandwidth AR rendering. Yangtze River Delta manufacturing bases host module assembly for European and Japanese Tier 1 vendors seeking local content compliance.
India
Underpenetrated luxury segments in Maharashtra and Karnataka create first-mover positioning for premium HUD suppliers as ADAS content per vehicle rises. BIS certification requirements for automotive electronics constrain import timelines for optical modules. Tamil Nadu automotive corridors attract German and Japanese Tier 1 engineering support centers for prototype-to-production acceleration.
Global Automotive HUD Market Vendor Landscape
Capability concentration sits with optical specialists commanding LCoS backplane fabrication and holographic waveguide simulation; scale advantage sits with diversified automotive electronics conglomerates with captive sensor-display integration. The vendor base separates into three strategic archetypes: integrated sensor-display stack providers, captive projection module fabricators, and open-architecture cockpit platform specialists. M&A activity targets waveguide optics startups in German and Japanese research institutes. Strategic partnerships between Tier 1 suppliers and semiconductor foundries secure allocation priority during demand spikes.
Among German diversified automotive suppliers, Continental AG and Bosch occupy positions exemplifying integrated stack and captive module archetypes respectively. Visteon Corporation represents the open-architecture platform specialist model in North American electric vehicle channels. Denso Corporation anchors the Japanese optical house cluster with backward integration into LCoS manufacturing.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| Nippon Seiki |
| Bosch |
| Yazaki Corporation |
| Panasonic Holdings Corporation |
| Visteon Corporation |
| Hyundai Mobis |
| Valeo |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor's container cost dynamics compress margins for indium tin oxide-coated windshield combiners while amplifying price differentiation between captive LCoS module producers and outsourced DLP suppliers. German OEM procurement teams leverage engineering co-location to negotiate waveguide premiums, whereas Indian mass-market buyers drive combiner HUD costs downward through aggressive volume consolidation.
Pricing Analysis
After-market service revenue tiers anchored by long-term sensor-display software contracts drive lifetime value capture for integrated stack providers. Three-tier pricing structure across premium waveguide, standard LCoS, and economy combiner levels stratifies by field-of-view specification and certification grade. Cost compression in economy tiers intensifies because transparent conductor pricing volatility erodes margins on windshield-integrated elements. Mass-market hybrid platforms in Japan exhibit highest price sensitivity; Stuttgart luxury segments absorb AR-HUD premiums without volume contraction.
Supply Chain Analysis
Contract manufacturing concentration at Taiwanese semiconductor foundries and Japanese optical houses with captive wafer fabrication holds capacity for LCoS backplane production. Geographic supply concentration centers on Germany, Japan, and China for optical module assembly and waveguide substrate processing. Raw material dependencies draw from indium tin oxide coatings, liquid crystal substrates, and halogen-free thermally conductive polymers. Single-source vulnerability in Japanese LCoS module allocation creates allocation risk during demand spikes. Distribution runs through Tier 1 engineering co-location clusters adjacent to OEM headquarters in Bavaria, Nagoya, and Michigan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through EU General Safety Regulation mandates creates switching costs that lock OEMs into validated supplier relationships.
For Market Incumbents: Harden platform standardization agreements with Volkswagen Group and BMW to block emerging DLP specialists from AR-HUD specification cycles. Deepen backward integration into LCOS backplane manufacturing to secure allocation priority during wafer fabrication constraints. Denso Corporation's captive Nagoya production demonstrates how upstream control over optical components neutralizes substitute technology threats from laser scanning architectures. For New Entrants and Emerging Players: Commercial vehicle AR overlay applications for long-haul trucking fleets in the United States represent the most penetrable entry point unserved by passenger-optimized platforms. India's underpenetrated luxury corridors in Maharashtra and Karnataka offer second-mover positioning as ADAS content per vehicle accelerates. A software-defined rendering stack go-to-market angle bypasses captive LCoS supply constraints that entrench Japanese optical houses. For Investors and Strategic Acquirers: EU General Safety Regulation enforcement timelines reshape the acquisition landscape toward suppliers with validated ECE R48 homologation pathways. Long-term viability over the projection horizon favors waveguide optics specialists with holographic simulation capabilities concentrated in German research institutes. Target acquisition archetype: mid-cap embedded HUD developers with dashboard integration IP for electric vehicle platforms. Monitor NHTSA FMVSS guideline revisions as the signal indicating AR-HUD mandate expansion beyond European jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Continental AG's integrated sensor-display stack locks Volkswagen Group into multi-vehicle-class deployment. |
| Backward Integration | Bosch's captive LCOS backplane manufacturing neutralizes allocation risk from Japanese optical house concentration. |
| Software-Defined Vehicle Investment | Visteon Corporation's open-architecture cockpit platforms capture North American electric vehicle channel share. |
| Geographic Manufacturing Footprint | Yangtze River Delta module assembly secures MIIT GB standards compliance for domestic OEM supply chain access. |
| Regulatory Certification Pathway | REACH-compliant thermally conductive polymer qualification ahead of 2025 enforcement deadlines defends European market position. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier procurement documentation anchors the qualitative findings. Primary interviews with HUD system architects, optical module procurement leads, windshield manufacturing engineers, and automotive regulatory affairs specialists combined with secondary validation from ECE R48 filings, JIS D 5507 test protocols, MIIT GB standard publications, and vehicle production databases. Bottom-up bill-of-materials analysis and top-down OEM fitment rate triangulation establish volume estimates.
Calibration against historical adoption curves for ADAS visualization technologies informs the analytical framework across the analysis window. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from fitted diffusion curves adjusted for regulatory mandate acceleration. Industry-specific forecast inputs incorporate EU General Safety Regulation phase-in schedules and electric vehicle platform refresh cadence.
Stress conditions across indium tin oxide price volatility, LCoS wafer allocation constraints, and homologation timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and OEM platform freeze schedules. Quarterly review of ECE R48 amendment proposals and NHTSA FMVSS docket activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Off-Highway Actuators Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Automotive Differential Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Automotive Bushing Market
Automotive Components
Automotive Brake Tube Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
Automotive Filters Market
Automotive Components
Global Automotive Chrome Accessories Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
Automotive Tailgate Market