
 B2C Mobility Sharing Market | 2026-2036
B2C Mobility Sharing Market Size, Share, and Industry Trends Forecast 2026-2036
B2C Mobility Sharing Market Outlook
Subscription-based fleet access is realigning how consumers contract mobility, converting sporadic ride purchases into recurring revenue relationships. Uber Technologies Inc. leverages its global driver network to sustain premium subscription tiers across multiple continents. ANI Technologies Pvt. Ltd. (Ola) anchors its position through deep backward integration into electric vehicle financing and charging infrastructure. Grab Holdings Inc. differentiates by embedding financial services within its mobility super-app, locking in Southeast Asian user retention.
B2C Mobility Sharing denotes platforms that allocate privately owned or fleet-managed vehicles to individual consumers through digital intermediation, typically orchestrated via GPS-tracked, smartphone-unlocked assets with real-time availability algorithms. The primary commercial purpose centers on monetizing underutilized vehicle capacity while reducing consumer capital expenditure on personal automobile ownership. Ride-hailing retains the largest revenue pool across service types, though scooter sharing demonstrates the steepest adoption curve in last-mile urban corridors. AI integration within technology stacks commands disproportionate R&D investment as platforms optimize dispatch algorithms and dynamic pricing engines.
The US Department of Transportation coordinates with the EPA to impose fleet emissions standards that directly shape vehicle procurement decisions by platform operators. China's MIIT enforces GB standards for connected vehicle data security, creating compliance barriers for foreign platform entrants. The EU AI Act imposes algorithmic transparency requirements on automated dispatch systems that will reshape how European operators train and deploy matching engines. Stakeholders must monitor regulatory divergence between data-localization mandates and cross-border platform interoperability standards to calibrate geographic expansion sequencing.
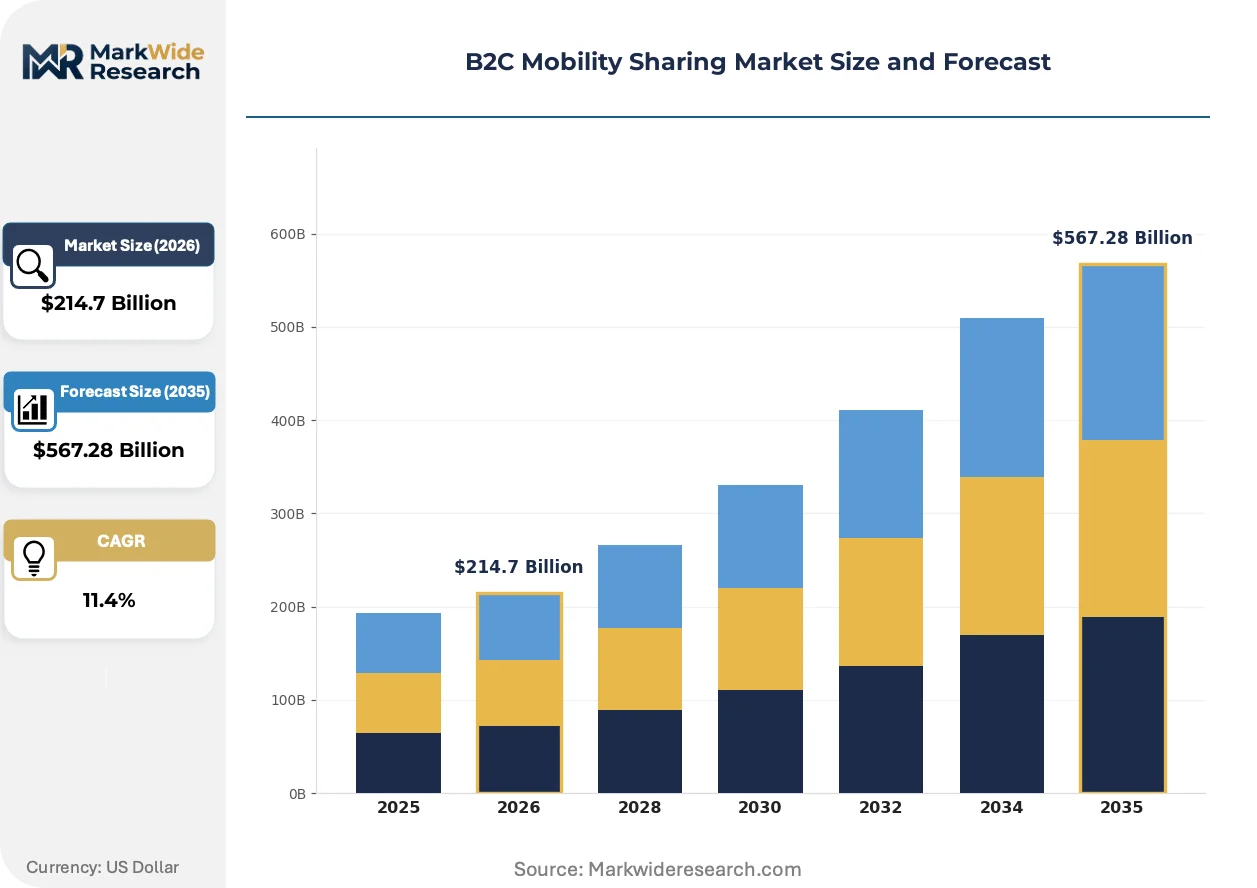
Market Dynamics
Fleet electrification mandates under the EU Green Deal are compressing vehicle procurement cycles while China's super-app integration locks users into consolidated mobility ecosystems, fundamentally restructuring how platforms monetize trip data and retain subscribers.
Growth Catalysts
- GB Standards Compliance:China's MIIT enforcement of connected vehicle data security protocols creates domestic competitive moats that insulate local platforms from foreign entrants while standardizing interoperability requirements.
- Last-Mile Density:Urban planners in Amsterdam and Copenhagen are redesigning street infrastructure to prioritize micromobility lanes, directly expanding addressable trip volumes for scooter and bike-sharing operators.
- Dynamic Pricing Engines:AI-powered demand forecasting algorithms now adjust per-minute rates in real-time based on weather patterns, event calendars, and transit disruptions, extracting higher revenue per asset-hour.
Market Restraints
- Lithium Supply Concentration:Battery cell production clusters in Chile and the Democratic Republic of Congo expose fleet electrification timelines to geopolitical extraction bottlenecks and export quota volatility.
- EU AI Act Algorithmic Transparency:Automated dispatch systems must now document training data provenance and decision logic, increasing compliance costs for European operators deploying machine-learning matching engines.
- Personal Vehicle Ownership Persistence:Suburban and exurban trip patterns outside Shanghai, London, and Los Angeles remain structurally resistant to shared mobility substitution due to low-density land use.
Strategic Opportunities
- India's Tier-Two Expansion:Cities including Pune, Ahmedabad, and Kochi exhibit rising smartphone penetration and congested central business districts without mature shared mobility saturation, presenting first-mover terrain.
- Vehicle-to-Grid Integration:Bidirectional charging infrastructure allows idle electric fleet assets to sell stored capacity back to utilities during peak demand windows, creating ancillary revenue streams.
- Embedded Financial Services:Mobility super-apps in Indonesia and Vietnam are layering micro-lending, insurance, and payment wallets atop trip booking, deepening user switching costs and data monetization.
Industry Challenges
- Certification Timeline Compression:Type-approval processes for connected and autonomous vehicle fleets under Germany's KBA and Japan's MLIT are extending from months to years as software-defined vehicle updates trigger re-homologation requirements.
- Charging Infrastructure Siting:Urban real estate scarcity in Paris, Seoul, and São Paulo forces operators into costly negotiations with commercial property owners for depot and fast-charging access.
- Data Localization Fragmentation:Divergent national requirements for trip data storage—Russia's Yarovaya Law versus Brazil's LGPD versus China's Cybersecurity Law—force platform architects into incompatible technical architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | B2C Mobility Sharing Market |
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $567.28 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Car Sharing, Bike Sharing, Scooter Sharing, Ride-Hailing Customer Type: Students, Professionals, Tourists, Families Technology: Mobile Apps, Web Platforms, IoT Solutions, AI Integration Pricing Model: Pay-As-You-Go, Subscription-Based, Flat Rate, Tiered Pricing |
| Companies Covered | Uber Technologies Inc., ANI Technologies Pvt. Ltd. (Ola), Lyft Inc., Grab Holdings Inc., Beijing Xiaoju Technology Co Ltd. (Didi Chuxing), Careem Networks LLC, Bolt Technology OÜ, Cabify SA, Europcar Group SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
B2C Mobility Sharing Market Strategic Shifts
Edge computing architectures are migrating dispatch decision-making from centralized cloud servers to vehicle-mounted processors, slashing latency for real-time matching while complicating software update distribution logistics across dispersed fleets.
Computer vision systems for automated damage detection are converging with smartphone-based unlock verification, eliminating manual inspection bottlenecks at trip start and end. European operators in Berlin and Milan are piloting these fused technologies to compress vehicle turnaround times from fifteen minutes to under ninety seconds. The structural compression of labor overhead is converging with the elimination of depot-based inspection infrastructure, enabling asset-light fleet management models.
The EU AI Act's algorithmic transparency requirements are forcing operators to maintain auditable logs of dispatch decisions, training data sources, and pricing adjustments. This industrial consequence is elevating compliance costs for automated matching systems while creating competitive differentiation for platforms that architect explainable AI from inception. Ride-hailing segments in France and the Netherlands are responding by segregating European data processing from global operations to limit regulatory exposure.
Subscription bundling is displacing per-trip purchasing as the dominant consumer contracting mechanism, with urban commuters in Singapore and Stockholm committing to monthly mobility budgets rather than evaluating each ride independently. Corporate benefit programs and insurance partnerships are replacing direct-to-consumer marketing as the primary customer acquisition channel. This pattern is most visible in Nordic markets where employer-subsidized mobility allowances now cover over forty percent of platform revenue.
B2C Mobility Sharing Market Segmentation
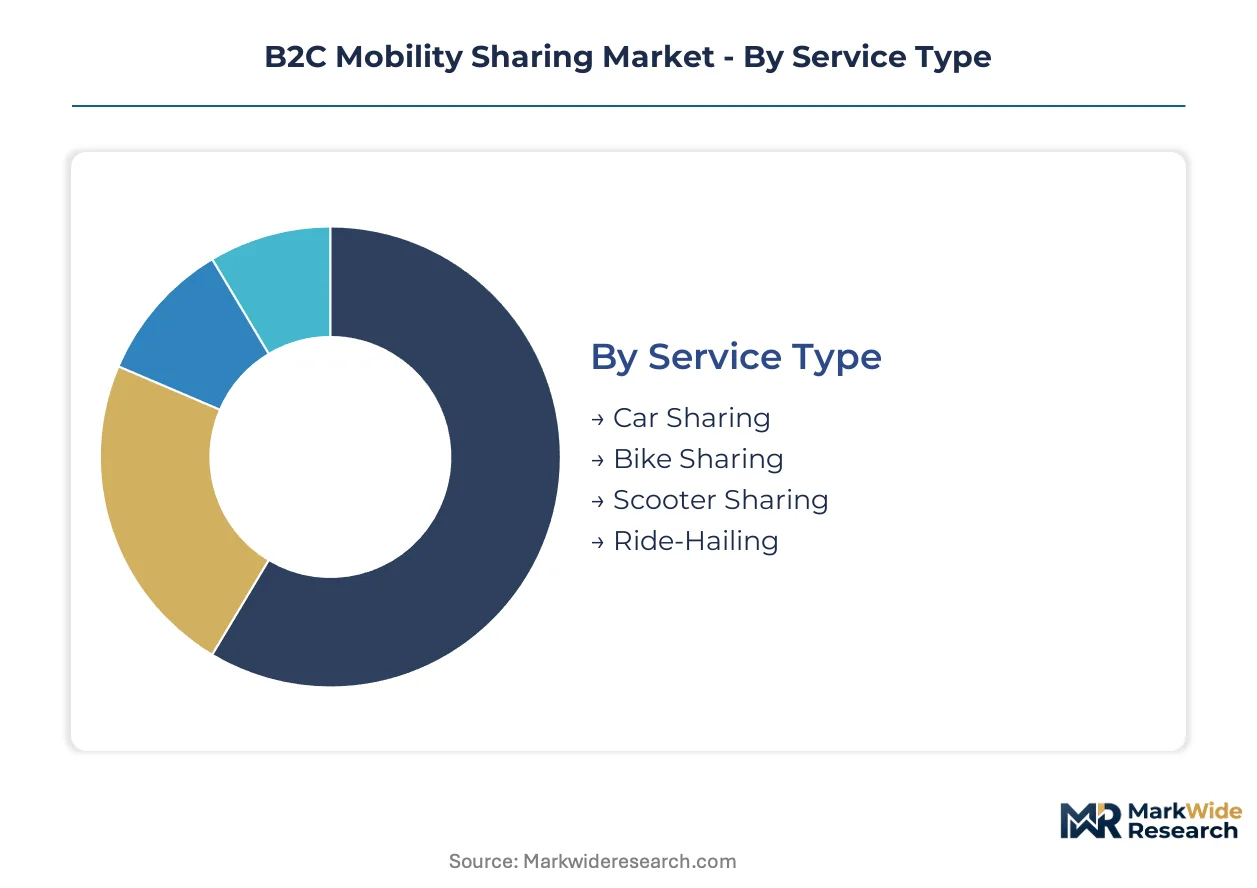
B2C Mobility Sharing platforms segment demand across four intersecting dimensions that determine asset deployment, technology stack investment, and customer lifetime value. Service type and pricing model choices fundamentally reshape unit economics, while customer type and technology selections dictate geographic prioritization and R&D allocation.
Service Type:
Urban density and trip distance preferences drive platform selection between asset-light and asset-heavy service models.
- Ride-Hailing:Platforms dispatch driver-operated vehicles through smartphone-mediated matching algorithms. Demand concentrates in Shanghai, London, and Los Angeles metropolitan corridors where parking scarcity and congestion pricing suppress personal vehicle use.
- Scooter Sharing:Dockless electric scooters deploy via GPS-tracked, app-unlocked hardware for sub-five-kilometer trips. Amsterdam and Copenhagen infrastructure investments are accelerating last-mile adoption in European city centers.
- Car Sharing:Fleet-owned or peer-to-peer vehicles offer hourly access without ownership burdens. Station-based models persist in German urban cores while free-floating variants dominate Paris and Madrid.
- Bike Sharing:Pedal and electric-assisted bicycles serve short-distance commuting through docked or dockless systems. Chinese tier-one cities maintain the densest deployment networks globally.
Ride-Hailing leads on scale; Scooter Sharing leads on momentum.
Customer Type:
Occupation and life-stage variables determine trip frequency, price sensitivity, and platform loyalty patterns.
- Professionals:Commuters with employer-subsidized mobility allowances generate predictable recurring revenue. Nordic corporate benefit programs now cover substantial platform subscription volumes.
- Students:University-affiliated users exhibit high price elasticity and preference for micromobility options. Campus-dense cities including Boston and Berlin show concentrated demand for bike and scooter services.
- Tourists:Episodic users prioritize ease of access over loyalty programs, driving seasonal demand spikes in Barcelona, Rome, and Tokyo.
- Families:Multi-passenger trip requirements favor ride-hailing and car-sharing segments with child-seat options and larger vehicle classes.
Professionals anchor revenue stability; Students are expanding most quickly.
Technology:
Stack architecture choices determine matching latency, fraud prevention, and regulatory compliance capabilities.
- AI Integration:Machine-learning dispatch engines optimize driver-rider matching and dynamic pricing in real time. EU AI Act transparency mandates are forcing European operators to maintain auditable decision logs.
- Mobile Apps:Super-app architectures in Southeast Asia embed financial services alongside trip booking. Grab Holdings and Gojek leverage this to deepen user switching costs.
- IoT Solutions:Vehicle-mounted telematics enable remote unlock, battery monitoring, and geofenced parking enforcement. China's MIIT GB standards shape domestic hardware specifications.
- Web Platforms:Browser-based booking persists for corporate account management and accessibility compliance in regulated European markets.
AI Integration commands R&D concentration; Mobile Apps dominate user acquisition.
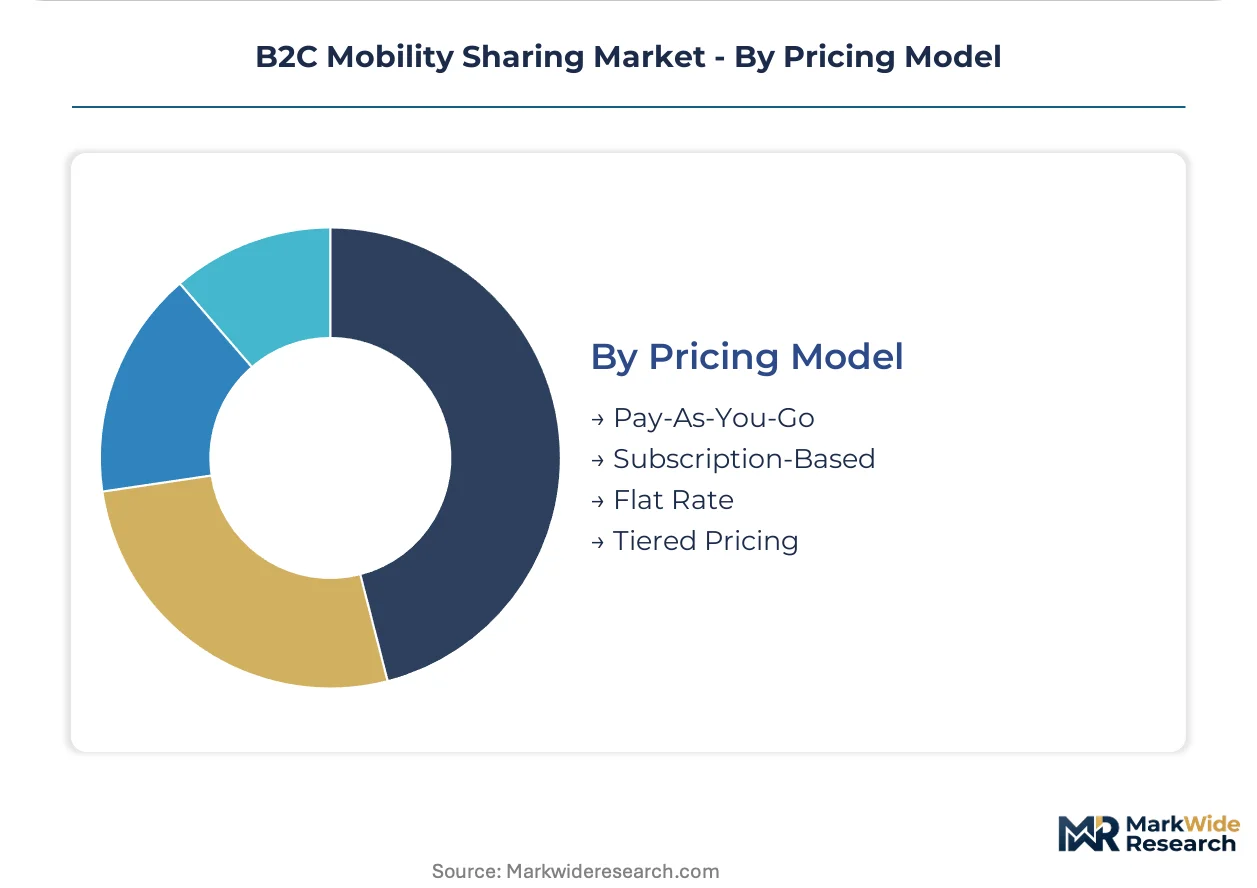
Pricing Model:
Contract structure selection converts transactional relationships into predictable revenue streams or maximizes asset utilization.
- Subscription-Based:Monthly or annual plans bundle trip allowances with priority matching and waived surge pricing. Stockholm and Singapore commuters increasingly commit to fixed mobility budgets.
- Pay-As-You-Go:Per-minute or per-mile billing aligns costs with actual usage for infrequent users. This model retains dominance in tourist-heavy markets with irregular demand patterns.
- Flat Rate:Unlimited-ride subscriptions within defined zones or time windows. Operators deploy this to defend market share against new entrants in contested urban markets.
- Tiered Pricing:Three-level structures separate premium vehicle classes, standard fleet access, and economy options with longer wait times. Uber and Lyft deploy this to capture willingness-to-pay variation.
Subscription-Based gains share fastest; Pay-As-You-Go retains volume leadership in tourist corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's super-app dominance contrasts sharply with Europe's regulatory fragmentation, while the United States sustains platform competition through venture-backed scaling and India's tier-two cities attract first-mover capital.
China
MIIT enforcement of GB standards for connected vehicle data security creates domestic competitive moats around fleet telematics. Beijing and Shanghai concentrate super-app integration where daily transport routines lock users into consolidated mobility ecosystems. The Yangtze River Delta corridor generates the densest deployment networks globally for bike-sharing infrastructure.
United States
Congestion pricing in Manhattan and parking scarcity across Los Angeles metropolitan corridors suppress personal vehicle dependency. The Department of Transportation coordinates with EPA to impose fleet emissions standards that reshape platform procurement decisions. Silicon Valley venture ecosystems sustain premium subscription tier development across multiple continents.
Germany
KBA type-approval processes for software-defined vehicle fleets extend certification timelines as over-the-air updates trigger re-homologation. Berlin and Munich anchor station-based car-sharing models while Amsterdam-style micromobility lanes expand in Hamburg. The EU Green Deal compresses electric vehicle procurement cycles for platform operators.
India
Pune, Ahmedabad, and Kochi exhibit rising smartphone penetration without mature shared mobility saturation. The central bank's digital payment infrastructure enables embedded financial services layering atop trip booking. ANI Technologies anchors position through backward integration into electric vehicle financing and charging infrastructure.
Singapore
Employer-subsidized mobility allowances now cover substantial platform subscription volumes among professional commuters. Land Transport Authority regulations enforce geofenced parking enforcement for dockless micromobility assets. The city-state's compact urban density maximizes asset utilization rates for scooter and bike-sharing operators.
B2C Mobility Sharing Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with asset-light platforms commanding valuation premiums over fleet-heavy operators. The vendor base organizes around three strategic archetypes: super-app integrators embedding financial services, subscription specialists converting transactional rides into recurring revenue, and infrastructure-backward platforms controlling charging and financing ecosystems. Competitive moves concentrate on strategic partnerships with automotive OEMs and geographic expansion into underpenetrated tier-two corridors.
Within the super-app tier, Grab Holdings Inc. and Beijing Xiaoju Technology Co Ltd. exemplify platform architectures that deepen user switching costs through consolidated service embedding. Uber Technologies Inc. occupies a position as the scale-driven archetype leveraging global driver network density. ANI Technologies Pvt. Ltd. anchors the infrastructure-control segment through captive supply of electric vehicle financing and charging assets.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| ANI Technologies Pvt. Ltd. (Ola) |
| Lyft Inc. |
| Grab Holdings Inc. |
| Beijing Xiaoju Technology Co Ltd. (Didi Chuxing) |
| Careem Networks LLC |
| Bolt Technology OÜ |
| Cabify SA |
| Europcar Group SA |
| Others |
Value Chain & Pricing Dynamics
Software engineering talent clusters in Bangalore and Shenzhen compress algorithm development costs for dynamic pricing engines, widening spreads between premium subscription tiers and pay-as-you-go baselines as platforms arbitrage labor-cost differentials across development centers.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for micromobility assets as scooter-sharing operators deploy denser fleets in Jakarta and Ho Chi Minh City. Three-tier pricing structure across premium, standard, and economy levels captures willingness-to-pay variation among corporate commuters versus students. Pricing pressure stems from battery cell cost volatility linked to Chilean lithium export quotas. Tourist segments exhibit highest price sensitivity; employer-subsidized professionals accept premium tier markups.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for electric vehicle fleets as Didi Chuxing and Ola negotiate direct procurement agreements with BYD and Tata Motors. Manufacturing concentrates in China, South Korea, and Germany for battery cells, electric drivetrains, and connected vehicle telematics. Component dependencies include lithium carbonate, rare earth magnets, and semiconductor-grade silicon. Single-source vulnerability runs through Congolese cobalt extraction. Distribution runs through platform-operated depots and third-party logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in B2C mobility sharing rests on fleet electrification cost curves and subscription-tier conversion, with AI-powered dispatch optimization compressing per-trip operating expenditures.
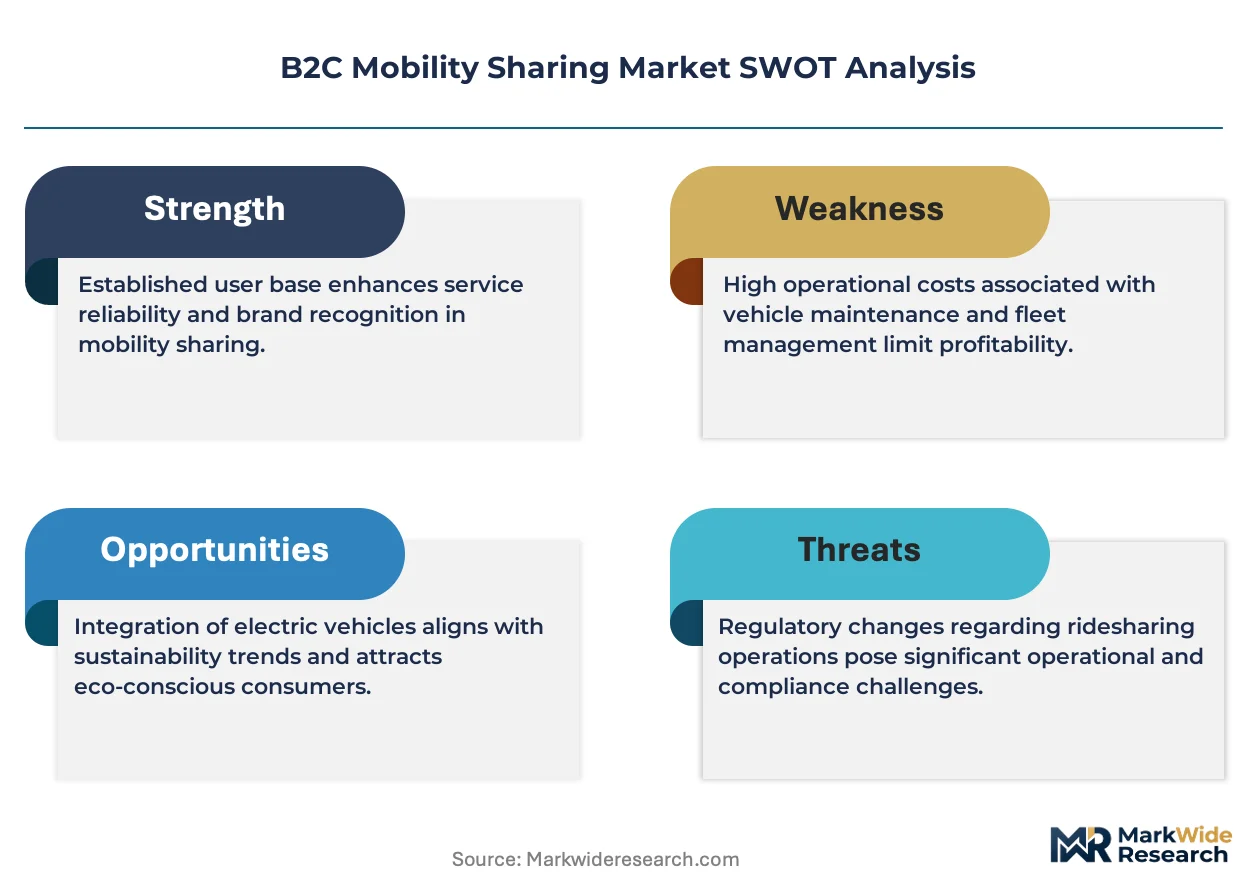
For Market Incumbents: Anticipate regulatory fragmentation as EU AI Act transparency mandates and China's GB standards diverge on algorithmic audit requirements. Consolidate position through backward integration into charging infrastructure in Amsterdam and Copenhagen micromobility corridors. Defend subscriber base by embedding financial services within super-app architectures to heighten switching costs against emerging platform entrants.
For New Entrants and Emerging Players: Launch via employer-subsidized corporate benefit programs in Nordic markets where forty percent of platform revenue already flows through human resources channels. Target India's tier-two cities including Pune and Ahmedabad where smartphone penetration rises without shared mobility saturation. Penetrate through white-label fleet management services for municipal bike-sharing contracts.
For Investors and Strategic Acquirers: Automotive OEMs are the most active acquirer in this space, seeking captive demand channels for electric vehicle output. Five-to-ten year viability hinges on platform differentiation between asset-light matching engines and infrastructure-heavy charging ecosystems. Monitor vehicle-to-grid revenue realization as the inflection signal for fleet-heavy operator valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Charging Infrastructure | Ola's captive financing and charging assets in India reduce supplier dependency and lock in fleet electrification timelines. |
| Super-App Financial Services Embedding | Grab Holdings layers micro-lending and insurance atop trip booking, deepening user retention across Southeast Asian markets. |
| AI Dispatch Engine Investment | Uber's machine-learning optimization extracts higher revenue per asset-hour through real-time demand forecasting. |
| Corporate Benefit Program Partnerships | Employer-subsidized mobility allowances in Stockholm and Singapore convert transactional riders into predictable recurring revenue. |
| Tier-Two Geographic Expansion | First-mover positioning in Pune and Kochi captures rising smartphone penetration before competitive saturation. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform operations executives, municipal transport planners, fleet procurement managers, and regulatory affairs specialists at EU and Chinese agencies with secondary validation against SEC filings, MIIT GB standard documentation, EU Green Deal implementation reports, and vehicle registration databases. Bottom-up fleet deployment counts and top-down mobility expenditure estimates were triangulated to anchor market sizing.
Historical reference periods established baseline penetration rates for subscription versus pay-as-you-go contracting across the analysis window. The projection framework modeled service type, customer segment, technology stack, and pricing model dimensions alongside regional regulatory cluster variations. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic mobility demand indicators, incorporating fleet electrification timelines and super-app adoption curves as mobility-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium supply disruption scenarios and algorithmic transparency compliance cost escalation. Outputs reflect documented assumptions on urban density thresholds and employer subsidy program expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Vehicle As a Service Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Contactless Ticketing Market
Smart Transportation Solutions
Mexico Ride Hailing Market
Smart Transportation Solutions
Automated Robotic Parking System Market
Smart Transportation Solutions
Global Smart Parking Market
Smart Transportation Solutions
Road Profile Laser Sensor Market
Smart Transportation Solutions
Global IoT Fleet Management Market
Smart Transportation Solutions
Automotive Digital Mapping Market
Smart Transportation Solutions
Smart Car Digital Key System Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Middle East and Africa Passenger Information System Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market