
 Australia Automotive Glass Fiber Composites Market | 2026-2036
Australia Automotive Glass Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Automotive Glass Fiber Composites Market Outlook
A skilled composites technician pool is bifurcating the Australia Automotive Glass Fiber Composites Market into regions with adequate trained labor and those facing recruitment bottlenecks. Owens Corning leverages its global glass fiber formulation expertise to supply consistent reinforcement grades across Australian OEM programs. Solvay Group specializes in high-performance resin systems that sustain structural integrity under Australian thermal cycling conditions. China Jushi Co. Ltd anchors cost-competitive E-glass supply into the Asia-Pacific region, competing aggressively on volume for commodity automotive applications.
Automotive glass fiber composites are fiber-reinforced polymer materials combining glass fibers with thermoset or thermoplastic matrices, typically achieving tensile strengths of 300-600 MPa while reducing component mass by 25-35% versus conventional steel. Their primary purpose centers on producing crash-resistant, aerodynamic vehicle body panels and structural members that improve fuel efficiency and extend electric vehicle range. Light Vehicles currently dominates application demand, though Electric Vehicles represents the fastest-expanding segment as battery weight penalties drive aggressive lightweighting targets. Among product types, structural panels for body-in-white applications command premium margins, while windshields remain a mature, specification-commoditized category.
TGA-administered Australian Design Rules and the Department of Infrastructure's vehicle safety standards shape composite material selection, crash-test validation protocols, and OEM homologation pathways. The National Transport Commission coordinates state-level enforcement, creating uniform compliance obligations across New South Wales, Queensland, and Western Australia. Stakeholders must monitor forthcoming revisions to pedestrian protection standards and battery enclosure fire-resistance criteria, as these will redefine glass fiber composite specifications for next-generation vehicle platforms.
Market Dynamics
Australian Design Rules administered by the Department of Infrastructure are tightening crashworthiness standards for composite-intensive vehicle architectures, forcing OEMs to recalibrate material specifications and validation protocols across their supply chains.
Growth Catalysts
- Electric vehicle lightweighting mandates:Battery weight penalties are accelerating structural panel adoption as manufacturers seek range extension through mass reduction.
- ADRs pedestrian protection revisions:Upcoming amendments to Australian Design Rules are mandating energy-absorbing front-end structures that favor glass fiber composite solutions.
- Victoria-South Australia supplier clustering:Concentrated EV assembly investments in these states are deepening localized composite component ecosystems and reducing logistics costs.
Market Restraints
- Petrochemical resin volatility:Epoxy and polyester feedstock price swings compress margin stability for Tier 2 molders serving Australian OEM programs.
- Asia-Pacific E-glass supply concentration:Import dependency on Chinese furnace capacity creates exposure to trade policy shifts and shipping rate spikes.
- Thermal cycling performance ceilings:Standard E-glass formulations face degradation thresholds under extreme Australian outback temperature differentials, limiting under-hood applications.
Strategic Opportunities
- Queensland manufacturing expansion:Underdeveloped composite infrastructure in this state offers first-mover positioning as EV production diversifies beyond Victoria.
- Recycled fiber integration:Emerging mechanical recycling streams for end-of-life wind turbine blades present secondary raw material feedstock for non-structural automotive panels.
- Automated fiber placement convergence:Robotics and thermoplastic tape laying are converging to enable high-volume, lower-cycle-time production previously uneconomical in Australian market scale.
Industry Challenges
- Certified composites technician scarcity:TAFE-level training program throughput lags OEM workforce demand, particularly for vacuum infusion and resin transfer molding specializations.
- Homologation timeline compression:Accelerated EV platform development cycles compress the 18-24 month ADR crash-test validation windows, straining engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Automotive Glass Fiber Composites Market |
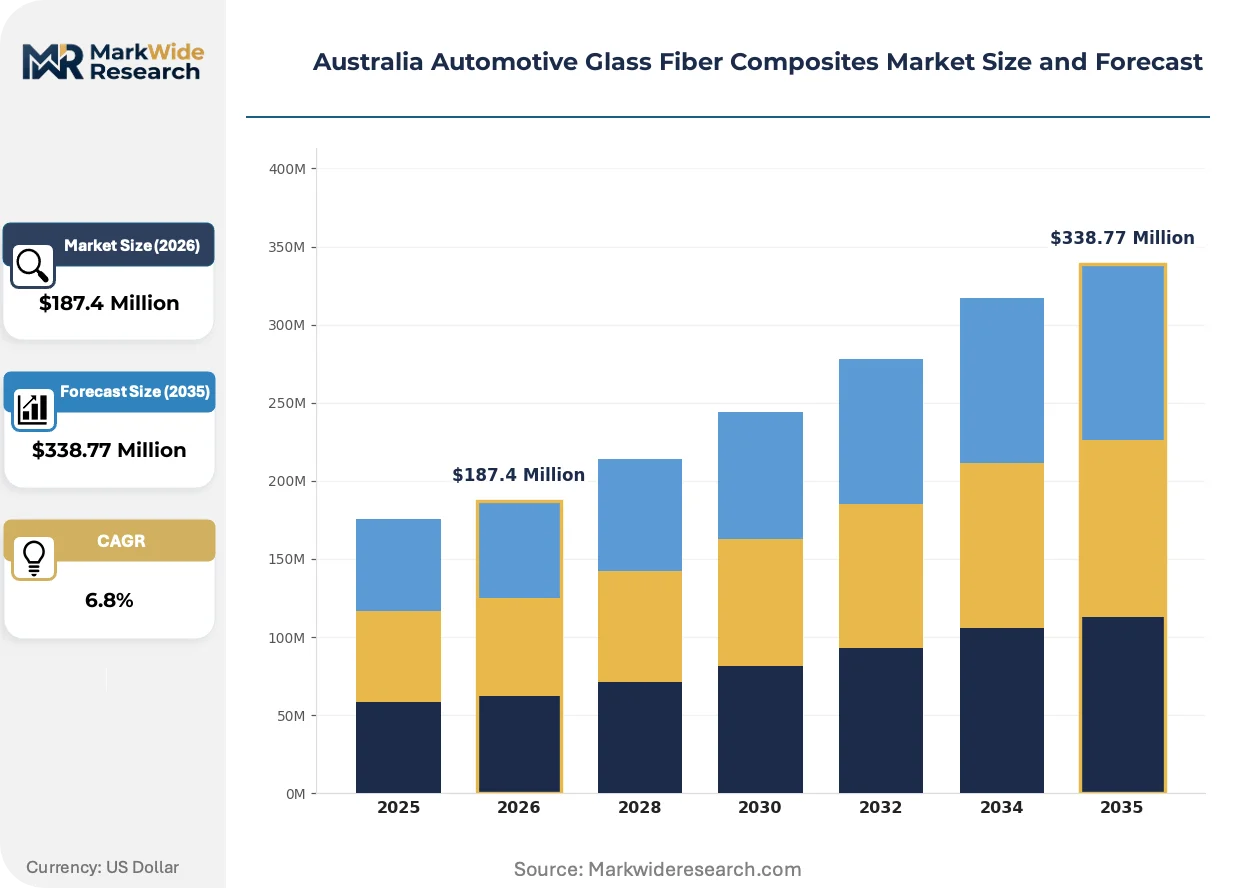
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windshields, Side Windows, Back Windows, Sunroofs Application: Light Vehicles, Heavy Duty Vehicles, Electric Vehicles, Luxury Cars Manufacturing Stage: Raw Material Preparation, Production, Quality Control, Final Assembly End User: OEMs, Aftermarket Suppliers, Repair Shops, Distributors |
| Companies Covered | Owens Corning, 3B (Braj Binani Group), Jiangsu Changhai Composite Materials, SAERTEX GmbH & Co. KG, Veplas Group, ASAHI FIBER GLASS Co Ltd, Solvay Group, China Jushi Co. Ltd, Nippon Sheet Glass Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Automotive Glass Fiber Composites Market Strategic Shifts
Material science advances and regulatory stringency are converging to reshape how Australian automotive manufacturers specify, validate, and source fiber-reinforced components across vehicle platforms.
Continuous fiber-reinforced thermoplastic (CFRTP) tapes are displacing traditional sheet molding compound in structural beam applications. Tier 1 suppliers to Australian EV programs are adopting these tapes for A-pillar and sill reinforcements at pilot scale. The shift is displacing incumbent thermoset processes by enabling sub-60-second cycle times and end-of-life recyclability that aligns with emerging state-level waste directives.
Revisions to Australian Design Rule 69 (occupant protection) and anticipated pedestrian impact standards are mandating multi-material front-end architectures. These regulations are compelling OEMs to redesign bumper beams and hood assemblies with engineered crush zones. Light vehicle platforms targeting five-star ANCAP ratings are most affected, with engineering teams expanding composite simulation capabilities to reduce physical prototype iterations.
Fleet operators and government procurement agencies are consolidating supplier relationships around vertically integrated composite component providers. Direct sourcing agreements are replacing traditional Tier 2-Tier 1-OEM chains for high-volume EV platforms. This concentration is most visible in Victoria, where state government electric bus procurement frameworks specify single-source accountability for body panel durability and crash performance.
Australia Automotive Glass Fiber Composites Market Segmentation
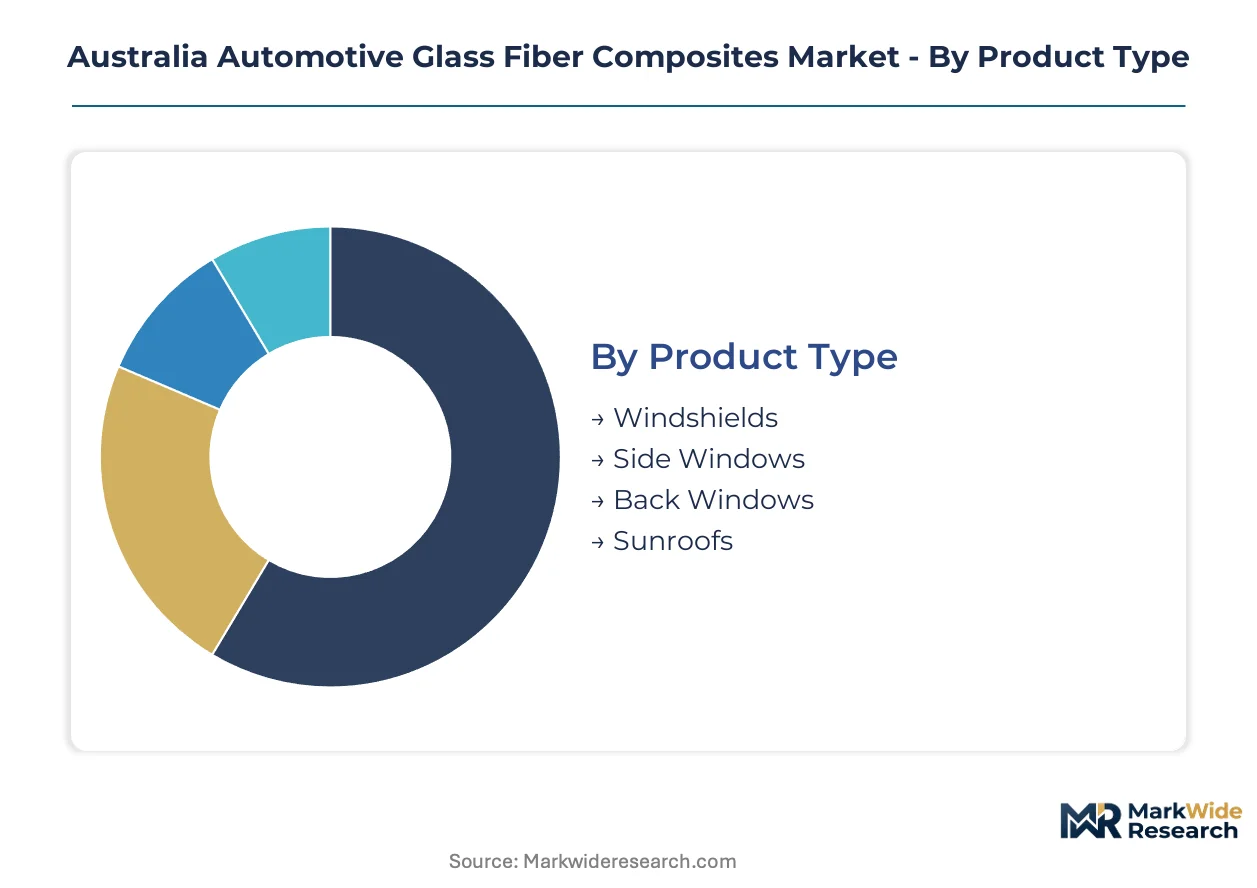
Glass fiber composites in Australian automotive applications fragment across four distinct taxonomies. Each dimension reveals divergent margin structures, regulatory exposure, and investment intensity that shape supplier strategy.
Product Type:
Premium margins concentrate in structural glazing where ADR crashworthiness certification commands specification lock-in.
- Windshields:Laminated safety glass with polyvinyl butyral interlayers dominates replacement volume. Victorian and South Australian assembly plants specify these for ANCAP five-star compliance, though import price volatility from Asia-Pacific float glass furnaces squeezes molder margins.
- Sunroofs:Panoramic and pop-up variants integrate glass fiber reinforced frames for torsional rigidity. Luxury EV platforms in Victoria specify these at rising rates as cabin differentiation intensifies, though thermal expansion mismatches between glass and composite frames create warranty exposure.
- Side Windows:Tempered glass with edge encapsulation for wind noise reduction.
- Back Windows:Heated defogger circuits with embedded antenna traces.
Windshields hold installed capacity. Sunroofs is rotating up the share rankings.
Application:
Volume concentration sits with mass-market platforms, yet value pools are migrating toward electrified architectures.
- Electric Vehicles:Battery enclosure side panels and structural floor pans absorb glass fiber composites at aggressive rates. South Australian OEM programs specify these for mass reduction that offsets lithium-ion pack weight, with TGA-administered battery fire-resistance standards dictating resin system selection.
- Light Vehicles:Conventional internal combustion platforms consume composites for bumper beams and hood assemblies. Queensland and Western Australia fleet operators drive replacement demand through high-kilometer commercial use patterns.
- Heavy Duty Vehicles:Cab structures and aerodynamic fairings for long-haul freight.
- Luxury Cars:Carbon-glass hybrid panels for weight-sensitive performance variants.
Light Vehicles maintains volume dominance. Electric Vehicles is climbing the fastest as platform launches accelerate.
Manufacturing Stage:
Process control intensity escalates downstream, with final assembly capturing quality-liability premiums.
- Production:Resin transfer molding and vacuum infusion of structural panels. Victorian Tier 1 suppliers operate these cells under ISO 9001 and IATF 16949 protocols, with cycle time optimization determining contract renewals.
- Quality Control:Non-destructive testing via ultrasonic and thermographic inspection. ADR homologation requires documented void content below threshold limits, creating specialized metrology service demand.
- Raw Material Preparation:E-glass roving chopping and resin catalyzation.
- Final Assembly:Bonded integration with metal body-in-white structures.
Production holds installed capacity. Quality Control is rotating up the share rankings.
End User:
Procurement authority concentrates with vehicle assemblers, though aftermarket channels offer working capital advantages.
- OEMs:Direct specification of composite components for new vehicle platforms. Australian Design Rules administered by the Department of Infrastructure mandate traceable supply chains, favoring Tier 1 suppliers with established homologation records.
- Aftermarket Suppliers:Crash replacement panels and upgrade accessories. Independent distributors in New South Wales and Queensland stock these for insurance-repair networks, with price sensitivity higher than OEM channels.
- Repair Shops:Localized bonding and refinishing services.
- Distributors:Wholesale inventory holding for fragmented regional demand.
OEMs holds installed capacity. Aftermarket Suppliers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TGA-administered Australian Design Rules administered by the Department of Infrastructure anchor national demand trajectories. State-level EV assembly investments and supplier clustering patterns concentrate composite consumption across five jurisdictions.
Victoria
Battery enclosure manufacturing for electric bus fleets drives structural panel demand. State government procurement frameworks mandate single-source accountability for body panel durability. Geelong and Melbourne host deepening Tier 1 supplier ecosystems serving OEM assembly plants.
South Australia
Passenger EV platform launches absorb glass fiber composites for floor pans and battery side panels. TGA battery fire-resistance standards dictate resin system selection for local OEM programs. Adelaide's automotive component cluster is expanding vacuum infusion capacity for structural applications.
New South Wales
Insurance-repair networks sustain aftermarket demand for crash replacement panels. The National Transport Commission coordinates uniform compliance obligations across state enforcement zones. Sydney distributors hold wholesale inventory for fragmented regional demand patterns.
Queensland
Underdeveloped composite infrastructure offers first-mover positioning as EV production diversifies beyond southeastern states. High-kilometer commercial fleet operators drive replacement demand through intensive use patterns. Brisbane suppliers are evaluating resin transfer molding investments for emerging OEM programs.
Western Australia
Mining fleet operators specify heavy-duty cab structures and aerodynamic fairings for long-haul freight applications. Extreme outback temperature differentials expose standard E-glass formulations to thermal cycling degradation thresholds. Perth-based distributors serve remote resource extraction corridors with extended logistics lead times.
Australia Automotive Glass Fiber Composites Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Owens Corning and Solvay Group anchor the upper tier through global formulation expertise and high-performance resin systems respectively. The middle tier comprises regional fabricators competing on volume and logistics proximity. Strategic moves concentrate on backward integration into raw material supply and geographic expansion into underpenetrated state markets.
Within the integrated materials tier, Owens Corning exemplifies global glass fiber formulation leadership, while Solvay Group represents high-performance resin specialization. China Jushi Co. Ltd anchors the cost-competitive volume segment. These three companies occupy distinct positioning vectors—formulation consistency, thermal performance, and scale economics—without direct overlap in customer targeting.
| Leading Market Players |
|---|
| Owens Corning |
| 3B (Braj Binani Group) |
| Jiangsu Changhai Composite Materials |
| SAERTEX GmbH & Co. KG |
| Veplas Group |
| ASAHI FIBER GLASS Co Ltd |
| Solvay Group |
| China Jushi Co. Ltd |
| Nippon Sheet Glass Company Limited |
| Others |
Value Chain & Pricing Dynamics
TGA-administered Australian Design Rules certification gates both supplier qualification and price differentiation simultaneously, with ADR homologation records commanding specification lock-in premiums while uncertified imports compete on spot pricing for aftermarket channels.
Pricing Analysis
Victorian Tier 1 suppliers command price spreads against Queensland distributors due to proximity to OEM assembly plants and embedded homologation costs. Pricing stratifies across ADR-certified structural panels, ISO-compliant commodity grades, and uncertified aftermarket alternatives, with certified tiers capturing margin premiums. Cost compression in commodity E-glass feedstock is intensifying because of Asia-Pacific furnace overcapacity. Aftermarket suppliers exhibit highest price sensitivity, while OEM procurement teams prioritize traceability over unit cost.
Supply Chain Analysis
Inventory buffers at Perth distributors stretch to eight weeks for remote mining fleet operators facing extreme outback logistics lead times. Raw material supply draws from Chinese E-glass furnace capacity, South Korean resin formulation plants, and domestic Victorian compounding facilities. Single-source vulnerability concentrates in China Jushi's Asia-Pacific volume position, exposing Australian molders to trade policy discontinuities. Distribution runs through Tier 1 direct contracts for OEM platforms and independent wholesalers for crash-replacement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's automotive glass fiber composites sector sits in early-cycle expansion, with electric vehicle platform launches driving penetration acceleration across structural applications.
For Market Incumbents: Fortify homologation records with TGA-administered Australian Design Rules to defend against emerging Chinese volume entrants seeking OEM qualification. Backward integration into resin catalyzation capacity in Geelong or Adelaide secures margin control against petrochemical feedstock volatility. Certification investment in battery enclosure fire-resistance testing represents the critical defensive lever as EV production scales. For New Entrants and Emerging Players: Differentiate on Queensland manufacturing expansion to capture first-mover positioning as EV assembly diversifies beyond Victoria-South Australia clustering. Target aftermarket crash-replacement panels in New South Wales insurance-repair networks as the most penetrable channel, leveraging working capital advantages over OEM direct contracts. Pursue recycled fiber integration from end-of-life wind turbine blades as a sustainability-led go-to-market angle for non-structural panel applications. For Investors and Strategic Acquirers: Australian Design Rule revisions for pedestrian protection and battery fire-resistance reshape the acquisition landscape toward vertically integrated composite component providers with established TGA validation records. Long-term viability centers on suppliers capable of spanning OEM specification and aftermarket distribution across the next decade. Acquisition targets should demonstrate vacuum infusion specialization and IATF 16949 certification. The signal to watch is accelerated EV platform homologation timelines compressing validation windows for uncertified entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captures margin stability against epoxy and polyester feedstock price swings at Victorian Tier 1 suppliers. |
| Queensland Manufacturing Footprint Expansion | Positions first-mover suppliers for EV production diversification beyond southeastern state clustering. |
| Recycled Fiber Feedstock Integration | Aligns with emerging state-level waste directives through mechanical recycling of end-of-life wind turbine blades. |
| Automated Fiber Placement Technology Adoption | Enables sub-60-second cycle times for CFRTP tapes displacing thermoset processes at Adelaide pilot facilities. |
| ADR Homologation Record Investment | Secures specification lock-in for structural glazing as TGA tightens crashworthiness standards for composite-intensive architectures. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of vehicle production databases, customs and trade data, IHS Markit registration records, and TGA-administered Australian Design Rule filings. Primary interviews engaged Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, TAFE training program administrators, and vacuum infusion cell operators. Bottom-up volume estimates from individual OEM program specifications triangulate against top-down market sizing from automotive component trade flows.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the projection horizon. CAGRs derive from weighted average of platform launch schedules, battery weight penalty trajectories, and ADR regulatory amendment timelines. Industry-specific forecast inputs include EV assembly capacity buildout in Victoria and South Australia, plus thermal cycling performance thresholds for outback operating conditions.
Forecasts assume regulatory continuity in TGA-administered Australian Design Rules and National Transport Commission coordination; material pedestrian protection standard revisions or battery enclosure fire-resistance criteria shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Automotive Carbon Fiber Components Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Automotive Mobile Accessories Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Global Automotive Bumpers Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
Automotive Backing Plate Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Automotive Tailgate Market
Automotive Components
North America Automotive Hydraulic Actuators Market
Automotive Components
Automotive Spark Plugs and Glow Plugs Market