
 EV Lightweight Materials Market | 2026-2036
EV Lightweight Materials Market Size, Share, and Industry Trends Forecast 2026-2036
EV Lightweight Materials Market Foresight
Automotive-grade carbon fiber specification upgrades is reorganizing procurement priorities across European and North American EV supply chains. Novelis Inc. leverages its closed-loop recycling infrastructure to secure primary aluminum supply contracts with Detroit-based OEMs. Toray Industries, Inc. anchors high-modulus carbon fiber output for premium electric sedan platforms in Japan and South Korea. Constellium SE specializes in advanced aluminum-lithium alloys that reduce body-in-white mass without sacrificing crash performance.
EV lightweight materials encompass engineered metals, polymers, and composites formulated to reduce vehicle curb weight while maintaining structural integrity, crashworthiness, and thermal management performance. Carbon fiber reinforced polymers achieve tensile strengths exceeding 3,500 MPa at densities below 1.6 g/cm³, enabling battery enclosure designs that offset cell mass with chassis savings. Aluminum dominates chassis and body panel applications due to mature stamping infrastructure and favorable cost-per-kilogram-saved ratios against steel. Composite formulations represent the fastest-expanding material type as thermoplastic resins enable sub-60-second cycle times for high-volume battery housing production.
The EPA tailpipe emission standards and NHTSA Corporate Average Fuel Economy rules in the United States, alongside the EU Green Deal's embedded carbon reporting requirements under CSRD, are mandating gram-per-kilometer reductions that cascade into material selection decisions. REACH compliance in Europe restricts certain epoxy resin hardeners, redirecting composite formulation R&D toward bio-based alternatives. Stakeholders must monitor how China's MIIT new-energy vehicle credit system and GB standards for recyclability reshape export qualification requirements for lightweight material suppliers serving multinational OEMs.
Market Dynamics
Europe's F-Gas Regulation and the EU Green Deal are tightening embodied carbon thresholds, forcing OEMs and Tier-1 suppliers to accelerate material substitutions across battery housing and body-in-white programs.
Growth Catalysts
- Battery Housing Demand:OEMs are specifying carbon fiber reinforced polymers and aluminum-lithium alloys to offset cell mass with chassis savings. This specification upgrade is pulling significant volume from Germany's automotive corridor.
- REACH Compliance Redirect:Restrictions on certain epoxy resin hardeners in Europe are redirecting composite formulation R&D toward bio-based alternatives, opening new supply channels for sustainable material suppliers.
- Closed-Loop Recycling Infrastructure:Novel aluminum recovery systems are securing primary supply contracts with Detroit-based OEMs, reducing virgin material dependency and stabilizing input costs.
Market Restraints
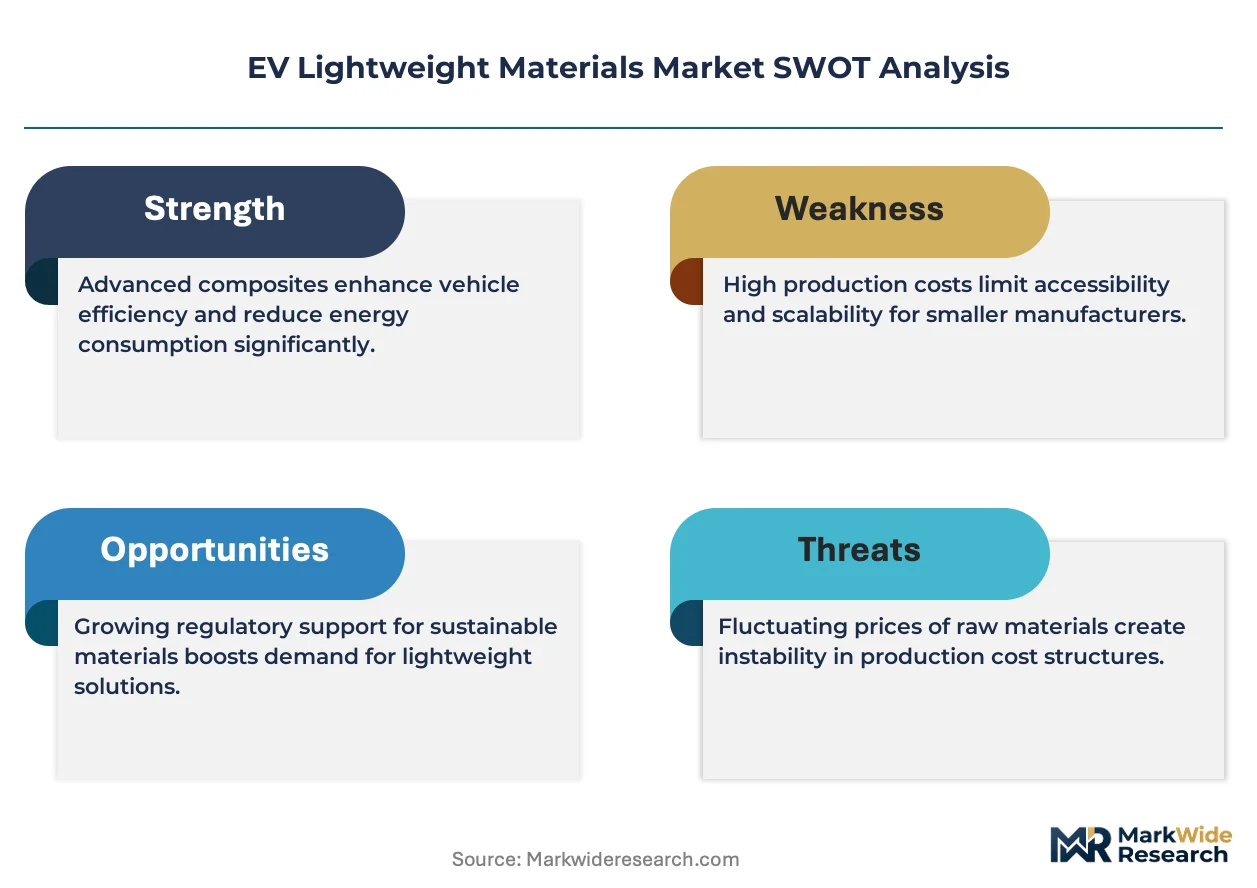
- Carbon Fiber Cost Structure:Aerospace-grade precursor availability constraints and energy-intensive oxidation cycles keep carbon fiber prices elevated versus aluminum extrusions.
- Aluminum Smelter Concentration:Primary aluminum supply concentrates in China's western provinces and the GCC, exposing European automakers to energy cost volatility and trade flow disruptions.
- Thermoset Recycling Limitation:Cross-linked polymer matrices in legacy composite battery enclosures resist mechanical or chemical recycling, complicating end-of-life compliance with EU battery regulations.
Strategic Opportunities
- Second-Life Battery Enclosures:Thermoplastic composite formulations enabling sub-60-second cycle times represent white space for high-volume production of reusable housing structures.
- India PLI Scheme Alignment:Component suppliers can qualify for production-linked incentives by localizing advanced aluminum-lithium alloy capacity for domestic EV platforms.
- CSRD Embedded Carbon Reporting:Material suppliers with verified lifecycle data capture competitive advantage as EU automakers face mandated gram-per-kilometer disclosure requirements.
Industry Challenges
- Multi-Material Joining Expertise:Bonding aluminum extrusions to carbon fiber panels requires specialized adhesive selection and surface preparation protocols that few Tier-1 suppliers have scaled.
- Crash Simulation Validation:Correlating finite element models with physical pole-impact tests for novel aluminum-lithium alloys extends OEM homologation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Lightweight Materials Market |
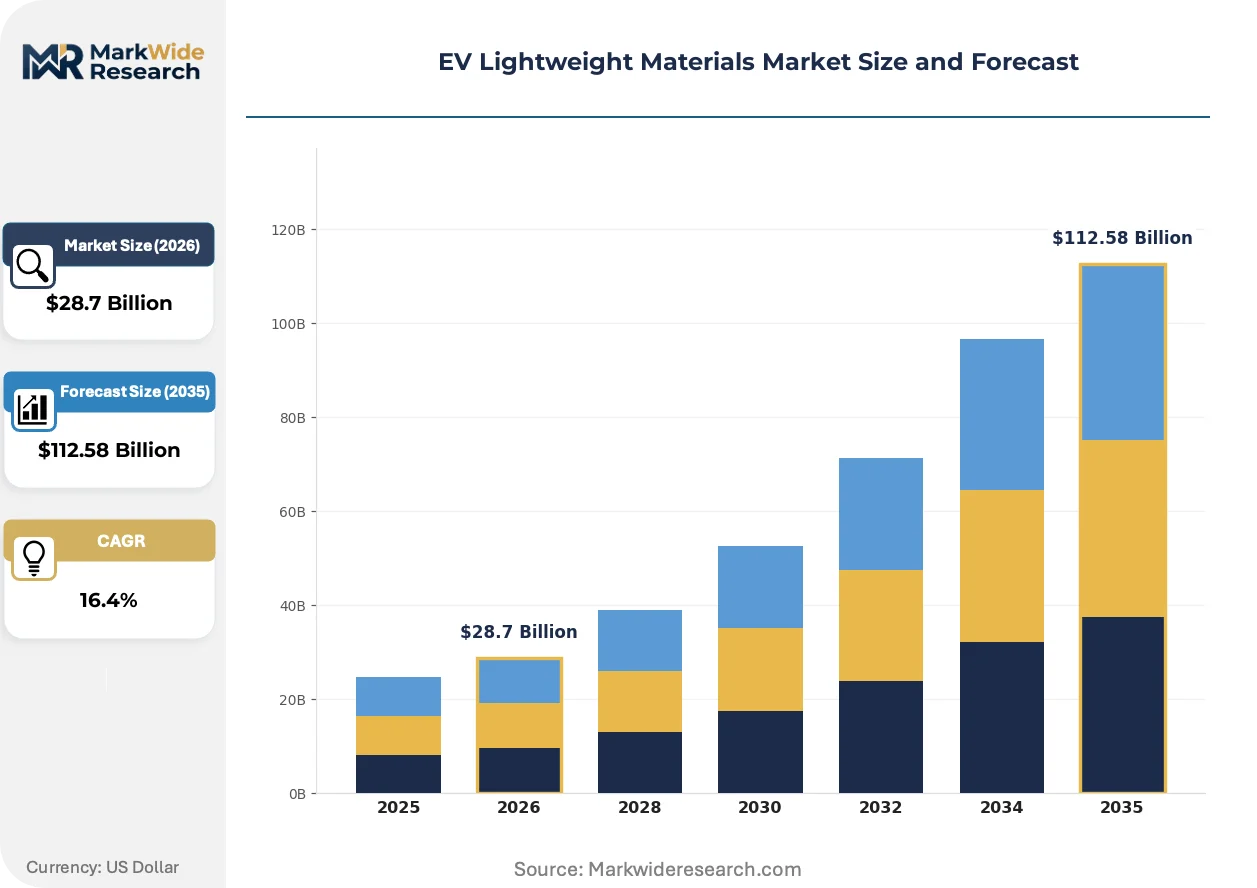
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $112.58 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Carbon Fiber, Magnesium, Composite Application: Chassis, Body Panels, Interior Components, Battery Housing End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Production Technique: Stamping, Molding, Extrusion, Laser Cutting |
| Companies Covered | Alcoa Corporation, Novelis Inc., Constellium SE, SGL Carbon SE, Toray Industries, Inc., BASF SE, ArcelorMittal, Covestro AG, Hexcel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Lightweight Materials Market Shifts & Advancements
Thermoplastic resin systems and high-pressure resin transfer molding are compressing cycle times for structural composite components, while regulatory pressure on embodied carbon is rewriting material qualification protocols across OEM engineering departments.
Carbon fiber reinforced thermoplastic tapes are decomposing the traditional thermoset-dominated supply chain for battery enclosure manufacturing. BMW and Mercedes-Benz engineering teams are qualifying these materials for 2026 platform launches. The technology is decomposing incumbent autoclave-based production by enabling automated fiber placement at automotive cycle times.
The EU Green Deal's embedded carbon reporting requirements under CSRD are mandating gram-per-kilometer reductions that cascade into supplier material selection decisions. Automakers must now document full lifecycle emissions from aluminum smelting through vehicle dismantling. Premium electric sedan platforms in Germany and South Korea face the steepest compliance ramps, accelerating adoption of closed-loop recycled aluminum and bio-based epoxy systems.
Fleet procurement contracts are consolidating specification authority at the OEM platform engineering level, displacing decentralized Tier-1 material selection. Battery housing suppliers now receive fully defined composite stack sequences rather than performance targets. This concentration is most visible in Germany's automotive corridor, where Volkswagen, BMW, and Mercedes-Benz have centralized lightweighting decisions within cross-functional platform teams.
EV Lightweight Materials Market Segmentation
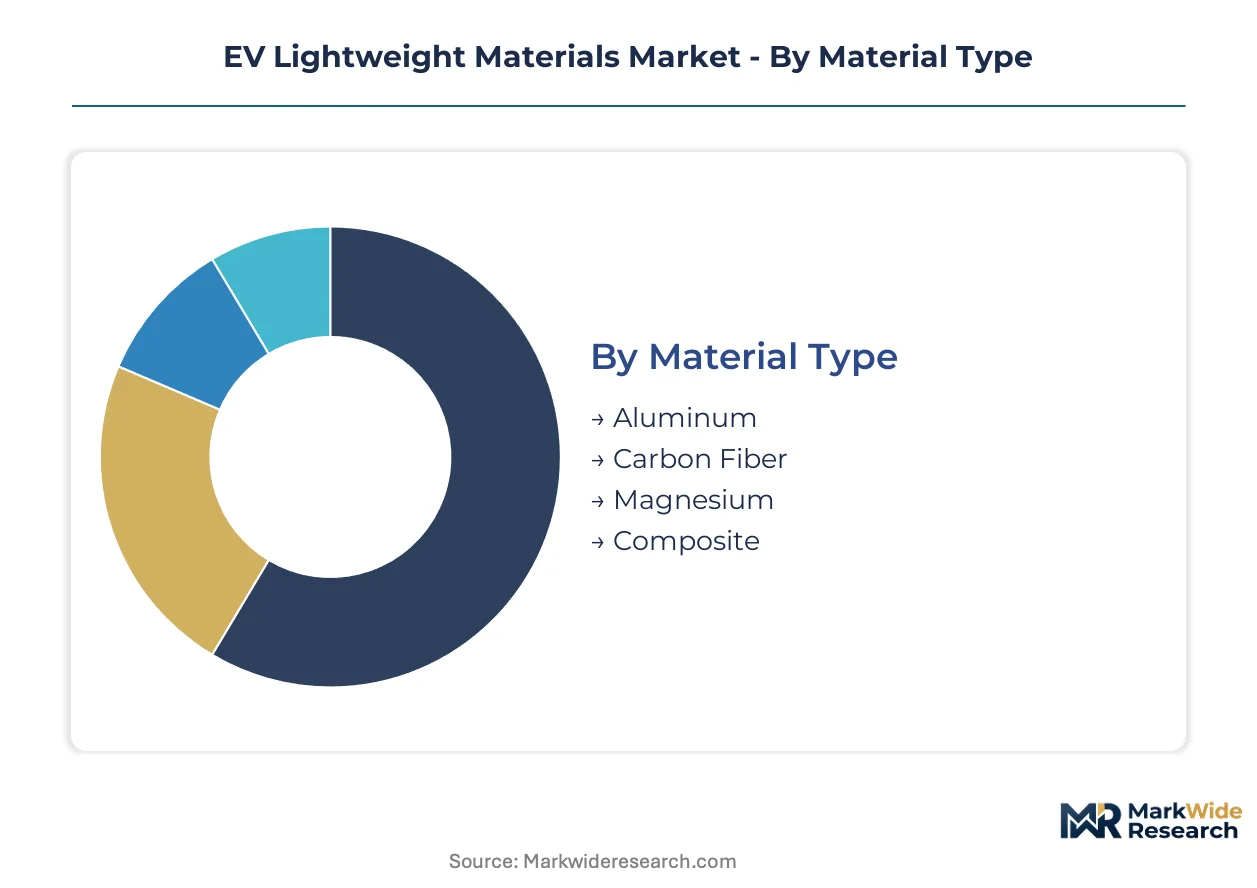
Material selection in electric vehicles cascades through procurement channels with distinct technical and commercial requirements. Each segmentation dimension reveals how specifications, volume thresholds, and regulatory compliance reshape supplier relationships across the value chain.
Material Type:
Aluminum flows through mature stamping and extrusion channels serving high-volume chassis programs, while carbon fiber concentrates in specialized composite houses supplying premium battery enclosures.
- Aluminum:Body-in-white and structural extrusion grades dominate procurement volumes through established rolling mill and smelter networks. German OEMs anchor demand in the automotive corridor, where closed-loop recycling infrastructure reduces virgin material dependency.
- Carbon Fiber:High-modulus PAN-based precursors achieve tensile strengths exceeding 3,500 MPa for battery housing applications. Japanese and South Korean premium sedan platforms pull significant volume, though energy-intensive oxidation cycles constrain price competitiveness against aluminum.
- Magnesium:Die-cast transmission housings and steering column brackets leverage the lowest density among structural metals. Supply concentrates in China's Shanxi province, exposing European automakers to export qualification risks under EU Green Deal carbon thresholds.
- Composite:Thermoplastic resin formulations enable sub-60-second cycle times for high-volume battery enclosure production. REACH restrictions on epoxy hardeners redirect R&D toward bio-based alternatives, opening new supply channels for sustainable material suppliers.
By volume, aluminum leads. By growth pace, composite formulations are expanding most quickly.
Application:
Cost tier stratification separates commodity body panels from engineered battery housings where crash performance and thermal management command premium pricing.
- Chassis:Aluminum-intensive subframes and crash structures balance mass reduction with manufacturing feasibility. Stamping infrastructure maturity keeps per-vehicle costs predictable for mid-market EV platforms.
- Body Panels:Outer skin and closure applications favor 6000-series aluminum alloys with proven dent resistance and surface finish quality. Volume concentration in Germany's automotive corridor reflects BMW, Volkswagen, and Mercedes-Benz lightweighting programs.
- Interior Components:Magnesium instrument panel beams and composite seat structures reduce unsprung mass. Procurement runs through Tier-1 interior specialists with established thermoplastic molding capacity.
- Battery Housing:Carbon fiber reinforced polymers and aluminum-lithium alloys offset cell mass with chassis savings. OEM engineering teams now specify fully defined composite stack sequences rather than performance targets, centralizing specification authority.
Chassis applications command the highest absolute volume. Battery housing specifications are climbing the fastest as cell energy densities rise.
End User:
Customer type determines contract structure, with OEM platform teams consolidating authority while Tier-1 suppliers compete on manufacturing scale.
- OEMs:Volkswagen, BMW, and Mercedes-Benz have centralized lightweighting decisions within cross-functional platform teams. Direct material specification authority now resides at the OEM engineering level rather than with decentralized Tier-1 procurement.
- Tier-1 Suppliers:Battery housing specialists receive fully defined composite stack sequences and must demonstrate sub-60-second cycle time capability. Multi-material joining expertise—bonding aluminum extrusions to carbon fiber panels—remains a scarce capability.
- Aftermarket Providers:Aerodynamic body kits and performance chassis components serve enthusiast segments with lower volume thresholds. Distribution runs through specialty retailers rather than OEM service channels.
- Vehicle Assemblers:Contract manufacturers and emerging EV startups procure standardized aluminum extrusion kits for skateboard platform architectures. India's PLI scheme incentivizes localization of advanced aluminum-lithium alloy capacity for domestic platforms.
OEMs dominate value capture. Tier-1 suppliers face the steepest capability investment requirements.
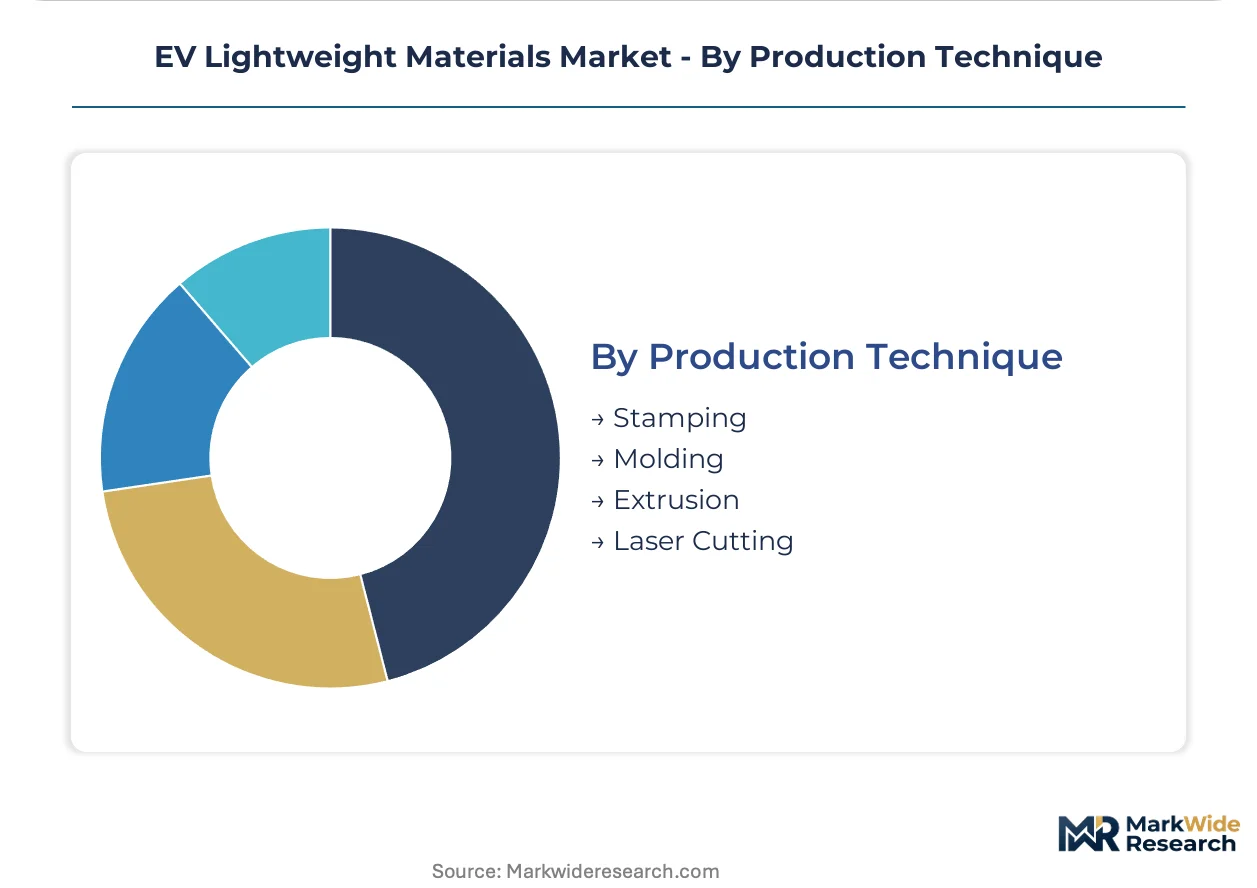
Production Technique:
Volume scale and part complexity dictate process selection, with high-pressure resin transfer molding displacing autoclave cycles in composite battery enclosures.
- Stamping:Mature press infrastructure for aluminum body panels achieves automotive cycle times with minimal capital reinvestment. Detroit-based OEMs leverage existing steel-to-aluminum conversion capacity.
- Molding:Thermoplastic composite formulations for battery housings enable automated fiber placement at automotive cycle times. BMW and Mercedes-Benz engineering teams are qualifying these materials for upcoming platform launches.
- Extrusion:Aluminum crash structures and battery tray rails benefit from continuous profile production with integrated hollow sections. European automakers source from Constellium SE and other advanced alloy specialists.
- Laser Cutting:Precision trimming of carbon fiber preforms and aluminum blanks supports low-volume premium platforms. Process integration with robotic handling systems reduces labor content in high-cost jurisdictions.
Stamping retains the largest installed base. Molding processes for thermoplastic composites are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in lightweight materials tilt toward deficit positions in automotive-intensive economies, while primary metal producers leverage energy cost arbitrage to capture upstream value. Germany's automotive corridor imports carbon fiber precursors from Japan and South Korea while exporting finished aluminum-lithium alloy components to North American assembly plants.
United States
Detroit-based OEMs anchor aluminum demand through closed-loop recycling partnerships that reduce virgin material dependency. EPA tailpipe emission standards and NHTSA Corporate Average Fuel Economy rules mandate gram-per-kilometer reductions that cascade into material selection decisions. Michigan and Ohio house the densest concentration of aluminum stamping infrastructure serving mid-market EV platforms.
Germany
BMW, Volkswagen, and Mercedes-Benz engineering teams centralize lightweighting decisions within cross-functional platform teams, consolidating specification authority at the OEM level. The EU Green Deal's embedded carbon reporting requirements under CSRD force documentation of full lifecycle emissions from smelting through dismantling. Bavaria and Baden-Württemberg host the principal composite qualification laboratories for 2026 platform launches.
China
Primary aluminum smelters in western provinces supply global automotive demand while MIIT new-energy vehicle credit systems reshape export qualification requirements. GB standards for recyclability mandate design-for-disclosure protocols that complicate composite material imports. The Yangtze River Delta concentrates die-cast magnesium capacity for transmission housings serving domestic EV platforms.
Japan
Toray Industries anchors high-modulus carbon fiber output for premium electric sedan platforms, leveraging PAN-based precursor technology developed for aerospace applications. METI industrial policy supports thermoplastic composite R&D to compress automotive cycle times. Nagoya and Tokyo metropolitan areas host the principal fiber placement automation development centers.
South Korea
Domestic battery manufacturers pull carbon fiber reinforced polymer volumes for enclosure applications as cell energy densities rise. MFDS and national industrial regulators align lightweight material incentives with export platform requirements. Gyeonggi-do province concentrates thermoplastic tape laying capacity for next-generation housing structures.
EV Lightweight Materials Market Competitive Landscape
Concentration sits with integrated aluminum producers and specialized composite houses rather than diversified chemical conglomerates. The vendor base organizes around three strategic archetypes: closed-loop recycling specialists securing OEM supply contracts, high-modulus fiber manufacturers serving premium platforms, and advanced alloy developers qualifying for crash-critical applications. Competitive moves center on backward integration into primary metal supply and geographic expansion through qualification partnerships with platform engineering teams.
Among North American aluminum specialists, Alcoa Corporation and Novelis Inc. occupy positions within the integrated producer tier, while Constellium SE exemplifies the European advanced alloy archetype. Toray Industries, Inc. anchors the high-modulus carbon fiber segment for battery enclosure applications. These named entities represent distinct capability concentrations rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Novelis Inc. |
| Constellium SE |
| SGL Carbon SE |
| Toray Industries, Inc. |
| BASF SE |
| ArcelorMittal |
| Covestro AG |
| Hexcel Corporation |
| Others |
Supply & Pricing Matrix
Primary aluminum smelter scale economies in China's western provinces and the GCC anchor global price floors, concentrating supply-side leverage among integrated producers while forcing European automakers to absorb energy cost volatility through long-term offtake premiums. This scale asymmetry compresses margins for mid-market converters and rewards backward-integrated specialists with captive primary supply.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across aerospace-grade carbon fiber, automotive-grade aluminum-lithium alloys, and commodity 6000-series sheet. Price differentiation hinges on crash-test certification tier and closed-loop recycling content verification under CSRD. Cost compression in aluminum extrusions is intensifying because Chinese smelter capacity expansions loosened spot market tightness. Fleet procurement teams at German OEMs exhibit lowest price sensitivity, prioritizing gram-per-kilometer compliance over per-kilogram cost.
Supply Chain Analysis
Strategic stockpiling of PAN-based carbon fiber precursors dominates inventory strategy, with Japanese and South Korean textile manufacturers maintaining six-month forward cover against aerospace demand surges. Geographic supply concentration centers on China for primary aluminum, Japan for high-modulus fiber, and Germany for advanced alloy development. Raw material dependencies include bauxite ore, acrylonitrile monomer, and lithium carbonate. Single-source vulnerability in aerospace-grade precursor supply exposes automotive qualification timelines to disruption. Distribution runs through Tier-1 system houses with integrated composite molding and aluminum stamping capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-material joining expertise—bonding aluminum extrusions to carbon fiber panels—represents the critical capability gap separating qualified suppliers from commodity converters, with fewer than twelve Tier-1 houses globally having scaled this competence.
For Market Incumbents: Fortify specification authority by embedding engineers within BMW, Volkswagen, and Mercedes-Benz platform teams before 2026 launch cycles solidify. Deepen captive supply of closed-loop recycled aluminum to offset virgin price volatility from Chinese smelter energy cost swings. Prioritize thermoplastic composite R&D partnerships with Toray Industries to defend against emerging tape-laying automation specialists. For New Entrants and Emerging Players: Differentiate on CSRD-compliant lifecycle data capture, offering verified embedded carbon accounting that incumbent metal suppliers lack. Target India's PLI-qualified domestic EV platforms, where localized aluminum-lithium capacity gaps create procurement urgency. Lead with automated fiber placement equipment leases rather than capital-intensive autoclave investments. For Investors and Strategic Acquirers: Composite-focused engineering houses with existing OEM platform qualifications represent the highest-conviction acquisition archetype, given five-to-ten-year automotive homologation timelines that protect incumbent positions. Watch for inflection when EU battery regulation enforcement tightens end-of-life recycling compliance, forcing OEMs to abandon thermoset legacy suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Infrastructure | Novelis and Alcoa secure Detroit OEM contracts by guaranteeing 80%+ recycled content under EPA standards. |
| Thermoplastic Composite Qualification | BMW and Mercedes-Benz engineering teams validate sub-60-second cycle times for 2026 battery housing platforms. |
| CSRD Lifecycle Data Systems | Material suppliers with verified smelting-to-dismantling emissions capture specification advantage in EU procurement. |
| Multi-Material Joining Scale-Up | Tier-1 houses with proven aluminum-to-carbon fiber adhesive protocols qualify for premium electric sedan programs. |
| India PLI Localization | Constellium and domestic partners anchor advanced alloy capacity to serve Mahindra and Tata EV platforms. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier-1 procurement directors, composite R&D leads, and aluminum smelter planning officers converged on the working assumptions driving material substitution timelines. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, IHS Markit vehicle production databases, EU ETS carbon price series, and customs trade flows for aluminum and carbon fiber precursor categories. Bottom-up buildups of battery housing content per vehicle triangulated against top-down market value estimates.
Segmentation dimensions modeled include material type, application tier, end-user category, and production technique across the analysis window. CAGRs derived from curve-fitting historical substitution elasticities against regulatory compliance ramps, with specific weighting for F-Gas Regulation phase-down schedules and NHTSA CAFE stringency curves. Forecast inputs incorporated cell energy density roadmaps from South Korean battery manufacturers and aluminum scrap recovery rates from European closed-loop systems.
Forecasts assume regulatory continuity in EU Green Deal implementation and EPA tailpipe standards; material policy shifts would require re-modeling. Revision becomes warranted when carbon fiber precursor capacity expansion crosses aerospace-automotive demand balance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Pickup Truck Market
Electric Vehicles
Europe Wireless Electric Vehicle Charging Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
Electric Passenger Cars Market
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
France E-Bike Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
Asia-Pacific Train Battery Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
ASEAN Electric Bicycle Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
South America Electric Vehicles Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
Europe Electric Scooter Market