
 Automotive Key Market | 2026-2036
Automotive Key Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Key Market Intelligence
The customer base for advanced automotive access systems is expanding beyond traditional OEMs to include large-scale fleet operators and mobility service providers. Continental AG leverages its expertise in vehicle electronics to supply integrated access and authorization systems. Robert Bosch GmbH competes through its development of secure digital key solutions for connected vehicles. Valeo specializes in smart access technologies, including phone-as-a-key systems.
An automotive key is an electronic device used for vehicle access and ignition authorization, communicating with the car's immobilizer via radio-frequency or digital protocols. Modern systems utilize technologies like Ultra-Wideband (UWB) for precise, secure ranging and passive entry. While Passenger Cars remain the largest product type, demand for integrated Connectivity Modules is highest in the Electric Vehicles segment. OEMs represent the primary end-user channel, though the Aftermarket Providers segment shows potential for digital key retrofitting.
Product development must comply with radio frequency regulations, such as those overseen by the FCC in the United States and the EU's Radio Equipment Directive. In China, vehicle security systems are subject to specific GB standards for anti-theft performance. These regulations dictate component certification, transmission power, and cybersecurity requirements for market access. Future competitiveness depends on aligning with cross-industry digital key standards being developed by automotive and technology consortia.
Market Dynamics
The central structural force shaping the automotive key market is the convergence of vehicle electronics with consumer mobile technology. This integration is transforming the key from a simple access device into a digital identity platform, driven by the adoption of standards like those from the Car Connectivity Consortium.
Growth Catalysts
- Ultra-Wideband (UWB) Technology:The adoption of UWB provides highly accurate and secure spatial awareness, enabling advanced passive entry and theft prevention features that are in high demand from premium vehicle manufacturers.
- Commercial Fleet Management:Large-scale fleet operators require sophisticated access control, vehicle tracking, and usage monitoring, creating substantial demand for integrated digital key and telematics systems to improve operational efficiency.
- Digital Key Standardization:The development of cross-industry standards by consortia facilitates interoperability between vehicles and smart devices, reducing development costs for OEMs and accelerating market-wide adoption of phone-as-a-key solutions.
Market Restraints
- High Integration Costs:The expense associated with integrating advanced UWB and NFC hardware, along with developing secure software ecosystems, limits their deployment primarily to premium and mid-range vehicle segments.
- Cybersecurity Vulnerabilities:The increasing connectivity of digital keys exposes them to sophisticated cyberattacks, such as relay attacks, necessitating significant and continuous investment in complex cryptographic and security protocols.
- Regulatory Fragmentation:Manufacturers face complex compliance hurdles due to differing radio frequency regulations, such as those from the FCC in the US and the EU's Radio Equipment Directive, which can delay product launches.
Strategic Opportunities
- Aftermarket Retrofitting:A significant opportunity exists in the aftermarket to provide digital key solutions for the vast global fleet of existing vehicles lacking factory-installed smart access systems.
- Biometric Integration:Combining digital keys with biometric authentication like fingerprint or facial recognition offers a path to enhanced security and personalization, creating a new tier of premium access systems.
- Expanded Functionality:Digital keys can evolve into platforms for new services, including in-car payments, automated toll collection, and personalized vehicle settings that follow the driver across different cars.
Industry Challenges
- Cross-Platform Interoperability:Ensuring seamless and reliable communication between diverse smartphone operating systems, vehicle models, and backend cloud services remains a persistent technical challenge for system developers.
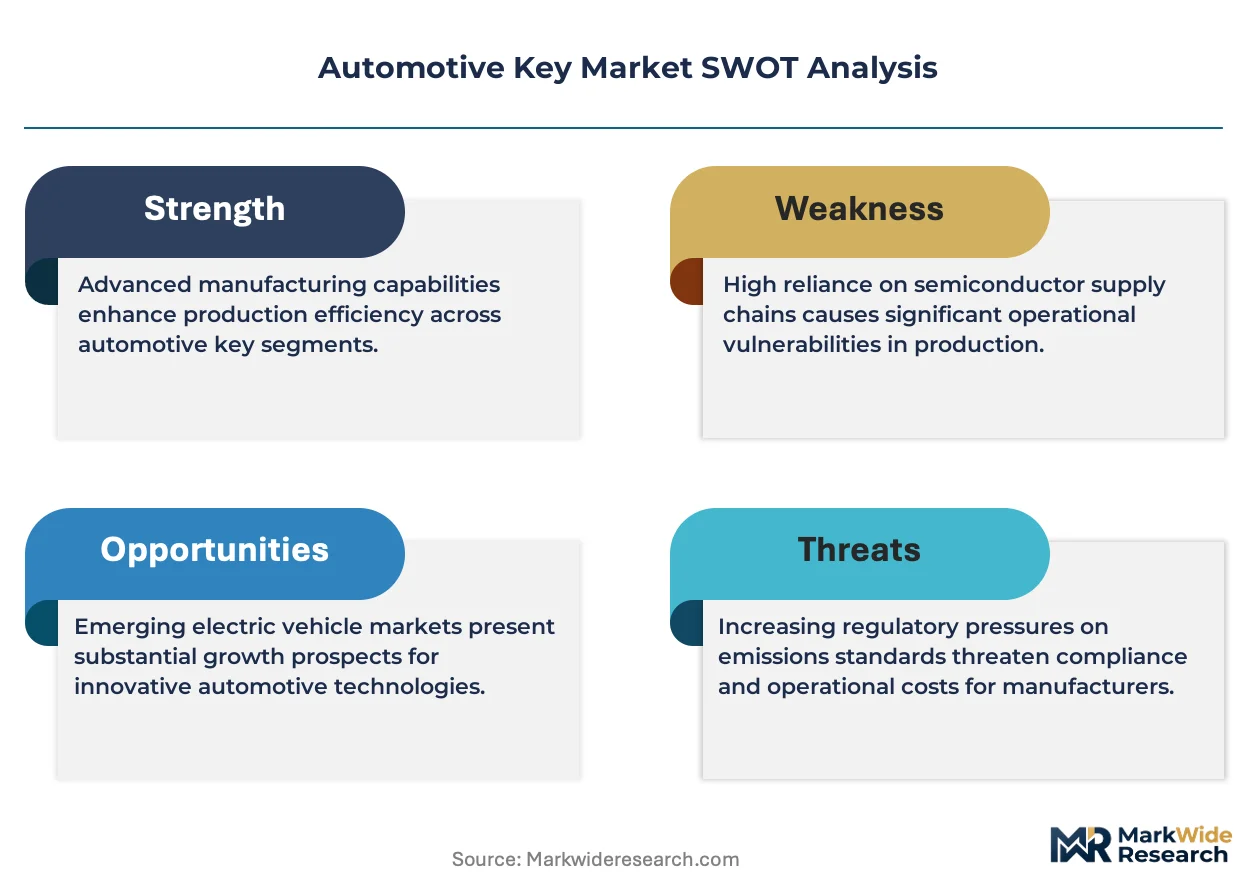
- Semiconductor Supply Chain:The market is dependent on a stable supply of specialized RF and security microcontrollers, making it vulnerable to the supply chain disruptions and shortages affecting the global semiconductor industry.
- Legacy System Integration:Integrating modern digital access systems with the legacy electronic architectures of older vehicle platforms presents significant engineering and compatibility hurdles for aftermarket providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Key Market |
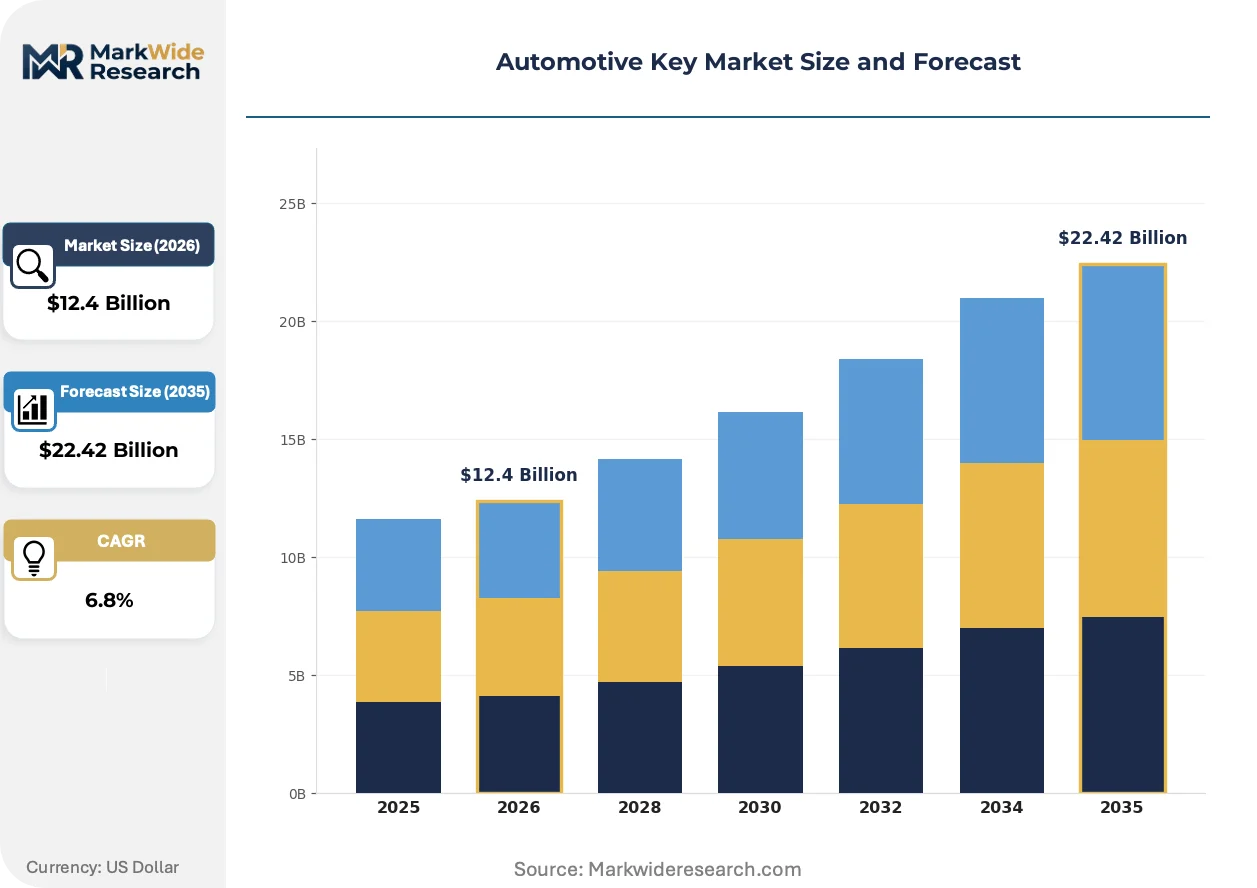
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles, Two-Wheelers Technology: Autonomous Driving, Infotainment Systems, Connectivity Modules, Advanced Driver Assistance Systems, Telematics Application: Fleet Management, Logistics, Personal Transportation, Ride-Hailing, Vehicle Leasing End User: OEMs, Tier-1 Suppliers, Dealerships, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Hella GmbH & Co. KGaA, Continental AG, Denso Corporation, ZF Friedrichshafen AG, Robert Bosch GmbH, Delphi Technologies, Keystone Automotive Industries, Strattee Security Corporation, Valeoo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Key Market Strategic Shifts & Innovations
A fundamental shift from hardware-centric fobs to software-defined access is redefining value in the automotive key market. This evolution prioritizes service-based features, connectivity, and user experience over the physical device itself, creating new revenue models tied to digital services and subscriptions.
Digital key technology, which leverages smartphones via NFC and Bluetooth, provides secure, shareable vehicle access. OEMs in the premium and electric vehicle segments are rapidly adopting these systems to enhance customer convenience and enable new mobility services. This technology is decentralizing access control away from a dedicated physical object, placing it onto user-owned smart devices and transforming the ownership model.
New cybersecurity mandates, such as the UN R155 regulation, are impacting product development. This rule requires manufacturers to implement and certify comprehensive cybersecurity management systems for all new vehicles sold in signatory regions like the European Union and Japan. Consequently, suppliers of automotive keys and access modules face stricter security validation and lifecycle management requirements to mitigate cyber threats.
Consumer expectations, shaped by the smartphone industry, are driving demand for seamless integration and convenience. This is disrupting the traditional model of providing a fixed number of physical keys, pushing OEMs to develop robust mobile apps and cloud platforms for digital key management. The shift is most visible in shared mobility fleets and among tech-savvy buyers in North America and Europe.
Automotive Key Market Segmentation
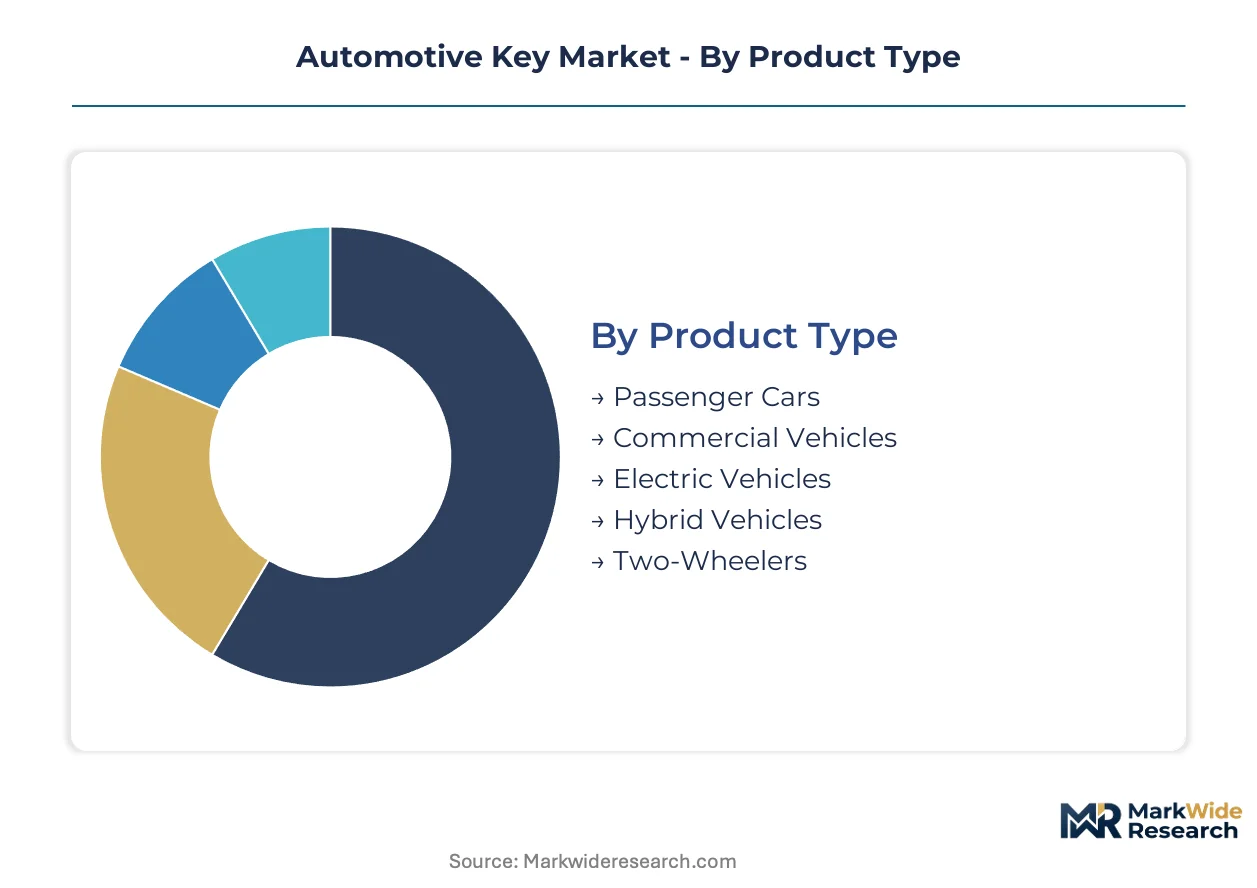
The automotive key market comprises diverse segments, each presenting unique technological requirements and investment thresholds. Understanding these distinctions helps stakeholders identify areas for strategic product development and market penetration. Market dynamics vary significantly across different vehicle types, access technologies, and end-user applications.
Product Type:
Segments within this category often reflect differing levels of capital investment for integration into vehicle platforms.
- Passenger Cars:This segment encompasses keys for standard consumer vehicles, frequently integrating advanced features like passive entry and remote start. Demand for these systems is driven by evolving consumer expectations for convenience and security across major automotive markets like Germany and Japan.
- Electric Vehicles:Automotive keys for EVs prioritize seamless digital integration and energy efficiency, often leveraging phone-as-a-key solutions. The rapid expansion of EV manufacturing in countries like China and the United States drives the demand for innovative, lightweight access systems.
- Commercial Vehicles:Keys for commercial fleets require robust durability and advanced telematics integration for fleet management.
- Hybrid Vehicles:These keys blend traditional and digital functionalities, catering to vehicles with mixed power trains.
- Two-Wheelers:Motorcycle and scooter keys increasingly incorporate smart features and enhanced anti-theft mechanisms.
Most installed capacity flows through Passenger Cars. Expansion is steepest in Electric Vehicles.
Technology:
Technology segments highlight the functional capabilities and integration complexities of modern automotive key systems.
- Connectivity Modules:These modules enable vehicle-to-cloud communication, supporting remote access, over-the-air updates, and digital key sharing capabilities. The automotive industry in South Korea and Germany heavily invests in these modules to enhance vehicle intelligence and user experience.
- Autonomous Driving:Keys for autonomous vehicles integrate with complex sensor suites and AI systems, requiring high levels of security and authorization protocols. Development in this area is concentrated in research hubs across the United States and Japan.
- Infotainment Systems:Keys often interface with vehicle infotainment for personalized settings and multimedia control.
- Advanced Driver Assistance Systems:Integration with ADAS can enable automated parking or specific driver profiles linked to the key.
- Telematics:Telematics systems leverage key data for vehicle tracking, diagnostics, and emergency services.
The largest volume is attributed to Connectivity Modules. The segment demonstrating the fastest growth is Autonomous Driving.
Application:
Application segments delineate how automotive key systems are utilized across various operational contexts.
- Fleet Management:This application involves sophisticated key systems for tracking, access control, and usage monitoring within large vehicle fleets. Demand for these integrated solutions is high among logistics companies in the United States and Europe.
- Personal Transportation:Keys for individual vehicle owners focus on convenience, security, and personalization features, such as passive entry and digital identity. This remains the dominant application in mature automotive markets like Japan and Germany.
- Logistics:Keys used in logistics operations prioritize robust security and efficient vehicle handovers.
- Ride-Hailing:These applications require flexible, shareable digital key solutions for multiple drivers.
- Vehicle Leasing:Keys for leased vehicles often include features for remote disablement and usage monitoring.
The primary use case remains Personal Transportation. However, Fleet Management is gaining share fastest.
End User:
End-user segments represent the primary purchasers and integrators of automotive key solutions, each with distinct procurement priorities.
- OEMs:Original Equipment Manufacturers integrate automotive key systems directly into new vehicles during the manufacturing process. These entities demand high-volume supply, stringent quality control, and compliance with global automotive standards from their suppliers.
- Aftermarket Providers:This segment includes companies offering key replacement, repair, and upgrade services for existing vehicles. Aftermarket providers seek cost-effective, compatible solutions that can be integrated into a wide range of vehicle models.
- Tier-1 Suppliers:These suppliers develop and provide integrated modules and components to OEMs.
- Dealerships:Dealerships handle key programming and replacement services for new and used vehicles.
- Vehicle Assemblers:Assemblers integrate key systems as part of the final vehicle production process.
The largest purchasing volume originates from OEMs. The segment with the most significant margin potential is Aftermarket Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Germany and Japan have long anchored traditional automotive key manufacturing, China and the United States are increasingly driving innovation in digital key integration for electric vehicles. The global automotive key market demonstrates varied regional dynamics influenced by established automotive industries and rapid technological shifts. This regional diversity shapes technology adoption rates and regulatory landscapes across different continents.
Germany
Demand in Germany is high for advanced security features and passive entry systems from premium vehicle manufacturers. The EU's Radio Equipment Directive (RED) dictates stringent compliance for wireless communication devices in these systems. The Stuttgart region remains a central hub for automotive innovation, fostering research and development in secure access technologies.
Japan
Japanese consumers expect high levels of convenience and security in their personal vehicles, driving demand for advanced key functionalities. METI oversees the certification and quality standards for electronic components used in automotive systems. The Tokyo metropolitan area is a significant center for automotive R&D and the manufacturing of sophisticated key technologies.
South Korea
South Korea exhibits strong demand for connectivity modules and leverages its expanding electric vehicle manufacturing base. The country's MFDS regulates electronic components, including those found in automotive access systems, ensuring product safety and performance. The Seoul and Gyeonggi regions are at the forefront of integrating advanced tech into vehicle access solutions.
China
China's rapid expansion in electric vehicle production fuels substantial demand for digital key solutions and integrated access systems. Specific GB standards govern anti-theft performance and security requirements for vehicle systems in the Chinese market. The Yangtze River Delta region is a key area for EV manufacturing, driving the supply chain for advanced automotive keys.
United States
The United States market is characterized by tech-savvy buyers and a growing shared mobility sector, increasing demand for phone-as-a-key solutions. FCC regulations control the radio frequency parameters for all wireless devices, including automotive keys, ensuring spectrum efficiency. Silicon Valley and Detroit serve as innovation centers for software-defined vehicle access and automotive technology development.
Automotive Key Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the automotive key market. The market exhibits a tiered structure, with established Tier-1 suppliers alongside emerging software-centric solution developers. Strategic partnerships for digital key standardization and continuous investment in robust cybersecurity protocols represent dominant competitive moves.
Established Tier-1 suppliers like Continental AG and Robert Bosch GmbH anchor much of the market's innovation, providing comprehensive integrated access and authorization systems. Valeo, a French automotive supplier, exemplifies a specialist in smart access technologies, including phone-as-a-key systems. These companies are actively navigating the convergence of vehicle electronics with consumer mobile technology.
| Leading Market Players |
|---|
| Hella GmbH & Co. KGaA |
| Continental AG |
| Denso Corporation |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Delphi Technologies |
| Keystone Automotive Industries |
| Strattee Security Corporation |
| Valeo |
| Others |
Cost & Logistics Intelligence
The Semiconductor Industry Association (SIA) billings index volatility directly influences the cost of specialized RF and security microcontrollers, cascading into varied pricing tiers for automotive key systems. This linkage shapes pricing power for Tier-1 suppliers and OEMs.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for standard automotive key components. The dominant pricing model remains per-unit transactional, with price differentiation driven by certification level for cybersecurity and customization for premium features. Pricing softness stems from increasing standardization by consortia like the Car Connectivity Consortium. Aftermarket providers exhibit the highest price sensitivity, while premium vehicle OEMs prioritize advanced security features over cost.
Supply Chain Analysis
Rising global freight costs impact the delivery of specialized RF microcontrollers and UWB transceivers critical for modern automotive keys. Geographic supply concentration for these components centers on South Korea, Germany, and Taiwan. The market draws from specialized RF chips and NFC modules, creating vulnerability to semiconductor supply chain disruptions. Distribution runs predominantly through Tier-1 suppliers directly to OEMs, with Aftermarket Providers sourcing through a fragmented network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive key market presents a margin-expansion story, driven by the shift towards software-defined access and new digital service revenue models. This transition allows for value capture beyond hardware sales.
For Market Incumbents: Cement leadership in UWB and digital key platforms to counter emerging software-centric entrants. Invest in advanced cybersecurity certification to mitigate risks from sophisticated cyberattacks and comply with UN R155 regulations. Deepen vertical integration into secure microcontroller development to control critical component supply. This strategy protects against margin erosion from commoditization of basic physical keys.
For New Entrants and Emerging Players: The EU's Radio Equipment Directive in Europe opens a window for specialized software solution providers focusing on digital key interoperability. Target the Aftermarket Providers segment by offering retrofitting solutions for older vehicle fleets. Develop platform-agnostic phone-as-a-key solutions that integrate seamlessly with diverse smartphone operating systems. Focus on subscription-based access management services for shared mobility fleets in urban centers.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized software developers and UWB technology innovators offering robust digital key ecosystems. The long-term viability of this market hinges on continued integration with broader vehicle electronics and mobility services. Seek acquisition targets with strong intellectual property in secure communication protocols and biometric authentication. A signal to watch is the widespread adoption of digital key standards across mid-range vehicle segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Ensures interoperability across vehicle models and smart devices, reducing OEM development costs. |
| UWB Technology Investment | Enables precise spatial awareness for enhanced security and passive entry features. |
| Cybersecurity Protocol Development | Mitigates sophisticated cyberattack risks, complying with global automotive regulations. |
| Digital Key Ecosystem Expansion | Creates new revenue streams through subscription services and personalized vehicle settings. |
| Aftermarket Retrofit Solutions | Captures significant demand from existing vehicles lacking advanced access systems. |
Research Approach
Multiple input streams — primary interviews, industry reports, and regulatory filings — were reconciled to build a comprehensive market view. Primary engagement included automotive OEM procurement leads, Tier-1 R&D directors, fleet management operators, and cybersecurity specialists. Secondary validation drew from vehicle production databases, FCC filings, and Car Connectivity Consortium publications. This approach employed both bottom-up and top-down triangulation for robust data synthesis.
Historical market performance was cross-referenced with expert panel input to project future trends across the analysis window. The analytical framework modeled dimensions such as product type, technology, application, end-user, and security protocol complexity. Compound annual growth rates were derived from a weighted average of historical trends and anticipated technological adoption. Key forecast inputs included electric vehicle production forecasts and digital key standardization roadmaps.
Revisions become necessary when significant shifts in regulatory frameworks or semiconductor supply chain stability materialize. Forecasts reflect assumptions regarding technological adoption rates and consumer preferences. A model refresh is warranted upon material change in cross-industry digital key standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
Automotive Filters Market
Automotive Components
Automotive Metal Stamping Market
Automotive Components
India Automotive Stamping Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Automotive Solenoid Market
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Automotive Resonator Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Automotive Distributor Market
Automotive Components
Automotive Mufflers Market
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Automotive Fuel Injection System Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Automotive Camshaft Phase Variator Market