
 Europe Torque Vectoring Market | 2026-2036
Europe Torque Vectoring Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Torque Vectoring Market Insights
The capital-intensity divergence between full-system integrators and component specialists is redrawing competitive boundaries in European torque vectoring. ZF Friedrichshafen leverages its integrated driveline portfolio to anchor premium all-wheel-drive contracts with German OEMs. BorgWarner competes through sustained R&D spending on electrified torque distribution architectures for hybrid platforms. Continental AG differentiates via sensor fusion capabilities that merge torque vectoring with advanced driver-assistance domains.
Torque vectoring encompasses active and passive driveline technologies that distribute rotational force across individual wheels to enhance vehicle stability, traction, and cornering precision; electronic torque distribution systems deploy clutch packs or electric motors modulated by control algorithms reacting within milliseconds to yaw-rate sensors and wheel-speed data. Active torque vectoring commands the dominant share of value pools as OEMs prioritize real-time adjustability over mechanical simplicity. Electric vehicles represent the fastest-expanding end-user category as dual-motor architectures inherently enable software-defined torque allocation without additional hardware.
The EU Green Deal and F-Gas Regulation shape powertrain electrification timelines that directly expand addressable demand for electronic torque distribution systems. EMA safety standards and CE marking requirements for automotive electronics govern product certification pathways and supplier qualification cycles. Stakeholders must monitor how CSRD disclosure mandates alter capital allocation transparency among tier-one suppliers and whether the EU AI Act extends compliance burdens to autonomous-vehicle-integrated torque control algorithms.
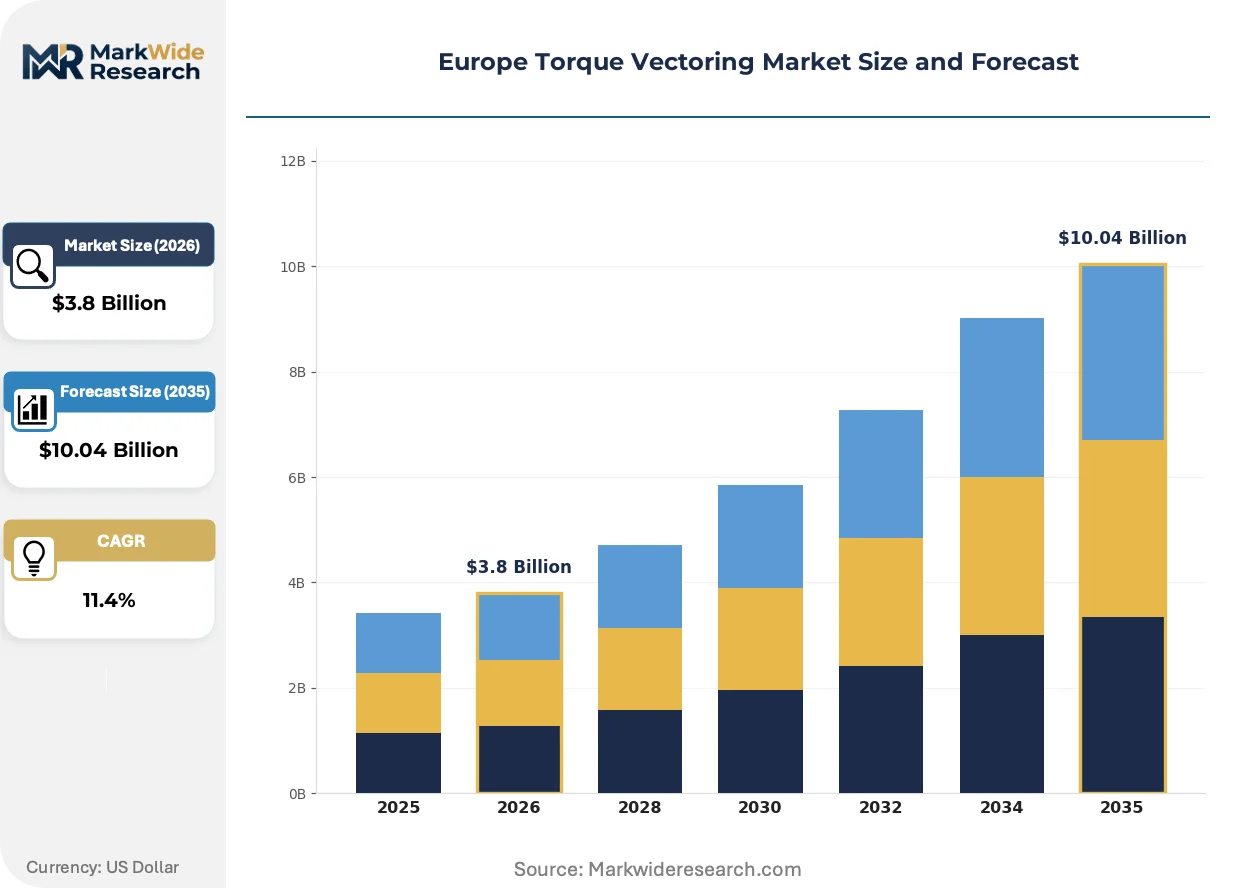
Market Dynamics
The EU Green Deal's powertrain electrification mandates are compressing development cycles for electronic torque distribution architectures, forcing OEMs to integrate software-defined torque allocation into dual-motor platforms before legacy mechanical systems reach end-of-life.
Growth Catalysts
- EMA Safety Standards:Updated vehicle stability requirements mandate yaw-rate-responsive torque modulation in premium passenger segments, accelerating control algorithm deployment across German and UK assembly lines.
- Dual-Motor EV Architectures:Battery-electric platforms eliminate mechanical differential hardware while enabling millisecond-level wheel torque adjustments through motor controllers alone.
- Stuttgart-Munich-Wolfsburg Corridor:Engineering talent concentration and tier-one supplier proximity reduce system integration lead times for German OEMs pursuing handling performance benchmarks.
Market Restraints
- Semiconductor Input Volatility:Torque vectoring control units depend on automotive-grade microcontrollers whose foundry allocation competes with consumer electronics and battery management systems.
- CE Marking Certification Burden:Electromagnetic compatibility testing and functional safety validation under automotive electronics directives extend supplier qualification cycles by 12-18 months.
- Mechanical Limited-Slip Differentials:Passive torque biasing remains cost-competitive in mass-market segments where electronic actuation hardware cannot achieve price parity.
Strategic Opportunities
- Poland and Czech Republic Manufacturing:Central European automotive assembly expansion creates demand for localized torque vectoring module production serving VW Group and Stellantis facilities.
- CSRD-Aligned Supplier Transparency:Corporate sustainability reporting mandates favor tier-one suppliers with documented carbon footprint reduction in electrified drivetrain component sourcing.
- Sensor Fusion Convergence:Integration of torque vectoring control with ADAS domain controllers enables predictive chassis adjustments using camera and radar trajectory data.
Industry Challenges
- Embedded Software Talent Scarcity:Control algorithm development for real-time torque modulation requires specialized expertise in vehicle dynamics modeling that outpaces European engineering graduate pipeline output.
- Legacy Platform Integration Friction:Retrofitting electronic torque distribution into existing vehicle electrical architectures demands extensive harness redesign and gateway recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Torque Vectoring Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Torque Vectoring, Passive Torque Vectoring, Electronic Torque Distribution, Mechanical Torque Distribution End User: Passenger Vehicles, Commercial Vehicles, Motorsports, Electric Vehicles Application: All-Wheel Drive, Front-Wheel Drive, Rear-Wheel Drive, Hybrid Systems Technology: Mechanical Systems, Sensor-Based Systems, Control Algorithms, Software Integration |
| Companies Covered | ZF Friedrichshafen AG, BorgWarner Inc., Continental AG, Schaeffler AG, GKN Automotive, Bosch Group, Magna International Inc., Haldex AB, Nexteer Automotive, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Torque Vectoring Market Trends and Innovations
Software-defined vehicle architectures are dissolving the boundary between powertrain and chassis control domains, enabling torque vectoring functionality to migrate from dedicated hardware modules into centralized compute platforms.
Multi-clutch torque vectoring differentials are fragmenting the traditional mechanical all-wheel-drive market by replacing passive center differentials with actively controlled clutch packs. Premium German OEMs are adopting these systems for performance variants where individual wheel torque modulation differentiates handling characteristics. The technology is fragmenting supplier value capture as clutch pack manufacturers compete with integrated driveline providers for control software ownership.
F-Gas Regulation refrigerant phase-down timelines are indirectly accelerating torque vectoring adoption by compressing internal combustion engine development investment, redirecting engineering resources toward electrified platforms where electronic torque distribution is native. Powertrain electrification roadmaps in Germany and France now prioritize dual-motor layouts with inherent torque vectoring capability over mechanical complexity. Battery-electric vehicle segments show the strongest regulatory pull for integrated electronic torque control systems.
Fleet procurement criteria for corporate mobility programs are elevating active safety and handling performance to primary selection factors, displacing traditional horsepower and displacement metrics. Leasing companies and corporate fleet managers in the UK and Netherlands now specify torque vectoring-equipped vehicles for executive transport categories. This specification shift concentrates demand in premium battery-electric segments where electronic torque distribution is standard rather than optional equipment.
Europe Torque Vectoring Market Segmentation
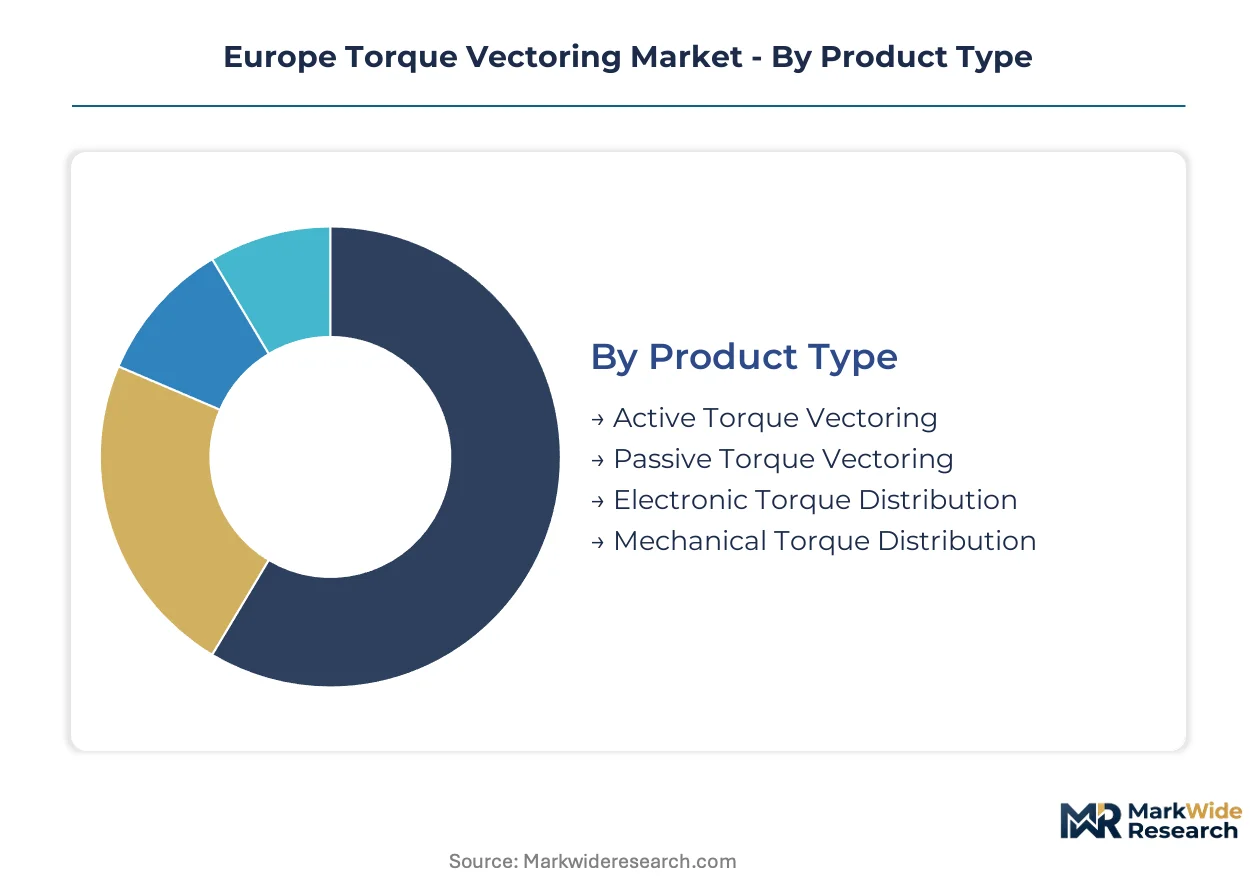
Torque vectoring architectures fragment across hardware-software boundaries that determine regulatory compliance pathways under EU automotive electronics directives. Segment selection dictates CE marking complexity, functional safety validation scope, and supplier qualification timelines for tier-one integrators.
Product Type:
EMA safety standards and F-Gas Regulation timelines differentiate certification burdens across mechanical and electronic architectures, with electronic systems facing extended electromagnetic compatibility testing cycles.
- Active Torque Vectoring:Clutch packs or electric motors modulate individual wheel torque in real-time through millisecond-response control algorithms. German OEMs in Stuttgart and Munich prioritize these systems for premium passenger vehicles to meet yaw-rate-responsive stability mandates under updated EMA requirements.
- Electronic Torque Distribution:Dual-motor EV platforms enable software-defined torque allocation without mechanical differentials, eliminating hardware mass while enabling predictive chassis adjustments. This architecture expands most quickly in battery-electric segments where EU Green Deal electrification timelines compress development cycles.
- Passive Torque Vectoring:Mechanical limited-slip differentials bias torque through gear friction without electronic actuation.
- Mechanical Torque Distribution:Traditional center and axle differentials distribute torque through fixed gear ratios.
Established volume favors passive torque vectoring; emerging adoption favors electronic torque distribution.
End User:
Customer procurement criteria concentrate demand in segments where handling performance and active safety specifications dominate fleet selection decisions.
- Passenger Vehicles:Premium German and UK manufacturers specify torque vectoring as standard equipment in executive segments, with corporate mobility programs in the Netherlands and UK elevating stability performance to primary selection criteria.
- Electric Vehicles:Dual-motor architectures inherently enable torque vectoring through motor controllers alone, making this segment the steepest expansion trajectory as OEMs redirect engineering resources from internal combustion platforms.
- Commercial Vehicles:Heavy-duty stability requirements drive adoption in premium van and truck categories serving logistics corridors.
- Motorsports:FIA-sanctioned competitions mandate specific torque distribution architectures for homologation.
Fleet procurement concentrates in passenger vehicles; technology migration favors electric vehicles.
Application:
Drivetrain configuration determines hardware complexity and software integration scope for tier-one suppliers.
- All-Wheel Drive:Multi-clutch center differentials with active torque modulation replace passive mechanical systems in premium segments, fragmenting supplier value capture between clutch manufacturers and integrated driveline providers.
- Hybrid Systems:Power-split architectures demand coordinated torque management between electric motors and internal combustion engines, requiring specialized control algorithms that merge powertrain and chassis domains.
- Front-Wheel Drive:Transverse engine layouts limit torque vectoring hardware packaging options.
- Rear-Wheel Drive:Performance variants adopt electronic limited-slip differentials for drift stability and launch control.
Volume production centers on all-wheel drive; electrification investment flows toward hybrid systems.
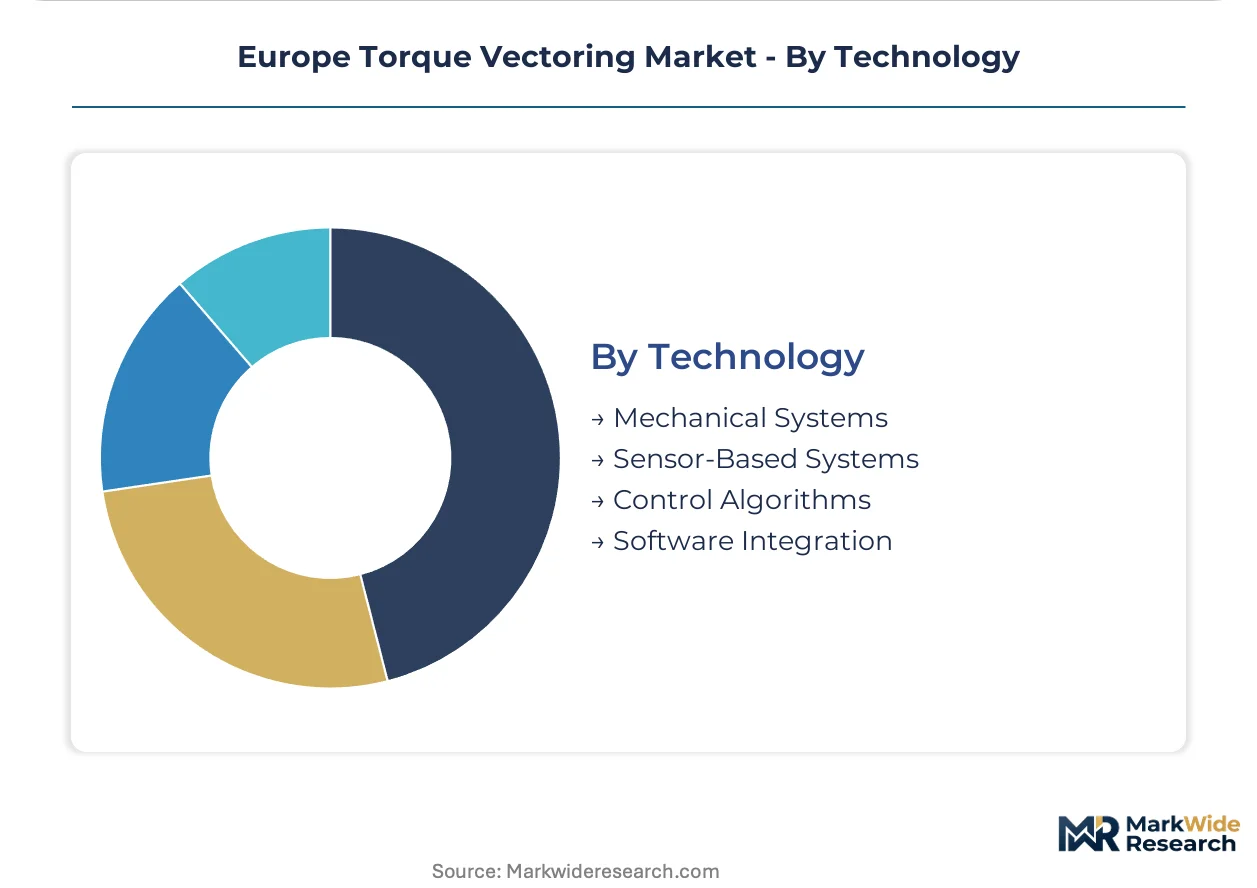
Technology:
Software-defined vehicle architectures are dissolving boundaries between powertrain and chassis control domains, redistributing value from hardware modules to centralized compute platforms.
- Control Algorithms:Real-time yaw-rate and wheel-speed processing enables predictive torque adjustments before traction loss occurs. Embedded software talent scarcity in vehicle dynamics modeling constrains development velocity across European engineering corridors.
- Software Integration:Migration of torque vectoring functionality into centralized domain controllers enables sensor fusion with ADAS trajectory data, though legacy platform electrical architecture redesign creates integration friction.
- Mechanical Systems:Gear-based torque biasing remains cost-competitive in mass-market segments.
- Sensor-Based Systems:Wheel-speed, accelerometer, and gyroscopic inputs feed control algorithms.
Hardware differentiation concentrates in mechanical systems; margin expansion favors software integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's torque vectoring trade flows reflect a structural deficit in electronic control modules, with Germany and the UK importing specialized semiconductors and sensor arrays while exporting integrated driveline systems to North American and Asian OEMs.
Germany
EMA safety standards mandate yaw-rate-responsive torque modulation in premium passenger vehicles, compressing development cycles for Stuttgart and Munich engineering centers. The EU Green Deal's powertrain electrification timelines redirect R&D spending from mechanical differentials toward dual-motor EV architectures. Wolfsburg anchors volume production for VW Group platforms where electronic torque distribution is becoming standard equipment.
United Kingdom
Corporate mobility procurement criteria elevate handling performance to primary fleet selection factors, concentrating demand in executive battery-electric segments. CE marking certification for automotive electronics extends supplier qualification cycles, favoring established tier-one relationships over new market entrants. The Midlands manufacturing corridor hosts Jaguar Land Rover and Aston Martin engineering facilities developing torque vectoring for performance variants.
France
F-Gas Regulation refrigerant phase-down timelines accelerate powertrain electrification roadmaps at Stellantis and Renault engineering centers. The EU AI Act's emerging compliance framework for autonomous vehicle systems creates uncertainty around torque control algorithm classification. Paris-Saclay automotive research clusters coordinate with Lyon-based supplier development programs for hybrid system integration.
Italy
Luxury sports car manufacturers in Modena and Maranello specify multi-clutch torque vectoring differentials as standard equipment for homologated performance variants. REACH chemical compliance for brake friction materials intersects with torque vectoring hardware sourcing decisions. Turin-based Stellantis engineering maintains legacy platform integration capabilities for mechanical all-wheel-drive systems serving export markets.
Poland
Central European automotive assembly expansion creates demand for localized torque vectoring module production serving VW Group and Stellantis facilities near Poznań and Gliwice. CSRD disclosure mandates favor suppliers with documented carbon footprint reduction in electrified drivetrain component sourcing. The country's engineering workforce development programs address embedded software talent scarcity for control algorithm development.
Europe Torque Vectoring Market Competitive Landscape
Concentration sits with integrated driveline providers that anchor premium OEM contracts through full-system capabilities rather than component supply. The supplier base organizes into three strategic archetypes: diversified automotive conglomerates with powertrain portfolios, specialized driveline engineering firms, and electronics-focused tier-one suppliers extending into chassis control. Competitive dynamics revolve around backward integration into semiconductor sourcing and geographic expansion into Central European manufacturing corridors to serve OEM assembly localization.
Within the diversified conglomerate tier, ZF Friedrichshafen AG and Continental AG exemplify full-system integrators leveraging sensor fusion and integrated driveline portfolios. BorgWarner Inc. occupies a position bridging mechanical heritage with electrified torque distribution architectures for hybrid platforms. These three German and US-based entities anchor the competitive structure, with Schaeffler AG and GKN Automotive representing specialized driveline engineering archetypes competing on clutch pack and torque transfer unit expertise.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| BorgWarner Inc. |
| Continental AG |
| Schaeffler AG |
| GKN Automotive |
| Bosch Group |
| Magna International Inc. |
| Haldex AB |
| Nexteer Automotive |
| Others |
Pricing and Supply Chain Analysis
Stuttgart-Munich-Wolfsburg engineering corridor capacity utilization above 85% anchors cost structures for torque vectoring module production, compressing supplier margins while elevating price floors for electronic control units serving German OEM platforms. CE marking certification timelines and semiconductor foundry allocation constraints concentrate pricing power with integrated tier-one suppliers possessing captive microcontroller sourcing.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for torque vectoring systems, with three-tier pricing structure across premium, standard, and economy levels differentiated by ISO 26262 functional safety certification grade and volume scale commitments. Price differentiation stems from electromagnetic compatibility testing burden and after-sales calibration service bundling. Cost compression in standard-tier electronic torque distribution modules is intensifying because foundry allocation competition with battery management systems constrains automotive-grade microcontroller supply. Fleet procurement managers at corporate mobility programs show lowest price sensitivity, prioritizing yaw-rate-responsive stability performance over per-unit cost.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for semiconductor wafers and rare-earth magnet arrays feeding clutch pack actuator production. Geographic supply concentration centers on Germany for integrated driveline systems, Taiwan for automotive microcontrollers, and China for rare-earth processing. Raw material dependencies rest on neodymium-iron-boron magnets, copper windings, and silicon carbide substrates. Single-source vulnerability in 300mm automotive-grade wafer supply creates structural risk exposure. Distribution runs through just-in-time sequences direct to Wolfsburg, Munich, and Stuttgart assembly plants with 48-hour replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded software expertise in vehicle dynamics modeling represents the critical capability gap constraining European torque vectoring development velocity, with engineering graduate pipeline output lagging dual-motor EV platform deployment timelines by 24-36 months.
For Market Incumbents: Compound sensor fusion capabilities by integrating torque vectoring control algorithms with ADAS domain controllers, defending against electronics-focused tier-one suppliers extending into chassis control. Prioritize backward integration into silicon carbide substrate sourcing to secure foundry allocation against battery management system competition. Expand Poznań and Gliwice manufacturing footprints to capture VW Group and Stellantis assembly localization in Central Europe. For New Entrants and Emerging Players: CE marking fast-track partnerships with established electromagnetic compatibility testing houses in Germany accelerate supplier qualification cycles by 8-12 months versus independent certification pathways. Target Poland-based torque vectoring module production for localized supply to Central European automotive corridors, penetrating through CSRD-aligned carbon footprint documentation that favors new suppliers with greenfield electrified drivetrain facilities. Pursue software licensing models for control algorithm IP rather than hardware module manufacturing to bypass capital-intensive clutch pack production. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized driveline engineering firms with clutch pack expertise and embedded software capabilities bridging mechanical heritage toward electrified architectures. Long-term viability hinges on 5-10 year dual-motor EV platform standardization trajectories at German OEMs. Acquisition target archetype: mid-cap suppliers with documented functional safety certification and established tier-one relationships. Monitor EU AI Act regulatory guidance on autonomous vehicle torque control algorithm classification as inflection indicator for compliance burden expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Migration of torque vectoring into centralized compute platforms dissolves hardware module boundaries at ZF and Continental. |
| Battery Supply Agreement | Dual-motor EV architectures inherently enable electronic torque distribution without mechanical differential hardware mass. |
| Geographic Manufacturing Footprint | Poland and Czech Republic assembly expansion creates localized module production demand serving VW Group facilities. |
| Platform Standardization | EMA yaw-rate-responsive stability mandates compress development cycles toward unified electronic torque distribution architectures. |
| Charging Infrastructure Partnership | Corporate fleet electrification elevates handling performance specifications in Netherlands and UK mobility procurement criteria. |
Research Methodology
A standing panel of OEM platform engineers, tier-one supplier procurement directors, aftermarket distributors, and embedded software architects provided ongoing calibration across primary interview cycles, combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC 10-K filings, and EU automotive electronics directive documentation. Bottom-up torque vectoring module shipment estimates triangulated against top-down electrified drivetrain investment disclosures from Stuttgart, Munich, and Wolfsburg engineering centers.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation modeled by propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from curve-fitting techniques applied to quarterly electrified platform deployment schedules and EMA safety standard implementation timelines. Industry-specific forecast inputs incorporated F-Gas Regulation phase-down schedules and CSRD disclosure mandate compliance patterns.
Underlying assumptions cover EU Green Deal electrification timeline adherence, semiconductor foundry allocation stability, and embedded software talent pipeline recovery, with deviation risk concentrated in EU AI Act regulatory uncertainty around autonomous vehicle torque control classification. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Carbon Fiber Composites Parts Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
Automotive Solenoid Market
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Alloys for Automotive Market
Automotive Components
Off-Highway Actuators Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Asia-Pacific Automotive Composites Market
Automotive Components
Automotive Door Module Market
Automotive Components
Global Automotive Plastic Bumper Market
Automotive Components
Automotive Steering Column Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Global Cylinder Deactivation System Market
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market