
 Automotive Glass Film Market | 2026-2036
Automotive Glass Film Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Glass Film Market Analysis
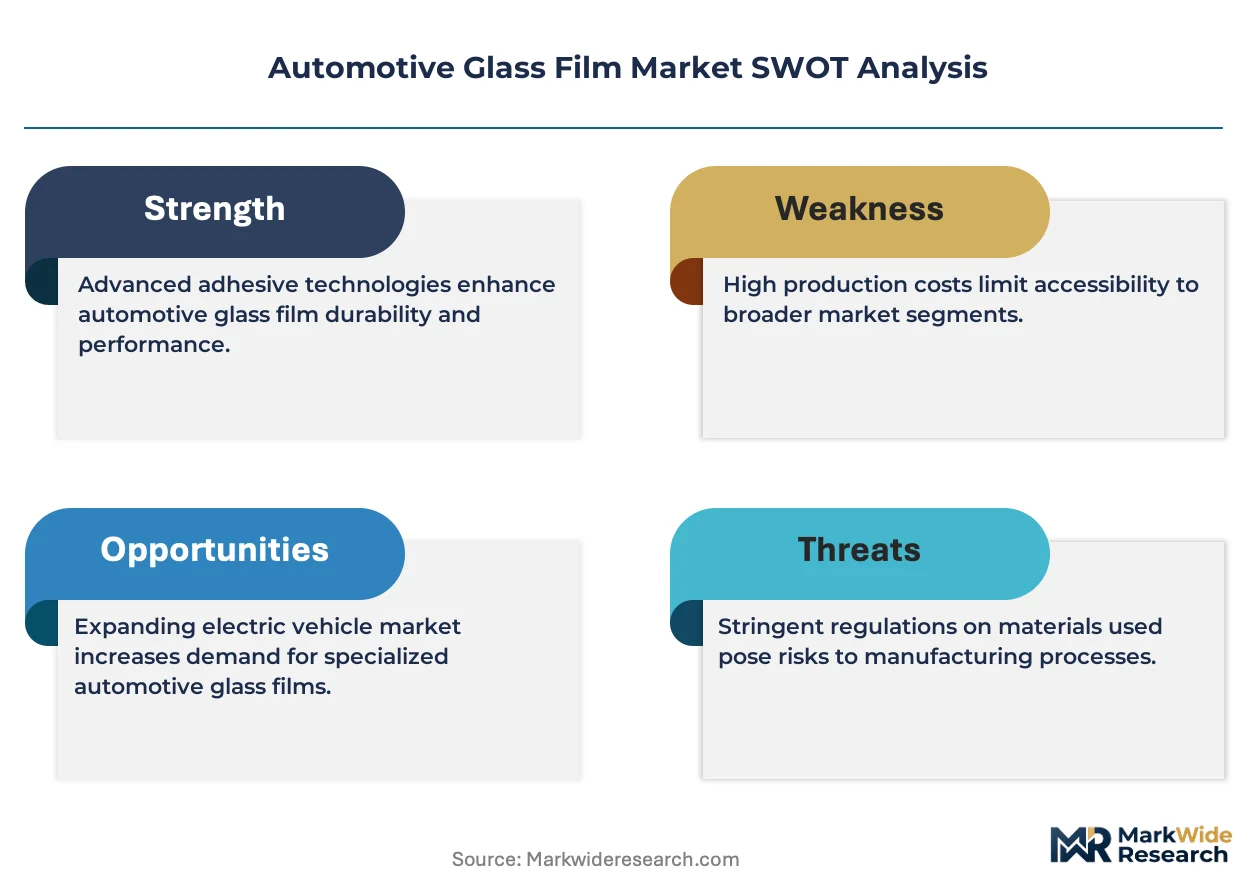
Fleet operators is redrawing procurement priorities across the Automotive Glass Film Market as commercial vehicle managers prioritize UV-blocking and shatter-resistant specifications over basic tinting. Eastman Chemical Company leverages its polyester manufacturing scale to supply OEM-grade ceramic films with consistent optical clarity. Saint-Gobain anchors European demand through integrated glass-film systems designed for premium vehicle platforms. XPEL specializes in paint protection and window film technologies that compete on warranty length and installation network density.
Automotive glass film comprises multi-layer polymer laminates, typically polyester substrates coated with metalized or ceramic infrared-rejecting compounds, adhesive-bonded to vehicle glazing for solar control, safety retention, or aesthetic modification. Ceramic films incorporate nanoscale titania or indium tin oxide particles to block infrared transmission while preserving radio-frequency transparency for GPS and cellular systems. Security film applications command premium positioning due to laminated construction that retains glass fragments during impact, while decorative film remains a margin-diluted segment driven by aftermarket customization trends. Professional installation dominates value capture compared with DIY channels, as warranty validity and optical precision requirements favor certified technician networks.
The US National Highway Traffic Safety Administration sets visible light transmission minimums that directly constrain tint film formulations sold for windshield and front-side window applications. Europes F-Gas Regulation and REACH framework restrict solvent-based adhesive chemistries, compelling suppliers to validate waterborne or hot-melt alternatives. Stakeholders must monitor evolving electromagnetic compatibility standards for ceramic films as vehicle-to-everything communication modules proliferate across OEM platforms.
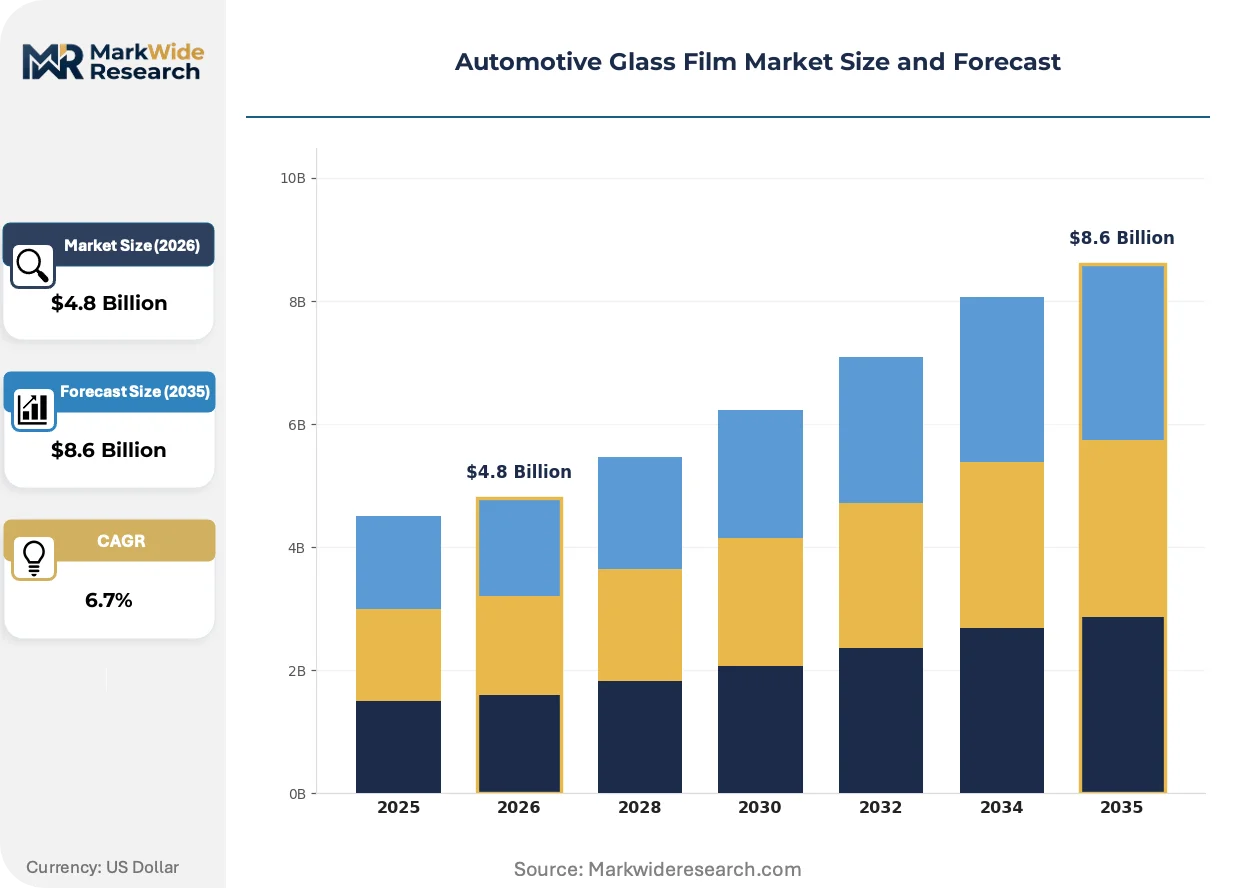
Market Dynamics
EU REACH compliance and F-Gas Regulation are forcing manufacturers to abandon solvent-based adhesive chemistries, compressing formulation timelines while elevating validation costs for waterborne and hot-melt alternatives across European supply chains.
Growth Catalysts
- Fleet operator procurement:Commercial vehicle managers now specify UV-blocking and shatter-resistant ceramic films as standard equipment, displacing basic tinting across logistics and ride-hailing fleets.
- REACH framework expansion:Restrictions on volatile organic compounds in adhesives are accelerating solvent-free formulation adoption, creating first-mover advantages for compliant suppliers.
- Smart glass integration:German OEMs are embedding electrochromic and thermochromic film layers directly into premium vehicle glazing at the factory level.
Market Restraints
- Petrochemical input volatility:Polyester substrate and metalized coating feedstock costs fluctuate with crude oil derivatives, compressing margin stability for film laminators.
- Optical clarity limitations:Ceramic nanoparticle dispersion technology faces yield constraints at nanoscale titania and indium tin oxide concentrations required for infrared rejection without signal interference.
- NHTSA visible light transmission floors:Federal minimums for windshield and front-side window applications cap tint depth, constraining premium product differentiation in the US market.
Strategic Opportunities
- Underpenetrated Indian aftermarket:Rising vehicle ownership and extreme solar exposure create addressable demand for ceramic UV-rejection films in Delhi, Mumbai, and Bangalore metro corridors.
- Vehicle-to-everything compatibility:Ceramic formulations preserving GPS and cellular signal integrity position suppliers for OEM integration as connected vehicle architectures proliferate.
- Certified installer network expansion:Professional warranty channels capture value unavailable to DIY segments, favoring franchised technician training programs in suburban and secondary markets.
Industry Challenges
- Electromagnetic compatibility certification:Ceramic films must validate non-interference with 5G and V2X communication modules, extending validation cycles with OEM platform teams.
- Skilled installation scarcity:Precision application of multi-layer laminates demands trained technicians; workforce gaps in secondary markets limit service coverage expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Glass Film Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tint Film, Security Film, Ceramic Film, Decorative Film Application: Car Windows, Windshields, Sunroofs, Lamps End User: OEMs, Aftermarket Installers, Fleet Operators, Dealerships Installation Type: DIY, Professional, Mobile, In-Store |
| Companies Covered | 3M Company, Eastman Chemical Company, Saint-Gobain, Avery Dennison Corporation, Madico, Inc., Johnson Window Films, Inc., XPEL, Inc., Toray Industries, Inc., Garware Suncontrol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Glass Film Market Emerging Trajectories
Formulation chemistry and installation channel structures are diverging simultaneously, with regulatory pressure on adhesives running parallel to consolidation in professional service networks.
Ceramic nanocomposite technology is bifurcating the performance segment. Nanoscale titania and indium tin oxide particles block infrared transmission while preserving radio-frequency transparency. German and Japanese OEMs are specifying these formulations for flagship electric vehicle platforms. The technology is bifurcating the market into signal-compatible premium tiers and metalized legacy products facing obsolescence in connected vehicle architectures.
Europe's F-Gas Regulation and REACH framework are eliminating solvent-based adhesive chemistries from approved formulations. Manufacturers must validate waterborne and hot-melt alternatives through accelerated aging and optical clarity testing. German film laminators and their supply base face the most compressed compliance timelines, with 2025-2026 certification deadlines forcing portfolio rationalization.
Fleet procurement teams are consolidating vendor relationships around integrated supply agreements. Commercial vehicle operators now bundle ceramic film specification with maintenance contracts and warranty coverage, displacing spot aftermarket purchases. This concentration is most visible in German logistics corridors and US ride-hailing hubs, where total-cost-of-ownership calculations favor single-source film and installation partnerships.
Automotive Glass Film Market Segmentation
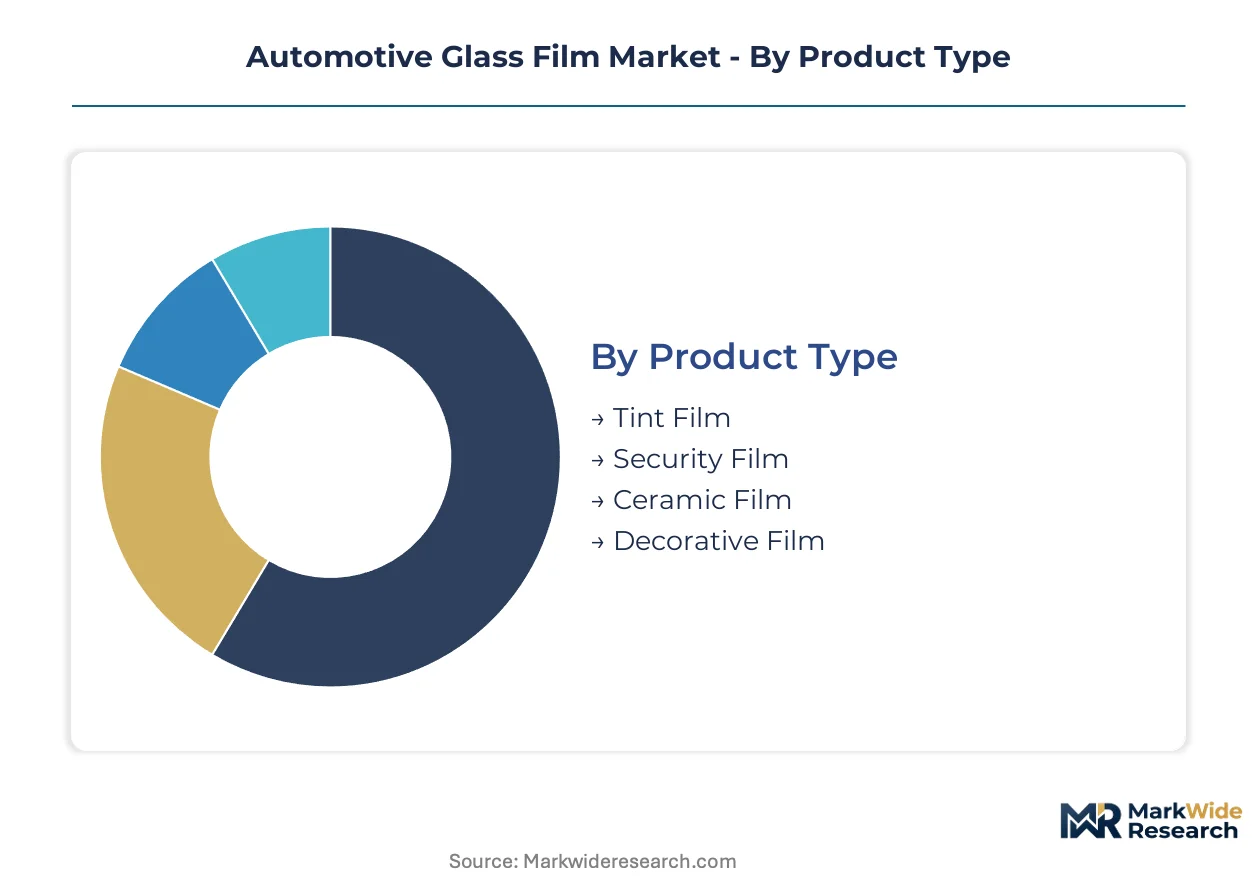
Automotive glass film segmentation reveals divergent margin structures across product chemistry, installation channel, and customer procurement behavior. Technology leadership in ceramic nanocomposites and security laminates commands premium positioning, while commoditized tint films compete on distribution density.
Product Type:
Margin pools concentrate in ceramic and security formulations where OEM validation and fleet procurement create pricing power, while decorative films face margin compression from aftermarket customization trends.
- Ceramic Film:Multi-layer polyester substrates incorporate nanoscale titania and indium tin oxide particles to block infrared transmission while preserving GPS and cellular signal integrity. German and Japanese OEMs specify these formulations for flagship electric vehicle platforms, displacing metalized legacy products in connected vehicle architectures.
- Security Film:Laminated polymer construction retains glass fragments during impact, commanding premium positioning in commercial fleet and armored vehicle specifications. EU safety regulations and insurance premium reductions for shatter-resistant glazing accelerate procurement across logistics corridors.
- Tint Film:Basic dyed or metalized polyester laminates for solar control and aesthetic modification face NHTSA visible light transmission minimums that constrain formulation depth in US windshield applications.
- Decorative Film:Color-shifting and patterned films serve aftermarket customization demand with limited OEM integration and compressed margins from DIY channel competition.
Ceramic film holds installed capacity. Security film is rotating up the share rankings.
Application:
Volume concentration follows vehicle glazing surface area, with side windows and windshields dominating unit economics while sunroofs and lamps represent emerging specification targets.
- Car Windows:Side and rear window applications constitute the primary volume channel, with ceramic formulations displacing dyed films as fleet operators standardize UV-blocking specifications.
- Windshields:Regulatory constraints on visible light transmission limit tint depth, creating demand for clear infrared-rejecting ceramic films that comply with NHTSA minimums while reducing cabin thermal load.
- Sunroofs:Expanding glass roof penetration in premium electric vehicles drives specification of thermochromic and electrochromic film layers for dynamic solar control.
- Lamps:Protective film applications for headlight and taillight assemblies remain a niche segment with limited standardization across OEM platforms.
Car windows capture the volume base. Sunroofs are gaining specification fastest.
End User:
Procurement authority determines margin structure, with OEM direct supply agreements and fleet consolidated purchasing extracting volume discounts while aftermarket channels preserve service premiums.
- Fleet Operators:Commercial vehicle managers bundle ceramic film specification with maintenance contracts and warranty coverage, displacing spot aftermarket purchases through total-cost-of-ownership calculations.
- OEMs:Factory integration of smart glass films at the glazing level requires electromagnetic compatibility validation with vehicle communication architectures, extending supplier qualification timelines.
- Aftermarket Installers:Certified technician networks capture value unavailable to DIY segments through warranty validity and optical precision guarantees.
- Dealerships:New vehicle add-on sales of window film compete with independent installers on convenience and financing integration.
Fleet operators concentrate purchasing leverage. Aftermarket installers are defending service premiums.
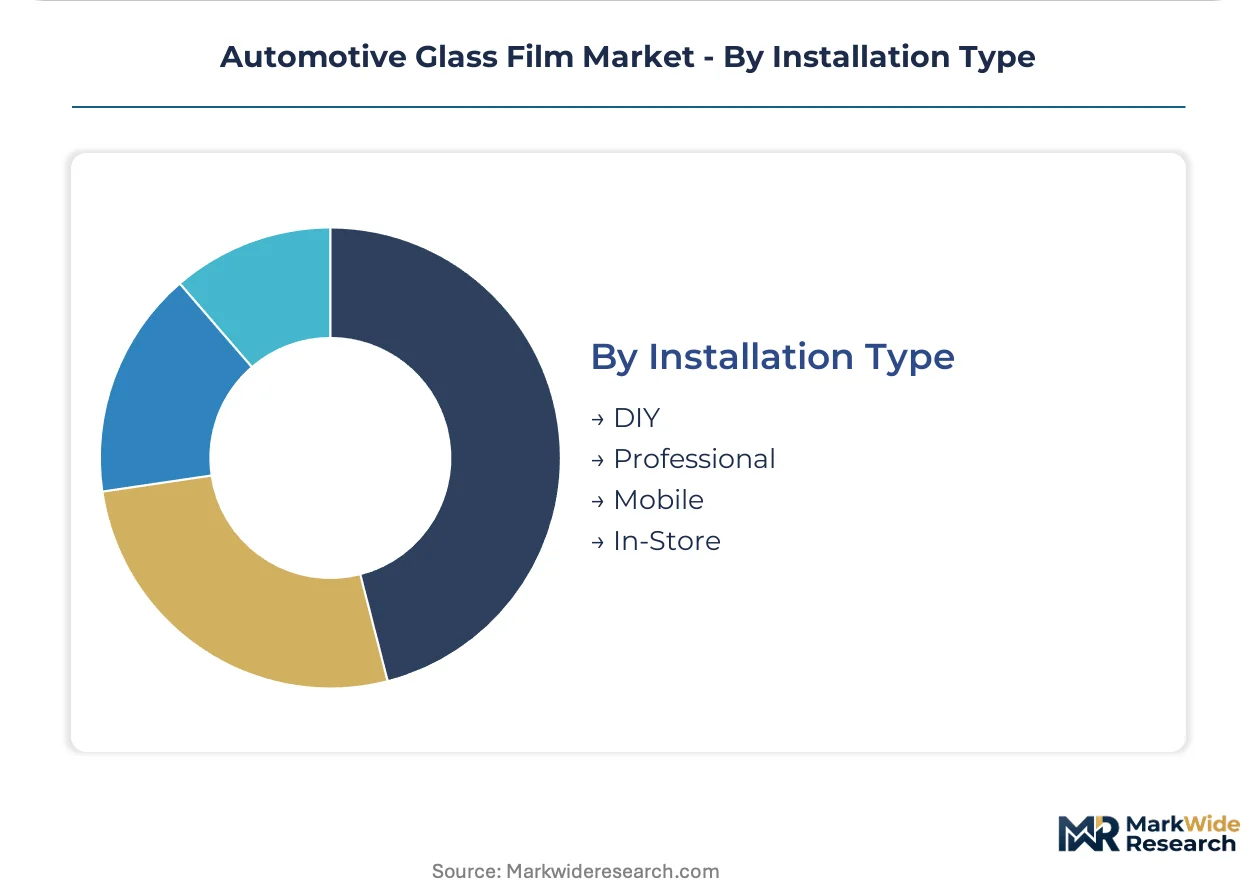
Installation Type:
Channel structure bifurcates between professional precision application commanding warranty premiums and convenience-oriented mobile services capturing time-sensitive demand.
- Professional:Fixed-location certified technician networks dominate value capture through warranty validity, optical clarity guarantees, and complex multi-layer laminate application.
- Mobile:On-site installation services address fleet downtime constraints and consumer convenience preferences, expanding coverage in suburban and secondary markets where fixed facilities are scarce.
- In-Store:Retail automotive service chains bundle film installation with maintenance appointments, competing on appointment density and cross-selling integration.
- DIY:Pre-cut film kits and liquid application products serve price-sensitive segments with limited warranty protection and higher defect rates.
Professional installation holds the margin base. Mobile services are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's petrochemical throughput underwrites Europe's polyester substrate supply chains for automotive glass film manufacturing. German industrial clusters along the Rhine corridor process these feedstocks into ceramic nanocomposite formulations.
Germany
OEM integration of electrochromic film layers drives demand from Stuttgart and Munich premium vehicle platforms. The F-Gas Regulation and REACH framework restrict solvent-based adhesive chemistries, forcing suppliers toward waterborne alternatives. The Rhine-Main industrial corridor concentrates film laminator facilities facing compressed 2025-2026 certification deadlines.
United States
Fleet procurement consolidation across logistics and ride-hailing hubs standardizes ceramic UV-blocking specifications. NHTSA visible light transmission minimums constrain tint depth for windshield applications. The Dallas-Fort Worth metroplex anchors aftermarket installer network expansion through franchised technician training programs.
China
Domestic electric vehicle production scales ceramic film specification for signal-compatible glazing across Ningbo and Shanghai manufacturing bases. MIIT electromagnetic compatibility standards govern V2X module interference testing. The Yangtze River Delta concentrates polyester substrate and metalized coating capacity serving both domestic OEMs and export laminators.
Japan
Flagship electric vehicle platforms from Toyota and Nissan specify nanoscale titania formulations for infrared rejection without GPS degradation. METI industrial standards guide ceramic nanoparticle dispersion quality thresholds. The Nagoya-Tokyo corridor hosts integrated glass-film system suppliers qualified for OEM direct supply agreements.
India
Extreme solar exposure in Delhi, Mumbai, and Bangalore metro corridors creates aftermarket demand for ceramic UV-rejection films as vehicle ownership expands. BIS quality certification requirements shape import and domestic manufacturing compliance. The Chennai-Bangalore industrial belt attracts film laminators targeting underpenetrated passenger vehicle and commercial fleet segments.
Automotive Glass Film Market Vendor Landscape
Listed leaders compete with private specialists across capital access and formulation agility. The vendor base spans multinational chemical conglomerates with polyester manufacturing scale, integrated glass systems suppliers, and dedicated film technology companies. Three archetypes dominate: substrate-integrated chemical producers, glazing-system integrators, and application-technology specialists. Capacity expansion in ceramic nanocomposite lines and certified installer network franchising represent the dominant competitive vectors.
Among chemical-sector fabricators, Eastman Chemical Company and Toray Industries occupy positions anchored by polyester substrate production scale. Saint-Gobain exemplifies the glazing-system integrator archetype through European premium platform relationships. XPEL represents the application-technology specialist tier competing on warranty infrastructure and installation network density rather than upstream material production.
| Leading Market Players |
|---|
| 3M Company |
| Eastman Chemical Company |
| Saint-Gobain |
| Avery Dennison Corporation |
| Madico, Inc. |
| Johnson Window Films, Inc. |
| XPEL, Inc. |
| Toray Industries, Inc. |
| Garware Suncontrol |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German OEMs and polyester substrate suppliers lock in feedstock access and stabilize unit cost visibility across ceramic nanocomposite formulation cycles. Fleet procurement consolidation amplifies volume-discount leverage, compressing spot-market premiums for non-contracted distributors.
Pricing Analysis
Volume-discount tiering structures separate OEM direct supply agreements from aftermarket installer spot purchases, with fleet bundled contracts capturing the steepest rebates. Price differentiation hinges on REACH compliance certification and ceramic nanoparticle concentration grade, with signal-compatible formulations commanding premiums over metalized legacy products. Cost compression in decorative tint tiers is intensifying due to DIY channel expansion, while security laminates show pricing resilience. Aftermarket installers exhibit highest price sensitivity, whereas armored vehicle and premium EV platforms demonstrate inelastic demand for validated ceramic specifications.
Supply Chain Analysis
Rotterdam petrochemical throughput underwrites European polyester substrate flows, creating a logistics chokepoint for German and Benelux film laminators. Manufacturing gravity centers on Germany, China, and Japan, with nanoscale titania and indium tin oxide particle supply resting on Japanese chemical specialist production. Single-source vulnerability concentrates in ceramic nanoparticle dispersion equipment, where German and Japanese toolmakers dominate. Distribution runs through certified installer networks and OEM direct supply channels, with mobile service franchises expanding coverage in undersupplied secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across installation channel structures creates niche opportunities as fleet procurement consolidation and DIY channel expansion simultaneously reshape buyer archetypes and service expectations.
For Market Incumbents: Consolidate certified installer network density in suburban corridors where mobile service penetration remains thin. Backward integration into ceramic nanoparticle dispersion capabilities reduces exposure to Japanese equipment lead times. Prioritize REACH-compliant adhesive formulation portfolios to defend OEM qualification status against emerging waterborne specialists. For New Entrants and Emerging Players: Lead with mobile installation franchises targeting Indian metro corridors where fixed-location coverage gaps persist. The underpenetrated Chennai-Bangalore industrial belt offers white-space for ceramic UV-rejection film specification. Bundle BIS certification support with local laminator partnerships to accelerate market access. For Investors and Strategic Acquirers: Capital is best deployed toward application-technology specialists with dense warranty infrastructure rather than substrate-integrated chemical conglomerates. Long-term viability favors installers with proprietary technician training platforms and fleet maintenance contract integration. Watch for inflection when OEM smart glass film integration rates cross threshold penetration in German premium EV platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Nanoparticle Dispersion Capacity Expansion | Captures margin pool from Japanese equipment bottlenecks while securing OEM qualification timelines. |
| REACH-Compliant Adhesive Certification Investment | Preserves European market access as F-Gas Regulation eliminates solvent-based alternatives. |
| Certified Installer Network Franchising | Builds defensive moats against mobile service entrants in suburban and secondary markets. |
| Fleet Maintenance Contract Integration | Locks in recurring revenue streams as logistics operators consolidate vendor relationships. |
| Vehicle-to-Everything Compatibility Validation | Positions suppliers for OEM smart glass integration as 5G and V2X architectures proliferate. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC chemical sector filings, and OEM procurement disclosures. Interviews with Tier 1 supplier procurement leads, aftermarket distributor operations heads, and ceramic nanoparticle R&D directors informed demand-side validation. Top-down triangulation against vehicle production databases and bottom-up build from installer network capacity estimates anchored volume projections.
Segmentation dimensions modeled span product chemistry, installation channel, and end-user procurement authority across the projection horizon. CAGRs derived from regression analysis of historical pricing elasticities and fleet penetration assumptions. Forecast inputs incorporated REACH compliance cost trajectories and ceramic film specification rates in German and Japanese electric vehicle platforms.
The analysis sits within stated boundaries; outcomes outside sustained OEM smart glass integration momentum or abrupt petrochemical feedstock disruption would require recalibration. Practitioners should keep alternative scenarios live as F-Gas Regulation enforcement timelines and V2X electromagnetic compatibility standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Brackets Market
Automotive Components
Egypt Automotive Lubricants Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Global Automotive Damper Control Unit Market
Automotive Components
Automotive Buffers Market
Automotive Components
Africa Automotive Lubricants Market
Automotive Components
Global Automotive Water Separation Systems Market
Automotive Components
Automotive Subframe Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
Asia-Pacific Automotive Composites Market
Automotive Components
Automotive Part Cleaners and Degreasers Market
Automotive Components
Global Automotive Aluminum Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Exhaust Components Aftermarket Market