
 Automotive Comfort Actuators Market | 2026-2036
Automotive Comfort Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Comfort Actuators Market Outlook
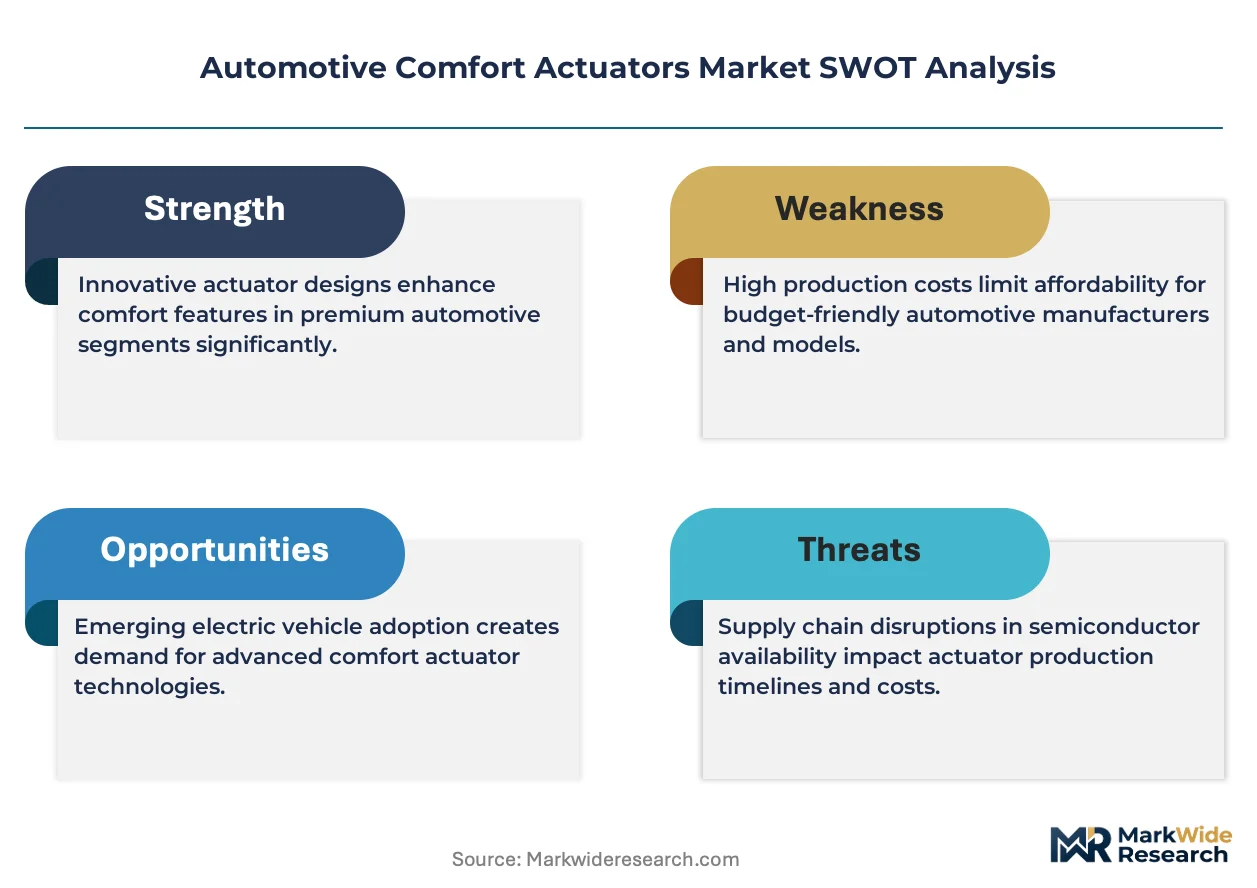
ISO 26262 functional safety certification is bifurcating the supplier landscape into qualified tier-1 incumbents and excluded aspirants. Robert Bosch GmbH leverages its in-house semiconductor and mechatronics depth to control high-integrity seat and climate actuator lines. Denso Corporation anchors Asian OEM supply through captive production of compact electric motors for lumbar and power seat modules. Continental AG competes on integrated cabin domain architectures that bundle multiple comfort actuators under single electronic control.
Automotive comfort actuators are electromechanical, pneumatic, or hydraulic devices that convert control signals into precise mechanical motion for seat positioning, climate venting, and ergonomic support, typically operating at voltages from 12V to 48V with positional feedback via Hall-effect sensors. Their primary purpose is to automate cabin environmental and postural adjustments without driver intervention. Electric actuators now dominate new program awards as OEMs eliminate pneumatic plumbing weight and hydraulic fluid maintenance from passenger vehicles. Heated seats and power seats command the largest revenue pools, though lumbar support modules generate higher per-unit margins due to specialized motor and memory-control content. Climate control actuators represent the fastest-expanding segment, driven by multi-zone HVAC architectures that require independent blend-door and vent-positioning motors per seating row.
Europe's EMA enforces MDR-adjacent reliability expectations for long-life automotive electromechanical components, while REACH restricts certain flame retardants and lubricants used in actuator housings and gear trains. China's MIIT mandates GB-standard electromagnetic compatibility testing that gates market access for imported actuator assemblies. India's BIS certification requirements for automotive electrical subcomponents add compliance layers for suppliers targeting Maruti Suzuki and Tata Motors programs. Stakeholders must monitor how 48V electrical architecture migration and software-defined vehicle platforms reshape actuator control topologies and supplier value capture.
Market Dynamics
Electric actuator architectures are displacing pneumatic and hydraulic systems as OEMs eliminate fluid maintenance and plumbing weight from passenger vehicle programs. This electrification push, reinforced by China's MIIT dual carbon mandates and Europe's REACH substance restrictions, is compressing supplier lead times while expanding certification requirements for functional safety compliance.
Growth Catalysts
- NEV mandate acceleration:China's MIIT dual carbon goals enforce electric actuator substitution across joint-venture and domestic OEM production lines, eliminating pneumatic infrastructure from new vehicle platforms.
- Multi-zone HVAC proliferation:Independent climate control per seating row requires dedicated blend-door and vent-positioning motors, expanding actuator counts per vehicle.
- Memory-enabled personalization:Power seat modules with positional recall functions command premium positioning in luxury passenger vehicle segments.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings destabilize motor cost structures for high-torque seat actuators.
- Tier-1 supply concentration:Qualified incumbents with ISO 26262 certification control program awards, excluding aspirant suppliers from high-integrity lines.
- Hydraulic legacy entrenchment:Commercial vehicle segments retain hydraulic actuation for extreme load-bearing seat mechanisms, slowing electric conversion.
Strategic Opportunities
- 48V architecture migration:Mild-hybrid electrical systems enable higher-power seat and climate actuators without full high-voltage redesign.
- Software-defined vehicle integration:Actuator control migration to domain controllers creates openings for suppliers with embedded software capabilities.
- India BIS certification pathway:Formal compliance with Bureau of Indian Standards unlocks procurement access to Maruti Suzuki and Tata Motors scaling programs.
Industry Challenges
- ISO 26262 functional safety certification timelines:ASIL-rated development cycles extend 18-24 months, gating supplier entry to safety-critical seat and steering column actuator lines.
- Legacy pneumatic system integration friction:Retrofit electric actuators into existing vehicle architectures requires custom bracketry and control signal translation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Comfort Actuators Market |
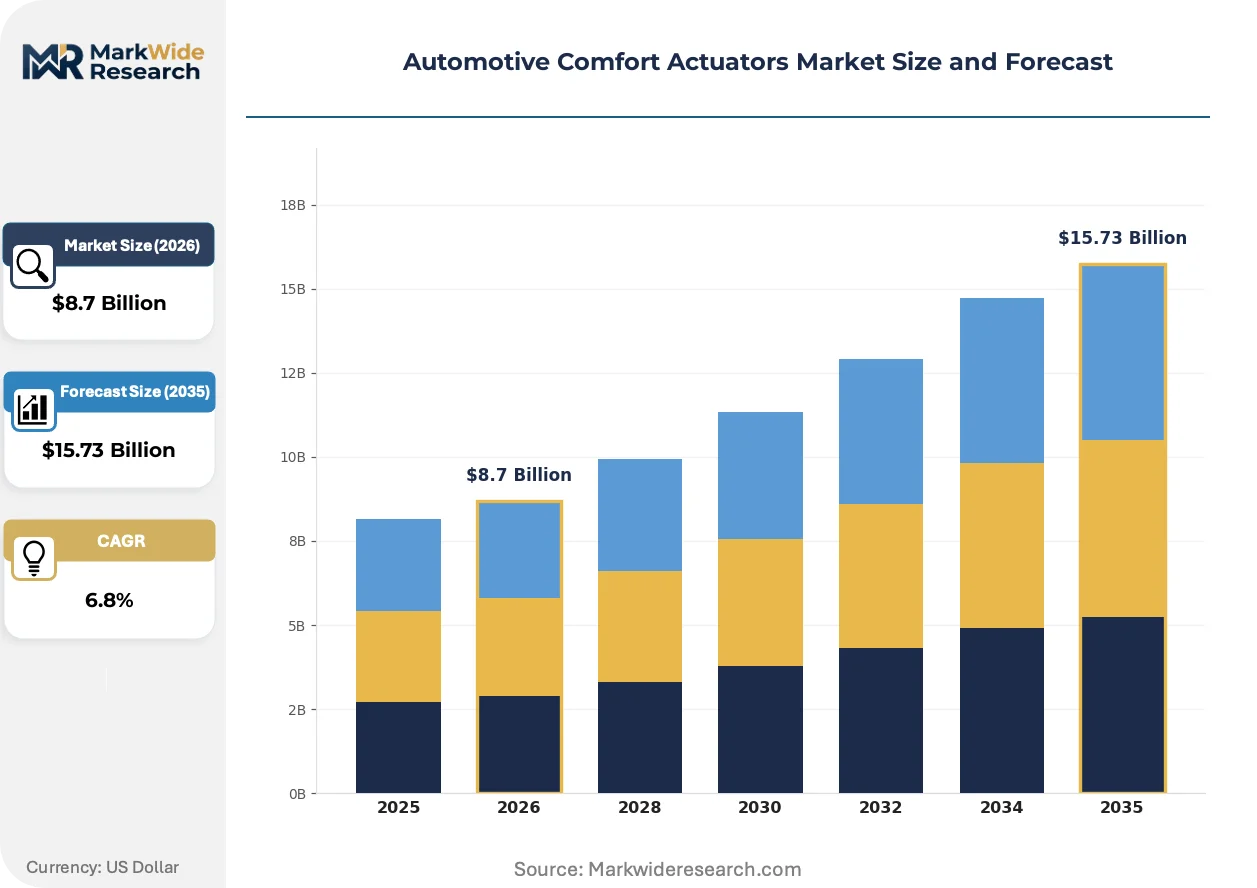
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heated Seats, Power Seats, Lumbar Support, Climate Control Technology: Electric Actuators, Pneumatic Actuators, Hydraulic Actuators, Mechanical Actuators End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Feature: Adjustability, Comfort Enhancements, Temperature Regulation, Vibration Control |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, Johnson Electric Holdings Limited, HELLA GmbH & Co. KGaA, Valeo SE, ZF Friedrichshafen AG, Mitsubishi Electric Corporation, Aisin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Comfort Actuators Market Strategic Shifts
Actuator control topologies are migrating from discrete motor drivers toward integrated cabin domain architectures that consolidate multiple comfort functions under centralized electronic management. This consolidation demands new supplier competencies in embedded software and systems integration.
Brushless DC motor technology with integrated Hall-effect position sensing is bifurcating the component supply base between semiconductor-capable tier-1s and commodity motor assemblers. Luxury OEMs specify these motors for lumbar and power seat modules requiring precise positional feedback. The technology is bifurcating value capture toward suppliers with in-house mechatronics and ASIL-rated control firmware.
Europe's EMA enforces MDR-adjacent reliability expectations for long-life electromechanical components used in safety-critical seating applications. REACH restrictions on specific flame retardants and lubricants force reformulation of actuator housings and gear train materials. German KBA type-approval processes now require documented fatigue testing for seat actuators in commercial vehicle applications.
Chinese OEM procurement patterns favor domestic actuator suppliers with captive semiconductor sourcing and GB-standard electromagnetic compatibility pre-certification. Joint ventures in the Yangtze River Delta automotive cluster consolidate comfort feature procurement under single-source agreements with tier-1s offering localized production and rapid iteration cycles. This concentration rewards suppliers with manufacturing presence in Jiangsu and Zhejiang provinces.
Automotive Comfort Actuators Market Segmentation
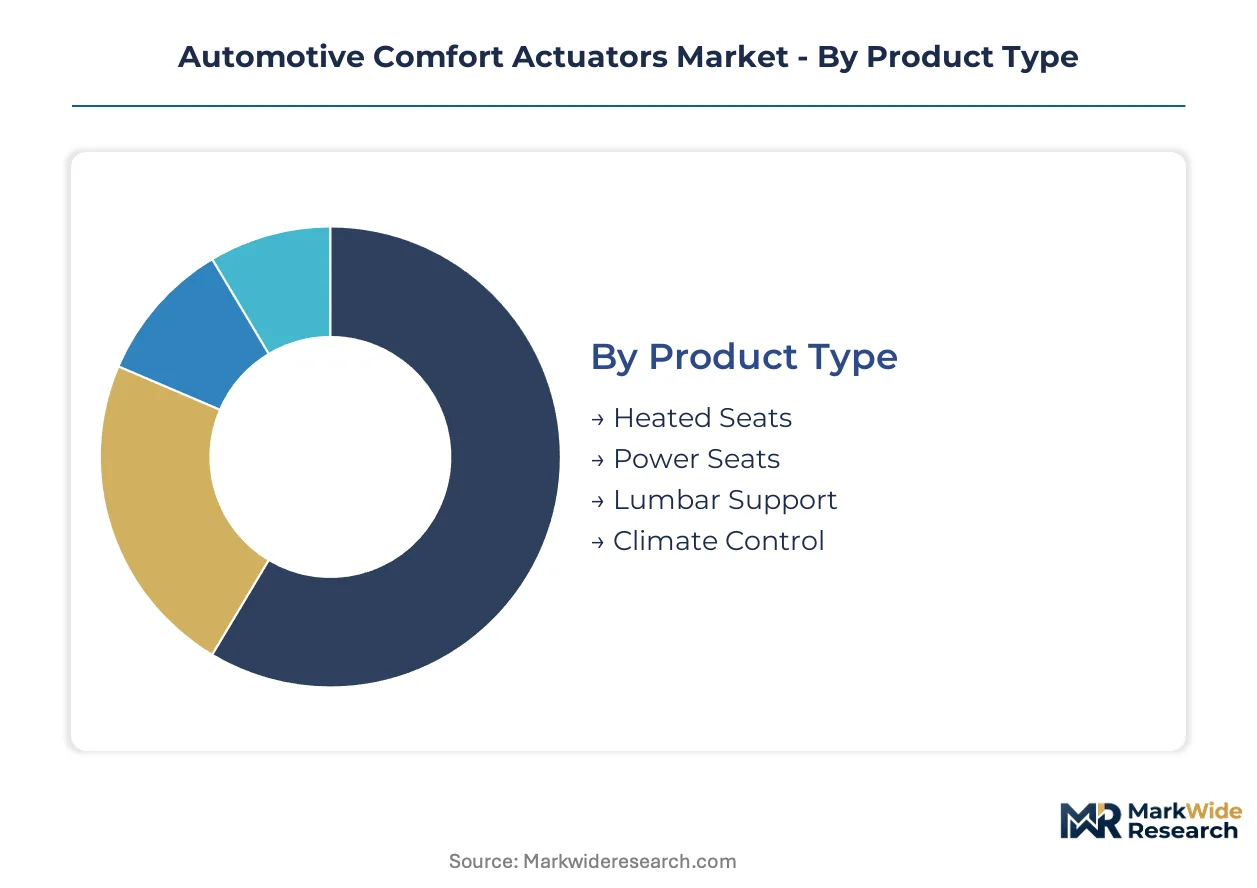
Automotive comfort actuators segment across multiple dimensions that determine supplier strategy, from electromechanical architecture choices to the channel through which components reach vehicle platforms. Understanding these divisions reveals where value concentrates and which technical specifications gate market access.
Product Type:
Margin pools concentrate in modules requiring precision motor control and memory-position firmware, while commodity heating elements compete on scale.
- Heated Seats:Resistive heating elements integrated into seat cushions and backrests, typically drawing 12V-48V through temperature-regulating control modules. Demand concentrates in North American and European cold-climate markets where OEMs bundle this feature across mid-trim passenger vehicles, though ceramic PTC heater variants command premium positioning for faster warm-up cycles.
- Power Seats:Multi-motor assemblies enabling fore-aft, height, tilt, and recline adjustments with optional memory recall functions. Luxury passenger vehicle manufacturers in Germany and Japan specify these modules with Hall-effect position sensing, creating margin concentration for suppliers with ASIL-rated control firmware and in-house mechatronics capabilities.
- Lumbar Support:Inflatable bladder or motorized arch systems providing ergonomic lower-back support.
- Climate Control:Blend-door and vent-positioning motors enabling multi-zone HVAC distribution.
The dominant share belongs to Power Seats, while Climate Control is closing the gap fastest.
Technology:
Electrification trajectories diverge sharply by vehicle class, with passenger platforms eliminating fluid-based systems faster than commercial applications.
- Electric Actuators:Brushless DC motors with integrated position sensing and electronic commutation, operating at 12V-48V. These systems displace pneumatic and hydraulic alternatives across China's MIIT-regulated NEV production lines, where dual carbon mandates accelerate electric substitution in joint-venture and domestic OEM programs.
- Pneumatic Actuators:Compressed-air systems using diaphragm or piston mechanisms for seat adjustment. Legacy installations persist in commercial vehicle segments where extreme load-bearing requirements and existing air-brake infrastructure sustain demand, though new program awards dwindle outside specialty applications.
- Hydraulic Actuators:Fluid-pressure systems for heavy-duty seat mechanisms.
- Mechanical Actuators:Manual lever and cable systems without powered assistance.
Electric Actuators now capture the majority of new program awards, while Hydraulic systems retain defensive positions in heavy-duty segments.
End User:
Channel structure determines certification burdens and design-in cycles, with direct OEM relationships requiring the longest qualification timelines.
- OEMs:Vehicle manufacturers specifying actuator modules directly for in-house seat and climate system integration. German KBA type-approval processes and ISO 26262 ASIL ratings gate entry to safety-critical seating applications, favoring incumbent tier-1s with documented fatigue testing and functional safety certification.
- Tier-1 Suppliers:Seating and HVAC system integrators procuring actuators for assembly into complete modules. These intermediaries consolidate procurement in China's Yangtze River Delta automotive cluster, where joint ventures favor single-source agreements with suppliers offering localized production and GB-standard electromagnetic compatibility pre-certification.
- Aftermarket Providers:Independent distributors serving vehicle modification and repair channels.
- Vehicle Assemblers:Contract manufacturers and kit assembly operations.
Tier-1 Suppliers handle the largest procurement volumes, while OEM direct relationships yield the highest per-unit margins.
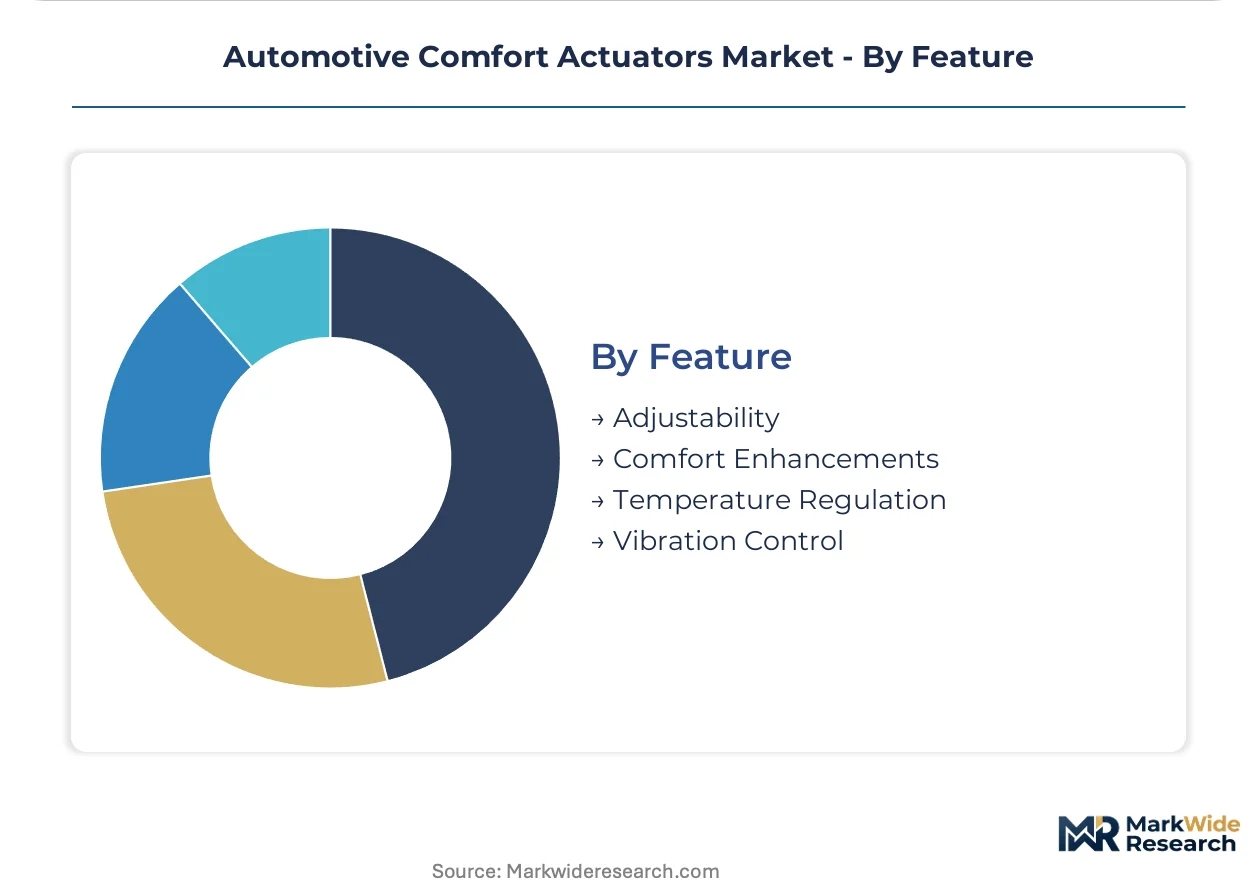
Feature:
Functional differentiation separates premium program wins from commodity supply, with software-enabled capabilities expanding value capture.
- Adjustability:Positional range of motion across multiple axes including lumbar, thigh extension, and headrest positioning. Multi-axis modules with memory recall concentrate demand in luxury segments where BMW, Mercedes-Benz, and Lexus specify 16-way or 20-way adjustable seats as competitive differentiators.
- Comfort Enhancements:Massage functions, ventilation fans, and pressure distribution systems. These features expand actuator counts per seat while requiring integration with cabin domain controllers, creating openings for suppliers with embedded software competencies as software-defined vehicle architectures mature.
- Temperature Regulation:Heating and cooling distribution management.
- Vibration Control:Active damping and road isolation systems.
Adjustability claims the largest installed base, while Comfort Enhancements demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT dual carbon mandates and NEV production quotas are redrawing procurement geography for electric actuator systems. Germany's KBA type-approval requirements and REACH substance restrictions impose parallel compliance burdens on European supply chains.
China
Domestic OEMs and joint ventures in the Yangtze River Delta automotive cluster are scaling comfort feature procurement for NEV platforms. MIIT mandates enforce electric actuator substitution, eliminating pneumatic infrastructure from new vehicle programs. Zhejiang and Jiangsu provinces host concentrated tier-1 production serving BYD, NIO, and Volkswagen Anhui.
Germany
Luxury passenger vehicle manufacturers specify 16-way and 20-way adjustable seat modules with ASIL-rated control firmware. KBA type-approval processes require documented fatigue testing for safety-critical seating applications. Baden-Württemberg's Stuttgart region anchors Continental AG and Robert Bosch GmbH mechatronics operations.
United States
Heated seat demand concentrates in cold-climate markets where OEMs bundle thermal comfort across mid-trim vehicles. NHTSA safety standards govern seat structure integrity, indirectly affecting actuator mounting specifications. Michigan's Detroit-Warren corridor hosts seating system integrators supplying Ford, General Motors, and Stellantis.
Japan
Denso Corporation and Aisin Corporation anchor Asian OEM supply through captive production of compact electric motors. METI industrial policy supports domestic semiconductor and mechatronics capabilities for automotive applications. Aichi Prefecture's Nagoya-Toyota corridor concentrates tier-1 actuator manufacturing for Toyota and Honda.
India
Maruti Suzuki and Tata Motors are scaling comfort feature procurement as passenger vehicle penetration rises. BIS certification requirements for automotive electrical subcomponents add compliance layers for imported actuator assemblies. Gujarat's Sanand automotive cluster and Tamil Nadu's Sriperumbudur corridor host expanding seating system operations.
Automotive Comfort Actuators Market Competitive Environment
Player mix skews toward diversified automotive tier-1s with in-house mechatronics and semiconductor capabilities. The supplier landscape bifurcates between ISO 26262-qualified incumbents controlling safety-critical program awards and excluded aspirants limited to non-ASIL applications. Two strategic archetypes dominate: integrated cabin domain architects bundling multiple actuators under centralized control, and specialized motor fabricators supplying discrete components to system integrators. Competitive moves center on embedded software competency acquisition and 48V electrical architecture readiness.
Among diversified German automotive suppliers, Continental AG and Robert Bosch GmbH occupy positions as integrated domain architects, while Denso Corporation represents the Asian captive-production archetype. These three exemplify how functional safety certification and in-house semiconductor depth concentrate program control among established tier-1s with documented fatigue testing and ASIL-rated development cycles.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| Johnson Electric Holdings Limited |
| HELLA GmbH & Co. KGaA |
| Valeo SE |
| ZF Friedrichshafen AG |
| Mitsubishi Electric Corporation |
| Aisin Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at China's Yangtze River Delta automotive cluster shapes both supply concentration and price floors for electric actuator modules. Joint-venture procurement consolidation under single-source agreements compresses supplier margins while rewarding tier-1s with localized semiconductor sourcing and GB-standard electromagnetic compatibility pre-certification.
Pricing Analysis
ISO 26262 functional safety certification creates the primary spread between ASIL-qualified tier-1 incumbents and excluded commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects firmware sophistication, motor torque density, and memory-control content. Price erosion runs through non-ASIL heating element segments where ceramic PTC heater variants compete on manufacturing scale. OEM direct relationships show lowest price sensitivity; aftermarket distributors face highest margin compression.
Supply Chain Analysis
China and Germany anchor electric actuator final assembly and mechatronics integration for global OEM programs. Rare-earth magnet supply draws from Chinese processing facilities and Australian mining operations, while semiconductor content sources from Taiwan and South Korea wafer fabrication. Single-source vulnerability concentrates in neodymium-dysprosium supply chains for high-torque seat motors. Distribution runs through tier-1 seating system integrators consolidating procurement in Jiangsu and Zhejiang provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive comfort actuators are recovering from cyclical lows as NEV production quotas and 48V electrical architecture migration restart capital deployment across OEM supply chains.
For Market Incumbents: Compound functional safety certification advantages by extending ASIL-rated development cycles into climate control and multi-axis seat modules before aspirant suppliers complete 18-24 month qualification timelines. Deepen backward integration into Hall-effect position sensing semiconductors to defend margin position against brushless DC motor commoditization. Prioritize captive production expansion in Zhejiang province to capture joint-venture procurement consolidation. For New Entrants and Emerging Players: Anchor in India's BIS certification pathway for automotive electrical subcomponents, where Maruti Suzuki and Tata Motors scaling programs lack qualified domestic actuator suppliers. Target lumbar support modules with specialized motor and memory-control content, the segment with highest per-unit margins and lowest incumbent lock-in. Pursue software-defined vehicle integration partnerships requiring embedded firmware capabilities rather than discrete motor supply. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors suppliers with 48V architecture readiness and cabin domain controller integration competencies over legacy 12V discrete motor fabricators. Long-term viability hinges on software-enabled personalization features expanding actuator counts per vehicle. Watch for inflection in Chinese domestic OEM procurement patterns shifting from joint-venture tier-1s toward local suppliers with captive semiconductor sourcing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 26262 ASIL Certification Investment | Gates program awards for safety-critical seat and steering column actuator lines at German KBA-regulated OEMs. |
| 48V Electrical Architecture Migration | Enables higher-power seat and climate actuators without full high-voltage redesign for mild-hybrid platforms. |
| Cabin Domain Controller Integration | Consolidates multiple comfort functions under centralized electronic management, demanding embedded software competency. |
| China GB-Standard EMC Pre-Certification | Unlocks procurement access to MIIT-regulated NEV production lines in Yangtze River Delta automotive cluster. |
| Rare-Earth Magnet Supply Hedging | Stabilizes motor cost structures against neodymium and dysprosium price volatility in high-torque seat mechanisms. |
Study Parameters
A spread of perspectives from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and semiconductor component specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, MIIT NEV production disclosures, and REACH substance restriction filings. Bottom-up triangulation across actuator content-per-vehicle estimates and top-down reconciliation against OEM program awards anchored volume and value outputs.
Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the projection horizon. CAGRs were derived from fitted growth curves incorporating MIIT dual carbon mandate enforcement timelines and multi-zone HVAC proliferation rates. Industry-specific forecast inputs captured 48V electrical architecture migration pace and software-defined vehicle platform rollout schedules.
Decision-makers should treat outputs as directional under assumptions of sustained NEV mandate enforcement and stable rare-earth magnet supply; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in Chinese procurement localization policy and European REACH substance restriction amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
Automotive Connecting Rod Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Japan Automotive Sunroof Market
Automotive Components
Europe Torque Vectoring Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Automotive Spark Plug Market
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
Automotive Retarders Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Automotive Backing Plate Market
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
Automotive Straps Market