
 Smart Bicycle Accessories Market | 2026-2036
Smart Bicycle Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bicycle Accessories Market Analytics
Modular bundling of GPS trackers with smart lights and app-compatible locks is hardening as the default retail configuration. Garmin leverages its proprietary ecosystem to anchor premium positioning across integrated ride-data platforms. Wahoo Fitness competes through deep specialization in trainer-to-accessory connectivity protocols. SRAM sustains technology leadership in wireless shifting interfaces that now extend into companion accessory control.
Smart bicycle accessories encompass connected electronic devices that attach to or integrate with bicycles to enhance safety, performance, navigation, or theft prevention, typically operating through Bluetooth Low Energy at 2.4 GHz or NFC protocols with IP67-rated weather sealing. These products serve commercial fleet operators, individual commuters, and competitive cyclists who require real-time telemetry, automated lighting response, or geofenced security alerts. Smart lights and GPS trackers currently occupy the largest margin pools as safety regulations tighten across European urban centers, while IoT-enabled cloud-connected integration levels are expanding fastest as cellular module costs decline and over-the-air firmware updates become standard. Bluetooth dominates unit volumes due to universal smartphone compatibility, though solar power charging interfaces are gaining traction in long-distance touring segments where battery anxiety constrains adoption.
The EU General Safety Regulation and CE marking requirements under the EU Green Deal are reshaping product standards for connected cycling equipment sold across member states. The US Consumer Product Safety Commission and FCC impose parallel electromagnetic compatibility and RF exposure limits that determine market access for wireless-enabled accessories. Stakeholders must monitor evolving interoperability mandates between municipal bike-share systems and third-party accessory protocols to anticipate which integration standards will consolidate.
Market Dynamics
Cellular module cost compression below the $8 threshold is dissolving the price barrier that previously confined fleet-grade connectivity to premium segments, forcing a recalibration of entry-level product architecture across the entire accessory stack.
Growth Catalysts
- EU General Safety Regulation:Mandates for intelligent lighting on commercial cycle logistics vehicles in member states are creating guaranteed procurement volumes for certified suppliers.
- Ruhr Valley cycling corridor:Dense commuter infrastructure and municipal fleet expansion in Germany's industrial heartland is concentrating demand for integrated GPS-security bundles.
- Bluetooth Low Energy 5.3:Extended range and reduced power draw are enabling single-device architectures that previously required dual-radio designs, cutting bill-of-materials complexity.
Market Restraints
- Li-ion cell supply concentration:Battery pack sourcing remains captive to East Asian cell manufacturers, exposing margins to raw material volatility and logistics bottlenecks.
- IP67 certification cost:Weather-sealing validation for full submersion resistance adds 12-18% to unit manufacturing cost, compressing entry-tier profitability.
- RF spectrum congestion:2.4 GHz band saturation in dense urban environments degrades real-time telemetry reliability, limiting performance claims in city-center applications.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for wearable and IoT device assembly are attracting contract manufacturers to establish regional supply nodes.
- Solar-integrated touring accessories:Photovoltaic charging interfaces for multi-day endurance cyclists remain underserved by incumbent players focused on urban commuter segments.
- Interoperability mandates:Municipal bike-share system integration standards in Copenhagen and Amsterdam are opening specification windows for third-party accessory protocols.
Industry Challenges
- Embedded firmware engineering:Over-the-air update architecture requires capabilities scarce among traditional bicycle component suppliers, forcing talent competition with consumer electronics firms.
- CE marking timeline compression:Radio Equipment Directive conformity assessment for multi-protocol devices extends certification cycles, delaying product launches relative to pure-hardware accessories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bicycle Accessories Market |
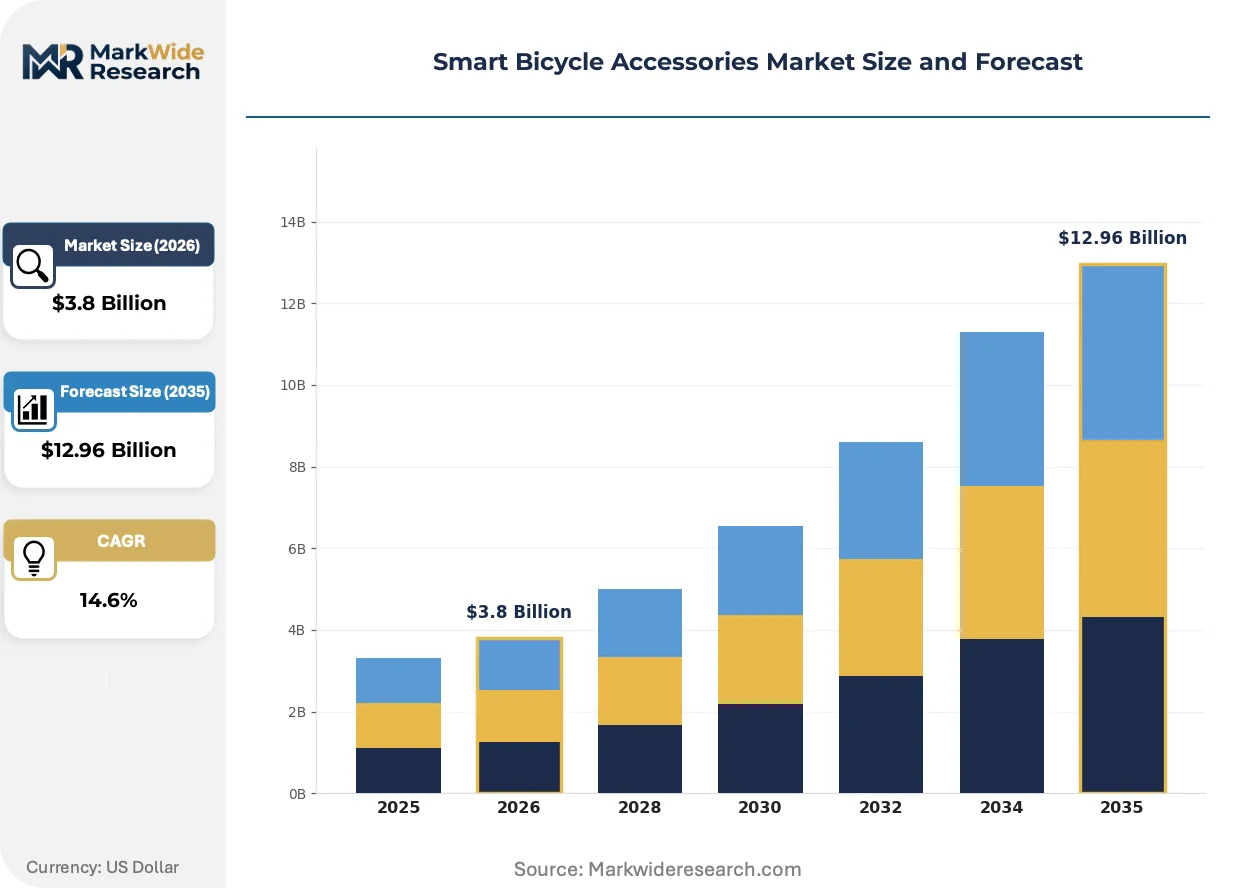
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lights, GPS Trackers, Smart Locks, Wireless Speakers Technology: Bluetooth, NFC, IoT, Solar Power End User: Recreational Cyclists, Commuters, Professional Cyclists, Tourists Integration Level: Standalone, Mobile App Compatible, Cloud-Connected, Smart Home Integrated |
| Companies Covered | Shimano, RockShox, Garmin, Favero, Fox, Wahoo Fitness, HoverAir, Crankbrothers, SRAM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bicycle Accessories Market Evolving Landscape
Convergence between cellular IoT architectures and solar harvesting interfaces is redrawing the power-autonomy boundary that has constrained long-distance cycling telemetry, while regulatory mandates in European logistics fleets are hardening technical specifications faster than consumer demand evolution.
Matter-over-Thread connectivity is absorbing the proprietary protocol fragmentation that previously forced cyclists to manage multiple companion apps. Long-distance tourers and bikepacking specialists are adopting solar-integrated head units and trackers first, drawn by multi-week autonomy without grid dependency. This absorption is compressing the addressable market for single-purpose Bluetooth accessories that cannot bridge into unified smart home or fleet management ecosystems.
REACH substance restrictions on persistent organic pollutants in battery housings are tightening material specifications for IP67-sealed enclosures sold across EU member states. Manufacturers must reformulate polymer compounds or source alternative sealing technologies to maintain market access. Commercial fleet operators in Germany and the Netherlands are responding fastest, embedding compliance documentation into procurement RFPs ahead of consumer channel requirements.
Direct-to-consumer subscription bundling is displacing traditional retail attachment selling for GPS-tracker and smart-light combinations. Urban commuters in Copenhagen and Amsterdam are purchasing hardware with embedded cellular service plans through manufacturer portals, bypassing bicycle shops entirely. This channel compression is most visible in markets with mature cycling infrastructure where buyers research specifications independently before purchase.
Smart Bicycle Accessories Market Segmentation
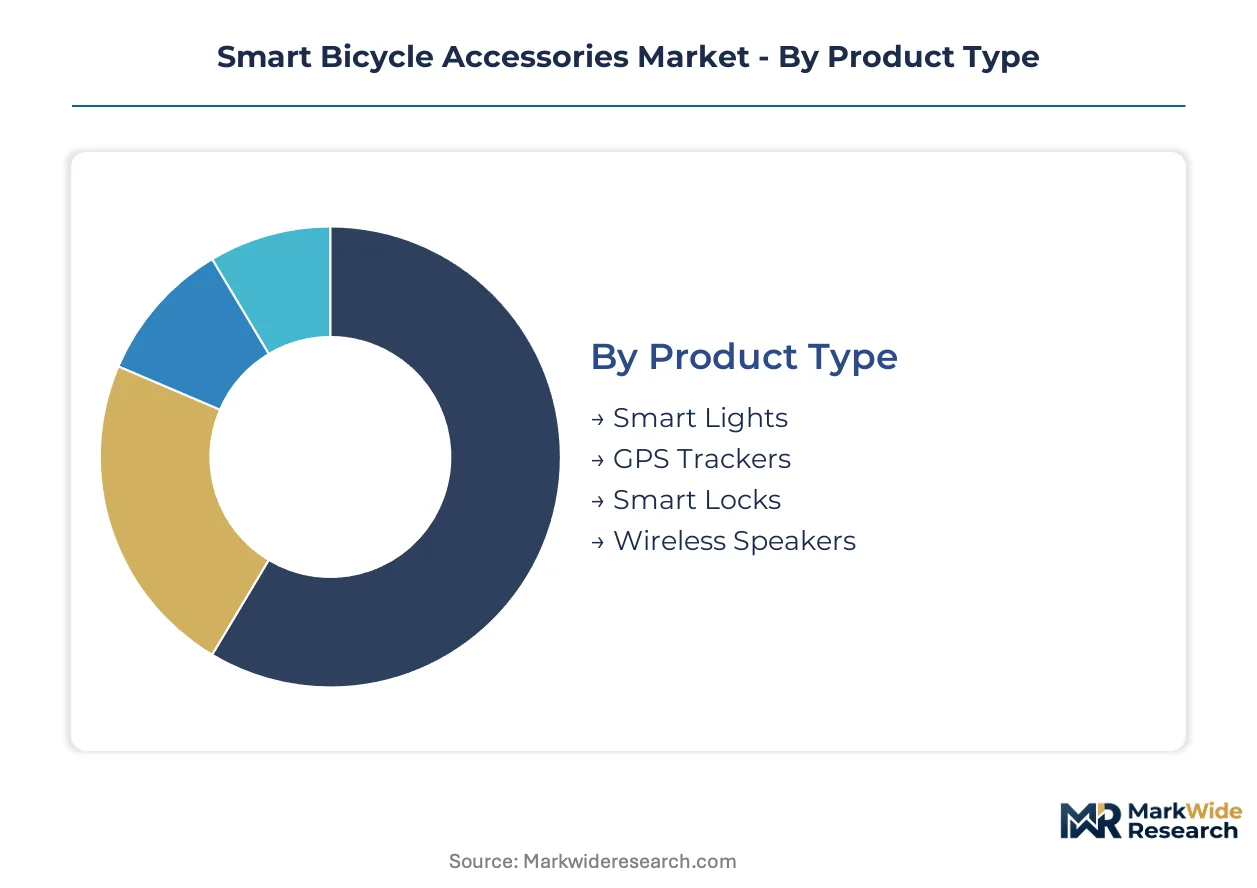
Segmentation in the Smart Bicycle Accessories Market reveals how upgrade cycles and replacement demand concentrate across distinct technology tiers and user profiles. Understanding these patterns allows suppliers to align component roadmaps with where procurement budgets actually flow.
Product Type:
Replacement cycles for connected accessories accelerate when safety regulations mandate specific equipment grades, forcing fleet operators and individual riders to retire legacy hardware ahead of normal wear-based schedules.
- Smart Lights:Intelligent lighting systems incorporate ambient sensors and automatic brightness modulation to comply with EU General Safety Regulation mandates for commercial cycle logistics. Copenhagen and Amsterdam municipal fleets are standardizing on units with integrated brake detection and turn signaling, driving volume concentration in certified product lines.
- GPS Trackers:Cellular-enabled location devices with geofencing capabilities and theft-alert protocols anchor security bundles for high-value bicycle deployments. Germany's Ruhr Valley cycling corridor exhibits concentrated demand for fleet-grade trackers with multi-year battery autonomy and tamper-resistant mounting.
- Smart Locks:Keyless entry systems leveraging Bluetooth Low Energy or NFC pairing eliminate mechanical key vulnerabilities while enabling access logging for shared mobility operators.
- Wireless Speakers:Handlebar-mounted audio devices with weather-sealed enclosures serve recreational riders seeking navigation prompts and entertainment without earbud isolation.
Smart lights sit at the top of the volume ranking, with GPS trackers climbing the fastest as cellular module costs compress below fleet adoption thresholds.
Technology:
Cost tier differentiation across radio protocols and power architectures determines which accessory categories can penetrate price-sensitive entry segments versus premium positioning.
- Bluetooth:Bluetooth Low Energy 5.3 dominates unit shipments through universal smartphone compatibility and simplified pairing workflows. Extended range specifications enable single-radio designs that previously required dual-protocol architectures, reducing bill-of-materials complexity for mid-tier manufacturers.
- IoT:Cellular-connected accessories with cloud telemetry capabilities command premium positioning in commercial fleet management applications. Over-the-air firmware update architectures distinguish IoT-enabled products from static-function alternatives, creating recurring service revenue attachment.
- NFC:Near-field communication enables tap-to-unlock functionality for smart locks and rapid device pairing without battery drain on passive tags.
- Solar Power:Photovoltaic charging interfaces address battery anxiety constraints in long-distance touring segments where grid access is intermittent.
Bluetooth occupies the highest shipment volumes, while IoT-enabled devices are expanding most quickly as cellular subscription bundling displaces traditional retail channels.
End User:
Application context shapes performance requirements and price elasticity across distinct cycling modalities from daily commuting to competitive racing.
- Commuters:Urban transportation cyclists prioritize theft prevention and visibility compliance over performance telemetry. Direct-to-consumer subscription bundling for GPS-tracker and smart-light combinations is displacing bicycle shop attachment selling in mature cycling infrastructure markets.
- Professional Cyclists:Competitive riders demand wireless shifting integration and real-time power meter compatibility with minimal latency. SRAM's proprietary protocols and Wahoo Fitness trainer connectivity standards create ecosystem lock-in that constrains third-party accessory interoperability.
- Recreational Cyclists:Weekend riders balance feature breadth against price points, favoring modular bundles that consolidate multiple functions through single-app management.
- Tourists:Multi-day endurance cyclists and bikepacking specialists prioritize power autonomy and weather resilience over urban-oriented feature sets.
Commuters represent the largest addressable base, with professional cyclists driving the steepest technology upgrade trajectory through integrated ecosystem demands.
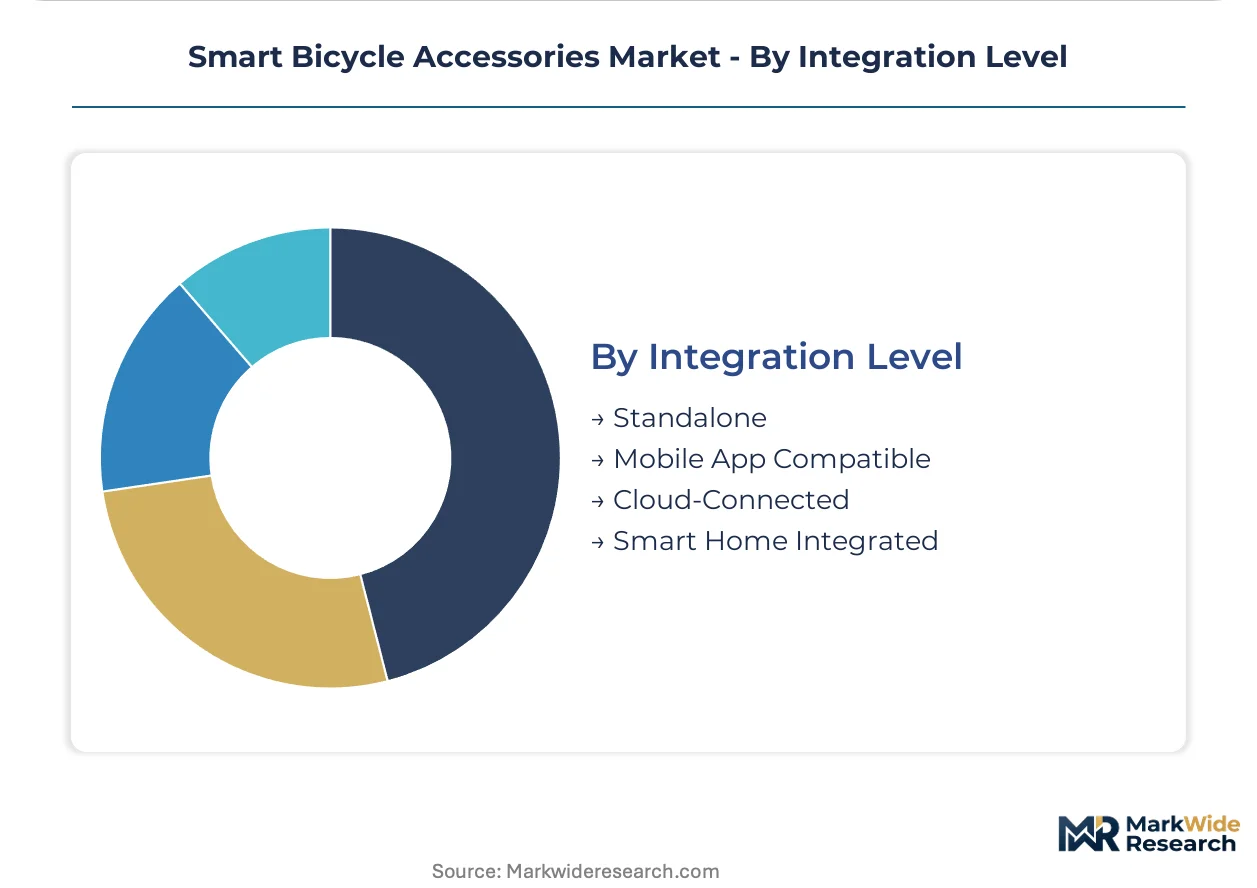
Integration Level:
Customer type and technical sophistication determine willingness to manage multiple companion apps versus demand for unified control interfaces.
- Cloud-Connected:Cellular-enabled accessories with persistent internet connectivity support real-time fleet tracking and remote security monitoring. Municipal bike-share systems in Copenhagen and Amsterdam are mandating interoperability protocols that favor cloud-connected architectures over standalone alternatives.
- Mobile App Compatible:Bluetooth-paired devices with smartphone companion applications dominate consumer channel volumes through lower hardware cost and simpler onboarding.
- Standalone:Self-contained accessories without external connectivity serve price-sensitive segments and jurisdictions with restricted RF equipment certification timelines.
- Smart Home Integrated:Matter-over-Thread compatibility enables bicycle accessories to bridge into unified smart home ecosystems, reducing app fragmentation for tech-forward households.
Mobile app compatible products hold the volume lead, with cloud-connected integration gaining share fastest as fleet procurement specifications harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smart bicycle accessories industry traces its commercial origins to European cycling infrastructure investments during the 1990s, when Dutch and Danish municipalities first deployed electronic fleet tracking systems. German engineering houses subsequently industrialized wireless connectivity protocols for commercial cycle logistics, establishing the technical foundations that now propagate across connected safety equipment markets worldwide.
Germany
The Ruhr Valley cycling corridor anchors concentrated procurement of GPS-security bundles for municipal and commercial fleets. The KBA enforces type-approval standards for intelligent lighting systems on logistics vehicles under the EU General Safety Regulation. Berlin-Brandenburg hosts emerging integration labs where bike-share operators test third-party accessory protocols against municipal interoperability mandates.
Netherlands
Amsterdam's municipal fleet expansion drives standardized procurement of connected safety equipment with automatic brightness modulation and brake detection. The EU Green Deal shapes CE marking requirements for weather-sealed enclosures sold across Dutch distribution channels. Randstad urban centers concentrate direct-to-consumer subscription bundling for GPS-tracker and smart-light combinations that bypass traditional retail.
United States
Silicon Valley venture deployment supports cellular-enabled accessory startups targeting long-distance touring segments with solar-integrated architectures. The FCC imposes electromagnetic compatibility and RF exposure limits that determine market access for Bluetooth Low Energy devices. Pacific Northwest metropolitan areas exhibit concentrated adoption of Matter-over-Thread compatible accessories bridging into unified smart home ecosystems.
China
Shenzhen contract manufacturers dominate bill-of-materials supply for cellular modules and battery pack assembly serving global brands. The MIIT regulates radio transmission standards and network access permits for IoT-enabled devices exported to European and North American markets. Pearl River Delta production nodes capture volume manufacturing for entry-tier Bluetooth accessories as India's PLI scheme diverts some final assembly capacity.
India
Bengaluru's electronics manufacturing services sector attracts wearable and IoT device assembly under production-linked incentive schemes. The BIS certifies product safety and electromagnetic compatibility for accessories sold in domestic and export markets. Maharashtra's industrial corridors host emerging regional supply nodes for solar-integrated touring accessories targeting underserved endurance cycling segments.
Smart Bicycle Accessories Market Competitive Landscape
Premium-margin players sit above commodity-margin players across ecosystem integration depth, with proprietary protocol control determining pricing power. The vendor base stratifies into three tiers: integrated platform owners commanding recurring service revenue, component specialists capturing hardware margins, and contract manufacturers competing on assembly cost. Consolidation pressure concentrates among mid-tier Bluetooth accessory producers as cellular module cost compression erodes their price-positioning advantage. Dominant competitive moves include strategic partnerships with municipal bike-share operators and backward integration into firmware engineering capabilities.
Within the integrated platform tier, Garmin and Wahoo Fitness exemplify divergent specialization strategies. Garmin anchors premium positioning through proprietary ride-data ecosystems that harden customer retention. Wahoo Fitness occupies a position emphasizing trainer-to-accessory connectivity protocols that constrain third-party interoperability. SRAM represents the component specialist archetype, with wireless shifting interfaces extending into companion accessory control standards that shape ecosystem boundaries.
| Leading Market Players |
|---|
| Shimano |
| RockShox |
| Garmin |
| Favero |
| Fox |
| Wahoo Fitness |
| HoverAir |
| Crankbrothers |
| SRAM |
| Others |
Value Network & Pricing Analysis
Cellular module cost compression below the $8 threshold is dissolving the price barrier that previously confined fleet-grade connectivity to premium segments, forcing a recalibration of entry-level product architecture across the entire accessory stack. This shift simultaneously erodes margins for Bluetooth-only manufacturers while concentrating procurement power among buyers who can specify multi-protocol requirements.
Pricing Analysis
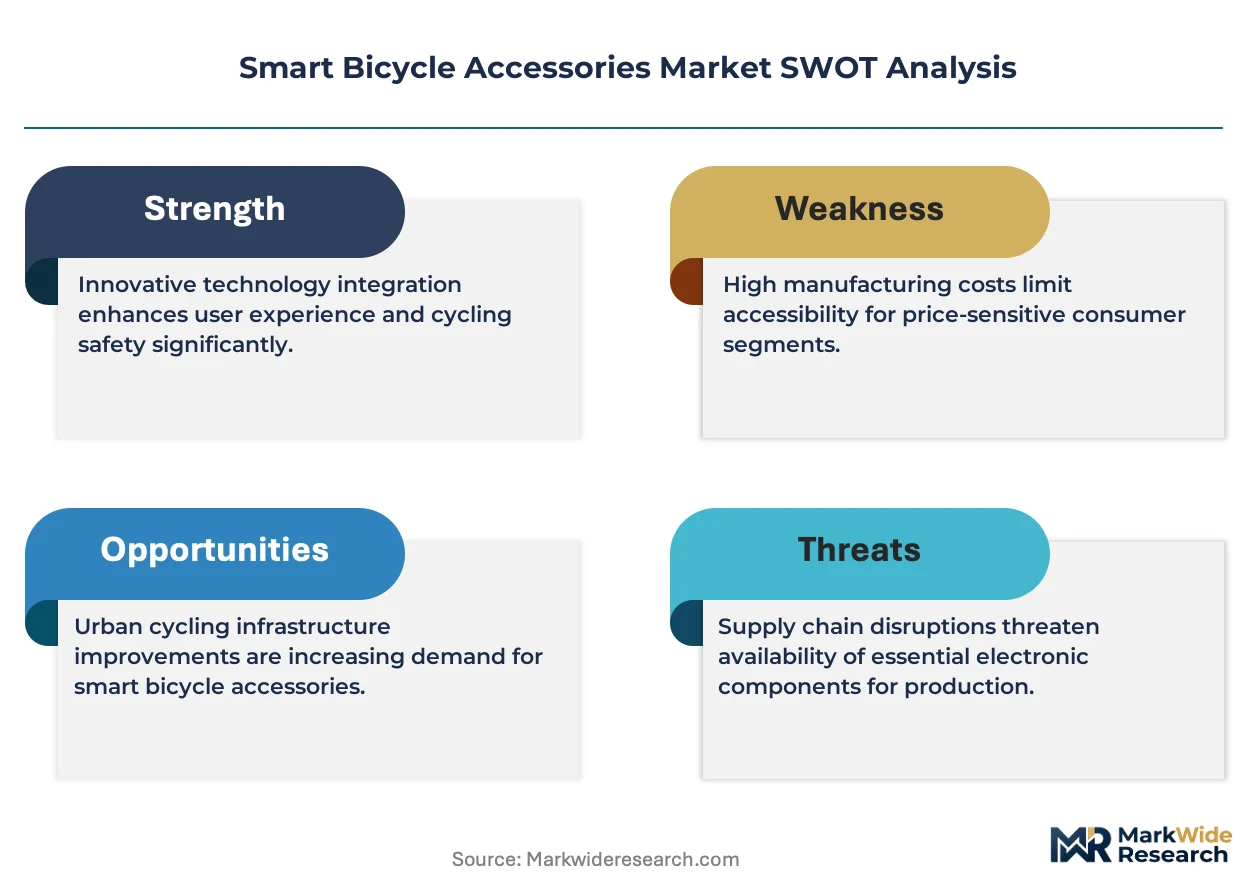
Three-tier pricing structure across premium, standard, and economy levels separates ecosystem-integrated platforms from single-function peripherals. Price differentiation hinges on CE marking tier and firmware update capability, with certified IoT bundles commanding substantial premiums over uncertified alternatives. Pricing pressure stems from Shenzhen contract manufacturers flooding entry-tier Bluetooth segments with undifferentiated hardware. Municipal fleet operators exhibit lowest price sensitivity due to regulatory compliance mandates, while recreational cyclists in emerging markets resist subscription bundling models.
Supply Chain Analysis
Direct-to-consumer channels handle subscription-bundled GPS-security combinations, bypassing traditional bicycle retail entirely. Manufacturing concentrates in China, Vietnam, and India as India's PLI scheme diverts final assembly capacity from Pearl River Delta nodes. Bill-of-materials draws from East Asian Li-ion cell manufacturers, Taiwanese semiconductor foundries, and German polymer compound suppliers. Single-source vulnerability in cellular module sourcing exposes margins to raw material volatility. Distribution runs through manufacturer portals and municipal procurement RFPs rather than specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Production cost differentials between India's emerging electronics manufacturing services sector and China's established Pearl River Delta infrastructure create geographic-arbitrage opportunities for contract manufacturing relocation.
For Market Incumbents: Deploy backward integration into firmware engineering capabilities to defend against consumer electronics firms poaching embedded systems talent. Secure type-approval pre-certification for EU General Safety Regulation compliance ahead of competitor submissions. Channel control through direct-to-consumer portals protects margin pools as traditional retail attachment selling collapses. For New Entrants and Emerging Players: Municipal bike-share operators represent the most penetrable channel partner type for third-party accessory protocol integration. Target solar-integrated touring accessories where incumbent players remain focused on urban commuter segments. White-space exists in multi-day endurance cycling telemetry where battery anxiety constrains adoption of existing solutions. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier Bluetooth accessory producers because cellular module cost compression is eroding their standalone price-positioning advantage. Acquire targets with existing CE marking documentation and municipal fleet relationships to compress regulatory timelines. Watch for India's PLI scheme maturation as the inflection signal for regional supply node consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Engineering Acquisition | Embedded systems talent scarcity forces capability buys from consumer electronics firms. |
| CE Marking Pre-Certification | Radio Equipment Directive compliance accelerates product launches against uncertified competitors. |
| Municipal Fleet Partnership | Copenhagen and Amsterdam interoperability mandates favor early protocol adopters. |
| Solar-Integrated Product Line | Underserved bikepacking segments offer margin refuge from urban commuter price wars. |
| India PLI Supply Node | Production-linked incentives reduce landed cost for European and North American distribution. |
Research Methodology
Multiple input streams — regulatory filing analysis, component cost databases, and municipal procurement documentation — were reconciled against primary interviews with fleet operations managers, embedded firmware engineers, bicycle shop category buyers, and contract manufacturing procurement leads. Secondary validation drew from FCC equipment authorization records, EU CE marking databases, MIIT radio transmission filings, and trade flow customs data. Bottom-up unit shipment estimates were triangulated against top-down market value reconstructions.
Historical volume trajectories were cross-referenced against expert panel assessments to anchor growth projections across the analysis window. Segmentation modeling incorporated product type, radio protocol architecture, end-user application context, and integration level complexity. CAGRs were derived from fitted trend analysis adjusted for regulatory mandate timing and cellular module cost decline curves. Industry-specific inputs included municipal fleet expansion schedules and bike-share system interoperability specification releases.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Li-ion supply concentration disruptions and REACH substance restriction enforcement. Outputs reflect documented assumptions around Bluetooth Low Energy adoption curves and solar harvesting efficiency improvements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorsports Motorcycle Market
Bikes and Motorcycles
Latin America Two-Wheeler Market
Bikes and Motorcycles
Europe E-Cargo Bike Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Vietnam Bike-Sharing Market
Bikes and Motorcycles
Maxi Scooter Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
Child Bike Seats Market
Bikes and Motorcycles
Two Wheeler Seats Market
Bikes and Motorcycles
Cargo Bike Market
Bikes and Motorcycles
Motorcycle Transmission Control Unit Market
Bikes and Motorcycles
Automotive Chain Sprockets Market
Bikes and Motorcycles
Two-Wheeler Fuel Injection Systems Market
Bikes and Motorcycles
Fuel Cell Bikes Market