
 North America Automotive Intercooler Market | 2026-2036
North America Automotive Intercooler Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Intercooler Market Analytics
Mexican intercooler foundry capacity is restructuring as Tier 1 suppliers relocate aluminum casting operations from Asia to serve Detroit Three just-in-sequence assembly schedules. MANN+HUMMEL Group leverages its filtration-adjacent thermal management expertise to anchor long-term supply agreements with major powertrain integrators. Modine Manufacturing Company sustains heavy-duty commercial vehicle intercooler dominance through vertically controlled tube-and-fin production lines in Missouri and Tennessee. Garrett Motion Inc. competes on turbocharger-intercooler system integration, bundling charge-air coolers with its compressor housing designs.
An automotive intercooler is a heat exchanger that reduces the temperature of compressed air before it enters an engine combustion chamber, typically constructed from aluminum alloy tubes and fins brazed in controlled-atmosphere furnaces to achieve thermal conductivity exceeding 200 W/m·K while resisting boost pressures above 2.5 bar. Its primary purpose is to increase charge density, enabling higher specific power output and reduced knocking tendency in forced-induction engines. Air-to-water intercoolers lead product type margins due to their compact packaging advantage in downsized engine bays, while liquid-to-gas architectures represent the fastest-growing category as hybrid powertrains demand secondary cooling loops for battery and inverter thermal management. Aluminum dominates material selection for OEM channels, though composite intercooler tanks gain share in weight-sensitive electric vehicle platforms where every kilogram of auxiliary mass directly reduces range.
EPA greenhouse gas emission standards for light-duty vehicles and NHTSA fuel economy regulations jointly mandate intercooler efficiency improvements that reduce pumping losses and enable higher exhaust gas recirculation rates. CARB zero-emission vehicle mandates in California indirectly shape intercooler demand by preserving internal combustion engine production in plug-in hybrid architectures that still require charge-air cooling. Stakeholders must monitor how EPA anticipated rulemakings on particulate matter from gasoline direct injection engines may tighten intercooler condensation management requirements, forcing design decisions about integrated oil separation and drain-back provisions before next-generation platform commitments lock in thermal system architectures.
Market Dynamics
EPA Corporate Average Fuel Economy standards and NHTSA greenhouse gas mandates are compressing engine bay packaging constraints, forcing charge-air cooling architectures toward higher thermal density and integrated thermal management systems.
Growth Catalysts
- Light truck turbocharger penetration:Forced-induction gasoline and diesel powertrains in full-size pickups and SUVs across the United States, Canada, and Mexico sustain OEM intercooler procurement volumes.
- CARB zero-emission vehicle mandates:California Air Resources Board regulations preserve internal combustion engine production in plug-in hybrid architectures requiring charge-air cooling for range-extender engines.
- Air-to-water thermal density:Liquid-cooled charge-air coolers enable downsized engine packaging in transverse powertrain layouts without sacrificing boost pressure tolerance.
Market Restraints
- Aluminum alloy price volatility:Primary aluminum and brazing sheet input costs fluctuate with energy-intensive smelting economics, compressing foundry margins on fixed-price OEM supply agreements.
- Great Lakes supply concentration:Tier 1 intercooler manufacturing clusters in Michigan, Ohio, and Ontario create geographic vulnerability to regional logistics disruptions or labor actions.
- Battery electric vehicle substitution:Pure battery electric platforms eliminate charge-air cooling entirely, threatening long-term addressable market scope as zero-emission mandates tighten.
Strategic Opportunities
- Mexican foundry expansion:Relocation of aluminum casting operations from Asia to Mexican manufacturing corridors serving Detroit Three just-in-sequence assembly schedules creates captive supply positioning.
- Hybrid secondary cooling loops:Liquid-to-gas intercooler architectures address battery and inverter thermal management in plug-in hybrid powertrains, extending product relevance into electrified platforms.
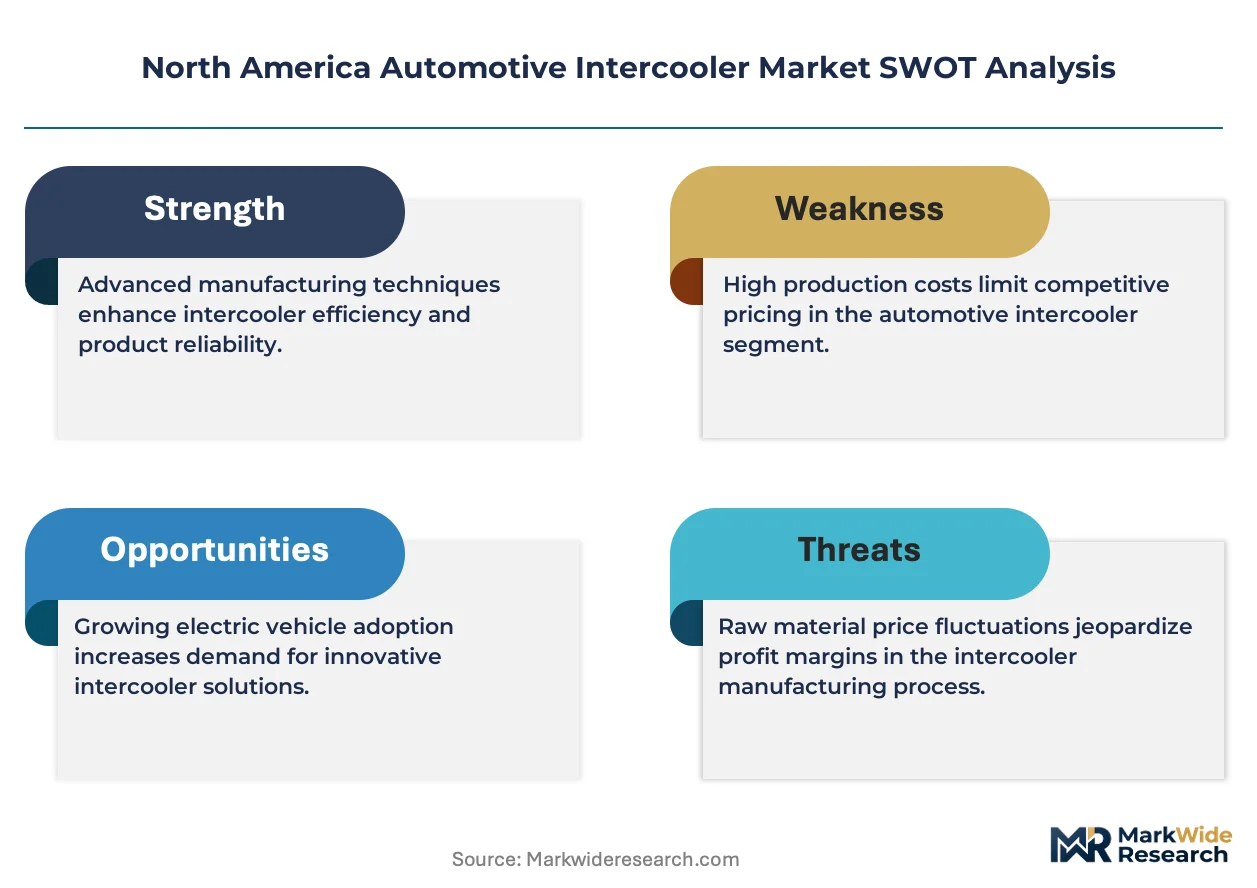
- Integrated oil separation:EPA anticipated rulemakings on gasoline direct injection particulate matter may mandate intercooler condensation management with drain-back provisions, creating design differentiation for early movers.
Industry Challenges
- Brazing furnace technician scarcity:Controlled-atmosphere brazing expertise for aluminum tube-and-fin cores is concentrated among aging workforce cohorts in Midwest manufacturing regions.
- Platform commitment lock-in:Thermal system architecture decisions made three to four years before production constrain retroactive design changes when regulations shift mid-development cycle.
- Multi-loop thermal integration:Hybrid powertrains demand simultaneous optimization of charge-air, battery, inverter, and cabin cooling loops, multiplying system complexity and validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Intercooler Market |
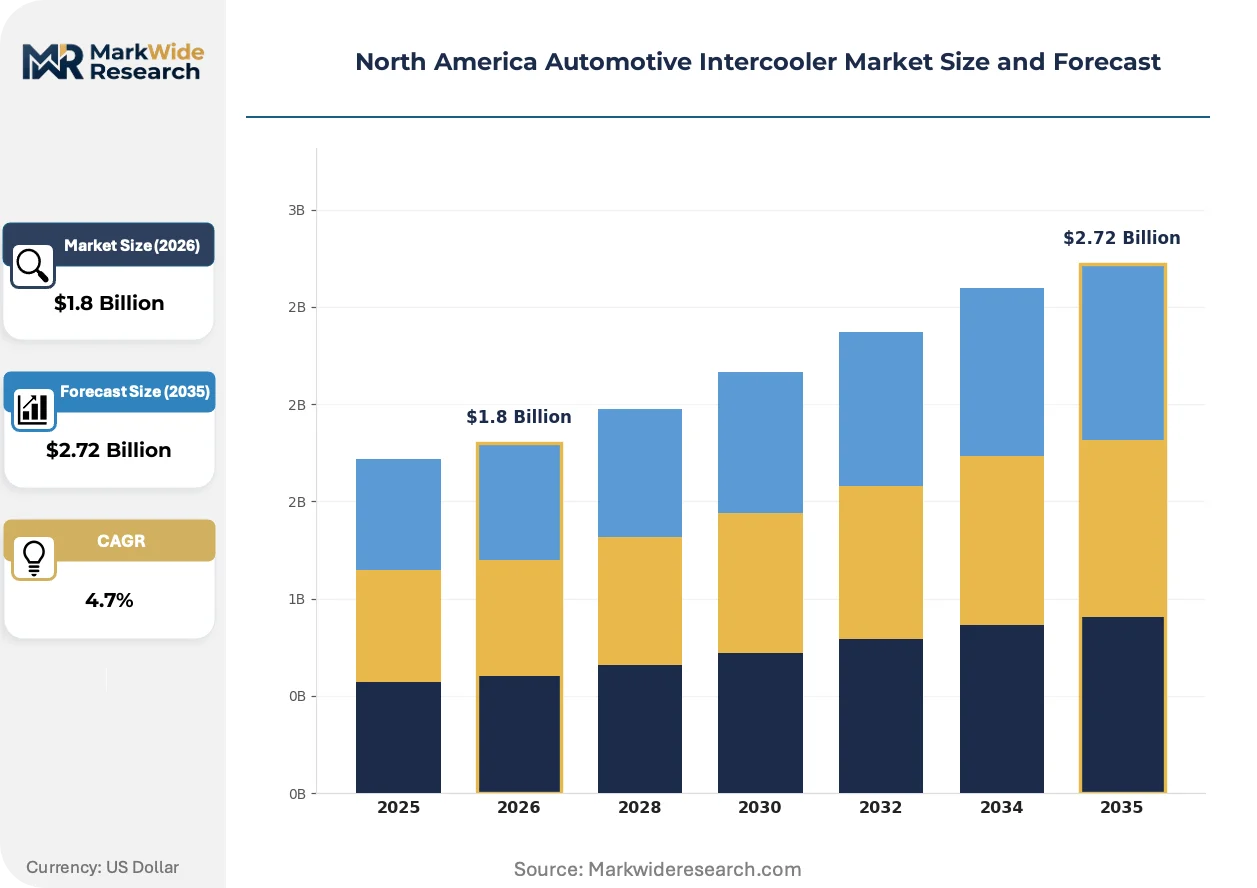
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-to-Air, Air-to-Water, Water-to-Water, Liquid-to-Gas Material: Aluminum, Plastic, Stainless Steel, Composite Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles Installation Type: OEM, Aftermarket, Retrofit, Custom |
| Companies Covered | MANN+HUMMEL Group, Modine Manufacturing Company, Garrett Motion Inc., PWR Holdings Limited, Mishimoto Automotive, Mahle GmbH, Nissens A/S, Bell Intercoolers, Valeo Service SAS, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Intercooler Market Evolving Landscape
Thermal management architectures are fragmenting across competing cooling strategies as electrification pressures force intercooler suppliers into adjacent heat exchanger categories and system integration roles.
Additive manufacturing of aluminum heat exchanger cores is decentralizing production economics for low-volume performance and aftermarket applications. Specialty vehicle builders and racing teams in the United States and Canada are adopting topology-optimized charge-air cooler designs with conformal cooling channels. This technology is decentralizing tool-and-die dependencies that previously favored high-volume OEM supply contracts.
EPA greenhouse gas emission standards for light-duty vehicles are tightening intercooler efficiency requirements to enable higher exhaust gas recirculation rates and reduced pumping losses. Manufacturers must demonstrate charge-air temperature reduction performance under standardized test cycles. The regulatory pressure is most acute for full-size truck platforms where towing duty cycles demand sustained thermal capacity.
Fleet procurement departments are consolidating supplier relationships around thermal system integrators capable of delivering complete charge-air, radiator, and condenser modules. Single-source contracting replaces discrete component purchasing for light truck and commercial vehicle programs. This concentration is most visible among Detroit Three powertrain engineering groups seeking reduced validation burden and warranty alignment.
North America Automotive Intercooler Market Segmentation
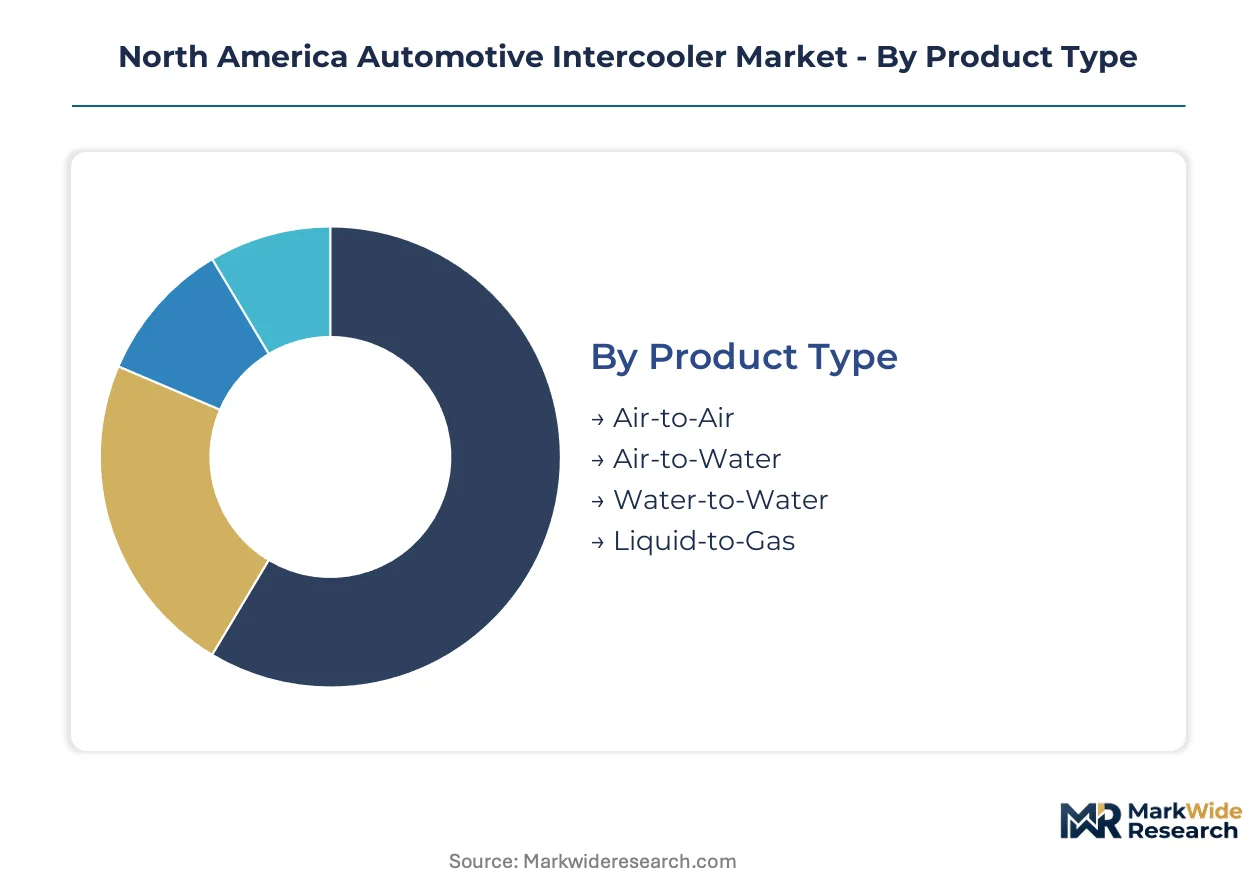
Intercooler procurement patterns diverge sharply across thermal architectures, material specifications, and vehicle platform requirements. Each segmentation dimension reveals distinct margin structures and supplier qualification barriers that shape competitive positioning in North American automotive supply chains.
Product Type:
Buyers differentiate primarily by packaging constraints and thermal density requirements rather than unit cost alone.
- Air-to-Water:Liquid-cooled cores achieve charge-air temperature reductions in compact engine bays where space limits traditional frontal-area designs. Full-size pickup platforms across Michigan and Ohio assembly plants specify these architectures for towing duty cycles demanding sustained thermal capacity.
- Air-to-Air:Conventional tube-and-fin constructions dominate high-volume light truck production where frontal packaging remains available. Ford F-Series and Ram 1500 programs in Kentucky and Mexico sustain procurement volumes through established aluminum brazing supply chains.
- Water-to-Water:Secondary-loop heat exchangers serve hybrid powertrain battery cooling integration in transverse engine layouts.
- Liquid-to-Gas:Emerging architectures address inverter and battery thermal management in plug-in hybrid platforms preserving internal combustion range extenders.
Air-to-Air leads volumes today; Liquid-to-Gas is gaining share fastest.
Material:
Material selection tracks directly with weight sensitivity and corrosion resistance requirements across vehicle electrification roadmaps.
- Aluminum:Controlled-atmosphere brazed alloys deliver thermal conductivity above 200 W/m·K while resisting boost pressures exceeding 2.5 bar. Detroit Three OEM procurement specifications mandate aluminum for all charge-air cooling applications in internal combustion and hybrid powertrains.
- Composite:Glass-fiber reinforced polymer tanks and end caps reduce auxiliary mass in battery electric platforms where every kilogram of cooling system weight directly reduces vehicle range. California-based EV manufacturers specify composite constructions for thermal management modules.
- Plastic:Injection-molded tanks serve cost-sensitive aftermarket replacement channels with reduced thermal cycling durability.
- Stainless Steel:Marine and extreme-duty commercial applications specify corrosion-resistant constructions for salt spray environments.
Aluminum dominates OEM channels; Composite is climbing the fastest as electric vehicle production scales.
Vehicle Type:
Platform thermal load profiles determine intercooler sizing, duty cycle specifications, and integration complexity.
- Commercial Vehicles:Heavy-duty trucking and vocational applications demand charge-air coolers with sustained thermal capacity under continuous boost conditions. Navistar and PACCAR programs specify oversized cores with redundant cooling capacity for grade hauling in Arizona and Nevada operating conditions.
- Passenger Cars:Downsized turbocharged sedans and crossovers prioritize packaging efficiency over absolute thermal capacity. Transverse powertrain layouts in Tennessee and Ontario assembly plants drive air-to-water specification rates.
- Electric Vehicles:Battery thermal management systems repurpose intercooler manufacturing competencies for coolant-to-refrigerant heat exchangers.
- Motorcycles:Performance and touring bike segments specify compact charge-air coolers for forced-induction powertrains in limited packaging envelopes.
Commercial Vehicles anchor supplier revenues; Electric Vehicles are expanding most quickly into adjacent thermal management categories.
Installation Type:
Channel economics separate captive OEM supply from fragmented aftermarket service demand.
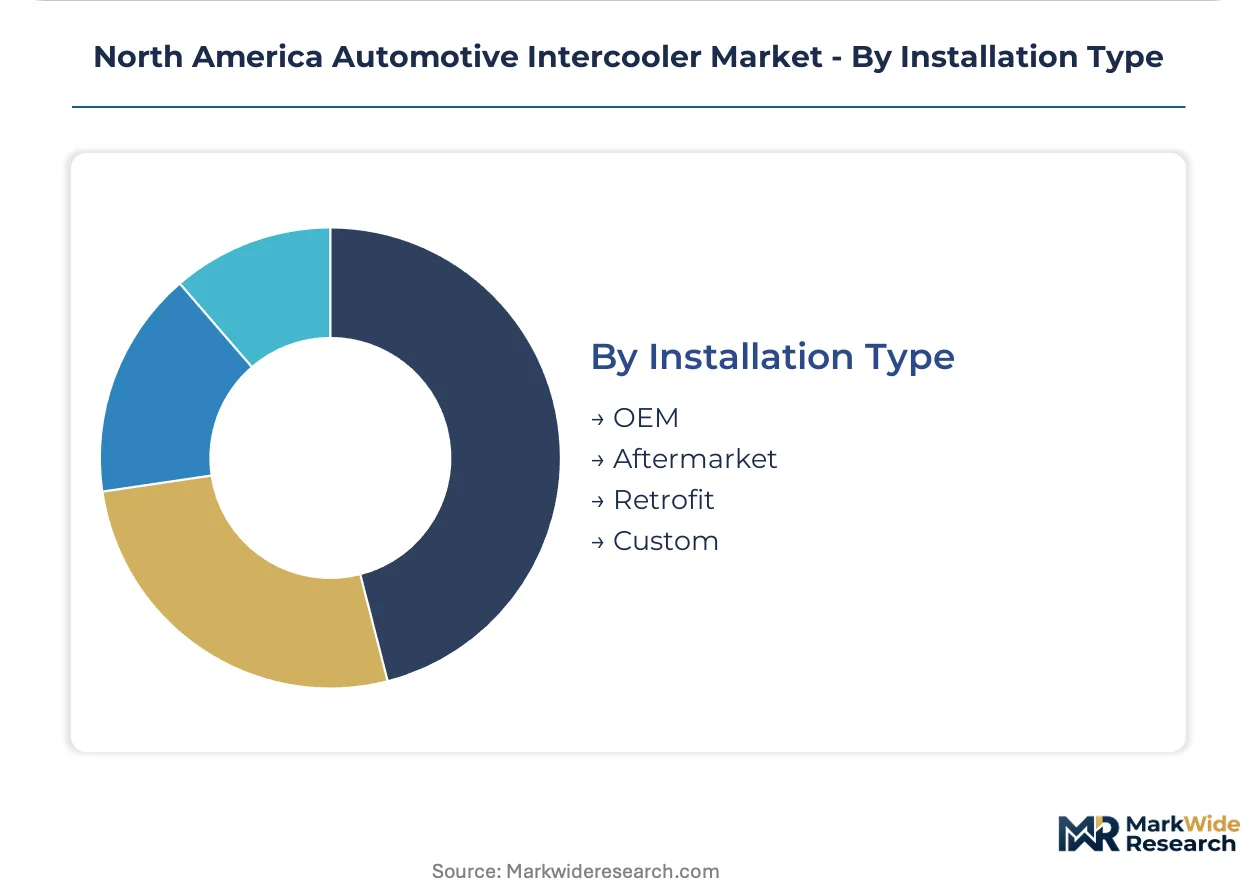
- OEM:Just-in-sequence delivery to powertrain assembly lines requires Tier 1 suppliers to locate foundry and brazing operations within 300 miles of Detroit Three manufacturing clusters. Long-term supply agreements span vehicle platform lifecycles with stringent warranty alignment provisions.
- Aftermarket:Independent service channels address turbocharger replacement and collision repair demand through distributor networks. Price competition intensifies as offshore manufacturers supply direct-fit replacements for out-of-warranty vehicles.
- Retrofit:Performance enthusiasts upgrade factory charge-air cooling for modified boost pressures in specialty applications.
- Custom:Low-volume builders and racing teams specify topology-optimized designs through additive manufacturing channels.
OEM captures value concentration; Aftermarket faces margin compression from import competition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican foundry operations capture production migrating from Asia to exploit proximity advantages and regulatory alignment with Detroit Three assembly schedules. Aluminum casting investments cluster along transport corridors feeding just-in-sequence delivery requirements. EPA and NHTSA standards apply uniformly across the integrated North American production zone.
United States
Full-size pickup and SUV turbocharger penetration sustains intercooler procurement volumes across Kentucky, Michigan, and Tennessee assembly plants. EPA Corporate Average Fuel Economy standards compel charge-air cooling efficiency improvements for light truck platforms. The Great Lakes manufacturing corridor spanning Ohio and Michigan anchors Tier 1 supplier foundry and brazing operations within 300 miles of Detroit Three powertrain facilities.
Canada
Ontario-based assembly plants serving Detroit Three programs drive OEM intercooler demand for transverse-engine crossovers and light trucks. Environment and Climate Change Canada regulations mirror EPA fuel economy mandates, preserving regulatory continuity across the integrated supply chain. The Windsor-Toronto automotive corridor concentrates thermal management supplier engineering centers serving North American platform development.
Mexico
Relocated aluminum casting operations from Asia establish captive supply positioning for Detroit Three just-in-sequence schedules in Nuevo León and Bajío Region corridors. Mexican manufacturing cost structures attract Tier 1 foundry investments without regulatory divergence from US standards. Monterrey and Querétaro industrial parks host expanding intercooler core production serving Ram and Ford truck assembly.
North America Automotive Intercooler Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue additive manufacturing and hybrid thermal management adjacencies. The supplier base concentrates around thermal system integrators capable of delivering complete charge-air, radiator, and condenser modules. Three archetypes dominate: filtration-adjacent diversifiers, vertically controlled heavy-duty specialists, and turbocharger-integrated bundlers. Competitive moves center on Mexican foundry expansion and long-term supply agreement anchoring with Detroit Three powertrain engineering groups.
Among filtration-originated diversifiers, MANN+HUMMEL Group exemplifies the thermal-management-adjacent archetype leveraging air handling expertise. Vertically controlled fabricators include Modine Manufacturing Company, which occupies a position in heavy-duty commercial vehicle supply through in-house tube-and-fin production control. Garrett Motion Inc. represents the turbocharger-integrated bundler archetype, sitting within the compressor housing design-to-cooler system convergence. These three anchors illustrate distinct competitive vectors: filtration crossover, manufacturing depth, and system integration.
| Leading Market Players |
|---|
| MANN+HUMMEL Group |
| Modine Manufacturing Company |
| Garrett Motion Inc. |
| PWR Holdings Limited |
| Mishimoto Automotive |
| Mahle GmbH |
| Nissens A/S |
| Bell Intercoolers |
| Valeo Service SAS |
| Others |
Value Network & Pricing Analysis
Additive manufacturing adoption for topology-optimized charge-air cooler cores simultaneously reduces tool-and-die capital requirements and fragments production economics away from high-volume OEM supply chains toward low-volume specialty builders across the United States and Canada.
Pricing Analysis
Distributor margin layers separate aftermarket channels from direct-to-OEM contract structures. Three-tier pricing structure across premium racing-grade, standard replacement, and economy direct-fit levels tracks thermal cycling durability and brand certification status. Cost compression in the economy tier intensifies as offshore manufacturers penetrate independent service channels with aluminum brazing capabilities. Fleet procurement departments exhibit lowest price sensitivity due to warranty alignment requirements, while collision repair shops face acute margin pressure.
Supply Chain Analysis
Dual-sourcing requirements mandated by Detroit Three powertrain engineering groups force Tier 1 suppliers to qualify redundant foundry operations within the Great Lakes corridor. Aluminum brazing sheet and primary alloy feedstock draw from domestic smelters and Canadian rolling mills. Single-source vulnerability concentrates in controlled-atmosphere furnace technician expertise concentrated among aging workforce cohorts in Midwest manufacturing regions. Distribution runs through just-in-sequence delivery networks feeding Michigan, Ohio, and Ontario assembly plants within 300-mile radii.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA greenhouse gas emission standards for light-duty vehicles compound intercooler demand through sustained internal combustion engine production in turbocharged and hybrid architectures.
For Market Incumbents: Lock in long-term supply agreements with Detroit Three powertrain integrators before next-generation platform commitments freeze thermal system architectures. Deepen backward integration into aluminum casting operations in Mexican manufacturing corridors to secure captive supply positioning against emerging additive manufacturing entrants. Prioritize brazing furnace technician apprenticeship pipelines to address workforce scarcity threatening production continuity. For New Entrants and Emerging Players: CARB zero-emission vehicle mandates in California preserve internal combustion range-extender production in plug-in hybrid architectures, opening a window for liquid-to-gas thermal management specialization. Target secondary-loop battery and inverter cooling integration where established suppliers lack hybrid powertrain validation heritage. Pursue direct qualification with California-based EV manufacturers specifying composite intercooler constructions for weight-sensitive platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among vertically controlled heavy-duty commercial vehicle specialists with in-house tube-and-fin production capabilities. Five-to-ten-year viability hinges on successful adjacency expansion into hybrid thermal management modules rather than pure charge-air cooling dependence. Monitor EPA anticipated rulemakings on gasoline direct injection particulate matter as the inflection signal for integrated oil separation technology premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Mexican Foundry Expansion | Captive supply positioning serves Detroit Three just-in-sequence schedules without regulatory divergence. |
| Hybrid Secondary Cooling Loop Development | Liquid-to-gas architectures extend product relevance into electrified platforms preserving internal combustion range extenders. |
| Integrated Oil Separation Investment | EPA particulate matter rulemakings may mandate condensation management with drain-back provisions for design differentiation. |
| Additive Manufacturing Capability Buildout | Topology-optimized cores address low-volume performance and racing applications decentralizing tool-and-die dependencies. |
| Brazing Technician Apprenticeship Pipeline | Controlled-atmosphere expertise scarcity in Midwest regions threatens production continuity for aluminum tube-and-fin cores. |
Research Methodology
Bottom-up vehicle production modeling reconciled against top-down aluminum brazing capacity tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and controlled-atmosphere furnace technicians combined with secondary validation from EPA regulatory filings, NHTSA safety mandate documentation, vehicle registration databases, and aluminum alloy trade flow records. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map intercooler content per vehicle across propulsion architectures, vehicle classes, and regional production clusters. Segmentation dimensions span product type, material specification, vehicle platform, and installation channel. CAGRs derive from regression analysis of historical procurement volumes against regulatory milestone timing. Forecast inputs incorporate turbocharger penetration curves, hybrid powertrain adoption rates, and foundry capacity expansion announcements.
Revisions become necessary when EPA rulemaking timelines accelerate, aluminum smelting energy economics shift materially, or battery electric vehicle substitution exceeds hybrid preservation scenarios. Deviation in CARB zero-emission vehicle mandate stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Asia-Pacific Automotive Composites Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Automotive Bushing Market
Automotive Components
Europe Heat Shrink Tubing for Automotive Market
Automotive Components
Electric Vehicle Fluid Lubricants Market
Automotive Components
Global Automotive Water Valve Market
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
Global Automotive Sun Visor Market
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Asia Pacific Automotive AHSS Market