
 Europe Automotive Heat Exchanger Market | 2026-2036
Europe Automotive Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Heat Exchanger Market Foresight
Electric vehicle thermal management is broadening the end-use vertical mix beyond traditional internal combustion cooling systems. Valeo SA leverages its European manufacturing footprint to supply battery thermal management modules across multiple OEM platforms. Mahle GmbH sustains R&D intensity in compact heat exchanger architectures optimized for electric powertrains. Bosch Mobility anchors its position through channel control of integrated thermal system sales to German vehicle assemblers.
An automotive heat exchanger transfers thermal energy between two or more fluids at different temperatures, typically constructed from aluminum alloy fins brazed to flat tubes with internal turbulators to maximize surface-area-to-volume ratios above 1000 m²/m³. Its primary purpose is maintaining optimal operating temperatures for engines, batteries, transmissions, and cabin climate systems across varying load conditions. Charge air cooler and battery thermal management segments are expanding fastest as turbocharged engines and electric vehicles multiply thermal loads per vehicle. Aluminum material configurations dominate production volumes due to weight reduction mandates, though copper-brass hybrids retain margin pools in heavy-duty aftermarket channels where durability premiums command pricing power.
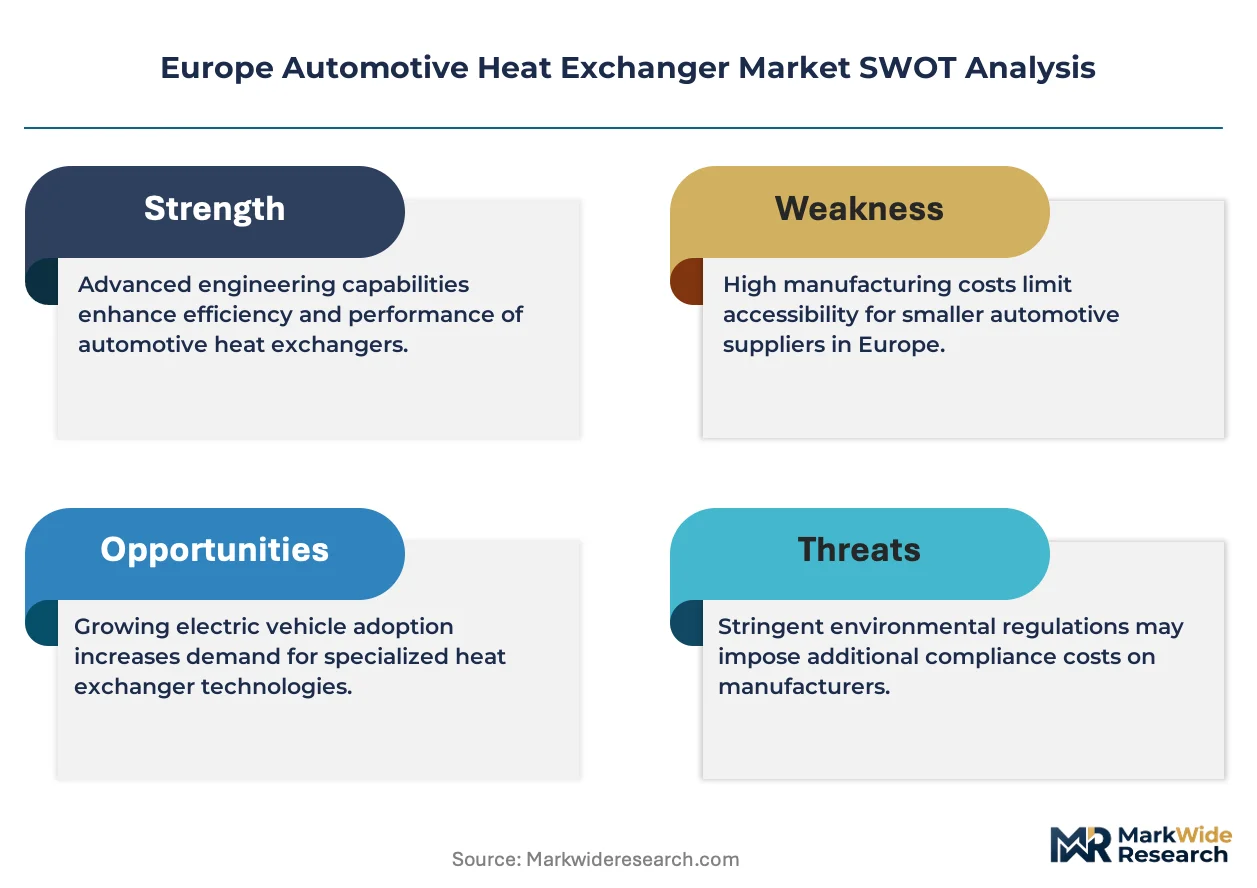
The EU Green Deal and Euro 7 standards are forcing OEMs to redesign cooling circuits for lower refrigerant leakage and higher energy recovery, directly shaping product specifications and validation protocols. ECHA REACH restrictions on fluorinated greenhouse gases are compressing supply chains toward CO₂-based and low-GWP refrigerant-compatible heat exchanger designs. Stakeholders must monitor how the EU AI Act and embedded software requirements reshape thermal system control architectures and supplier qualification timelines.
Market Dynamics
The EU Green Deal and Euro 7 emission standards are forcing OEMs to redesign cooling circuits for lower refrigerant leakage and higher energy recovery, directly compressing supplier margins while demanding simultaneous thermal efficiency gains across internal combustion and electric powertrains.
Growth Catalysts
- EV thermal management demand:Battery electric vehicles require multi-circuit thermal architectures that integrate cabin comfort, battery conditioning, and power electronics cooling into unified systems.
- REACH F-Gas Regulation:ECHA restrictions on fluorinated greenhouse gases are accelerating heat exchanger redesigns compatible with CO₂ and low-GWP refrigerants across European OEM platforms.
- German manufacturing corridor concentration:The Stuttgart-to-Wolfsburg production belt generates concentrated procurement volumes that reward localized supplier footprints with logistics cost advantages.
Market Restraints
- Aluminum price volatility:Raw material input costs for brazed aluminum heat exchanger cores fluctuate with energy-intensive smelting economics, compressing margin visibility for tier-two suppliers.
- Supplier concentration in Southern Germany:A narrow geographic band of specialized brazing equipment manufacturers creates single-source vulnerability for European heat exchanger fabricators.
- Copper-brass substitution ceiling:Weight reduction mandates cap the addressable market for durable copper-brass architectures in heavy-duty aftermarket channels despite their thermal performance advantages.
Strategic Opportunities
- Poland and Czech Republic manufacturing:Lower labor cost structures in Central European automotive clusters offer assembly relocation potential for standardized heat exchanger modules.
- Thermal system software integration:The EU AI Act's embedded software requirements create openings for heat exchanger suppliers to capture value through intelligent control module partnerships.
- Second-life battery cooling:Stationary energy storage applications in Germany and the Netherlands require repurposed automotive thermal management expertise for grid-scale battery conditioning systems.
Industry Challenges
- Brazing technician scarcity:Controlled atmosphere brazing expertise is concentrating among aging workforces in Baden-Württemberg, constraining production scaling for new entrant suppliers.
- Euro 7 validation timelines:Compressed certification cycles for refrigerant leakage testing are extending engineering resource commitments without corresponding revenue recognition acceleration.
- Multi-refrigerant platform complexity:Simultaneous engineering for R-134a, R-1234yf, and CO₂ systems fragments R&D spending across incompatible sealing and pressure vessel specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Heat Exchanger Market |
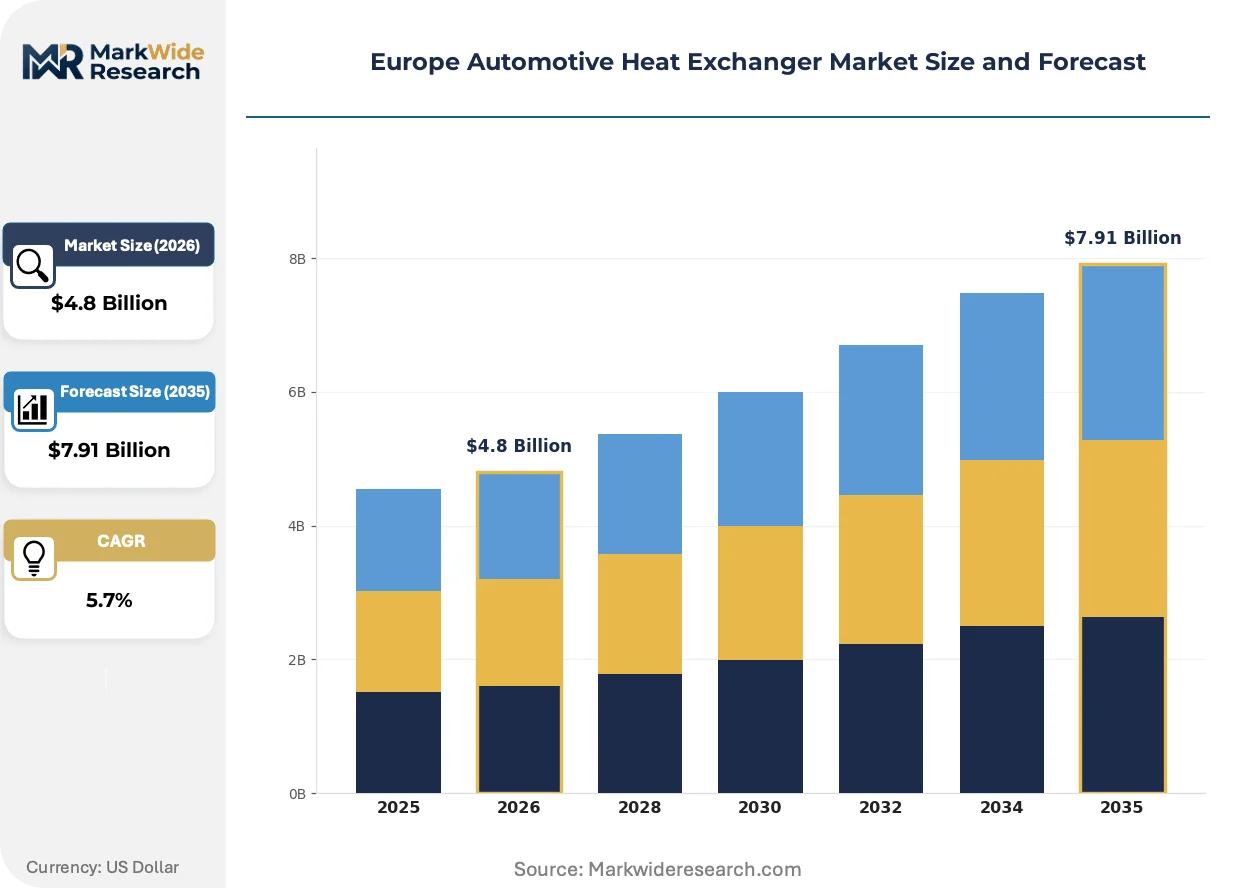
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiator, Oil Cooler, Heater Core, Charge Air Cooler Material: Aluminum, Copper, Brass, Plastic Technology: Conventional, Hybrid, Electric, Turbocharged End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators |
| Companies Covered | Valeo SA, Modine Manufacturing Company, Mahle GmbH, Dana Incorporated, Behr Hella Service GmbH, Bosch Mobility, DENSO Corporation, BorgWarner Inc., Hanon Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Heat Exchanger Market Shifts & Advancements
Heat exchanger architectures are fragmenting into application-specific thermal modules as electric vehicle platforms displace unified engine-radiator designs, while regulatory pressure on refrigerant chemistry forces concurrent materials science adaptation.
Micro-channel aluminum tubing with internal turbulators is modularizing battery cold plate designs across European EV platforms. Tier-one suppliers are adopting standardized manifold interfaces that enable rapid configuration changes between pouch and cylindrical cell formats. This standardization is compressing development lead times for new vehicle programs while locking in supplier relationships through interface patent portfolios.
ECHA REACH restrictions on fluorinated greenhouse gases are mandating heat exchanger pressure vessel ratings above 100 bar for transcritical CO₂ systems. European OEMs are qualifying dual-refrigerant architectures that maintain R-1234yf compatibility for export markets while deploying CO₂ in domestic European configurations. The battery thermal management segment bears the highest compliance cost burden due to its sensitivity to refrigerant thermodynamic properties.
Fleet operators in Germany and France are unbundling thermal system service contracts from vehicle procurement agreements, creating direct aftermarket relationships with component suppliers. This disintermediation is compressing dealer channel margins while rewarding heat exchanger manufacturers with diagnostic and predictive maintenance capabilities. The shift is most visible in commercial vehicle segments where total cost of ownership contracting dominates procurement evaluation.
Europe Automotive Heat Exchanger Market Segmentation
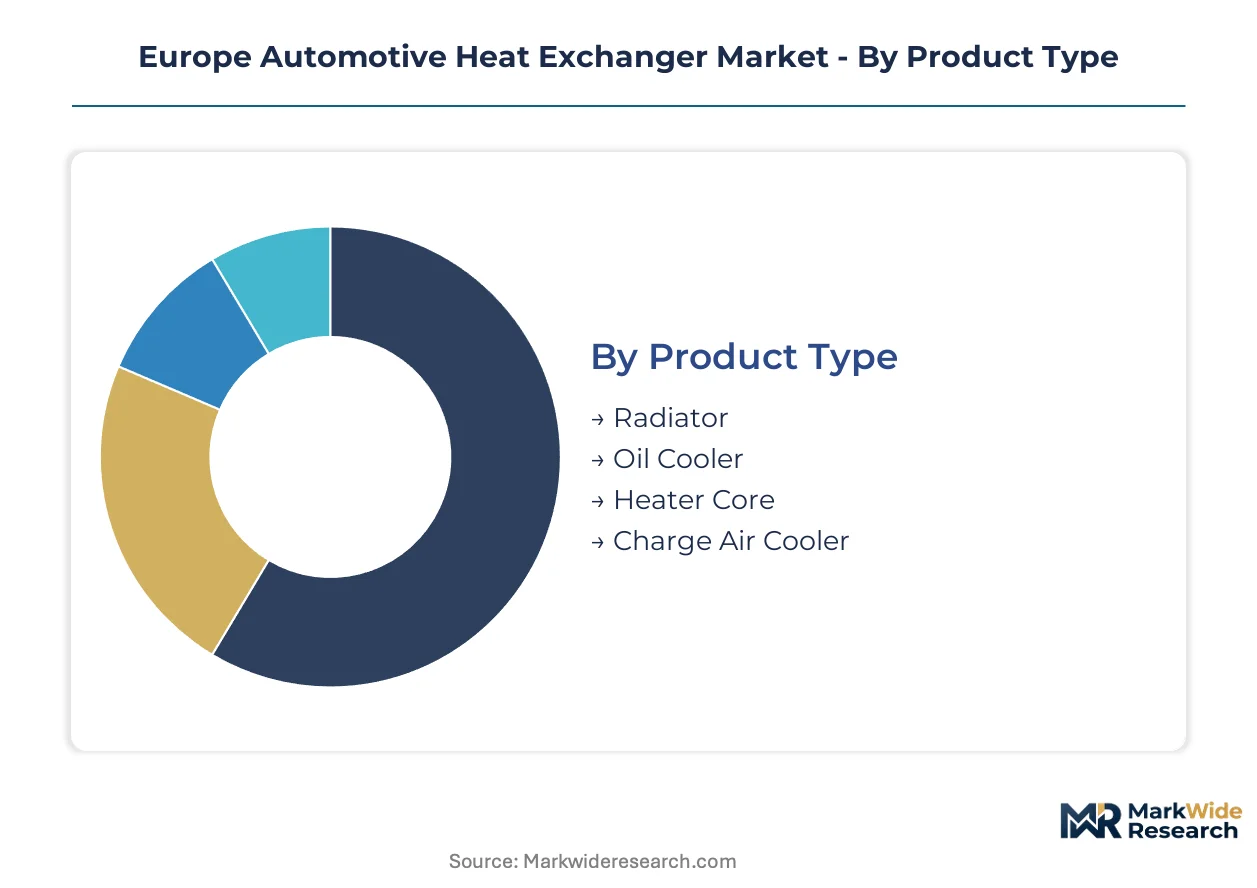
Heat exchanger procurement patterns diverge sharply across European automotive supply chains. Product specifications, material choices, and technology integration levels each create distinct margin pools and supplier qualification barriers that reshape competitive positioning.
Product Type:
Standardization dominates high-volume radiator production while charge air coolers and battery thermal modules demand application-specific engineering.
- Radiator:Brazed aluminum cores with louvered fins dissipate engine coolant heat across conventional internal combustion platforms. German OEMs in the Stuttgart corridor source these through long-term frame contracts that lock in annual volume commitments and compress spot-market participation.
- Charge Air Cooler:Compact aluminum heat exchangers reduce compressed air temperature before cylinder intake, enabling higher boost pressures in downsized turbocharged engines. European powertrain electrification is accelerating demand as hybrid thermal loads combine engine cooling with battery conditioning in single integrated circuits.
- Oil Cooler:Plate-fin or shell-and-tube configurations manage transmission and power electronics lubricant temperatures.
- Heater Core:Cabin heat delivery modules integrated into HVAC distribution boxes.
Most installed capacity flows through Radiator. Expansion is steepest in Charge Air Cooler.
Material:
Weight reduction mandates push aluminum penetration while durability requirements in commercial vehicle channels sustain copper-brass hybrids.
- Aluminum:Vacuum-brazed aluminum alloys achieve surface-area-to-volume ratios exceeding 1000 m²/m³ for powertrain and battery cooling applications. The EU Green Deal's CO₂ fleet emission targets make aluminum the default specification for new European passenger vehicle platforms.
- Copper:Superior thermal conductivity and corrosion resistance command aftermarket premiums in heavy-duty segments where service life expectations exceed 15 years.
- Brass:Marine and industrial vehicle applications retain brass-tube construction for mechanical robustness.
- Plastic:Polyamide end tanks and structural housings reduce galvanic corrosion risks in multi-material assemblies.
Volume concentrates in Aluminum. Value capture is climbing fastest in Copper.
Technology:
Thermal architecture complexity escalates from conventional single-circuit designs toward multi-zone systems serving electrified powertrains.
- Electric:Battery cold plates, power electronics chillers, and integrated thermal management modules require precision temperature control within ±2°C for cell longevity. ECHA F-Gas Regulation compliance costs are highest here due to refrigerant thermodynamic sensitivity.
- Turbocharged:Intercooling and charge air management multiply heat rejection requirements per unit displacement. Downsized gasoline engines across French and Italian OEM portfolios sustain procurement volumes despite electrification headwinds.
- Conventional:Engine radiator and heater core configurations for internal combustion architectures.
- Hybrid:Dual-mode thermal systems switching between engine waste heat and electric heating elements.
Production gravity centers on Electric. Steepest volume gains are appearing in Turbocharged.
End User:
Procurement concentration varies from consolidated OEM frame agreements to fragmented aftermarket channels with diverging service requirements.
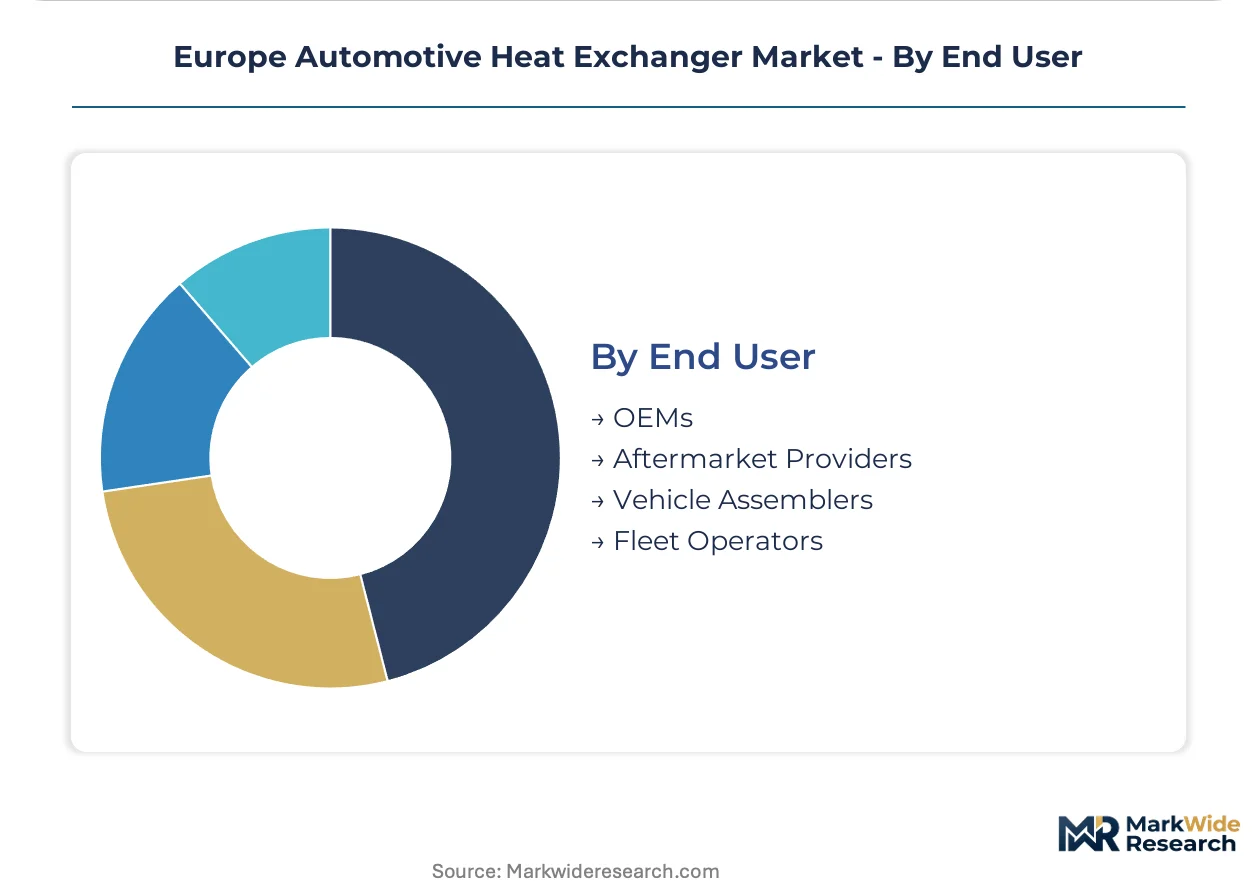
- OEMs:Volkswagen Group, Stellantis, and BMW specify heat exchangers through integrated thermal system suppliers rather than direct component procurement. Platform standardization across multiple nameplates rewards suppliers with validated manufacturing processes.
- Fleet Operators:German and French commercial vehicle fleets are unbundling thermal system service contracts from vehicle acquisition, creating direct component supplier relationships. Predictive maintenance capabilities and diagnostic tool integration determine supplier selection.
- Aftermarket Providers:Independent distributors serving collision repair and wear-item replacement.
- Vehicle Assemblers:Contract manufacturers and niche producers purchasing thermal modules.
Contract value concentrates with OEMs. Relationship restructuring is advancing fastest among Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production maps as suppliers relocate assembly to jurisdictions with lower compliance costs while maintaining proximity to German OEM engineering centers. Labor cost differentials between Western and Central Europe now exceed the logistics premium for just-in-time delivery to Stuttgart and Wolfsburg.
Germany
Volkswagen Group and BMW procurement specifications dominate thermal module demand across the Stuttgart-to-Wolfsburg corridor. The KBA enforces Euro 7 pre-certification timelines that compress supplier engineering cycles. Baden-Württemberg hosts the densest concentration of controlled atmosphere brazing equipment in Europe.
Poland
Lower labor cost structures attract standardized heat exchanger assembly from German tier-one suppliers. The Polish Investment and Trade Agency offers automotive sector incentives that offset REACH compliance investments. The Silesian automotive cluster near Katowice is accumulating battery thermal management production capacity.
Czech Republic
Skoda Auto and Hyundai Motor Manufacturing Czech generate concentrated procurement volumes for compact radiator and charge air cooler modules. Czech environmental regulations align with EU Green Deal implementation schedules without additional national overlays. The Ostrava industrial region is emerging as a secondary brazing equipment hub.
France
Stellantis thermal system specifications diverge from German OEM platforms, fragmenting supplier validation requirements. ANSM and CNIL oversight of embedded thermal control software adds compliance layers beyond hardware certification. The Auvergne-Rhône-Alpes region around Lyon sustains aluminum processing capacity for HVAC component supply.
Netherlands
Second-life battery cooling demand from stationary energy storage projects creates aftermarket thermal management relationships. Dutch environmental permitting accelerates CO₂ refrigerant system validation compared to German federal-state complexity. The Eindhoven-Brabant corridor hosts power electronics cooling R&D for European EV platforms.
Europe Automotive Heat Exchanger Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated thermal system suppliers capturing OEM frame agreements while component fabricators serve aftermarket channels. The supplier base concentrates among European-headquartered firms with brazing equipment captive in Southern Germany. Three archetypes dominate: full-system integrators, component specialists with patent-protected manifold interfaces, and Central European cost-optimized assemblers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms position for Euro 7 validation timelines.
Among French-origin suppliers, Valeo SA exemplifies the full-system integrator archetype through its European manufacturing footprint. Mahle GmbH occupies a position among German component specialists with R&D intensity in compact architectures. Bosch Mobility anchors the premium tier through channel control relationships with German vehicle assemblers.
| Leading Market Players |
|---|
| Valeo SA |
| Modine Manufacturing Company |
| Mahle GmbH |
| Dana Incorporated |
| Behr Hella Service GmbH |
| Bosch Mobility |
| DENSO Corporation |
| BorgWarner Inc. |
| Hanon Systems |
| Others |
Supply & Pricing Matrix
Aluminum ingot costs cascade through vacuum-brazing operations in Baden-Württemberg before stratifying into three-tier pricing structures across German OEM frame contracts, Polish assembly subcontracts, and aftermarket distributor markups.
Pricing Analysis
Distributor markups compress as fleet operators unbundle thermal service contracts and source charge air coolers and battery cold plates directly from tier-one fabricators. Three-tier pricing structure across premium, standard, and economy levels separates validated CO₂-compatible designs from legacy R-134a architectures and unbranded aftermarket replacements. Price differentiation rests on Euro 7 pre-certification status and REACH F-Gas compliance documentation. Cost compression in standard-tier modules is intensifying because Polish and Czech assembly plants are capturing frame contract volumes previously held by Southern German fabricators. Aftermarket providers show highest price sensitivity, while OEM platform engineering teams prioritize thermal efficiency validation over unit cost.
Supply Chain Analysis
Controlled atmosphere brazing equipment rests on specialized machinery producers concentrated in Germany, Switzerland, and Austria. Aluminum alloy feedstock draws from Norwegian smelters and German rolling mills, while copper-brass tube stock sources from Finnish and Belgian semi-finished metal processors. Single-source vulnerability concentrates in Baden-Württemberg brazing furnace maintenance expertise, constraining capacity expansion for new market entrants. Distribution runs through just-in-time pipelines to Stuttgart and Wolfsburg assembly corridors, with secondary channels feeding independent aftermarket distributors across France and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in battery thermal management modules where REACH F-Gas compliance investments create certification barriers that sustain premium pricing for validated suppliers.
For Market Incumbents: Extend patent-protected manifold interface portfolios to lock in platform standardization across multiple OEM electrification programs. Deepen backward integration into aluminum alloy rolling capacity to offset ingot price volatility. Prioritize controlled atmosphere brazing technician apprenticeship pipelines in Baden-Württemberg to preempt workforce scarcity constraints on production scaling. For New Entrants and Emerging Players: Capture second-life battery cooling opportunities in Dutch and German stationary energy storage installations where automotive thermal expertise transfers to grid-scale applications. Target Poland and Czech Republic assembly locations for standardized radiator modules where labor cost structures undercut German fabrication economics. Pursue direct fleet operator relationships in French commercial vehicle segments where service contract unbundling creates bypass opportunities around established dealer channels. For Investors and Strategic Acquirers: Roll-up economics work for Central European cost-optimized assemblers because German OEMs are fragmenting procurement across multiple qualified suppliers to mitigate concentration risk. Five-to-ten year viability hinges on CO₂ refrigerant system validation capabilities rather than legacy R-1234yf exposure. Monitor ECHA regulatory guidance on fluorinated greenhouse gas phase-down timelines as the primary inflection signal for asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| CO₂ Refrigerant System Validation | ECHA REACH F-Gas compliance locks in premium tier positioning for pressure-rated architectures above 100 bar. |
| Platform Standardization Partnerships | Manifold interface patents across multiple OEM electrification programs secure multi-year frame contract volumes. |
| Central European Manufacturing Footprint | Polish and Czech assembly locations capture cost advantages while maintaining just-in-time delivery to German corridors. |
| Thermal System Software Integration | EU AI Act embedded control requirements open value capture opportunities beyond hardware fabrication margins. |
| Second-Life Battery Cooling Expansion | Stationary energy storage applications in the Netherlands and Germany repurpose automotive thermal management expertise. |
Research Methodology
Multiple input streams — OEM platform engineering specifications, tier-one supplier production data, and ECHA regulatory filings — were reconciled through structured interviews with thermal system procurement managers, controlled atmosphere brazing equipment manufacturers, and fleet operator maintenance directors. Secondary validation drew from KBA vehicle registration databases, EU Green Deal implementation progress reports, and REACH restriction proposal documentation. Bottom-up build of charge air cooler and battery thermal module volumes was cross-checked against top-down OEM production forecasts across the analysis window.
Historical shipment patterns were cross-referenced against panel input from platform engineers at Volkswagen Group, Stellantis, and BMW to establish content-per-vehicle assumptions across propulsion architectures. Segmentation modeling incorporated vehicle class, thermal circuit complexity, refrigerant chemistry compatibility, and regional production cluster. CAGRs were derived from slope analysis of technology adoption curves rather than linear extrapolation. Forecast inputs included Euro 7 pre-certification timeline compressions and ECHA F-Gas phase-down schedule assumptions.
Aluminum price volatility, brazing technician availability constraints, and multi-refrigerant platform engineering fragmentation are the dominant revision risks to volume and value projections. A small set of named triggers — ECHA regulatory acceleration, OEM platform consolidation decisions, and Central European labor cost shifts — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Composite Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Automotive Actuators Market
Automotive Components
Automotive Plastic Components Market
Automotive Components
Auto Fender Market
Automotive Components
Automotive Polycarbonate Glazing Market
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Automotive Metal Stamping Components Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Europe Automotive Relay Market
Automotive Components
Middle East and Africa Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Solar Control Glass Market