
 Beryllium Copper for Automobile Market | 2026-2036
Beryllium Copper for Automobile Market Size, Share, and Industry Trends Forecast 2026-2036
Beryllium Copper for Automobile Market Insights
Electric powertrain electrification is consolidating demand for beryllium copper within automotive connector systems. Materion leverages captive refining capacity to secure high-purity feedstock for precision alloy production. NGK Metals anchors Asian supply chains through integrated strip and wire manufacturing in Japan. IBC Advanced Alloys differentiates via aerospace-certified processes that transfer directly to automotive quality tiers.
Beryllium copper denotes a precipitation-hardened alloy containing approximately 0.5-3% beryllium by weight, delivering tensile strengths exceeding 1,400 MPa after age-hardening heat treatment while retaining conductivity values near 20-60% IACS depending on temper. Automotive engineers specify this material for miniature springs and electrical contacts requiring fatigue resistance across million-cycle operating lives. Alloy sheets and precision rods command the deepest margin pools, as cold-rolled strip products with sub-millimeter thickness tolerances serve high-density connector packaging in inverter modules. Electrical contacts and springs represent the fastest-growing application cluster, driven by rising pin counts in 800-volt architectures and the thermal cycling demands of silicon carbide power electronics.
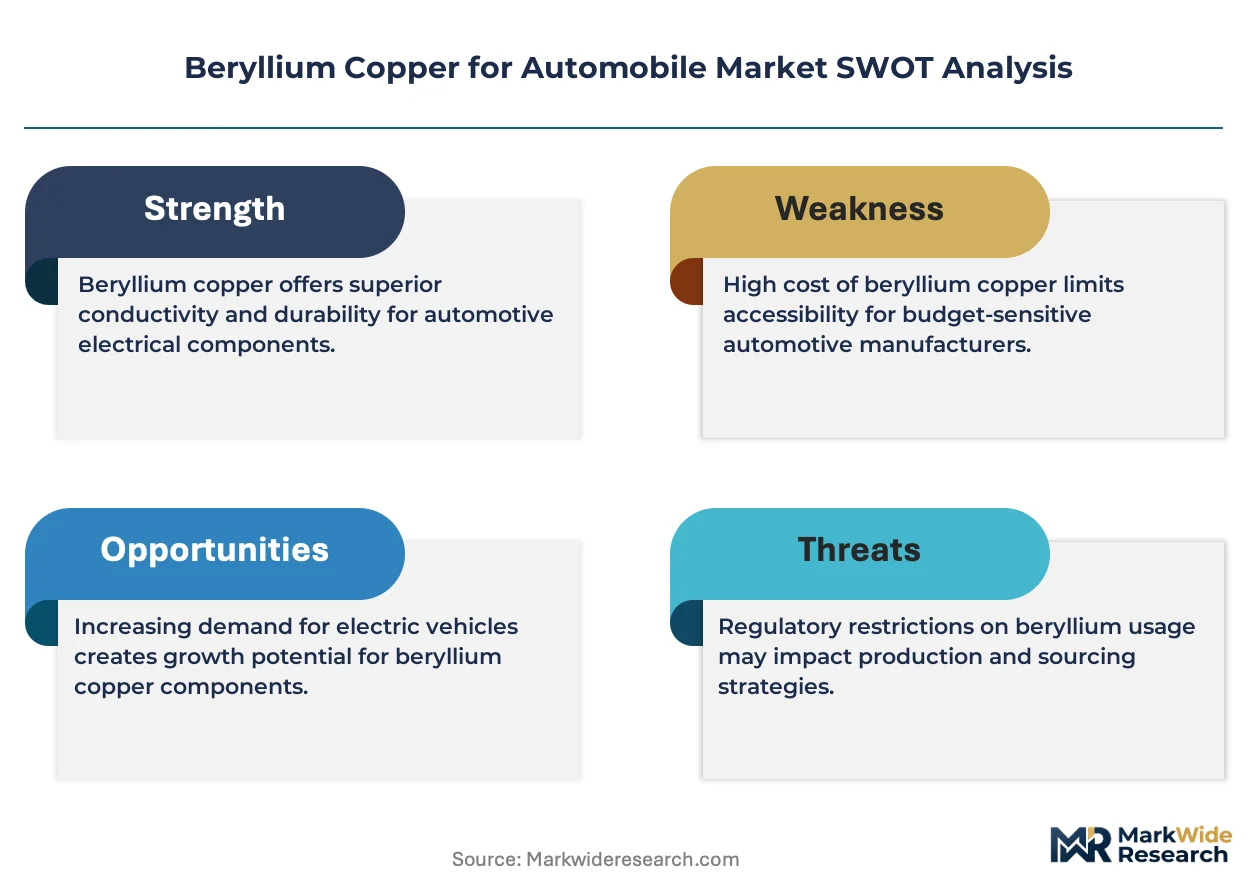
EPA toxicity reporting requirements under TSCA Section 8(a) obligate U.S. processors to document beryllium content in imported alloy articles, while REACH candidate list scrutiny in Europe pressures substitution analysis for contained beryllium above threshold concentrations. Japan's METI maintains JIS H 3800 alloy standards that govern automotive supplier qualification protocols across Pacific Rim manufacturing networks. Stakeholders must monitor evolving substance restriction timelines and pre-qualify alternative alloy formulations before regulatory thresholds disrupt component sourcing.
Market Dynamics
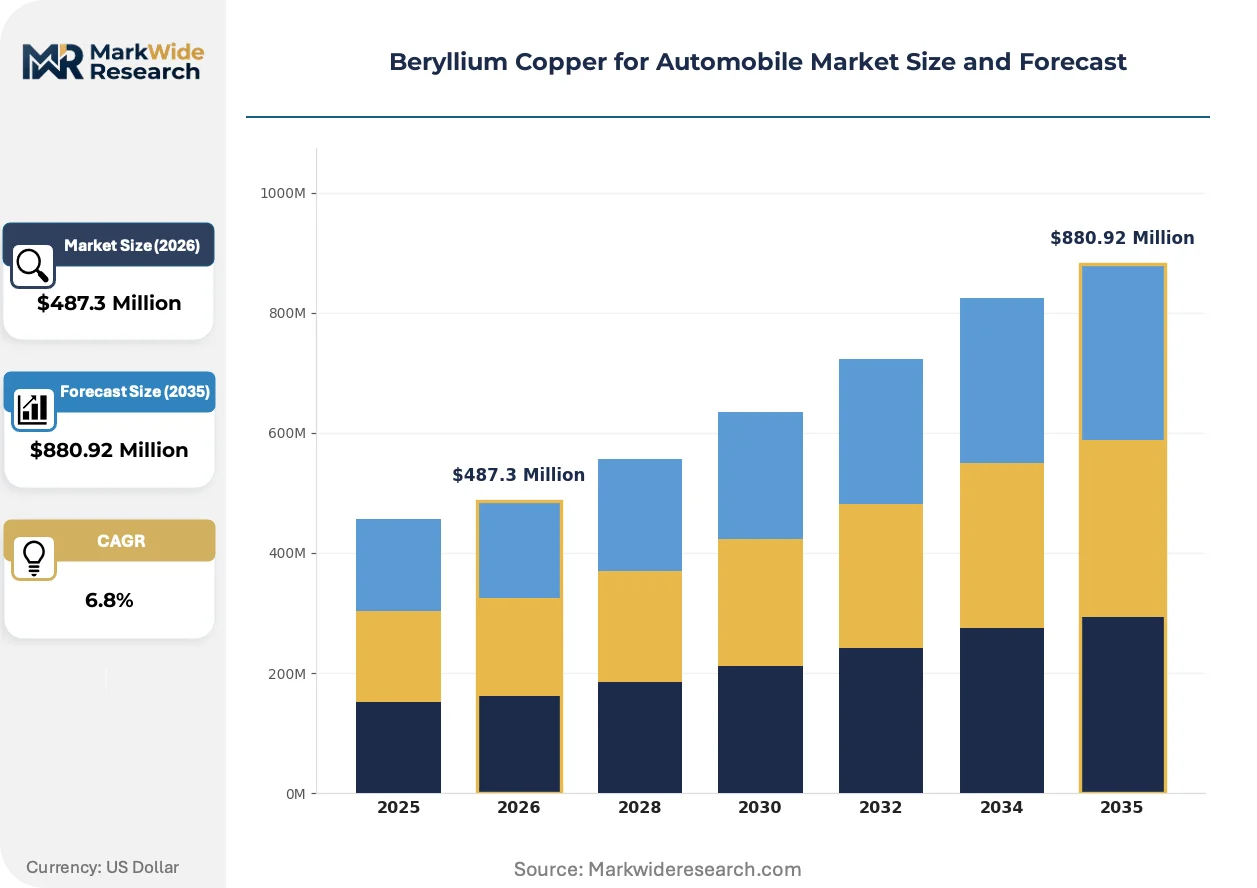
Electric powertrain electrification is consolidating beryllium copper demand as 800-volt architectures replace legacy 400-volt systems, forcing automakers to source fatigue-resistant alloys for high-density connector packaging in silicon carbide inverter modules.
Growth Catalysts
- REACH substance compliance:European automotive Tier 1 suppliers pre-qualify beryllium copper alloys ahead of candidate list restrictions, locking in approved material streams for next-generation EV platforms.
- Silicon carbide power electronics:Wide-bandgap semiconductor deployment generates thermal cycling stresses that only precipitation-hardened copper-beryllium alloys withstand across million-cycle operating lives.
- Germany's inverter manufacturing corridor:Precision alloy strip demand concentrates along the Stuttgart-Munich supplier belt as domestic OEMs localize 800-volt powertrain component sourcing.
Market Restraints
- Beryllium oxide toxicity:EPA TSCA Section 8(a) reporting obligations increase compliance overhead for U.S. processors importing alloy articles, elevating administrative costs relative to non-beryllium alternatives.
- High-purity feedstock concentration:Captive refining capacity limits constrain non-integrated alloy producers, creating supply vulnerability for automotive stampers without backward-linked material security.
- Phosphor bronze substitution:Lower-cost copper-tin alloys capture standard-duty electrical contact applications where conductivity requirements permit reduced fatigue resistance.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives attract precision alloy strip producers to establish localized supply for emerging EV assembly operations.
- Charging infrastructure connector standardization:IEC 62196 and CCS2 protocol harmonization creates specification pull for uniform high-reliability contact materials across multiple OEM programs.
- Additive manufacturing qualification:Powder bed fusion of copper-beryllium grades enables topology-optimized spring geometries impossible through conventional stamping.
Industry Challenges
- Age-hardening process control:Precipitation heat treatment windows measured in minutes demand continuous furnace monitoring to prevent over-aging and conductivity degradation.
- JIS H 3800 certification timelines:Japanese automotive supplier qualification protocols extend 18-24 months for new alloy temper approvals, compressing product development cycles.
- Scrap segregation complexity:Beryllium-containing alloy recycling requires dedicated handling streams to prevent cross-contamination with standard copper scrap circuits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beryllium Copper for Automobile Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloy Sheets, Precision Rods, Strips, Tubes, Wires Application: Electrical Contacts, Springs, Bushings, Connectors, Valve Seats End User: OEM Manufacturers, Component Suppliers, Aftermarket Providers, Automotive Assemblers Processing Method: Hot Rolling, Cold Rolling, Forging, Machining, Heat Treatment |
| Companies Covered | Materion, NGK Metals, IBC Advanced Alloys, Belmont Metals, Ampco Metal, Aviva Metals, Wieland-Werke, Mitsubishi Shindoh, National Bronze & Metals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beryllium Copper for Automobile Market Trends and Innovations
Material specification patterns across automotive electrical systems are pivoting toward alloys that survive combined thermal-electrical-mechanical stresses. Engineers now prioritize million-cycle fatigue data over initial conductivity metrics when selecting contact materials.
Sub-millimeter cold-rolled strip products are consolidating market share as connector pin densities rise in 800-volt inverter architectures. Automakers specify these precision thickness tolerances for high-density packaging in next-generation power electronics modules. The shift is compressing demand for conventional wire and rod formats toward engineered strip geometries.
ECHA REACH candidate list scrutiny is tightening substitution analysis requirements for contained beryllium above threshold concentrations. European component importers now conduct pre-emptive material risk assessments to avoid supply disruption from future restriction timelines. German Tier 1 suppliers have established dedicated compliance teams to monitor SVHC updates and pre-qualify alternative formulations.
Automotive procurement teams are compressing supplier qualification cycles as EV platform launches accelerate. Direct alloy producer relationships are displacing traditional distributor channels for high-volume precision strip programs. This pattern is most visible in Japan's keiretsu supplier networks, where METI-guided JIS standards enforce integrated quality protocols across Pacific Rim manufacturing clusters.
Beryllium Copper for Automobile Market Segmentation
Automotive beryllium copper procurement splits across material form, functional application, and supply chain position. Each segmentation axis carries distinct margin structures and qualification barriers that shape supplier selection and contract duration.
Product Type:
Upgrade cycles in EV powertrain packaging are forcing dimensional specification shifts across all alloy formats.
- Alloy Sheets:Cold-rolled precipitation-hardened plates deliver the sub-millimeter thickness tolerances required for high-density inverter module housings. German Tier 1 suppliers along the Stuttgart-Munich corridor source these formats for 800-volt silicon carbide power electronics where thermal cycling resistance is non-negotiable.
- Precision Rods:Age-hardened round stock machined to tight concentricity specifications serves high-current busbar applications and structural fasteners in battery pack assemblies. Japan's METI-guided JIS H 3800 certification protocols extend 18-24 month qualification timelines for new rod temper approvals, compressing product development cycles for automotive stampers.
- Strips:Narrow-gauge cold-rolled products feed progressive die operations for miniature connector contacts.
- Tubes:Seamless hollow sections accommodate fluid-cooled power module jackets.
- Wires:Drawn round and shaped conductors for high-flexibility harness applications.
Volume placements concentrate in precision rods; the faster expansion belongs to alloy sheets.
Application:
Functional specification patterns pivot toward million-cycle fatigue survival over initial conductivity metrics.
- Electrical Contacts:Miniature spring fingers and pin interfaces in charging couplers and inverter connectors demand the fatigue resistance that only precipitation-hardened copper-beryllium alloys provide across million-cycle operating lives. Silicon carbide power electronics deployment generates thermal cycling stresses that phosphor bronze substitutes cannot withstand.
- Springs:Retention clips and contact force elements in high-voltage interlock systems require consistent modulus of elasticity across temperature extremes. ECHA REACH candidate list scrutiny pressures substitution analysis for contained beryllium above threshold concentrations, locking in pre-qualified material streams for European EV platforms.
- Bushings:Wear-resistant bearing surfaces for steering and suspension linkages.
- Connectors:Housing and terminal assemblies for power distribution modules.
- Valve Seats:Heat-dissipating seals in thermal management circuits.
Electrical contacts command the deepest margin pools; springs are climbing the fastest as pin densities multiply in 800-volt architectures.
End User:
Procurement authority is consolidating at the platform-program level as EV launch cycles compress.
- OEM Manufacturers:Volkswagen, BMW, and Mercedes-Benz parent entities specify approved vendor lists for precision alloy strip programs, displacing traditional distributor channels. Direct alloy producer relationships now govern high-volume supply agreements with 3-5 year lock-in periods.
- Component Suppliers:Bosch, Continental, and ZF Friedrichshafen stamp connector subassemblies from certified alloy feedstock, absorbing JIS H 3800 and EPA TSCA Section 8(a) compliance overhead into landed costs.
- Aftermarket Providers:Independent distributors service repair and replacement demand for legacy internal combustion platforms.
- Automotive Assemblers:Contract manufacturers integrate pre-kitted connector modules into final powertrain assembly.
Contract concentration sits with component suppliers; OEM direct sourcing is gaining share fastest as platform standardization advances.
Processing Method:
Thermomechanical history determines final property portfolios and qualification tier placement.
- Hot Rolling:Initial breakdown of cast ingots establishes baseline workability for subsequent precision forming operations.
- Cold Rolling:Thickness reduction below recrystallization temperature develops the sub-millimeter tolerances and surface finish required for high-density connector packaging. Age-hardening process control demands continuous furnace monitoring to prevent over-aging and conductivity degradation.
- Forging:Closed-die forming of complex structural geometries for high-stress automotive applications.
- Machining:Finish operations on heat-treated components to achieve final dimensional specifications.
- Heat Treatment:Precipitation hardening in controlled-atmosphere furnaces develops peak strength-conductivity combinations.
Process investment concentrates in cold rolling; heat treatment capacity expansion is steepest as alloy producers defend specification tier positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive scheme for auto components is concentrating precision alloy manufacturing investment in emerging EV supply corridors. Germany's Stuttgart-Munich belt anchors European demand for high-reliability connector materials. Japan's keiretsu networks enforce integrated quality protocols across Pacific Rim manufacturing clusters.
United States
EPA TSCA Section 8(a) reporting obligations shape compliance overhead for processors importing beryllium-containing alloy articles. Domestic OEMs specify approved vendor lists for precision strip programs with multi-year lock-in periods. Michigan and Ohio manufacturing corridors host stamping operations serving Detroit Three 800-volt platform launches.
Germany
Volkswagen, BMW, and Mercedes-Benz parent entities drive specification pull for sub-millimeter cold-rolled strip in silicon carbide inverter modules. ECHA REACH candidate list scrutiny pressures pre-emptive material risk assessments for contained beryllium above threshold concentrations. The Stuttgart-Munich supplier belt concentrates Tier 1 precision alloy demand for localized powertrain component sourcing.
Japan
METI-guided JIS H 3800 certification protocols extend 18-24 month qualification timelines for new alloy temper approvals. Keiretsu supplier networks enforce backward-linked material security through integrated quality hierarchies. Kanto and Kansai manufacturing clusters anchor Pacific Rim supply chains for automotive electrical contact materials.
China
Domestic EV platform launches accelerate procurement cycle compression for high-density connector packaging materials. GB standards and MIIT oversight govern automotive supplier qualification protocols across Yangtze River Delta manufacturing networks. Shanghai and Shenzhen precision metalworking clusters serve domestic OEM silicon carbide inverter assembly operations.
India
PLI scheme incentives attract precision alloy strip producers to establish localized supply for emerging EV assembly operations. BIS standards and DGFT import regulations shape material compliance requirements for automotive component sourcing. Maharashtra and Gujarat manufacturing corridors concentrate domestic stamping capacity for next-generation powertrain connector modules.
Beryllium Copper for Automobile Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated alloy producers commanding premium-tier positioning in precision strip markets. The vendor base concentrates around captive refining capacity holders and JIS-certified fabricators with established automotive qualification histories. Three archetypes dominate: backward-integrated primary producers, precision cold-rolling specialists, and aerospace-certified processors transferring quality protocols to automotive tiers. Capacity expansion and strategic partnerships represent the dominant competitive moves as EV platform launches compress supplier qualification cycles.
Among North American integrated producers, Materion anchors the premium-tier vector through captive refining operations. NGK Metals exemplifies the Asia-Pacific keiretsu model with METI-guided certification continuity. IBC Advanced Alloys occupies a position bridging aerospace and automotive quality tiers. These three represent distinct geographic and structural archetypes rather than direct substitutability.
| Leading Market Players |
|---|
| Materion |
| NGK Metals |
| IBC Advanced Alloys |
| Belmont Metals |
| Ampco Metal |
| Aviva Metals |
| Wieland-Werke |
| Mitsubishi Shindoh |
| National Bronze & Metals |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between JIS H 3800-certified precision strip and non-certified commodity alloys manifests in both pricing premiums and supply chain exclusivity. German Tier 1 suppliers pay lead-time premiums for METI-governed material streams while spot-market buyers absorb EPA TSCA Section 8(a) compliance overhead into landed costs.
Pricing Analysis
Short lead-time premiums for JIS H 3800-certified precision strip command substantial markups over spot-market alternatives with extended qualification timelines. Three-tier pricing structure across aerospace-certified, automotive-qualified, and industrial-grade tiers reflects beryllium content purity and fatigue-test documentation depth. Cost compression in standard-duty phosphor bronze substitutes is intensifying because conductivity requirements in 400-volt legacy platforms permit reduced fatigue resistance. Aftermarket distributors exhibit highest price sensitivity; OEM direct sourcing programs demonstrate lowest elasticity due to platform-lock-in effects.
Supply Chain Analysis
Dual-sourcing requirements mandated by Volkswagen, BMW, and Mercedes-Benz parent entities force Tier 1 stampers to qualify multiple alloy producers per program. Geographic supply concentration centers on Japan, Germany, and the United States for precision strip and rod formats. Raw material dependencies draw from captive beryllium refining capacity, high-purity copper cathode, and controlled-atmosphere heat treatment infrastructure. Single-source vulnerability concentrates in age-hardening furnace capacity with sub-minute process windows. Distribution runs through direct alloy producer relationships displacing traditional distributor channels for high-volume programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive refining capacity constraints prop pricing power for backward-integrated producers as automotive platform launches compress supplier qualification cycles.
For Market Incumbents: Anchor market position through JIS H 3800 certification continuity and dedicated heat treatment capacity expansion in Germany's Stuttgart-Munich corridor. Defend against phosphor bronze substitution by documenting million-cycle fatigue superiority in silicon carbide inverter applications. Prioritize scrap segregation infrastructure to prevent cross-contamination penalties under REACH candidate list scrutiny. For New Entrants and Emerging Players: The mid-tier pricing gap between aerospace-certified and industrial-grade alloys opens white-space targeting for automotive-qualified strip producers without full JIS pedigree. India's PLI scheme corridors offer lowest qualification barrier entry for emerging EV assembly operations. Pursue charging infrastructure connector standardization as specification pull creates uniform material demand across multiple OEM programs. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by keiretsu networks seeking backward-linked material security. Long-term viability hinges on age-hardening process control IP and automotive qualification history depth. Watch ECHA SVHC list updates as inflection indicator for substitution-driven demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Refining | Materion and NGK Metals secure high-purity feedstock against supply vulnerability. |
| JIS H 3800 Certification Investment | METI-guided protocols enforce 18-24 month qualification timelines compressing product development cycles. |
| India PLI Corridor Manufacturing Footprint | Localized precision strip supply captures emerging EV assembly operations in Maharashtra and Gujarat. |
| Silicon Carbide Power Electronics Partnership | Direct alloy producer relationships with inverter module stampers displace distributor channels. |
| Additive Manufacturing Powder Qualification | Powder bed fusion enables topology-optimized spring geometries impossible through conventional stamping. |
Research Methodology
Independent corroboration across primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, and aftermarket distributors underwrites the qualitative findings. Secondary validation draws from EPA TSCA Section 8(a) filings, METI JIS standard documentation, ECHA REACH candidate list updates, and automotive production registration databases. Bottom-up segmentation modeling triangulates against top-down alloy consumption estimates derived from EV platform launch schedules.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. The analytical framework models material form, functional application, supply chain position, and processing method as core segmentation dimensions. CAGRs derive from fitted growth curves applied to platform-specific content-per-vehicle assumptions and regional EV adoption trajectories. Silicon carbide inverter penetration rates and 800-volt architecture migration timelines serve as key forecast inputs.
Underlying measurement precision varies by segment; JIS H 3800-certified precision strip carries tighter precision than non-certified commodity grades due to documented qualification histories. Forecasts reflect assumptions regarding REACH restriction timelines, PLI scheme disbursement continuity, and thermal cycling stress specifications in next-generation power electronics. Deviation in ECHA SVHC list inclusion thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Pneumatic Valve Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
Europe Automotive Relay Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Argentina Automotive Electric Actuators Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Global Automotive Collapsible Steering Column Market
Automotive Components
Automotive Radiator Fan Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Asia-Pacific Automotive Parts and Components Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Automated Lubrication Systems Market