
 Automotive Pedals Market | 2026-2036
Automotive Pedals Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Pedals Market Intelligence
Aluminum is broadening its share in pedal bracket and arm assemblies as OEMs pursue gram-level weight reduction targets. ZF Friedrichshafen leverages its chassis systems integration expertise to bundle electronic pedal modules with braking controllers. Continental AG sustains R&D intensity in position-sensor architectures for drive-by-wire platforms. Robert Bosch GmbH dominates the electronic throttle control segment through captive semiconductor sourcing.
Automotive pedals are mechanical or electromechanical foot-operated control interfaces that translate driver input into vehicle propulsion, deceleration, or powertrain disengagement, typically incorporating stamped steel or aluminum arms, polymer pivot bushings, and Hall-effect or potentiometric position sensors with operating temperatures from minus forty to one hundred twenty degrees Celsius. Electronic pedal technology leads value generation as torque-demand encoding replaces cable linkages in hybrid and battery-electric architectures. The OEM end user channel anchors volume while aftermarket replacement concentrates in aging internal-combustion fleets across emerging economies.
The EPA tailpipe standards and NHTSA Federal Motor Vehicle Safety Standards govern pedal entrapment prevention and unintended acceleration mitigation in the United States, while ECE R79 and the EU General Safety Regulation mandate fail-safe performance for electronic accelerator controls in Europe. China's MIIT issues GB standards for electromagnetic compatibility of electronic pedal assemblies sold into domestic production. Stakeholders must monitor divergence between mechanical pedal phase-out timelines in developed markets and sustained demand for clutch pedals in manual-transmission strongholds.
Market Dynamics
Electric vehicle platform proliferation is dissolving the mechanical-cable legacy in pedal systems, forcing suppliers to reengineer torque-encoding architectures and consolidate sensor-software competencies that hybrid-era incumbents never required.
Growth Catalysts
- EU Green Deal Ecodesign Mandates:Gram-level weight reduction targets for steel-intensive assemblies are accelerating aluminum substitution in bracket and arm production.
- Intelligent Cockpit Integration:Chinese domestic automakers are scaling orders for electronic pedal modules bundled with drive-by-wire position sensors.
- EPA Tailpipe Standards:Stringent emissions thresholds are compelling OEMs to eliminate mechanical linkages in favor of electronic throttle control architectures.
Market Restraints
- Semiconductor Supply Concentration:Captive sourcing of Hall-effect sensor chips creates dependency on Taiwan and South Korean foundry capacity.
- Steel-Aluminum Price Volatility:Input cost swings for stamped metal arms compress margin buffers at tier-two bracket suppliers.
- Manual Transmission Clutch Demand:Sustained clutch pedal volumes in emerging-market ICE fleets fragment R&D resource allocation.
Strategic Opportunities
- India PLI Scheme for Auto Components:Incentive structures for advanced manufacturing are drawing electronic pedal assembly investment away from legacy mechanical production.
- Drive-by-Wire Convergence:Brake-pedal force sensors are merging with regenerative braking controllers to create unified deceleration management systems.
- Aftermarket Sensor Retrofit Channels:Aging internal-combustion fleets in Brazil and Indonesia generate replacement demand for potentiometric pedal position modules.
Industry Challenges
- ISO 26262 Functional Safety Certification:ASIL-D compliance timelines for electronic accelerator controls extend product validation cycles by fourteen to eighteen months.
- Legacy System Integration Complexity:Hybrid architectures require simultaneous support for cable-actuated and drive-by-wire pedal interfaces, doubling validation matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Pedals Market |
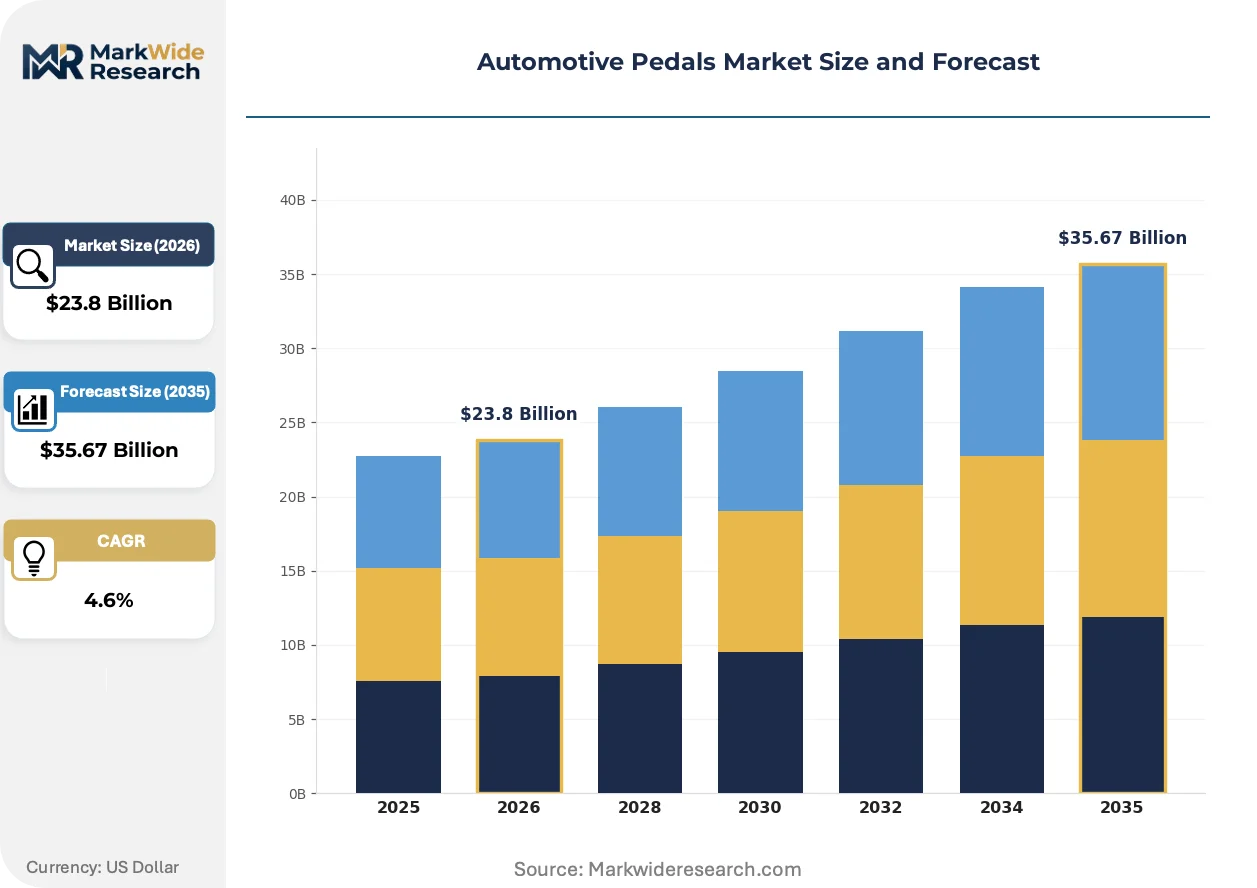
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $35.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pedal Type: Accelerator, Brake, Clutch, Dead Pedal, Footrest Technology: Mechanical, Electronic, Hydraulic, Pneumatic, Electro-Hydraulic Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy-Duty Vehicles, Two-Wheelers End User: OEMs, Aftermarket, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | ZF Friedrichshafen AG, Toyoda Iron Works Co. Ltd., Continental AG, CTS Corporation, KSR International Inc., Robert Bosch GmbH, F.TECH Inc., Shanghai Kaizhong Materials Science and Technology Co. Ltd., DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Pedals Market Strategic Shifts & Innovations
Sensor fusion and material substitution are collapsing the boundary between pedal hardware and powertrain software, redefining supplier value capture away from stamped metal toward encoded signal integrity.
Capacitive force sensing is converging with haptic feedback actuators to create non-contact pedal interfaces that eliminate mechanical pivot wear. Tier-one suppliers are piloting these modules with premium German OEMs for deployment in next-generation battery-electric platforms. The technology is converging with autonomous emergency braking systems to enable predictive pedal resistance that alerts drivers before collision events.
ECE R79 and the EU General Safety Regulation are mandating redundant position encoding and fail-safe return-to-idle protocols for all electronic accelerator controls sold in member states. Suppliers must dual-source sensor chips and implement latch-up detection circuits to satisfy type-approval requirements. The regulation most affects low-cost Asian module producers seeking European OEM qualification.
Fleet procurement departments are consolidating brake and accelerator pedal sourcing into single-supplier chassis control contracts that bundle electronic modules with steering angle sensors. Tier-one integrators are displacing standalone pedal manufacturers through this bundled pricing leverage. The shift is most visible in Chinese state-owned automaker purchasing organizations consolidating supplier panels under ZF Friedrichshafen and Continental AG framework agreements.
Automotive Pedals Market Segmentation
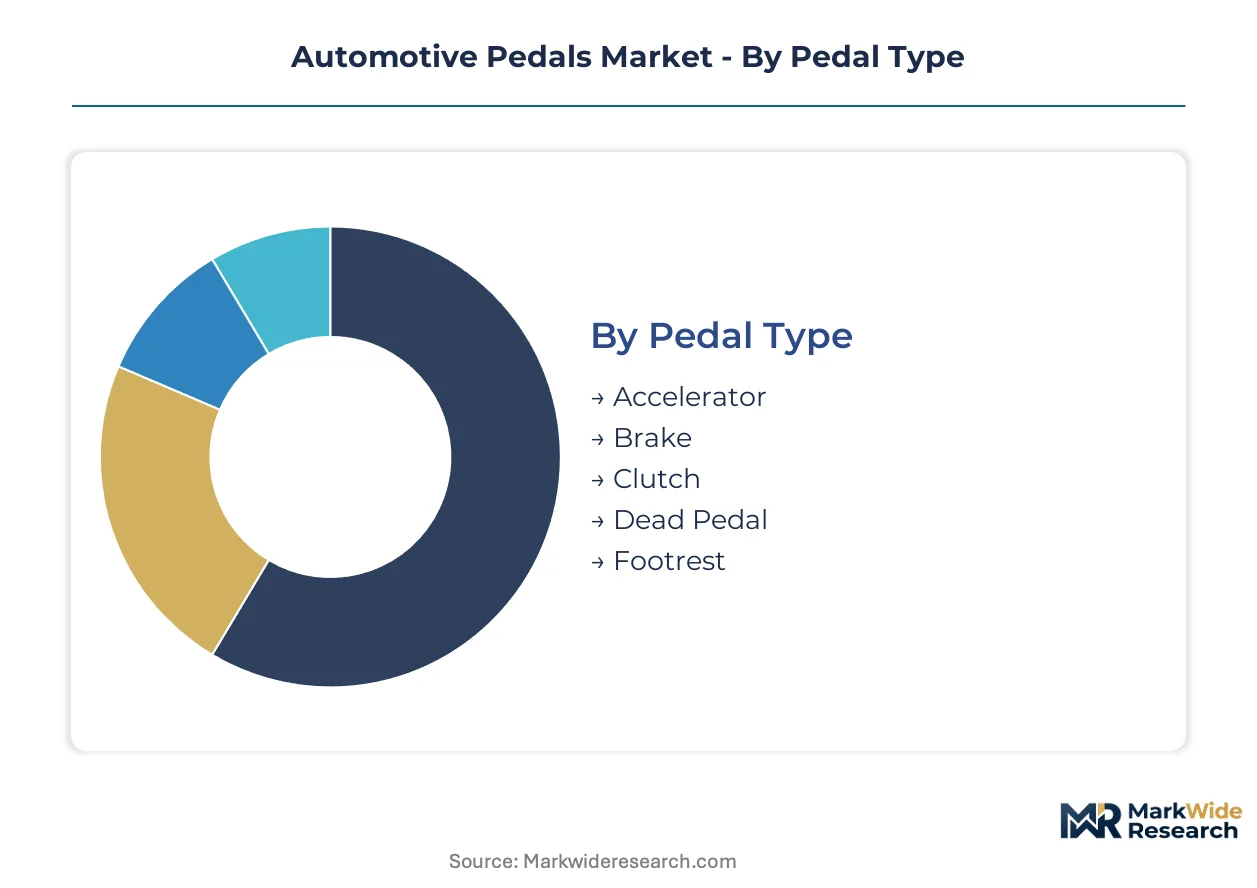
Pedal system architectures fragment across propulsion technologies, forcing suppliers to maintain parallel production lines for cable-actuated legacy platforms and torque-encoding electronic modules. Material composition and sensor integration requirements diverge sharply between segments, compressing margin structures at tier-two bracket manufacturers unable to scale across multiple technology tiers.
Pedal Type:
Supply concentration in electronic accelerator modules is reshaping procurement patterns as OEMs consolidate sourcing under chassis integration contracts.
- Accelerator:Torque-demand encoding modules integrate Hall-effect position sensors with polymer pivot bushings operating across minus forty to one hundred twenty degrees Celsius. Chinese domestic automakers are scaling orders for intelligent cockpit-compatible electronic variants, while European OEMs demand redundant fail-safe architectures under ECE R79 mandates.
- Brake:Force-sensing interfaces are converging with regenerative braking controllers to create unified deceleration management systems. The segment gains share fastest in battery-electric platforms where blended braking algorithms require precise pedal position encoding.
- Clutch:Mechanical cable-actuated designs persist in manual-transmission strongholds across emerging-market ICE fleets.
- Dead Pedal:Stamped aluminum footrests serve ergonomic and safety functions with minimal sensor integration.
- Footrest:Polymer-molded variants dominate cost-optimized vehicle programs with basic structural requirements.
Today's leader: Accelerator. Tomorrow's challenger: Brake.
Technology:
Cost tier stratification separates premium electronic architectures from commodity mechanical production, with electro-hydraulic bridging the gap in heavy-duty applications.
- Mechanical:Cable-actuated linkages with stamped steel arms and polymer pivot bushings retain volume in manual-transmission and emerging-market fleets. Brazil and Indonesia generate sustained aftermarket replacement demand for potentiometric position modules in aging ICE vehicles.
- Electronic:Drive-by-wire position sensors with redundant encoding and ASIL-D functional safety certification extend validation cycles by fourteen to eighteen months. The technology is climbing the fastest as EPA tailpipe standards and EU Green Deal ecodesign mandates eliminate mechanical linkages from hybrid and battery-electric architectures.
- Hydraulic:Fluid-pressure actuation persists in commercial vehicle brake systems requiring high force multiplication.
- Pneumatic:Compressed-air systems serve specialized industrial and off-highway equipment segments.
- Electro-Hydraulic:Hybrid actuation combines electronic control with hydraulic force transmission in heavy-duty braking applications.
Mechanical retains volume dominance. Electronic commands value capture.
Vehicle Type:
Application intensity varies by propulsion architecture, with passenger vehicles driving electronic module adoption and commercial fleets sustaining mechanical-hybrid demand.
- Passenger Cars:Intelligent cockpit integration and drive-by-wire convergence concentrate electronic pedal procurement in premium and mass-market battery-electric platforms. China's state-owned automakers are consolidating supplier panels under framework agreements with tier-one chassis integrators.
- Light Commercial Vehicles:Mixed powertrain fleets require simultaneous support for cable-actuated and electronic pedal interfaces, doubling validation matrices for suppliers.
- Heavy-Duty Vehicles:Hydraulic and electro-hydraulic brake systems dominate due to force requirements and regulatory durability standards.
- Two-Wheelers:Simplified mechanical designs with basic polymer components serve cost-sensitive emerging-market demand.
Passenger cars anchor technology transition. Heavy-duty vehicles resist full electrification.
End User:
Customer type determines margin structure, with OEMs extracting bundled pricing leverage and aftermarket channels fragmenting across geographic replacement cycles.
- OEMs:Single-supplier chassis control contracts bundle electronic pedal modules with steering angle sensors and braking controllers, displacing standalone pedal manufacturers through consolidated procurement. Fleet procurement departments in German premium automakers and Chinese state-owned enterprises are driving this consolidation.
- Aftermarket:Aging internal-combustion fleets across Brazil and Indonesia generate replacement demand for potentiometric pedal position modules and mechanical cable assemblies.
- Tier-1 Suppliers:Chassis systems integrators capture value through sensor-software competencies and captive semiconductor sourcing.
- Vehicle Assemblers:Contract manufacturing arrangements in India under the PLI scheme for auto components are drawing electronic pedal assembly investment from legacy mechanical production.
OEMs dictate technology roadmaps. Aftermarket extends mechanical revenue tails.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors electronic pedal procurement as Chinese automakers scale intelligent cockpit production. Domestic OEMs in Shanghai and Jiangsu province consolidate supplier panels under chassis integration contracts. MIIT's GB standards for electromagnetic compatibility shape certification requirements for electronic accelerator assemblies.
China
State-owned automakers in Shanghai and Beijing are scaling orders for drive-by-wire pedal modules with redundant position encoding. MIIT's GB standards mandate electromagnetic compatibility testing for all electronic accelerator controls sold into domestic production. The Yangtze River Delta cluster concentrates tier-one chassis integrators supplying BYD and NIO with bundled electronic modules.
Germany
Premium OEMs in Munich and Stuttgart demand ASIL-D certified electronic pedals with fail-safe return-to-idle protocols. ECE R79 and the EU General Safety Regulation enforce redundant position encoding for all electronic accelerator controls sold in member states. The Baden-Württemberg industrial corridor hosts ZF Friedrichshafen and Continental AG development centers for sensor-software integration.
United States
Detroit-based automakers are phasing out mechanical cable linkages under EPA tailpipe standards pressure. NHTSA Federal Motor Vehicle Safety Standards govern pedal entrapment prevention and unintended acceleration mitigation protocols. The Michigan-Ohio manufacturing belt sustains aftermarket demand for potentiometric position modules in aging ICE fleets.
Japan
Toyoda Iron Works and DENSO Corporation anchor domestic supply chains for hybrid vehicle pedal architectures. METI oversees industrial standards coordination while JIS specifications govern component interoperability. The Aichi prefecture cluster around Nagoya concentrates precision stamping and sensor integration capabilities for Toyota and Honda platforms.
India
Maruti Suzuki and Tata Motors are drawing electronic pedal assembly investment through the PLI scheme for auto components. The country's national automotive regulator aligns type-approval processes with UNECE frameworks to accelerate export qualification. The Tamil Nadu-Gujarat manufacturing corridor hosts contract assemblers transitioning from mechanical to electronic module production.
Automotive Pedals Market Key Industry Players
Chassis integration bundling dominates the current landscape as tier-one suppliers displace standalone pedal manufacturers. The vendor base concentrates around sensor-software competencies rather than stamped metal fabrication. Three archetypes define positioning: captive semiconductor sourcers, chassis systems integrators, and precision metal stampers. M&A activity and strategic partnerships represent the primary competitive vectors as suppliers seek Hall-effect sensor chip access and drive-by-wire software stacks.
Within the captive semiconductor tier, Robert Bosch GmbH exemplifies backward integration into sensor chip sourcing that insulates against Taiwan and South Korean foundry concentration. Among German chassis integrators, ZF Friedrichshafen and Continental AG occupy positions bundling electronic pedal modules with braking controllers and steering angle sensors. Shanghai Kaizhong Materials Science and Technology Co., Ltd. represents the precision metal fabrication archetype, supplying stamped aluminum bracket and arm assemblies to domestic Chinese OEMs scaling intelligent cockpit production.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Toyoda Iron Works Co. Ltd. |
| Continental AG |
| CTS Corporation |
| KSR International Inc. |
| Robert Bosch GmbH |
| F.TECH Inc. |
| Shanghai Kaizhong Materials Science and Technology Co. Ltd. |
| DENSO Corporation |
| Others |
Cost & Logistics Intelligence
Precision sensor engineering talent concentration in the Baden-Württemberg corridor feeds labor-cost differentials into tiered pricing spreads across electronic pedal modules. OEM procurement consolidation under chassis integration contracts compresses margin buffers at standalone bracket manufacturers unable to match bundled pricing leverage.
Pricing Analysis
Input-cost pass-through from Hall-effect sensor chip foundry pricing governs module-level quotations to OEMs. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified architectures with redundant encoding from basic potentiometric designs. Pricing pressure stems from captive semiconductor sourcing advantages at backward-integrated suppliers like Robert Bosch GmbH. Tier-two bracket manufacturers exhibit highest price sensitivity due to steel-aluminum input volatility, while German premium OEMs demonstrate lowest sensitivity given functional safety certification requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Chinese state-owned automakers consolidating supplier panels under framework agreements. Geographic supply concentration centers on Germany for precision stamping and sensor integration, China for aluminum bracket fabrication and intelligent cockpit module assembly, and Taiwan for Hall-effect semiconductor foundry capacity. Raw material dependencies span stamped aluminum alloys, polymer pivot bushings, and position-sensor chipsets. Single-source vulnerability in Taiwan and South Korean foundry capacity for sensor semiconductors represents the dominant structural risk. Distribution runs through tier-one chassis systems integrators bundling electronic pedals with braking controllers and steering angle sensors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive pedals market functions as a stable compounder anchored by irreversible platform electrification that mandates electronic torque-encoding architectures across all propulsion tiers.
For Market Incumbents: Extend sensor-software competency moats through ASIL-D certification investment and captive semiconductor sourcing arrangements that insulate against Taiwan foundry concentration risk. Consolidate procurement relationships with Chinese state-owned OEMs scaling intelligent cockpit production before tier-two bracket manufacturers achieve electronic module qualification. Chassis integration bundling represents the priority defensive lever. For New Entrants and Emerging Players: Aftermarket sensor retrofit channels for aging ICE fleets in Brazil and Indonesia offer the most penetrable white-space target, with potentiometric position module replacement demand extending mechanical revenue tails. India's PLI scheme for auto components provides contract manufacturing entry points for electronic pedal assembly transitioning from legacy mechanical production. Direct digital sourcing relationships with fleet procurement departments bypass entrenched tier-one distributor networks. For Investors and Strategic Acquirers: Tier-one chassis systems integrators are the most active acquirer in this space, seeking Hall-effect sensor chip access and drive-by-wire software stacks to complete bundled control system portfolios. Five-to-ten year viability hinges on electronic module share expansion as manual transmission clutch demand phases out in emerging markets. Acquisition target archetype: precision metal stampers with aluminum bracket capabilities and nascent sensor integration partnerships. Watch for MIIT GB standard harmonization with UNECE frameworks as inflection indicator for Chinese export qualification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEMs consolidate electronic pedal architectures across hybrid and battery-electric vehicle programs to reduce validation overhead. |
| Backward Integration into Semiconductors | Suppliers secure captive Hall-effect sensor chip sourcing to mitigate Taiwan and South Korean foundry concentration risk. |
| Software-Defined Vehicle Investment | Drive-by-wire convergence merges pedal position encoding with regenerative braking controllers and autonomous emergency braking systems. |
| Geographic Manufacturing Footprint | Tamil Nadu-Gujarat corridor in India draws electronic pedal assembly investment through PLI scheme incentive structures. |
| Charging Infrastructure Partnership | Battery-electric platform proliferation creates bundled procurement opportunities for electronic throttle modules with charging system controllers. |
Research Approach
Direct dialogue with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads grounded qualitative assessment in operational realities. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive component suppliers, and MIIT GB standard documentation. Bottom-up and top-down triangulation reconciled segment-level volume assumptions with aggregate market sizing.
Bottom-up modeling of electronic and mechanical pedal shipments by vehicle class, propulsion architecture, and regional production cluster anchored value projections across the analysis window. Top-down cross-checks against OEM purchasing data and tier-one supplier revenue disclosures verified segment splits. CAGRs derived from production ramp schedules for battery-electric platforms and manual transmission phase-out timelines in emerging markets. Content-per-vehicle assumptions for sensor integration intensity and aluminum substitution rates informed technology-tier trajectories.
The model assumes a particular technology adoption path; alternative pathways for drive-by-wire convergence would alter the outlook if hybrid architectures persist longer than projected. Forecasts reflect assumptions about EPA tailpipe standard enforcement timelines and EU Green Deal ecodesign mandate implementation. Semiconductor supply normalization and steel-aluminum price stabilization represent key variables that could revise projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Drive System Market
Automotive Components
Automotive Rear End Module Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
Automotive Axle Market
Automotive Components
Automotive Glass Film Market
Automotive Components
Global Automotive Collapsible Steering Column Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
Brazil Automotive Composites Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Automotive Fuel Injection System Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Russia Automotive Pneumatic Actuators Market