
 Global Automotive Condenser Market | 2026-2036
Global Automotive Condenser Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Condenser Market Intelligence
Divergent capital investment in microchannel and serpentine condenser manufacturing technology is bifurcating the competitive landscape. Large-scale suppliers like Denso Corporation leverage extensive R&D and global production footprints to serve OEM clients. In contrast, specialists such as Modine Manufacturing Company differentiate through customized solutions for heavy-duty and specialty vehicle applications. Valeo sustains its market position through a balanced portfolio catering to both OEM and aftermarket channels.
An automotive condenser is a heat exchanger, typically made of aluminum, that dissipates heat from the compressed refrigerant gas, converting it back into a high-pressure liquid. Its primary function is to enable the air conditioning system's cooling cycle. Microchannel product types dominate new installations due to their superior thermal efficiency and compact size. The passenger vehicles application represents the largest volume segment, with procurement heavily weighted towards direct supply to OEMs.
Regulatory frameworks are a primary influence on condenser design and material selection. The EU's F-Gas Regulation and refrigerant phase-down rules from the US EPA compel the use of specific refrigerants, directly impacting condenser specifications. These standards drive the need for higher-efficiency heat exchangers. Component suppliers must now decide whether to specialize in systems for electric vehicles or maintain a broader portfolio covering internal combustion engine models.
Market Dynamics
The transition towards lower global warming potential refrigerants, driven by global regulatory mandates, is the central force shaping condenser design, material science, and capital investment strategies across the automotive industry. This shift directly influences product specifications and technology choices.
Growth Catalysts
- EV Thermal Management:The expanding electric vehicle segment requires sophisticated thermal management systems where condensers are integral for battery and cabin cooling, driving volume demand for high-efficiency units.
- EU F-Gas Regulation:Mandates in Europe compelling the use of refrigerants with lower global warming potential necessitate the redesign and replacement of condensers, stimulating both OEM and aftermarket sales.
- Aftermarket Expansion:A growing vehicle parc in automotive manufacturing hubs, particularly in China, fuels consistent demand for replacement condensers through the independent aftermarket channel.
Market Restraints
- Aluminum Price Volatility:As the primary material for condensers, fluctuations in aluminum prices directly impact manufacturing costs and profitability, creating margin pressure for component suppliers.
- High Manufacturing Capex:The production lines for advanced microchannel condensers require significant capital investment, creating a high barrier to entry for new or smaller manufacturers.
- Refrigerant System Incompatibility:Condensers designed for new, low-GWP refrigerants are not backward-compatible with older systems, complicating aftermarket inventory management and repair services.
Strategic Opportunities
- Heavy-Duty Electrification:Developing customized, ruggedized condenser solutions for electric buses, commercial trucks, and off-highway vehicles represents a significant, underserved market segment.
- Integrated Thermal Modules:There is a clear opportunity to design and supply complete thermal management modules that integrate the condenser with battery cooling plates and other heat exchangers for EVs.
- Circular Economy Models:Establishing programs for the remanufacturing of condensers and the certified recycling of aluminum from end-of-life units can create new revenue streams, especially in Europe.
Industry Challenges
- System Integration Complexity:Ensuring the seamless electronic and physical integration of new condenser technologies with existing vehicle HVAC controls and architectures presents a persistent engineering challenge.
- Supply Chain Reconfiguration:Suppliers face logistical hurdles and costs associated with shifting production capacity to align with the geographic concentration of electric vehicle assembly plants in China and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Condenser Market |
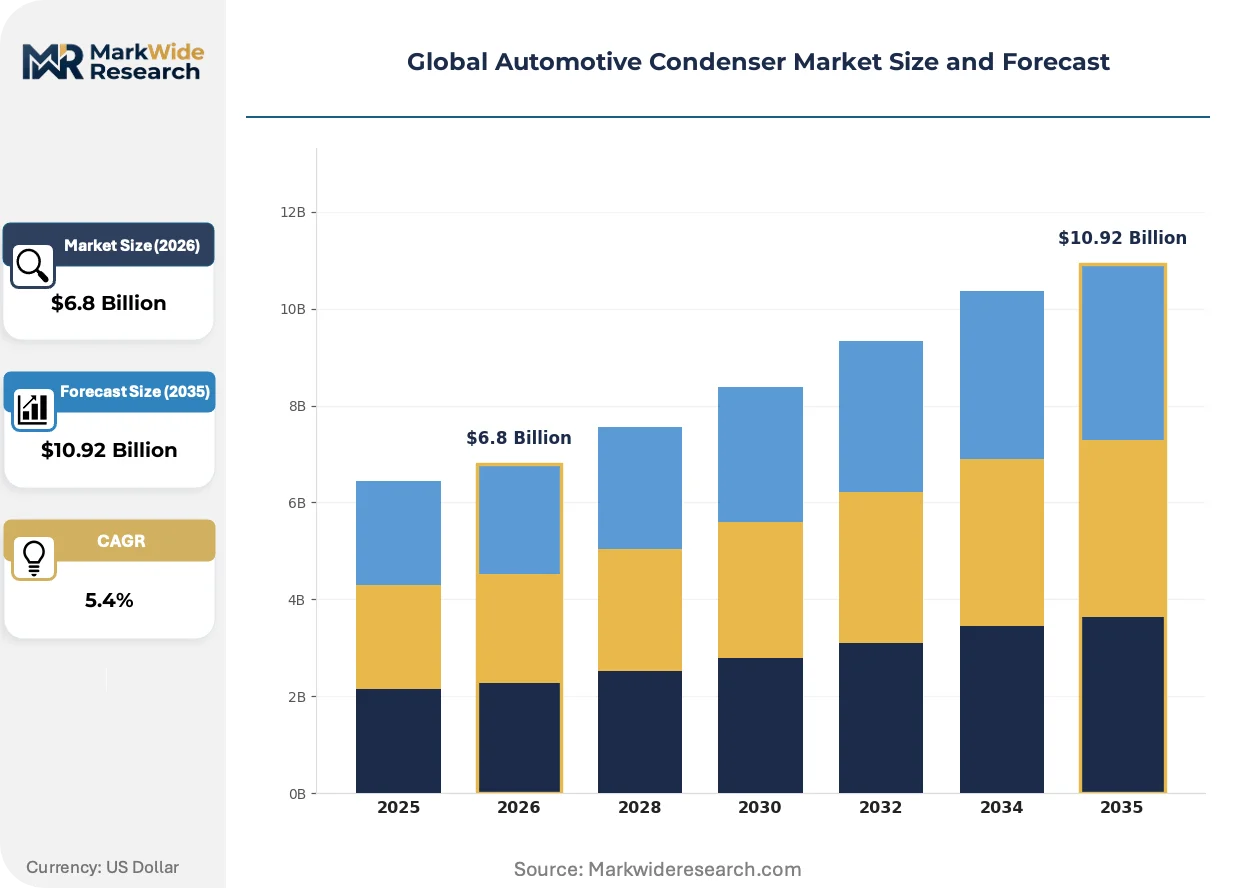
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tube & Fin, Plate Type, Microchannel, Serpentine, Corrugated Technology: Air Cooling, Water Cooling, Hybrid Cooling, Thermoelectric, Radiative Application: Passenger Vehicles, Heavy-Duty Vehicles, Commercial Trucks, Specialty Vehicles, Agricultural Machinery End User: OEMs, Aftermarket Suppliers, Dealerships, Tier-1 Manufacturers |
| Companies Covered | MAHLE GmbH, Denso Corporation, Valeo, Hanon Systems, Robert Bosch GmbH, Modine Manufacturing Company, Sanden Corporation, Keihin Corporation, Subros Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Condenser Market Strategic Shifts & Innovations
Automotive condenser evolution is defined by the convergence of material science advancements and stringent environmental regulations. This dynamic is reshaping product architectures to meet new thermal efficiency targets for both electric and internal combustion engine platforms, driving innovation across the supply chain.
Microchannel condensers, which utilize brazed aluminum tubes and fins, provide superior heat transfer within a compact and lightweight package. Automakers are rapidly adopting these designs for new passenger vehicles, especially electric models, due to strict space and efficiency requirements. This widespread adoption is fragmenting the aftermarket, creating a divide between suppliers who can service newer microchannel systems and those focused on legacy serpentine designs.
The EU F-Gas Regulation and parallel refrigerant phase-down rules from the US EPA mandate a transition away from high-GWP refrigerants. This directly impacts condenser specifications, as newer alternatives like R-1234yf operate at higher pressures, requiring more robust and often costlier designs. The passenger vehicle segment is most affected, compelling OEMs to specify these higher-performance condenser units for all new models entering production.
OEM purchasing behavior now prioritizes suppliers offering complete thermal management modules over standalone condenser components. This trend favors large, Tier 1 suppliers capable of delivering pre-validated, integrated systems, thereby reducing assembly complexity for the automaker. This shift is most visible within the electric vehicle supply chains of Germany and China, where rapid product development cycles are critical for competitive positioning.
Global Automotive Condenser Market Segmentation
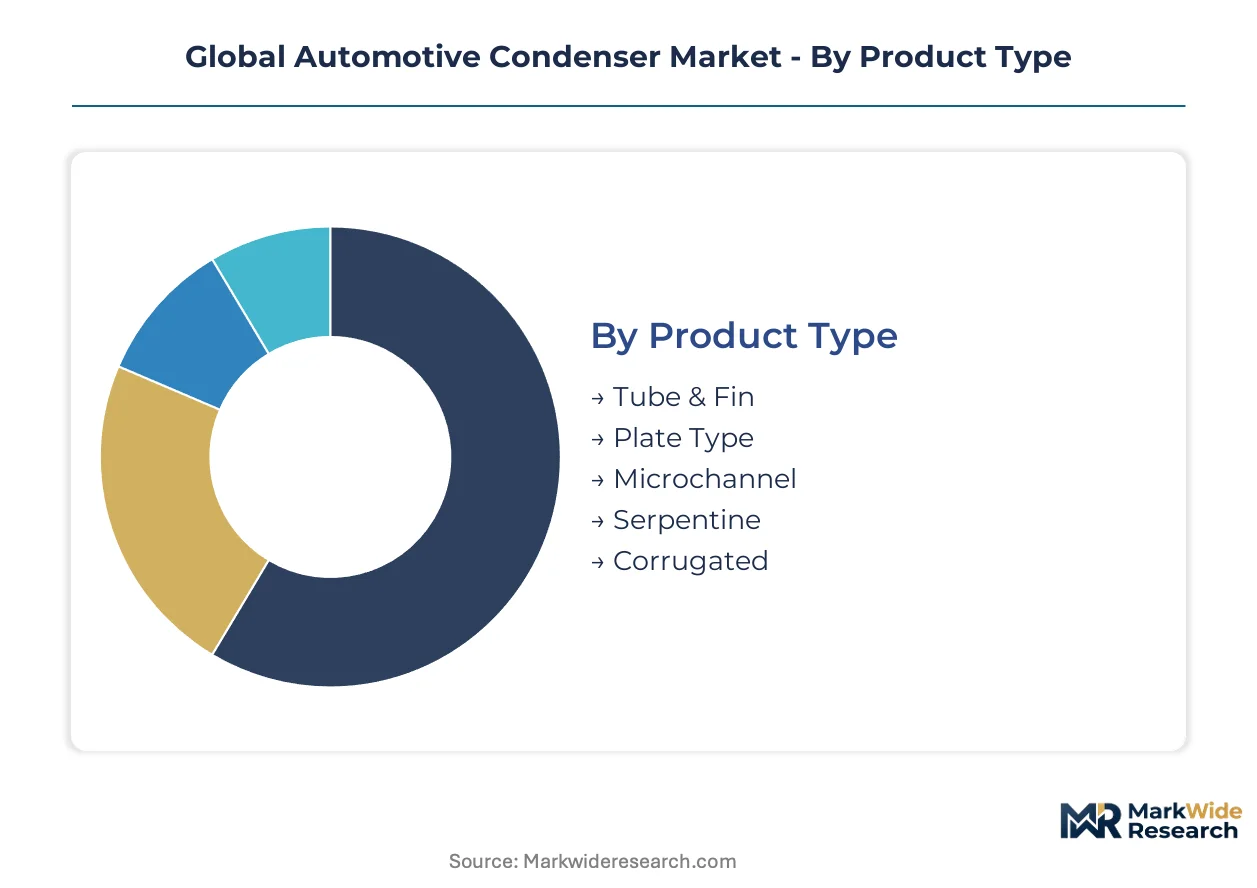
The automotive condenser market segments reflect distinct product characteristics, technological approaches, and end-use applications. Understanding these divisions helps stakeholders identify specific demand drivers and regulatory influences shaping product development. Each segment addresses unique thermal management requirements within the evolving automotive landscape.
Product Type:
Regulatory frameworks significantly differentiate condenser product types, compelling innovation in design and material science.
- Microchannel:These condensers feature brazed aluminum tubes and fins, offering superior heat transfer within a compact and lightweight package. Demand concentrates in new passenger electric vehicles, driven by strict space and thermal efficiency requirements in Germany and China.
- Serpentine:Comprising bent aluminum tubes and fins, serpentine designs represent a legacy technology with established performance characteristics. Aftermarket demand for replacement units in older internal combustion engine models sustains this segment.
- Tube & Fin:This traditional design utilizes tubes running through fins to facilitate heat exchange, commonly found in various automotive applications.
- Plate Type:Characterized by stacked plates, these condensers offer good heat transfer efficiency in specific, often smaller, applications.
- Corrugated:Featuring corrugated fins, this type provides enhanced surface area for heat dissipation, suitable for certain high-performance systems.
Established volume favors Serpentine designs; emerging adoption favors Microchannel units.
Technology:
Application-specific requirements often dictate the preferred cooling technology for automotive condensers.
- Air Cooling:This technology dissipates heat directly into the ambient air, representing the most common and cost-effective method for cabin air conditioning systems. Most internal combustion engine vehicles and many electric vehicles utilize air-cooled condensers.
- Water Cooling:Employing a liquid coolant loop, water cooling offers higher heat rejection capacity and more precise temperature control than air systems. Battery thermal management systems in performance electric vehicles and heavy-duty applications increasingly integrate water-cooled condensers.
- Hybrid Cooling:Combining elements of both air and liquid cooling, hybrid systems optimize thermal performance across varying operating conditions.
- Thermoelectric:Utilizing the Peltier effect, thermoelectric cooling offers compact, solid-state solutions for niche or supplementary cooling needs.
- Radiative:Passive radiative cooling concepts explore heat rejection to the environment without active fluid circulation, primarily for specialized or auxiliary functions.
Efficiency and integration capabilities are key differentiators across these cooling technologies.
Application:
Volume concentration across different vehicle types shapes demand patterns for automotive condensers.
- Passenger Vehicles:This segment represents the largest volume, encompassing a diverse range of cars and SUVs requiring compact and efficient thermal management. OEM procurement for new models, especially electric variants in China and Germany, drives significant demand.
- Heavy-Duty Vehicles:Condensers for heavy-duty vehicles require rugged designs and high capacity to manage larger thermal loads and withstand demanding operating environments. Electrification initiatives for commercial trucks and buses are expanding demand in this segment.
- Commercial Trucks:These applications demand durable and efficient condensers capable of enduring long-haul operations and varying climate conditions.
- Specialty Vehicles:Includes niche applications such as recreational vehicles, ambulances, and construction equipment, requiring customized condenser solutions.
- Agricultural Machinery:Condensers for agricultural machinery must withstand harsh outdoor conditions and provide reliable cooling for operator comfort and engine performance.
The shift towards electrification is expanding the application scope beyond traditional internal combustion engines.
End User:
Supply chain roles define distinct purchasing behaviors and product requirements among end users.
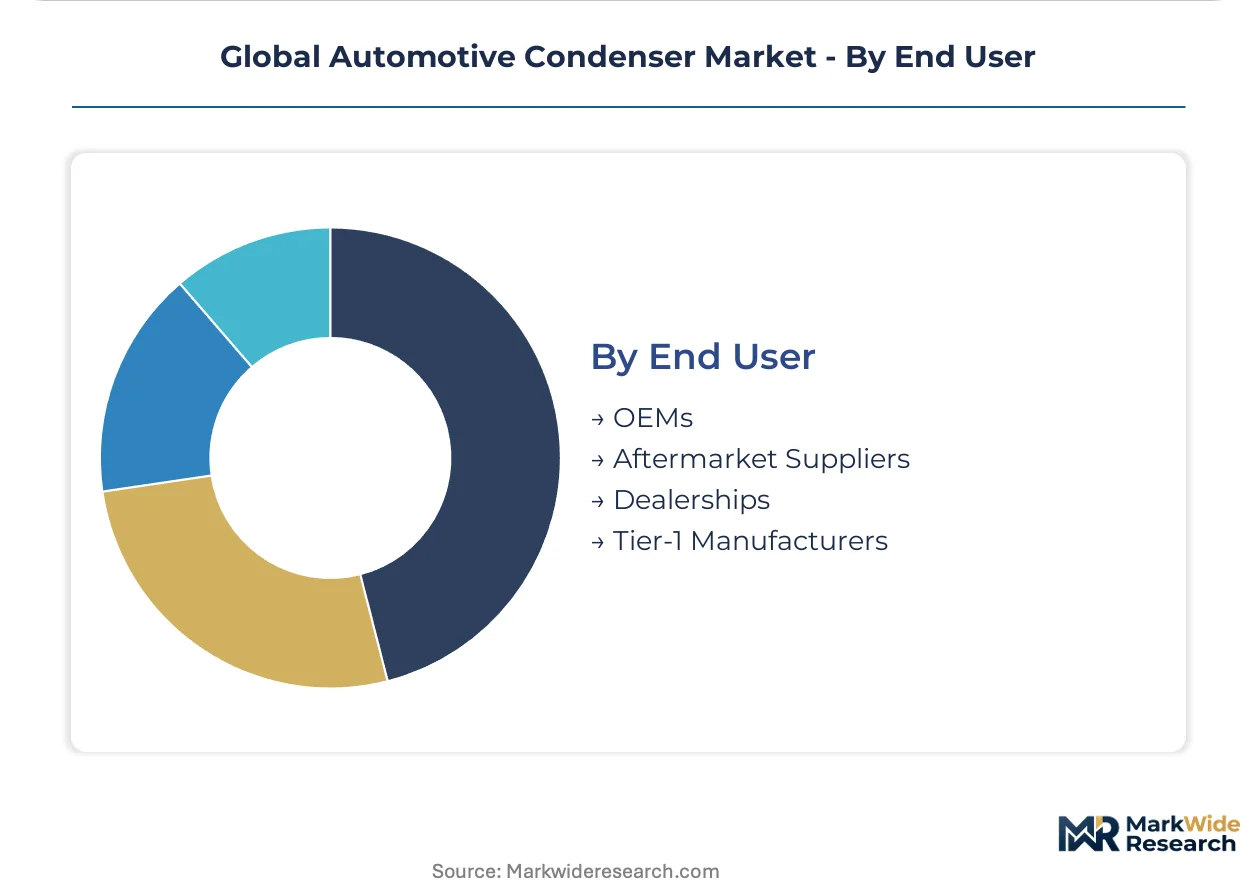
- OEMs:Original Equipment Manufacturers procure condensers directly for integration into new vehicle assembly lines, prioritizing custom designs, supply chain reliability, and advanced technology. Large Tier 1 suppliers often serve these clients with integrated thermal modules.
- Aftermarket Suppliers:These entities provide replacement condensers for vehicle repair and maintenance, focusing on broad compatibility, availability, and competitive pricing. The independent aftermarket channel in China and Europe is a significant consumer.
- Dealerships:Dealerships typically source condensers through OEM channels or authorized distributors for their service and repair operations.
- Tier-1 Manufacturers:These suppliers integrate condensers into larger thermal management systems or modules before delivering them to OEMs.
Direct supply channels dominate new installations, while independent channels serve ongoing maintenance needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive condenser market exhibits a dynamic regional landscape, with significant trade flows influencing local production and demand. Countries with established automotive manufacturing bases often act as net exporters of condensers, while others rely on imports to meet their vehicle production or aftermarket needs. This balance shapes investment in local manufacturing capabilities and supply chain resilience.
China
Demand for automotive condensers in China is primarily driven by the nation's vast electric vehicle production and expanding domestic vehicle parc. The dual carbon goals set by the Chinese government compel automakers to adopt high-efficiency thermal management systems. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta regions are central to condenser production for both domestic and export markets.
Germany
Germany represents a major hub for automotive condenser innovation, particularly for premium and performance vehicle segments, including electric models. The EU F-Gas Regulation directly influences condenser design, necessitating robust units compatible with lower global warming potential refrigerants. Key automotive manufacturing regions like Bavaria and Baden-Württemberg host significant research and development activities and production facilities.
United States
The United States market sees steady demand for condensers from its established automotive manufacturing sector and a large aftermarket for replacement components. US EPA refrigerant phase-down rules dictate the specifications for new condenser units, driving technological upgrades. Automotive assembly plants in Michigan and the Southeast region are significant consumers of advanced thermal management components.
Japan
Japan's automotive industry drives consistent demand for compact and efficient condensers, especially for its extensive hybrid and electric vehicle production. METI regulations and national standards influence material selection and manufacturing processes to ensure high quality and environmental compliance. Major automotive component suppliers are concentrated in the Chubu region, supporting global OEM supply chains.
India
India's automotive condenser market expands with the growth of its domestic passenger vehicle segment and increasing adoption of electric two-wheelers and cars. BIS standards guide local manufacturing practices and product quality for both OEM and aftermarket channels. Production facilities in Maharashtra and Tamil Nadu cater to the country's diverse automotive manufacturing ecosystem.
Global Automotive Condenser Market Key Industry Players
Concentration sits with large, diversified Tier 1 suppliers that leverage extensive R&D capabilities and global production networks. These players often provide integrated thermal management modules to major OEMs. The competitive landscape also includes specialized manufacturers focusing on niche applications like heavy-duty vehicles or specific condenser technologies. Dominant competitive moves include strategic partnerships for technology co-development and continuous capacity expansion to meet rising EV demand.
Large-scale OEM suppliers like Denso Corporation exemplify the market presence achieved through broad product portfolios and established relationships with global automakers. Valeo sustains its market position by offering a balanced portfolio that addresses both OEM and aftermarket channels, adapting to evolving refrigerant standards. Modine Manufacturing Company represents specialists in customized solutions for heavy-duty and specialty vehicle applications, differentiating through ruggedized designs and application-specific engineering.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Denso Corporation |
| Valeo |
| Hanon Systems |
| Robert Bosch GmbH |
| Modine Manufacturing Company |
| Sanden Corporation |
| Keihin Corporation |
| Subros Limited |
| Others |
Cost & Logistics Intelligence
Significant economies of scale in microchannel condenser manufacturing shape both supply concentration and price floors across the automotive industry. This scale advantage often dictates which suppliers can effectively serve large OEM contracts, influencing overall market pricing structures.
Pricing Analysis
Industrial OEM buyers anchor long-term contract-based pricing for new condenser installations, prioritizing supply reliability and technological alignment. Price differentiation stems from product type, with microchannel units commanding higher prices due to superior thermal efficiency and compact design. Pricing pressure stems from aluminum price volatility, impacting profitability for component suppliers. Aftermarket suppliers demonstrate higher price sensitivity than OEMs, seeking cost-effective replacements for legacy serpentine designs.
Supply Chain Analysis
Managing inventory and lead times for automotive condensers presents ongoing challenges, particularly given global manufacturing footprints. Geographic supply concentration sits with China, Germany, and Japan, which serve as major production hubs for both OEM and aftermarket components. Raw material dependencies include aluminum for heat exchangers and specialized refrigerants like R-1234yf. Single-source vulnerability for advanced microchannel components represents a structural supply chain risk. Distribution runs through direct supply to OEMs and independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global automotive condenser market is an early-cycle expansion story, buoyed by the rapid electrification of passenger and heavy-duty vehicles.
For Market Incumbents: Secure OEM relationships by prioritizing investment in advanced microchannel production capacity, especially in China and Germany. Expand R&D into integrated thermal modules to counter fragmentation from specialized EV startups. Leverage global production footprints to mitigate supply chain risks and maintain competitive pricing against aluminum price volatility.
For New Entrants and Emerging Players: Anchor in underserved niches like heavy-duty electrification, where specialized thermal management solutions are critical for electric buses and commercial trucks. Target the integrated thermal module segment for EV platforms, offering pre-validated systems to reduce OEM assembly complexity. A customized engineering approach for specific application requirements provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors firms with established microchannel expertise and strong OEM integration capabilities, essential for long-term viability. Evaluate acquisition targets specializing in high-efficiency thermal management for electric vehicles or those with strong aftermarket distribution networks. The signal to watch is the continued acceleration of global EV production volumes and corresponding regulatory shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Microchannel Production in China | Meets rising EV demand and strengthens OEM supply relationships in a critical manufacturing hub. |
| Invest in Integrated Thermal Module R&D | Reduces OEM assembly complexity and secures larger contracts for complete thermal management systems. |
| Develop Ruggedized Condensers for Heavy-Duty EVs | Addresses a specialized, underserved market segment with unique durability and capacity requirements. |
| Establish Circular Economy Programs for Aluminum | Creates new revenue streams and enhances sustainability credentials, particularly in regulated European markets. |
| Strengthen Aftermarket Distribution for Low-GWP Units | Ensures availability of replacement components compatible with new refrigerant standards, supporting vehicle parc longevity. |
Research Approach
The analysis maps distinct automotive condenser sub-sectors, each validated through extensive interviews with OEM procurement leads, Tier 1 R&D directors, and aftermarket distributors. This primary research combines with secondary data from vehicle production databases, automotive component trade statistics, and regulatory reports like the EU F-Gas Regulation. Bottom-up data aggregation and top-down market sizing ensure comprehensive industry coverage and accuracy.
Outputs undergo rigorous consistency checks against external benchmarks, ensuring the integrity of projections across the analysis window. The analytical framework models market segmentation by product type, technology, application, end user, and key regional production clusters. Compound annual growth rates are derived from historical trends and forward-looking assessments of EV adoption rates and refrigerant phase-down schedules, incorporating aluminum futures as a key input.
Decision-makers should treat outputs as directional under current EV adoption rates and regulatory phase-down schedules; material deviation would warrant model refresh. Forecasts reflect assumptions concerning stable geopolitical trade relations and consistent material supply. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Canada Automotive Glass Fiber Composites Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Automotive Exhaust Emission Control Device Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Asia Pacific Automotive AHSS Market
Automotive Components
Automotive Grade Modules Market
Automotive Components
Automotive Heater Core Market
Automotive Components
Asia-Pacific Automotive Composites Market
Automotive Components
Global Automotive Damper Control Unit Market
Automotive Components
Egypt Automotive Lubricants Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
Automotive Polycarbonate Glazing Market
Automotive Components
Global Automotive Plastic Compounding Market