
 Automotive Electric Fuel Pumps Market | 2026-2036
Automotive Electric Fuel Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electric Fuel Pumps Market Intelligence
Asset-light manufacturing partnerships and third-party production financing is reconfiguring capital requirements for new entrants in the Automotive Electric Fuel Pumps Market. Robert Bosch GmbH leverages captive semiconductor sourcing to control brushless motor controller costs. Continental AG anchors European OEM supply through integrated fuel module assembly lines. Denso Corporation dominates Asian passenger vehicle platforms with high-volume brushless pump production.
Automotive electric fuel pumps are electromechanical devices that deliver pressurized fuel from the tank to the engine injection system, typically operating at pressures between 3 and 5 bar for port-injected gasoline applications and exceeding 10 bar for direct-injection architectures. Their primary purpose is to maintain precise fuel flow rates under varying engine load conditions while minimizing vapor generation and evaporative losses. Brushless pump configurations are capturing margin pools as OEMs prioritize electromagnetic compatibility and extended service life over lower-cost brushed alternatives. Submersible pumps remain the volume leader across passenger car installations, while fuel modules integrate level sensing, pressure regulation, and filtration into single assembly units that command premium pricing. Aftermarket channels face pricing pressure as module complexity raises technical barriers for independent service providers.
The US EPA enforces evaporative emission standards under Tier 3 regulations that mandate onboard refueling vapor recovery and sealed fuel system integrity, directly shaping pump sealing specifications and materials selection. The European Commission advances Euro 7 standards through ECHA and member-state type-approval authorities, tightening particulate and hydrocarbon limits that cascade into fuel system component redesigns. China's MIIT implements GB standards for fuel consumption and emissions that push domestic OEMs toward higher-pressure direct-injection pumps. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether platform standardization or regional customization offers lower total compliance cost.
Market Dynamics
Passenger vehicle electrification programs are compressing demand for traditional brushed pump architectures while simultaneously elevating brushless motor specifications for remaining internal combustion platforms. OEM procurement teams now weight electromagnetic compatibility and service life metrics above unit cost in sourcing decisions.
Growth Catalysts
- Euro 7 emission protocols:The European Commission's tightening hydrocarbon limits through ECHA enforcement are mandating sealed fuel system redesigns that elevate pump sealing specifications and materials selection across EU member states.
- Brushless motor controllers:Semiconductor integration into pump control electronics is extending service intervals and reducing electromagnetic interference, satisfying OEM electromagnetic compatibility requirements for modern vehicle electrical architectures.
- German OEM procurement concentration:Volkswagen, BMW, and Mercedes-Benz platform standardization efforts are consolidating supplier qualification pools around integrated fuel module assemblies that combine pumping, sensing, and filtration functions.
Market Restraints
- Neodymium magnet cost volatility:Rare earth price swings for brushless motor permanent magnets are compressing margin predictability for manufacturers committed to high-efficiency pump architectures.
- Semiconductor foundry concentration:Taiwan-based wafer fabrication bottlenecks are extending lead times for motor controller ASICs, constraining production scaling for brushless pump programs.
- Direct-injection pressure ceilings:Current solenoid-driven pump designs face mechanical limits near 35 bar, restricting gasoline compression ignition applications that would extend internal combustion relevance against battery electric displacement.
Strategic Opportunities
- India BS-VI Phase II implementation:The country's leapfrog to stringent evaporative emission standards is opening qualification windows for sealed fuel module suppliers as domestic OEMs redesign tank systems.
- Hydrogen internal combustion retrofits:Modified high-pressure pump architectures for hydrogen direct injection are emerging as bridge technologies for commercial vehicle decarbonization pathways.
- Amazon Business and Alibaba industrial procurement:B2B e-commerce platforms are compressing distributor margins while enabling aftermarket pump manufacturers to reach independent service garages directly.
Industry Challenges
- Embedded software validation:Functional safety certification to ISO 26262 ASIL-B for brushless motor control firmware is extending development timelines and requiring specialized automotive software engineering talent.
- Legacy tank architecture integration:Retrofitting sealed fuel modules into existing vehicle platforms designed for loose vapor recovery systems demands custom saddle-tank adaptations that fragment production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electric Fuel Pumps Market |
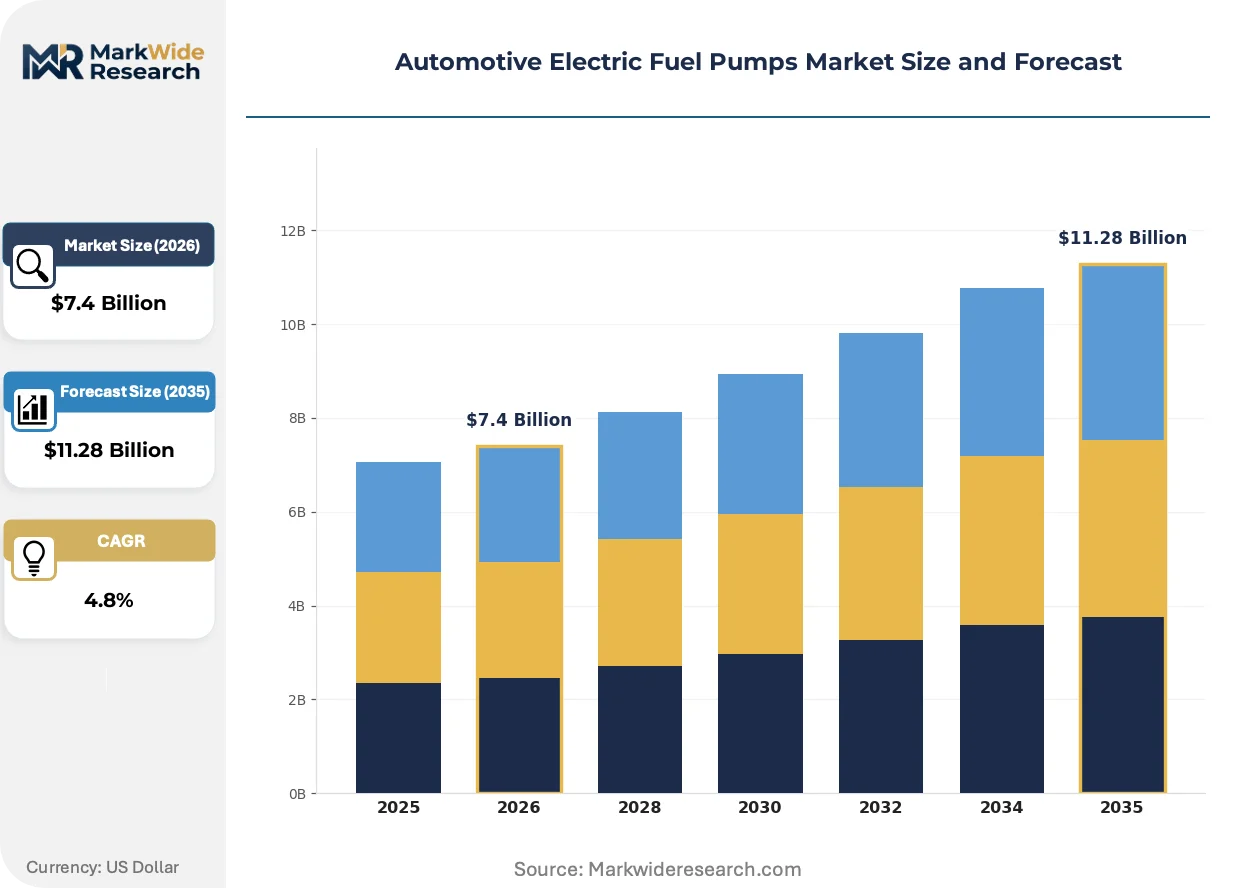
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $11.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Pumps, Submersible Pumps, Brushless Pumps, Fuel Modules Application: Passenger Cars, Commercial Vehicles, Two-Wheelers, Recreational Vehicles Fuel Type: Gasoline, Diesel, Ethanol, Biofuels Installation Type: OEM, Aftermarket, Retrofit, Custom Installation |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Delphi Automotive PLC, Visteon Corporation, Daewha Fuel Pump Ind. Ltd, Federal-Mogul Corporation, ACDelco, Aisan Industry Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electric Fuel Pumps Market Strategic Shifts & Innovations
Brushless motor architectures are hybridizing with smart control electronics to enable predictive maintenance and real-time fuel system diagnostics. Material science advances in fluoropolymer seals and carbon composite impellers are simultaneously addressing chemical compatibility and weight reduction targets.
Permanent magnet synchronous motor technology is hybridizing with integrated motor control electronics to deliver variable speed fuel delivery that matches engine demand curves rather than fixed-flow operation. European OEMs are qualifying these systems for start-stop applications where rapid pressure recovery prevents restart delays. The technology is hybridizing brushed and brushless cost structures, creating mid-tier pricing segments that capture volume from economy pump suppliers while pressuring premium brushless margins.
EPA Tier 3 evaporative emission enforcement through onboard refueling vapor recovery mandates is dictating sealed fuel system architectures that eliminate traditional vapor lines. The regulation is forcing module-level integration of pressure sensors, rollover valves, and carbon canister purge controls into single tank-mounted assemblies. Aftermarket service providers in the United States are struggling with diagnostic complexity, compressing independent garage participation and consolidating dealer service retention.
Fleet procurement departments are unbundling fuel system maintenance from powertrain service contracts to capture component-level lifecycle cost transparency. Commercial vehicle operators in Japan are negotiating direct pump replacement schedules with suppliers rather than accepting bundled maintenance from OEM dealer networks. This pattern is most visible in long-haul trucking segments where fuel system reliability directly impacts route scheduling and penalty clause exposure.
Automotive Electric Fuel Pumps Market Segmentation
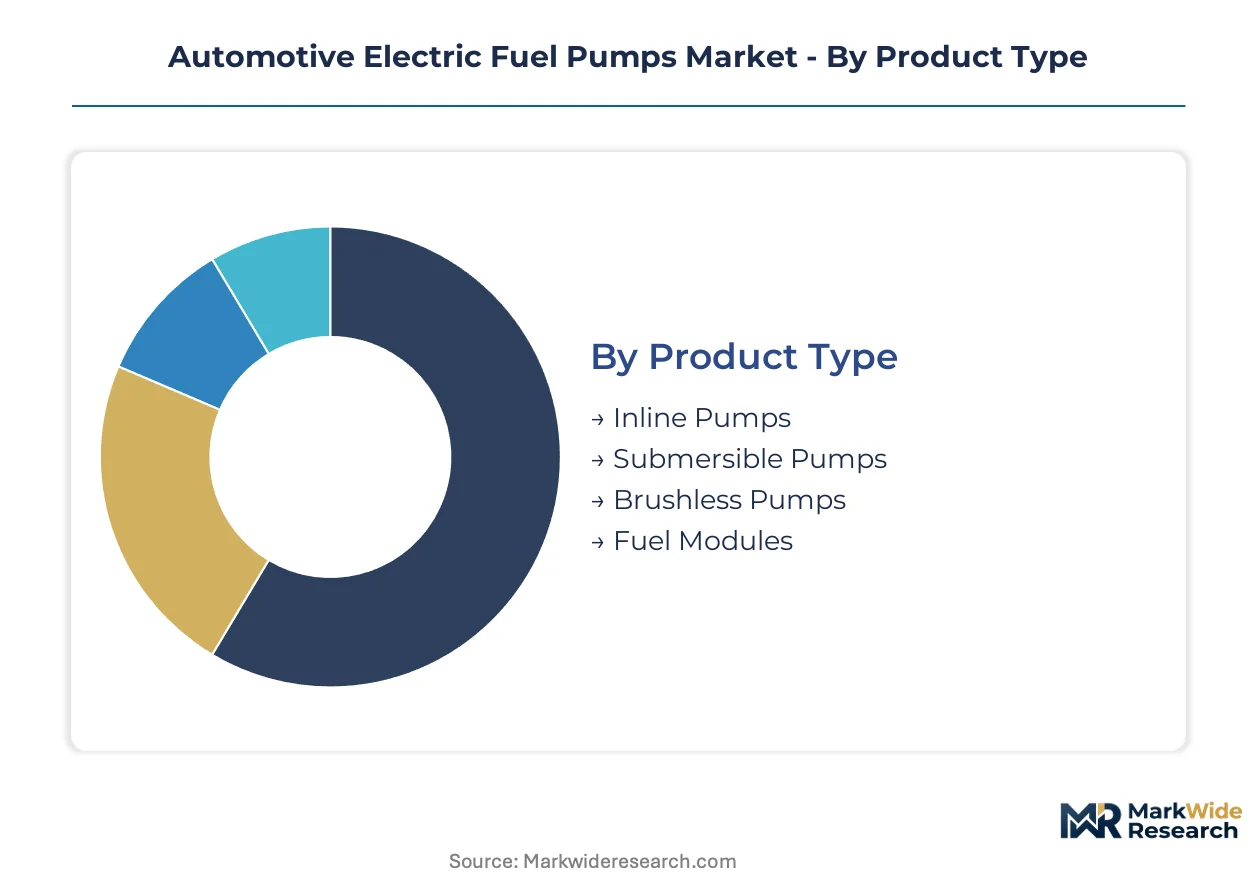
Segmentation in the Automotive Electric Fuel Pumps Market reveals how electrification pressures and emission mandates are fragmenting demand across pump architectures and vehicle platforms. Procurement patterns diverge sharply between integrated module buyers and component-level purchasers.
Product Type:
Cost tier positioning separates legacy brushed architectures from premium brushless motor systems and fully integrated fuel delivery modules.
- Submersible Pumps:These tank-mounted units operate fully immersed in fuel for cooling and noise suppression, dominating passenger car volume production across German OEM platforms. Volkswagen and BMW procurement specifications favor submersible designs for start-stop compatibility and rapid pressure recovery.
- Fuel Modules:Integrated assemblies combine pumping, level sensing, pressure regulation, and filtration into single tank-mounted units that command premium pricing. EPA Tier 3 sealed system mandates are accelerating module adoption in United States passenger vehicle platforms where evaporative emission compliance requires consolidated vapor management.
- Inline Pumps:External mounting designs persist in commercial vehicle and aftermarket applications where tank access constraints favor line-mounted installation.
- Brushless Pumps:Permanent magnet synchronous motor architectures deliver extended service life and electromagnetic compatibility for modern vehicle electrical systems.
Fuel Modules hold installed capacity. Brushless Pumps is rotating up the share rankings.
Application:
Vehicle platform scale determines procurement concentration, with passenger car electrification programs compressing demand while commercial segments pursue decarbonization bridge technologies.
- Passenger Cars:Direct-injection gasoline architectures require pumps exceeding 10 bar delivery pressure, with Euro 7 hydrocarbon limits forcing sealed module redesigns across European OEM portfolios. German platform standardization efforts by Volkswagen, BMW, and Mercedes-Benz are consolidating supplier qualification pools.
- Commercial Vehicles:Long-haul trucking operators in Japan are unbundling fuel system maintenance from powertrain service contracts, negotiating direct pump replacement schedules with suppliers. Fleet procurement departments demand component-level lifecycle cost transparency for route scheduling reliability.
- Two-Wheelers:Cost-sensitive motorcycle and scooter markets in India retain carbureted architectures that limit electric pump penetration to premium displacement segments.
- Recreational Vehicles:Low-volume specialty applications favor aftermarket channel distribution with extended service interval requirements.
Passenger Cars retains volume dominance. Commercial Vehicles is climbing the fastest among application segments.
Fuel Type:
Chemical compatibility requirements and combustion pressure specifications fragment pump material selection and sealing architectures.
- Gasoline:Direct-injection architectures operating above 10 bar dominate pump specification complexity, with EPA Tier 3 and Euro 7 emission protocols mandating fluoropolymer seal materials and carbon composite impellers for vapor suppression.
- Diesel:High-pressure common rail systems require precision metering pumps with piezoelectric injector compatibility, concentrating demand in commercial vehicle platforms.
- Ethanol:E85 flex-fuel compatibility demands specialized elastomer seals resistant to alcohol-induced swelling and degradation.
- Biofuels:Biodiesel and renewable diesel variants impose additional chemical compatibility testing for pump housing materials and internal coatings.
Gasoline maintains specification leadership. Ethanol is gaining share fastest as flex-fuel platform deployment expands.
Installation Type:
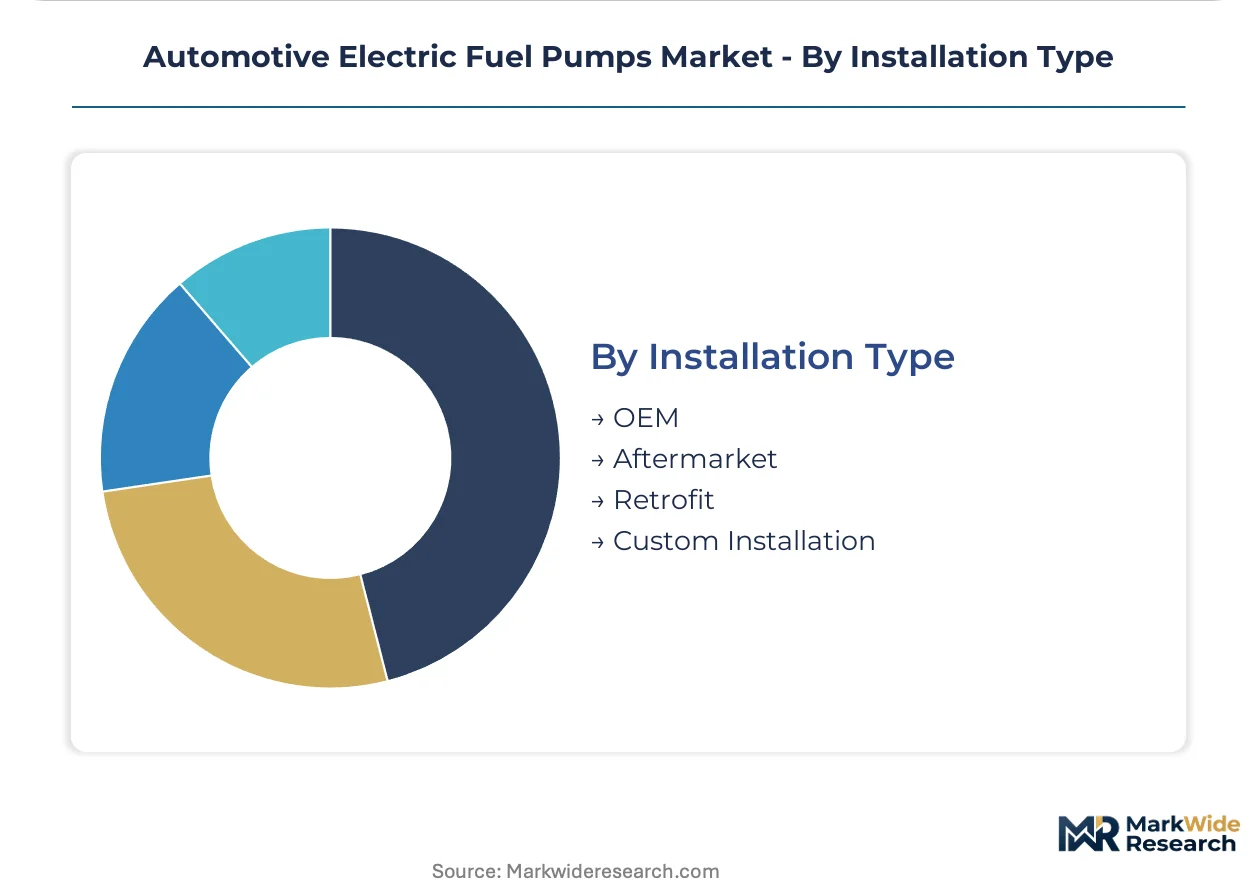
Channel structure separates captive OEM supply from independent aftermarket and retrofit conversion markets with diverging technical barriers.
- OEM:Integrated fuel module procurement by Volkswagen, BMW, and Mercedes-Benz in Germany anchors volume concentration, with qualification cycles spanning 24-36 months and requiring ISO 26262 ASIL-B functional safety certification for brushless motor control firmware.
- Aftermarket:Module complexity and sealed system diagnostic requirements are compressing independent garage participation in the United States, consolidating dealer service retention as EPA Tier 3 enforcement raises technical barriers.
- Retrofit:Hydrogen internal combustion conversion programs for commercial vehicles are emerging as bridge technologies requiring modified high-pressure pump architectures.
- Custom Installation:Low-volume specialty and motorsport applications favor configurable pump specifications outside standardized OEM platforms.
OEM commands procurement volume. Aftermarket is rotating up the share rankings as vehicle age profiles extend replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in automotive electric fuel pumps track regulatory stringency and domestic OEM production scale. Germany and Japan maintain structural surpluses in brushless pump exports, while the United States and China balance trade through module assembly localization.
United States
EPA Tier 3 evaporative emission enforcement drives sealed fuel module procurement from Volkswagen and BMW North American assembly plants. The regulation mandates onboard refueling vapor recovery and zero-leak fuel system integrity. Detroit's supplier corridor concentrates brushless motor controller production for domestic OEM qualification programs.
Germany
Volkswagen, BMW, and Mercedes-Benz platform standardization consolidates supplier pools around integrated fuel module architectures. Euro 7 hydrocarbon limits through ECHA enforcement elevate fluoropolymer seal specifications across EU member states. Stuttgart and Munich anchor captive semiconductor sourcing for brushless motor control electronics.
Japan
Long-haul trucking fleet operators unbundle fuel system maintenance contracts to negotiate direct pump replacement schedules with suppliers. METI coordinates domestic OEM alignment with international evaporative emission protocols. Nagoya's industrial belt concentrates high-volume brushless pump production for Asian passenger vehicle platforms.
China
MIIT implements GB standards for fuel consumption and emissions that push domestic OEMs toward higher-pressure direct-injection pumps. Dual carbon goals accelerate electrification programs compressing traditional pump demand while elevating specifications for remaining combustion platforms. Shanghai and Guangzhou house module assembly lines serving joint-venture OEM production.
India
BS-VI Phase II implementation opens qualification windows for sealed fuel module suppliers as Maruti Suzuki and Tata Motors redesign tank systems. BIS certification requirements align with Euro 6-equivalent evaporative emission benchmarks. Pune and Chennai manufacturing corridors attract brushless pump localization investments from Japanese and European tier-one suppliers.
Automotive Electric Fuel Pumps Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream on motor and controller supply. Market structure consolidates around three German and Japanese conglomerates with captive electronics sourcing, while mid-tier specialists fragment across regional OEM supply bases. Archetypes include integrated module assemblers, brushless motor component suppliers, and aftermarket service specialists. Competitive moves center on semiconductor foundry partnerships and fuel module assembly capacity expansion.
Among German-based conglomerates, Robert Bosch GmbH and Continental AG occupy positions anchoring European OEM supply through integrated fuel module qualification. Denso Corporation exemplifies the scale-driven archetype dominating Asian passenger vehicle procurement. These three entities represent the tier consolidating around brushless motor controller integration and sealed system architectures.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Delphi Automotive PLC |
| Visteon Corporation |
| Daewha Fuel Pump Ind. Ltd |
| Federal-Mogul Corporation |
| ACDelco |
| Aisan Industry Co. Ltd. |
| Others |
Cost & Logistics Intelligence
The Shanghai-Rotterdam maritime corridor carries fluoropolymer seal components and brushless motor controllers across concentrated supplier networks, with freight cost volatility amplifying price spreads between integrated module assemblers and component specialists. This logistics backbone connects Taiwan semiconductor foundries to German fuel module assembly plants, embedding freight exposure into tiered pricing structures that separate premium sealed-system suppliers from economy pump manufacturers serving aftermarket channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for integrated fuel modules, with price differentiation resting on ISO 26262 ASIL-B certification grade and volume scale commitments. Three-tier pricing structure across premium, standard, and economy levels stratifies procurement pools, with Volkswagen and BMW platform standardization compressing margins at the standard tier. Cost compression in economy brushed pump segments is intensifying because Chinese domestic OEMs source locally at aggressive price points. Aftermarket distributors exhibit highest price sensitivity due to diagnostic complexity barriers, while captive OEM supply relationships demonstrate lowest sensitivity given qualification lock-in effects.
Supply Chain Analysis
Neodymium magnet feedstock draws from Chinese rare earth processing facilities and Australian mining operations, with semiconductor controller wafers tethered to Taiwan foundry capacity. Brushless motor laminations and fluoropolymer seal materials complete the critical input matrix. Single-source vulnerability concentrates in Taiwan wafer fabrication, where motor controller ASIC bottlenecks constrain production scaling. Distribution runs through tier-one module assemblers with direct OEM qualification, bypassing traditional distributor networks for sealed fuel system architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance software and real-time fuel system diagnostics expand faster than hardware replacement cycles. Recurring revenue from embedded firmware updates and fleet telematics integration outpaces unit sales growth in mature passenger vehicle segments.
For Market Incumbents: Build captive semiconductor sourcing moats through foundry partnerships or in-house controller production to insulate against Taiwan wafer fabrication bottlenecks. Deepen backward integration into rare earth magnet supply through offtake agreements with Australian processors. Defend against Chinese domestic OEMs by accelerating Euro 7 qualification cycles that raise technical barriers for unproven entrants.
For New Entrants and Emerging Players: Pursue aftermarket diagnostic tool development for EPA Tier 3 sealed fuel systems, where independent garage technical barriers create white-space for specialized service equipment. Target India's BS-VI Phase II implementation window before Maruti Suzuki and Tata Motors lock in supplier qualifications. Anchor go-to-market through B2B e-commerce platforms reaching independent service garages directly.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized fuel pump divisions lacking brushless motor controller integration. Long-term viability hinges on hydrogen internal combustion retrofit capability as commercial vehicle decarbonization bridge technology. Watch Taiwan semiconductor foundry utilization rates as inflection indicator for brushless pump production scaling constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen and BMW procurement consolidation reduces supplier qualification pools to pre-qualified module assemblers. |
| Backward Integration into Semiconductors | Robert Bosch GmbH's captive controller sourcing controls cost exposure from Taiwan foundry concentration. |
| Hydrogen Pump Architecture Development | Modified high-pressure designs for hydrogen direct injection extend internal combustion relevance against battery electric displacement. |
| Geographic Manufacturing Footprint Expansion | Pune and Chennai corridors attract Japanese and European tier-one suppliers for Indian BS-VI Phase II qualification. |
| Software-Defined Diagnostics Investment | Predictive maintenance firmware creates recurring revenue streams beyond hardware replacement cycles. |
Research Approach
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet maintenance directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, EPA Tier 3 enforcement records, and ECHA Euro 7 preparatory documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators to constrain estimation variance.
Demand-supply balance dynamics across propulsion architecture transitions shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include vehicle class, fuel system pressure tier, OEM procurement tier, and regional regulatory cluster. CAGRs derived from segment-level volume trajectories weighted by content-per-vehicle assumptions. Forecast inputs incorporated electrification program timelines and evaporative emission protocol enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in rare earth commodity prices, semiconductor foundry utilization, or maritime freight rates would shift the trajectory materially. Forecasts reflect documented assumptions about regulatory enforcement timing and platform standardization adoption curves. Cross-checking against vehicle production forecasts from external automotive industry benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Suspension Spring Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
Passenger Car Motor Oil Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
AWD Coupling System Market
Automotive Parts
Automotive Spacer Ring Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Wheel Speed Sensor Tone Ring Market
Automotive Parts
Brass Synchronizer Ring Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Gasoline Direct Injection Market
Automotive Parts
Autonomous Forklift Market
Automotive Parts
Automotive Brake Fluid Market
Automotive Parts
South Africa Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Common Rail System Market