
 Automotive Carbon Ceramic Brakes Market | 2026-2036
Automotive Carbon Ceramic Brakes Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Carbon Ceramic Brakes Market Analysis
ECE R90 is hardening the cost-of-entry calculus for brake system suppliers seeking European type approval. Brembo S.p.A. leverages its Italian manufacturing base to dominate premium OEM fitments for supercar platforms. ZF Friedrichshafen AG anchors its position through captive supply relationships with German luxury vehicle assemblers. SGL Carbon GmbH specializes in carbon fiber preform production, controlling a critical upstream input that competitors must source externally.
Automotive carbon ceramic brakes are composite friction devices manufactured from silicon carbide-reinforced carbon matrices, typically processed through chemical vapor infiltration or liquid silicon infiltration at temperatures exceeding 1,400°C to achieve density above 1.8 g/cm³ and thermal stability beyond 1,000°C surface temperatures. These systems serve primarily to reduce unsprung mass by 50-70% versus cast iron while maintaining fade-free deceleration during repeated high-energy braking events. Disc Brakes occupy the dominant product position given their standard fitment across performance road vehicles, while Racing Brakes capture concentrated margin pools through low-volume, high-specification motorsport procurement. OEMs represent the most structurally defended demand channel due to multi-year platform integration cycles and homologation barriers that aftermarket providers cannot easily replicate.
The EU F-Gas Regulation constrains fluorinated greenhouse gas use in brake manufacturing ancillary processes, while REACH compliance obligations govern chemical disclosure across the carbon fiber supply chain. NHTSA FMVSS 135 braking performance standards in the United States create parallel certification requirements for suppliers targeting transatlantic OEM programs. Stakeholders must monitor evolving particulate emission regulations from ECHA and EPA, as brake wear debris classification decisions will determine whether carbon ceramic materials gain preferential treatment over conventional metallics in future vehicle certification schemes.
Market Dynamics
ECE R90 deceleration standards are hardening procurement specifications for brake system suppliers serving European OEM platforms, compressing homologation timelines and elevating technical qualification barriers for new market entrants.
Growth Catalysts
- EU Green Deal particulate mandates:Foundries face binding emission cuts from conventional cast-iron brake production, redirecting OEM sourcing toward carbon-ceramic alternatives that generate negligible airborne particulates during manufacturing.
- Bavarian automotive cluster concentration:Porsche, BMW, and Audi integrate carbon ceramic systems into flagship sport and luxury lines, creating concentrated demand pull from Stuttgart and Munich assembly plants.
- Silicon carbide preform advances:Chemical vapor infiltration process refinements are reducing production cycle times for carbon fiber reinforced matrices, expanding viable supply capacity for volume OEM programs.
Market Restraints
- Carbon fiber supply concentration:SGL Carbon GmbH controls critical preform production, forcing competitors into external sourcing dependencies with limited qualified alternative suppliers.
- Energy-intensive densification:Liquid silicon infiltration requires sustained furnace temperatures exceeding 1,400°C, exposing manufacturers to volatile European natural gas pricing and carbon border adjustment costs.
- Cast-iron substitution economics:Conventional metallics retain 70-80% cost advantage for standard passenger vehicle applications, constraining carbon ceramic penetration to performance segments.
Strategic Opportunities
- US NHTSA FMVSS 135 alignment:Transatlantic OEM programs require parallel certification, creating first-mover advantage for suppliers achieving dual-homologation status in American performance vehicle lines.
- Electric vehicle unsprung mass reduction:Battery-heavy platforms prioritize rotating weight savings, positioning carbon ceramic discs as range-extending enablers for premium EV architectures.
- Racing brake aftermarket expansion:Motorsport procurement channels offer concentrated margin pools through low-volume, high-specification orders from track-day enthusiast segments.
Industry Challenges
- High-temperature materials engineering talent scarcity:Chemical vapor infiltration expertise concentrates among senior technicians in Italian and German industrial centers, constraining workforce scaling for new production facilities.
- Multi-year platform integration cycles:OEM brake system selection locks in 4-6 years before vehicle launch, compressing supplier revenue visibility and requiring sustained R&D commitment without near-term returns.
- REACH chemical disclosure complexity:Carbon fiber supply chain transparency obligations impose documentation burdens across silicon carbide precursor sourcing, extending compliance timelines for new material qualifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Carbon Ceramic Brakes Market |
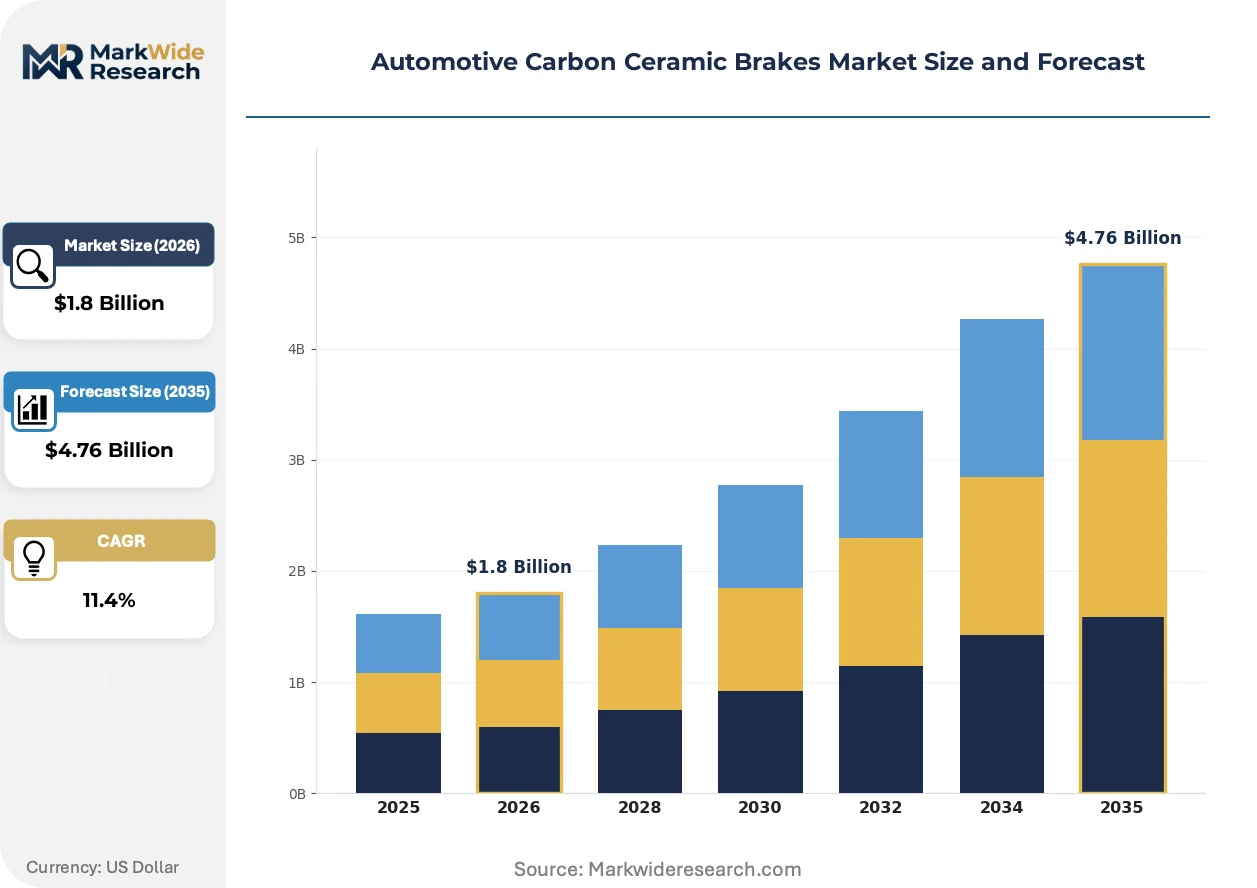
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brakes, Drum Brakes, Racing Brakes, Performance Brakes End User: Aftermarket Providers, Vehicle Assemblers, OEMs, Tier-1 Suppliers Application: Passenger Cars, Commercial Vehicles, Motorsports, Luxury Vehicles Technology: Wet Technology, Dry Technology, Carbon-Resin Technology, High-Temperature Technology |
| Companies Covered | Akebono Brake Industry Co., Ltd., ZF Friedrichshafen AG, Brembo S.p.A., Performance Friction Corporation, Wilwood Engineering Inc., Surface Transforms PLC, Continental AG, Rotora Inc., SGL Carbon GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Carbon Ceramic Brakes Market Emerging Trajectories
Advanced manufacturing processes and tightening environmental regulations are restructuring competitive positioning in brake system supply, with technology convergence and procurement model evolution creating new entry pathways.
Continuous fiber-reinforced ceramic matrix composites are rewriting performance benchmarks for thermal management in braking systems. High-performance passenger car manufacturers in Germany are accelerating adoption of these materials for flagship platforms. The technology is compressing development cycles for next-generation disc architectures that sustain fade-free operation across repeated high-energy deceleration events.
REACH compliance obligations now govern chemical disclosure across the entire carbon fiber supply chain, extending transparency requirements to silicon carbide precursor manufacturers. Industrial consequence includes elongated qualification timelines for new material suppliers seeking European market access. Brake system assemblers serving German OEM platforms are responding by consolidating supplier relationships with established preform producers possessing documented substance inventories.
Track-day enthusiast segments are driving unbundling of racing brake service contracts from original vehicle purchase, creating independent aftermarket channels for pad and disc replacement. Specialty distributors in motorsport hubs are displacing traditional dealer networks for high-specification procurement. This behavioral shift concentrates in Bavaria's automotive cluster, where proximity to Nürburgring and Hockenheim circuits supports rapid-turn refurbishment demand.
Automotive Carbon Ceramic Brakes Market Segmentation
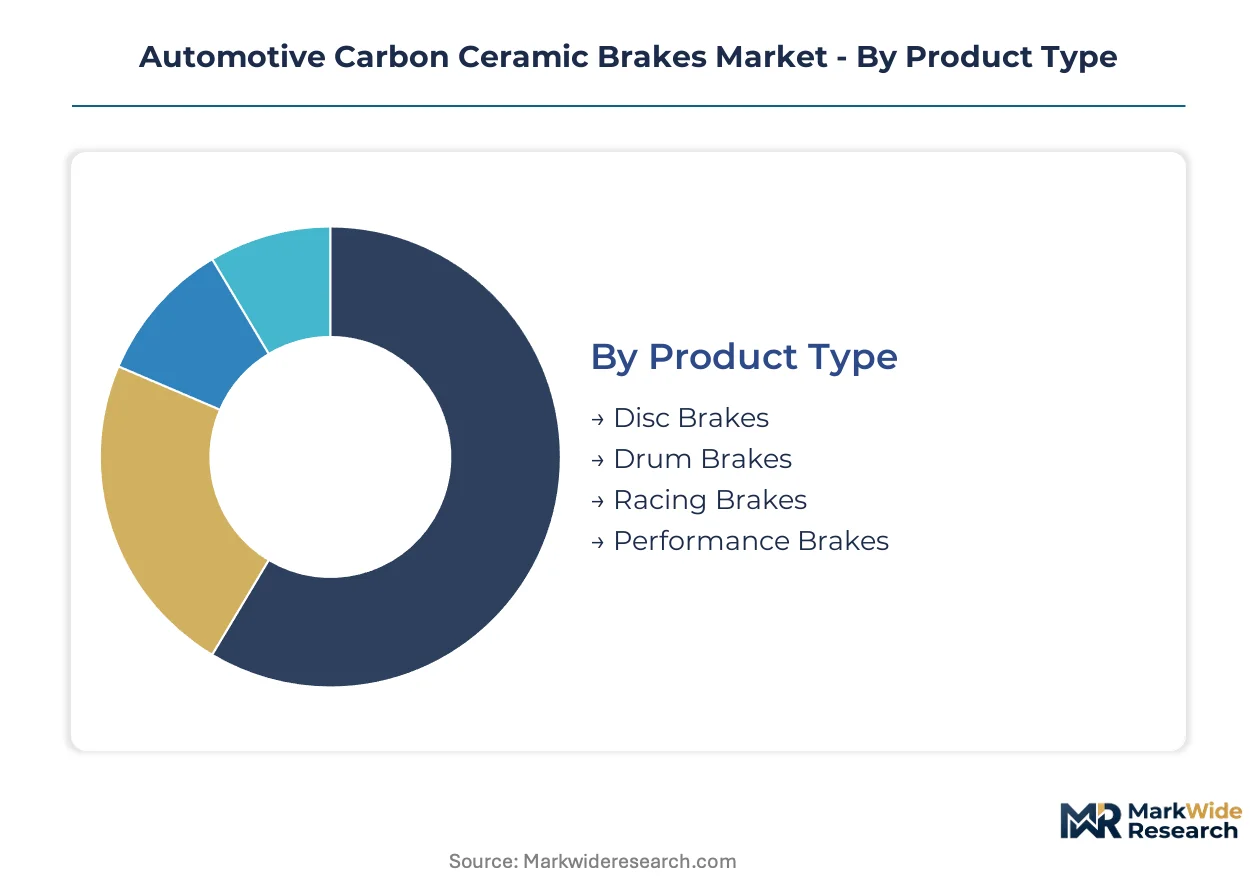
Carbon ceramic brake procurement splits sharply between volume road applications and specialized motorsport platforms. Technology selection and supply channel configuration determine margin capture across each segment tier.
Product Type:
Disc Brakes anchor volume production while Racing Brakes command specialized margin pools.
- Disc Brakes:Silicon carbide-reinforced carbon matrix discs processed through chemical vapor infiltration at temperatures exceeding 1,400°C. Porsche, BMW, and Audi in Bavaria specify these for flagship sport and luxury vehicle lines under ECE R90 deceleration mandates.
- Racing Brakes:Low-volume, high-specification systems for motorsport procurement with fade-free thermal stability beyond 1,000°C surface temperatures. Track-day enthusiast segments in Germany's Nürburgring and Hockenheim corridors drive concentrated aftermarket refurbishment demand.
- Drum Brakes:Limited carbon ceramic adoption due to heat dissipation constraints in enclosed drum architectures.
- Performance Brakes:Intermediate specification tier bridging road and track applications with modified thermal mass characteristics.
Mature deployment sits with Disc Brakes. Newer deployment is concentrated in Racing Brakes.
End User:
Supply channel structure determines homologation burden and revenue visibility duration.
- OEMs:Multi-year platform integration cycles lock in brake system selection 4-6 years before vehicle launch. German luxury vehicle assemblers maintain structurally defended demand through captive supply relationships with Tier-1 suppliers.
- Tier-1 Suppliers:ZF Friedrichshafen AG and Brembo S.p.A. dominate premium fitments through direct OEM platform integration, bearing full ECE R90 and NHTSA FMVSS 135 certification costs.
- Vehicle Assemblers:Final integration points for brake system modules with limited direct procurement of carbon ceramic components.
- Aftermarket Providers:Service contract unbundling from original vehicle purchase creates independent channels for pad and disc replacement among motorsport enthusiasts.
Revenue concentration favors Tier-1 Suppliers. Margin expansion is shifting toward Aftermarket Providers.
Application:
Unsprung mass reduction priorities vary by vehicle architecture and duty cycle intensity.
- Luxury Vehicles:Battery-heavy electric platforms from German OEMs prioritize rotating weight savings, positioning carbon ceramic discs as range-extending enablers for premium EV architectures.
- Motorsports:Repeated high-energy braking events demand fade-free deceleration performance. Chemical vapor infiltration process refinements are compressing development cycles for next-generation disc architectures in this segment.
- Passenger Cars:Standard performance road vehicles with intermittent high-load braking requirements.
- Commercial Vehicles:Limited penetration due to cast-iron cost economics and duty cycle mismatch with carbon ceramic thermal characteristics.
Technology leadership resides in Motorsports. Volume scaling is accelerating in Luxury Vehicles.
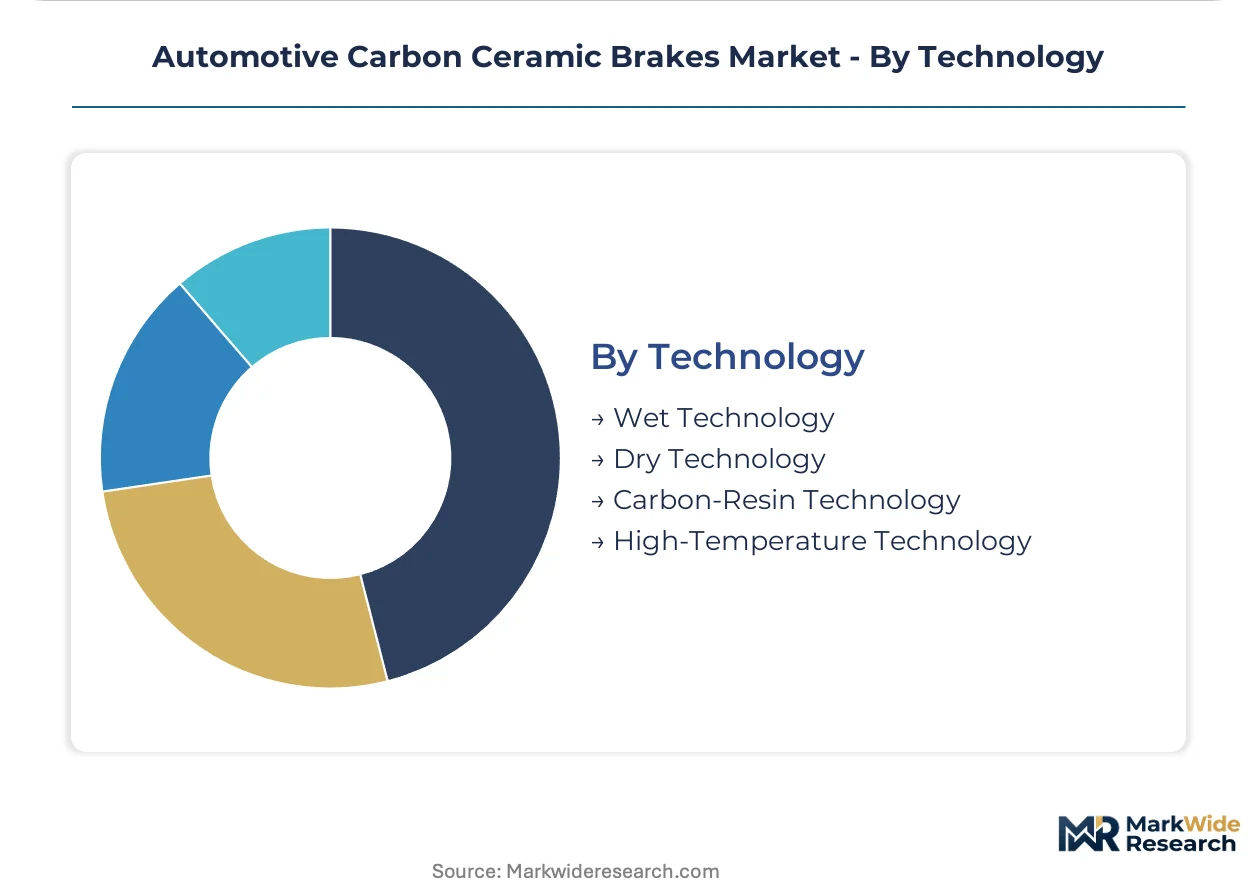
Technology:
Manufacturing process selection governs density achievement and production cycle economics.
- Dry Technology:Chemical vapor infiltration of carbon fiber preforms without liquid phase silicon introduction. SGL Carbon GmbH controls critical upstream preform production for this pathway.
- Wet Technology:Liquid silicon infiltration requiring sustained furnace temperatures exceeding 1,400°C, exposing manufacturers to volatile European natural gas pricing and carbon border adjustment costs.
- Carbon-Resin Technology:Polymer-derived carbon matrices with intermediate thermal performance characteristics.
- High-Temperature Technology:Specialized densification protocols for extreme thermal cycling applications in motorsport environments.
Process maturity centers on Wet Technology. Capacity expansion is targeting Dry Technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's automotive cluster operates as the primary tax-advantaged manufacturing zone, concentrating high-performance brake system procurement from Stuttgart to Munich assembly corridors. German OEM platform integration drives regional sourcing intensity.
Germany
Porsche, BMW, and Audi anchor carbon ceramic brake demand through flagship sport and luxury vehicle programs. ECE R90 deceleration standards harden procurement specifications for suppliers seeking European type approval. Bavaria's Nürburgring and Hockenheim circuit proximity sustains concentrated aftermarket refurbishment demand.
Italy
Brembo S.p.A. leverages its Italian manufacturing base to dominate premium OEM fitments for supercar platforms. REACH compliance obligations govern chemical disclosure across carbon fiber supply chains entering European markets. Emilia-Romagna's motorsport engineering corridor concentrates chemical vapor infiltration expertise among senior technicians.
United States
NHTSA FMVSS 135 braking performance standards create parallel certification requirements for suppliers targeting transatlantic OEM programs. EPA particulate emission monitoring influences brake wear debris classification decisions for future vehicle certification. California's electric vehicle density prioritizes unsprung mass reduction for battery-heavy premium architectures.
United Kingdom
Surface Transforms PLC exemplifies specialized carbon ceramic disc production serving motorsport and performance road applications. The UK's departure from EU regulatory alignment creates dual-track homologation burdens for brake system exporters. Motorsport Valley around Oxfordshire and Northamptonshire sustains low-volume, high-specification racing brake procurement.
Japan
Akebono Brake Industry Co., Ltd. represents integrated brake system manufacturing with historical strength in friction material science. METI industrial policy supports advanced materials R&D for next-generation vehicle platforms. Toyota City and surrounding Aichi prefecture clusters concentrate hybrid and electric vehicle brake system development.
Automotive Carbon Ceramic Brakes Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. Tier-1 suppliers bearing full ECE R90 and NHTSA certification costs dominate structurally defended OEM channels. Three archetypes prevail: integrated automotive suppliers with captive brake divisions, specialized friction material houses, and upstream carbon fiber preform controllers. Competitive moves concentrate on multi-year platform integration cycles and strategic partnerships for silicon carbide supply security.
Among German-based industrial conglomerates, ZF Friedrichshafen AG anchors its position through captive supply relationships with luxury vehicle assemblers. Brembo S.p.A. exemplifies the specialized friction material archetype with Italian manufacturing concentration. SGL Carbon GmbH represents upstream preform control, forcing competitors into external sourcing dependencies. These three occupy positions spanning the value chain from raw material to final assembly.
| Leading Market Players |
|---|
| Akebono Brake Industry Co., Ltd. |
| ZF Friedrichshafen AG |
| Brembo S.p.A. |
| Performance Friction Corporation |
| Wilwood Engineering Inc. |
| Surface Transforms PLC |
| Continental AG |
| Rotora Inc. |
| SGL Carbon GmbH |
| Others |
Supply Flow & Price Mechanics
Silicon carbide powder price indices cascade through carbon ceramic brake manufacturing into three distinct procurement tiers: motorsport-specification systems commanding premium placement, volume OEM programs negotiating long-term offtake terms, and aftermarket refurbishment channels absorbing spot-market volatility. Chemical vapor infiltration furnace capacity constraints in Germany and Italy concentrate pricing power among incumbent preform producers, compressing margin capture for second-tier assemblers.
Pricing Analysis
Lead-time compression commands measurable pricing premiums, with spot inventory availability for racing brake discs trading at substantial discounts against six-month forward contracts for OEM platform integration. Three-tier pricing structure across premium, standard, and economy levels separates ECE R90-certified motorsport systems from volume road applications and unbranded aftermarket alternatives. Cost compression in standard-tier road applications is intensifying because foundry emission compliance costs are eroding the cast-iron cost advantage that previously constrained carbon ceramic penetration. Aftermarket providers serving track-day enthusiasts exhibit highest price sensitivity, while captive OEM supply relationships demonstrate lowest elasticity due to homologation lock-in effects.
Supply Chain Analysis
Refurbishment flows from Nürburgring and Hockenheim circuit operators back to Bavarian preform processors are creating closed-loop material recovery channels that reduce virgin carbon fiber demand. Geographic supply concentrates in Germany, Italy, and Japan, with SGL Carbon GmbH controlling critical preform production in Bavaria and Brembo S.p.A. anchoring finished disc manufacturing in Emilia-Romagna. Raw material dependencies rest on polyacrylonitrile precursor fibers, silicon carbide powders, and high-purity liquid silicon. Single-source vulnerability around chemical vapor infiltration expertise concentrates among senior technicians in Italian and German industrial centers. Distribution runs through Tier-1 supplier direct OEM integration for volume programs, with specialty motorsport distributors handling low-volume racing procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chemical vapor infiltration furnace capacity scarcity props pricing across all tiers, creating structurally defended returns for incumbent preform producers while constraining new entrant scale-up economics.
For Market Incumbents: Deepen captive supply relationships with Bavarian OEM platforms through multi-year preform offtake commitments that lock out emerging competitors. Expand in-house silicon carbide precursor production to offset SGL Carbon GmbH supply concentration risk. Prioritize ECE R90 certification investment for next-generation electric vehicle architectures before platform integration windows close. For New Entrants and Emerging Players: Dry technology process innovation offers the most viable entry vector, bypassing liquid silicon infiltration energy cost exposure that burdens established wet-technology producers. Target aftermarket refurbishment channels serving German track-day enthusiasts, where homologation barriers are lowest and margin capture is concentrated. Pursue direct partnerships with racing circuit operators for rapid-turn disc replacement service contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor carbon fiber preform specialists with documented REACH compliance inventories in Germany and Italy. Long-term viability hinges on electric vehicle platform penetration rates and regulatory preference for particulate-free brake manufacturing. Monitor ECHA brake wear debris classification decisions as the critical inflection signal for carbon ceramic material preference over conventional metallics.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Vapor Infiltration Capacity Expansion | Reduces production cycle times for silicon carbide-reinforced matrices serving volume OEM programs. |
| REACH-Compliant Preform Supply Agreement | Locks in upstream carbon fiber sourcing with documented substance inventories for European market access. |
| Dual ECE R90 and NHTSA FMVSS 135 Certification | Enables transatlantic OEM platform integration for American performance vehicle lines. |
| Electric Vehicle Platform Partnership | Positions carbon ceramic discs as unsprung mass reduction enablers for battery-heavy premium architectures. |
| Racing Brake Aftermarket Service Contract | Captures concentrated margin pools from track-day enthusiast refurbishment demand near German circuits. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, chemical vapor infiltration technicians, and motorsport team logistics managers. Bottom-up vehicle production databases and top-down brake system content-per-vehicle estimates were triangulated against ECE R90 certification records and EPA emission disclosure filings.
Granularity-level modeling disaggregated volume and value outputs across product type, end-user channel, vehicle application, and manufacturing technology dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate convergence analysis. Industry-specific forecast inputs incorporated electric vehicle platform rollout schedules and evolving particulate emission regulatory thresholds from ECHA.
Several conditions sit outside the modeled scope, including potential brake wear debris reclassification decisions, abrupt natural gas price shocks affecting liquid silicon infiltration economics, and geopolitical disruption to carbon fiber precursor supply chains. Practitioners should monitor ECHA regulatory consultations and OEM electric vehicle architecture announcements for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
North America Automotive Hydraulic Actuators Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Europe Torque Vectoring Market
Automotive Components
Iran Automotive Lubricants Market
Automotive Components
Russia Automotive Electric Actuators Market
Automotive Components
Global Automotive Radiator Market
Automotive Components
Automotive Bearing Market
Automotive Components
Automotive Stainless Steel Tubes Market
Automotive Components
Automotive Actuators Market
Automotive Components
Automotive Brackets Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
India Automotive Heat Exchanger Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Automotive Carbon Thermoplastic Market