
 Automotive Resonator Market | 2026-2036
Automotive Resonator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Resonator Market Outlook
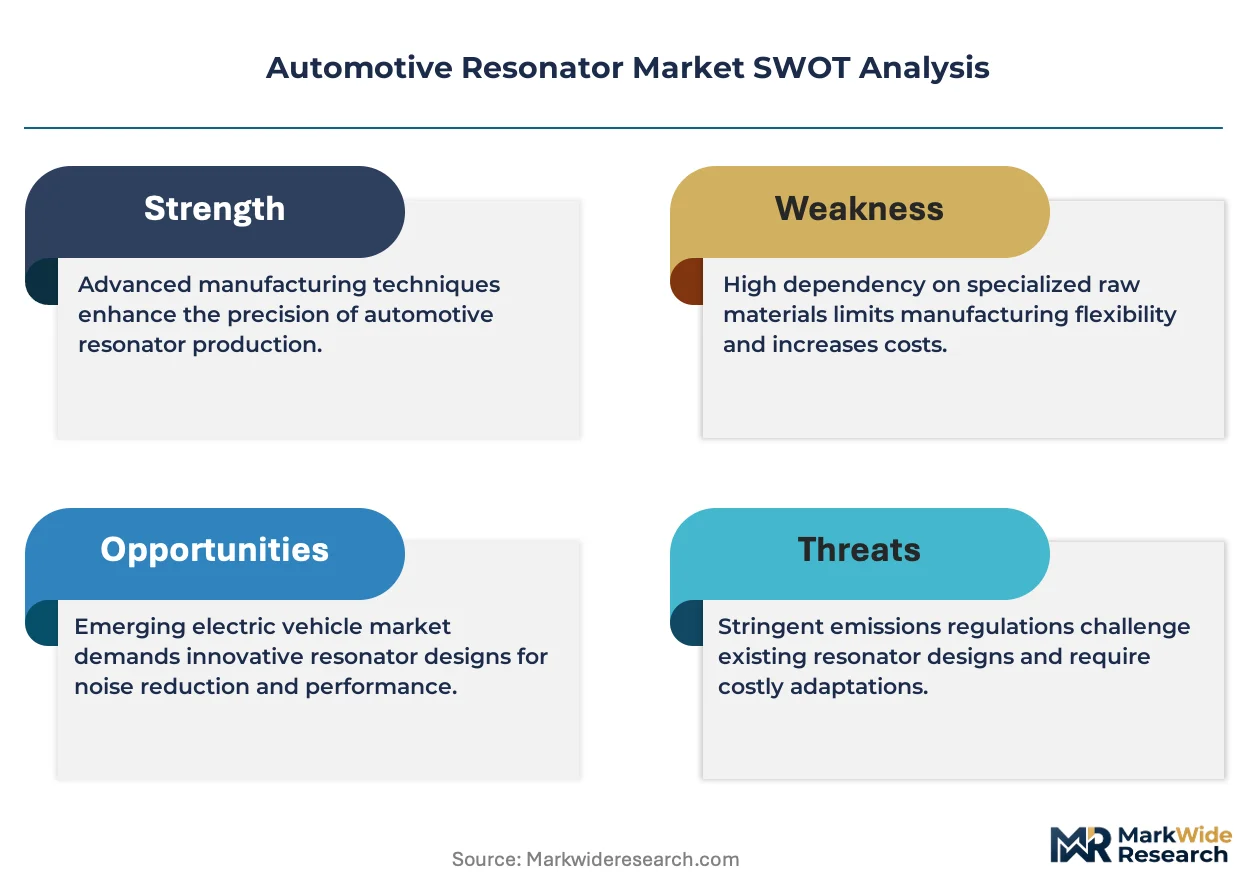
Commercial vehicle electrification is rebalancing demand toward cabin-focused acoustic management. Tenneco Inc. leverages its exhaust heritage to pivot into active noise cancellation modules for hybrid platforms. MANN+HUMMEL anchors European supply through specialized filtration-integrated resonator designs. MAHLE GmbH competes on thermal-acoustic coupling expertise in high-performance engine bays.
An automotive resonator is a tuned acoustic device, typically fabricated from 409-grade stainless steel or aluminum alloys with perforated internal tubes and fiberglass packing, engineered to attenuate specific frequency bands in exhaust or intake systems. Its primary function is destructive interference of pressure waves to meet regulatory noise limits while preserving engine backpressure efficiency. The exhaust resonator segment remains structurally mature with consolidated margin pools among Tier-1 incumbents, whereas active resonator technology captures expanding value as OEMs electrify powertrains and eliminate mechanical exhaust sources. Stainless steel dominates material procurement for thermal durability, though aluminum gains share where weight reduction governs platform economics.
The EPA and NHTSA jointly enforce pass-by noise and emissions compliance that dictates resonator specification thresholds for vehicles sold in the United States. EMA and REACH frameworks in Europe restrict certain acoustic packing materials and mandate recyclability disclosures, elevating development costs for suppliers without green chemistry portfolios. Stakeholders must monitor how dual carbon goals in China and evolving EPA test cycles reshape the technical boundary between mechanical and electronic noise abatement architectures.
Market Dynamics
Powertrain electrification is collapsing mechanical exhaust volumes while forcing acoustic engineering into cabin interiors and active electronic systems. This structural shift fragments incumbent supply chains and elevates electronics specialists alongside traditional metal-forming suppliers.
Growth Catalysts
- Pass-by noise enforcement:NHTSA and EPA test cycles in the United States now mandate lower decibel thresholds for vehicle certification, forcing OEMs to redesign intake and exhaust acoustic architectures across combustion and hybrid platforms.
- China's dual carbon goals:Domestic EV production quotas and premium platform scaling concentrate resonator demand for cabin noise management in electric drivetrains from BYD, NIO, and XPeng supply bases.
- Active noise cancellation modules:Hybrid powertrain architectures require electronic resonator systems that cancel harmonic frequencies through speaker arrays and software algorithms rather than physical wave interference.
Market Restraints
- Stainless steel price volatility:409-grade stainless feedstock costs fluctuate with nickel and chromium spot markets, compressing margin pools for stamped resonator housings and perforated tube assemblies.
- Supply concentration in East Asian forging:Cold-forming capacity for thin-wall resonator shells clusters in Zhejiang and Guangdong provinces, exposing Tier-1 suppliers to logistics disruption and tariff exposure.
- Fiberglass packing substitution limits:REACH restrictions on certain glass fiber acoustic media in Europe constrain material selection without mature biodegradable alternatives at equivalent thermal durability.
Strategic Opportunities
- Underpenetrated Indian EV procurement:Domestic electric two-wheeler and three-wheeler production lacks established acoustic tiering, creating white space for resonator suppliers with localized stamping and packing operations.
- Software-defined acoustic tuning:Convergence of CAN bus integration and machine learning-based frequency mapping enables resonator systems that adapt to driving modes without hardware swaps.
- EU battery regulation recyclability mandates:Component traceability requirements under the EU Green Deal favor resonator designs with disassembly-friendly joints and material passports, rewarding early compliance investments.
Industry Challenges
- Acoustic-thermal simulation talent scarcity:Finite element analysis expertise combining exhaust gas dynamics with NVH modeling concentrates in Germany and Japan, limiting supplier engineering bandwidth elsewhere.
- Dual certification timelines:Simultaneous EPA and EMA homologation for global platform resonators extends development cycles by 8-14 months, delaying revenue recognition on shared vehicle architectures.
- Legacy exhaust supplier integration:Electronics-first active noise systems require firmware competencies alien to metal-forming incumbents, forcing partnership or acquisition decisions under compressed electrification schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Resonator Market |
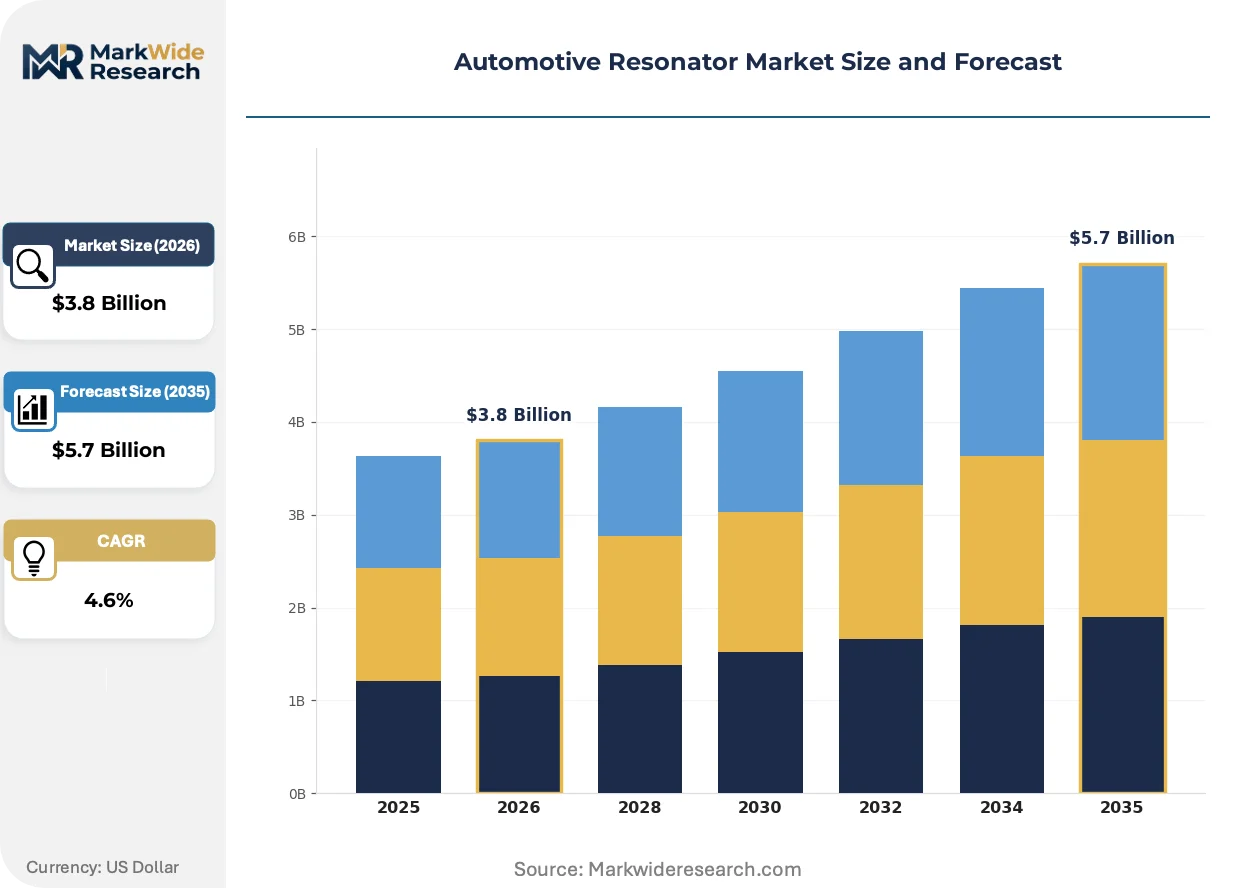
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Combustion Engine, Electric Vehicle, Exhaust Resonator, Active Resonator Material: Stainless Steel, Aluminum, Plastic, Composites End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Acoustic Engineering, Computational Fluid Dynamics, Simulation Software, Sound Design |
| Companies Covered | Tenneco Inc., MANN+HUMMEL, MAHLE GmbH, Faurecia, Donaldson Company, Inc., AISIN CORPORATION, K&N Engineering, Inc., Continental AG, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Resonator Market Strategic Shifts
Acoustic engineering is migrating from passive mechanical devices toward software-integrated active systems, with material science and regulatory chemistry simultaneously constraining and enabling next-generation designs.
Aluminum-silicon alloy resonator housings are rewriting thermal-acoustic tradeoffs in high-performance engine bays. Porsche and BMW M-division procurement teams specify these castings for weight-critical underbody packaging. The substitution is compressing stainless steel share in premium segments where 15-20 kilogram exhaust system reductions justify unit cost premiums.
REACH annex XVII restrictions on persistent organic pollutants in acoustic packing materials are forcing reformulation of fiberglass blends across European supply chains. MANN+HUMMEL and MAHLE GmbH have accelerated bio-based fiber testing programs to maintain EMA certification eligibility. The regulatory friction falls heaviest on mid-tier suppliers without in-house polymer chemistry capabilities, consolidating specification authority among integrated filtration-acoustic houses.
Fleet procurement departments now unbundle resonator specification from exhaust system turnkey contracts, issuing direct RFQs to acoustic specialists for active cabin modules. This disintermediation bypasses traditional exhaust Tier-1s and channels volume toward electronics-originated suppliers with software integration competencies. The pattern is most visible in German premium EV platforms where platform-sharing consortia centralize NVH purchasing decisions separately from powertrain sourcing.
Automotive Resonator Market Segmentation
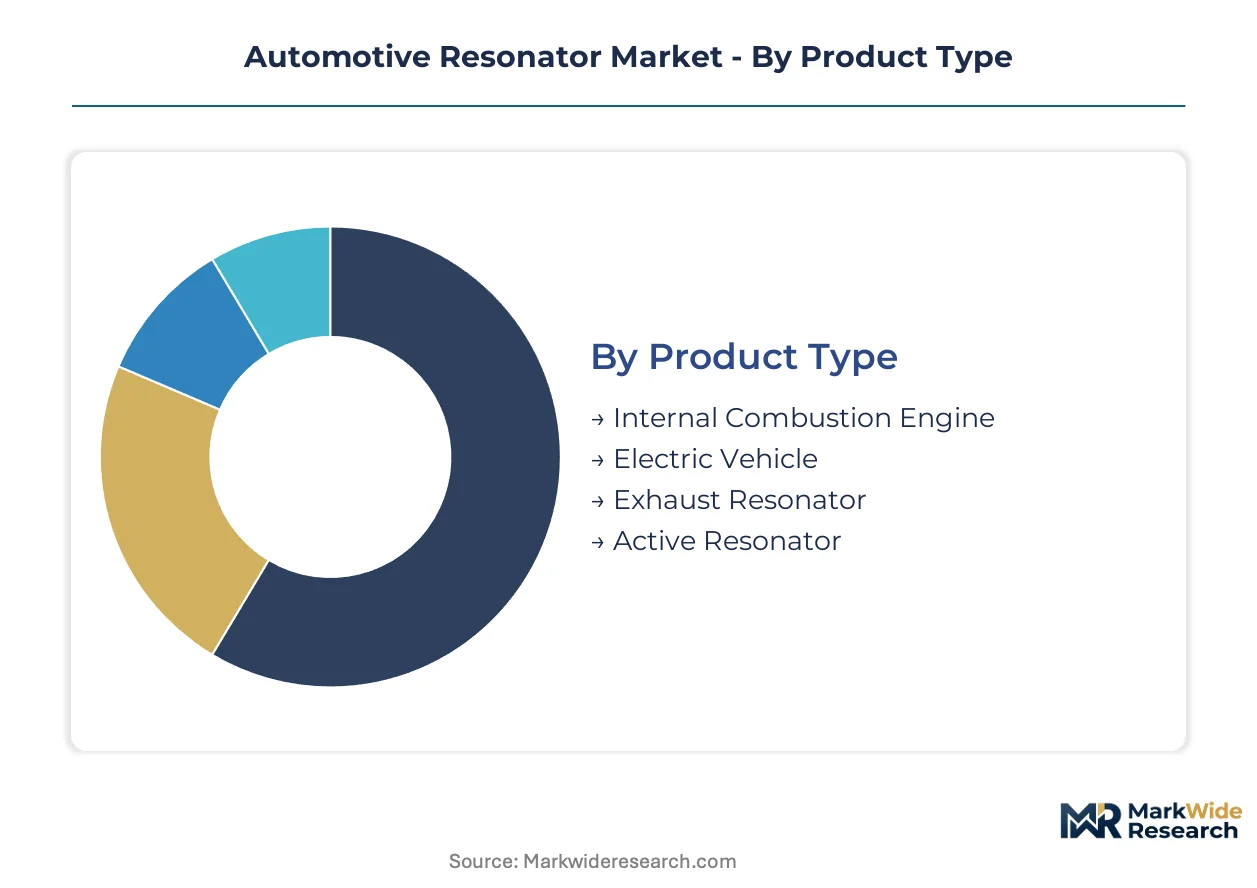
Automotive resonator procurement fragments across legacy mechanical systems and emerging electronic architectures. Material selection and customer channel determine margin pools, while powertrain electrification rebalances segment significance.
Product Type:
Volume concentration favors combustion-era designs, though premium value migrates toward active electronic systems.
- Internal Combustion Engine:Tuned cavity resonators with perforated baffles and fiberglass packing attenuate exhaust harmonics through wave cancellation. Demand concentrates in Detroit Three and German premium OEM supply chains where NHTSA pass-by noise enforcement mandates hardware refresh cycles.
- Electric Vehicle:Cabin-focused active modules replace underbody exhaust hardware, employing speaker arrays and CAN-integrated algorithms to manage road and wind noise. Procurement from BYD, NIO, and XPeng concentrates in Zhejiang and Guangdong forging clusters.
- Exhaust Resonator:Stainless steel shells with thermal-acoustic packing remain structurally mature.
- Active Resonator:Software-defined frequency mapping enables adaptive noise cancellation without hardware swaps.
Mature deployment sits with Internal Combustion Engine. Newer deployment is concentrated in Electric Vehicle.
Material:
Cost tier stratification separates premium aluminum applications from commodity stainless procurement.
- Stainless Steel:409-grade alloys dominate exhaust resonator fabrication for thermal durability above 600°C. Nickel and chromium spot volatility compresses margins for stamped housings and perforated tube assemblies sourced through East Asian forging networks.
- Aluminum:Silicon-alloy castings from Porsche and BMW M-division procurement enable 15-20 kilogram system weight reductions. Premium segment share gains where underbody packaging constraints govern platform economics.
- Plastic:Polymer housings serve intake-side acoustic management at lower thermal loads.
- Composites:Bio-based fiber formulations respond to REACH annex XVII restrictions on persistent organic pollutants.
Stainless Steel commands the highest shipment volumes. Aluminum delivers the steepest expansion trajectory in premium segments.
End User:
Customer type determines specification authority and contract structure across the value chain.
- OEMs:Volkswagen Group and Toyota Motor Corporation centralize NVH purchasing decisions for platform-sharing architectures, issuing direct RFQs that bypass traditional exhaust Tier-1 intermediaries.
- Aftermarket Providers:Independent distributors and repair networks stock universal-fit resonators for legacy fleet maintenance. Demand clusters where vehicle age exceeds seven years and original equipment warranties expire.
- Vehicle Assemblers:Contract manufacturers integrate resonator modules into complete exhaust or cabin systems.
- Tier-1 Suppliers:Integrated filtration-acoustic houses consolidate specification authority through chemistry and simulation capabilities.
Specification control concentrates with OEMs. Volume fragmentation persists in Aftermarket Providers.
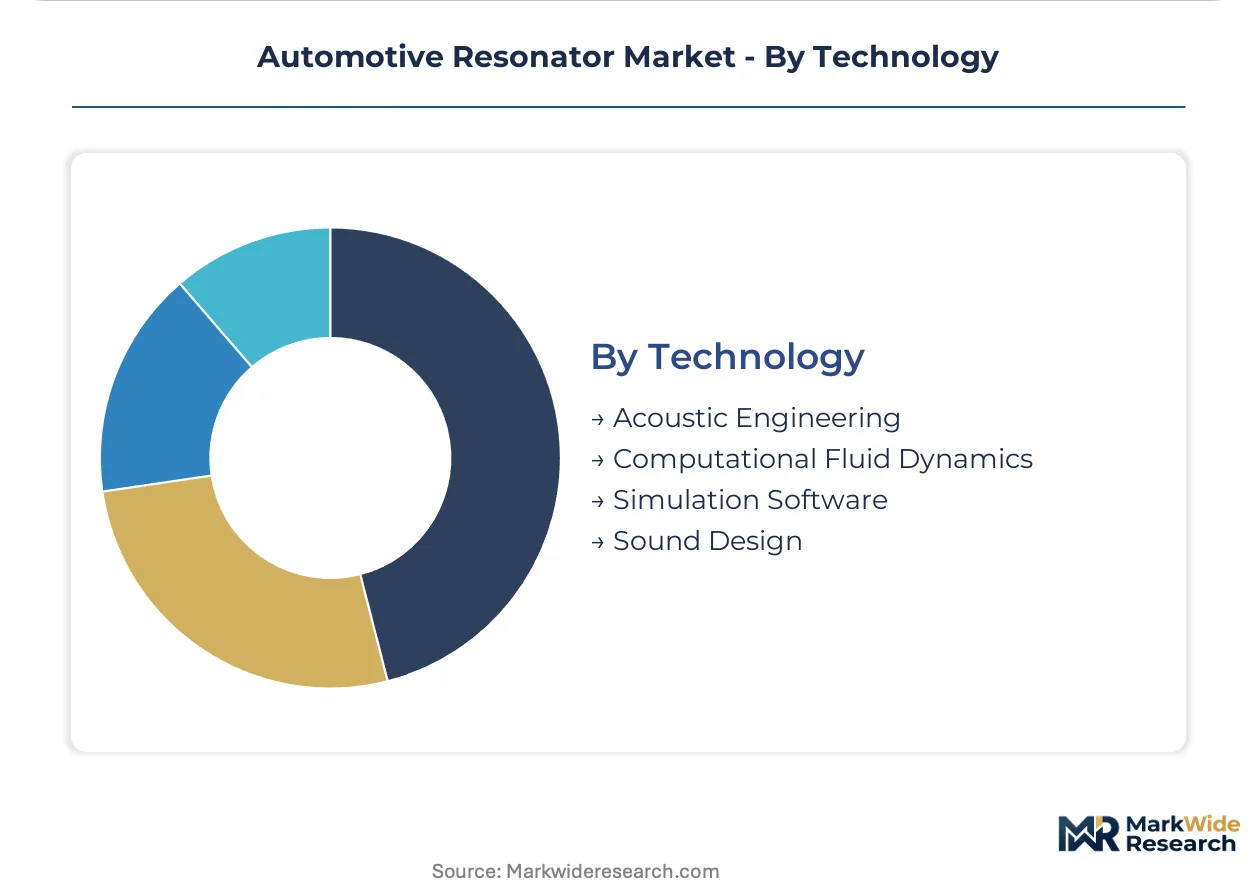
Technology:
Capability maturity separates established simulation methods from emerging software-integrated approaches.
- Acoustic Engineering:Destructive interference design for passive resonators relies on Helmholtz cavity calculations and empirical tuning. German and Japanese finite element analysis expertise limits supplier engineering bandwidth elsewhere.
- Computational Fluid Dynamics:Exhaust gas dynamics modeling combines thermal and NVH simulation for high-performance engine bay packaging. Dual EPA and EMA homologation requirements extend development cycles.
- Simulation Software:Machine learning-based frequency mapping enables adaptive resonator tuning across driving modes.
- Sound Design:Active cabin noise sculpting integrates with infotainment and autonomous driving interfaces.
Established deployment centers on Acoustic Engineering. Capability investment concentrates in Simulation Software.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in East Asian forging networks while consumption tilts toward electrified vehicle markets in China, Germany, and the United States. Regulatory divergence across EPA, EMA, and MIIT frameworks fragments homologation pathways. Tier-1 suppliers navigate this geography by anchoring stamping capacity near Zhejiang and Guangdong while positioning active acoustic engineering closer to OEM R&D centers.
United States
NHTSA pass-by noise enforcement and EPA emissions compliance drive hardware refresh cycles across Detroit Three supply chains. The Inflation Reduction Act's domestic content incentives reshape procurement patterns for resonator stampings. Manufacturing concentration clusters in Michigan and Ohio, where exhaust system integration plants serve Ford and General Motors platforms.
China
Domestic EV production quotas from BYD, NIO, and XPeng concentrate demand for cabin noise management modules. MIIT dual carbon goals and GB standards accelerate the shift from mechanical exhaust to active electronic systems. Zhejiang and Guangdong provinces host cold-forming capacity for thin-wall resonator shells serving both local OEMs and export markets.
Germany
Porsche and BMW M-division procurement of aluminum-silicon alloy housings prioritizes weight-critical underbody packaging. EMA and REACH annex XVII restrictions on acoustic packing materials force reformulation of fiberglass blends. Bavaria and Baden-Württemberg anchor finite element analysis expertise combining exhaust gas dynamics with NVH modeling.
Japan
Toyota Motor Corporation and hybrid platform consortia centralize NVH purchasing decisions for active noise cancellation modules. METI industrial standards govern thermal-acoustic coupling specifications in high-performance engine bays. Kanto and Chubu regions concentrate supplier engineering bandwidth for computational fluid dynamics simulation.
India
Domestic electric two-wheeler and three-wheeler production lacks established acoustic tiering, creating procurement white space. BIS certification requirements and PLI scheme incentives attract localized stamping and packing operations. Maharashtra and Tamil Nadu industrial corridors emerge as candidate locations for resonator manufacturing investments.
Automotive Resonator Market Competitive Environment
Top-tier vendors anchor specification authority through integrated filtration-acoustic capabilities, while mid-tier fabricators compete on stamping scale and regional logistics. The structure consolidates around chemistry and simulation competencies, with electronics specialists displacing traditional metal-forming suppliers in electrified segments. Three archetypes dominate: integrated filtration-acoustic houses, exhaust heritage pivots into active modules, and electronics-first entrants from adjacent automotive domains. Competitive moves center on backward integration into bio-based fiber formulations and firmware partnerships to compress electrification schedules.
Within the integrated filtration-acoustic tier, MANN+HUMMEL GmbH and MAHLE GmbH exemplify European supply anchoring through specialized designs and thermal-acoustic coupling expertise. Tenneco Inc. occupies a position representing exhaust heritage pivots, leveraging legacy stamping capabilities toward hybrid platform modules. These three entities collectively illustrate the competitive tension between mechanical legacy and electronic transformation reshaping procurement patterns across OEM supply bases.
| Leading Market Players |
|---|
| Tenneco Inc. |
| MANN+HUMMEL |
| MAHLE GmbH |
| Faurecia |
| Donaldson Company, Inc. |
| AISIN CORPORATION |
| K&N Engineering, Inc. |
| Continental AG |
| Denso Corporation |
| Others |
Value Chain & Pricing Dynamics
Nickel and chromium spot market indices cascade through 409-grade stainless procurement into three-tier pricing stratification across premium, standard, and economy resonator tiers. OEMs with platform-sharing architectures extract volume discounts from East Asian forging networks, while mid-tier fabricators absorb feedstock volatility through compressed margin pools on perforated tube assemblies.
Pricing Analysis
Margin tightening in commodity stainless stampings reflects nickel price volatility and REACH-driven reformulation costs for European acoustic packing. Tiered pricing separates aluminum-silicon alloy castings for Porsche and BMW M-division procurement from commodity 409-grade exhaust housings, with premium segments commanding unit cost premiums for 15-20 kilogram system weight reductions. Price differentiation rests on thermal durability certification and finite element analysis bandwidth, with aftermarket distributors exhibiting highest price sensitivity and German premium OEMs least.
Supply Chain Analysis
Ocean freight rate fluctuations from Zhejiang and Guangdong ports amplify landed cost variability for thin-wall resonator shells destined to Detroit Three integration plants. Cold-forming capacity concentrates in China, with secondary forging networks in Germany and Japan serving thermal-acoustic coupling specifications. Raw material dependencies span nickel-chromium stainless feedstock, bio-based fiber formulations, and silicon-alloy aluminum castings. Tariff exposure on Chinese-origin stampings constitutes the primary structural risk. Distribution runs through Tier-1 exhaust system integrators toward OEM platform engineering teams, with direct RFQs to acoustic specialists bypassing traditional intermediaries in electrified segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive resonator market functions as a cost-of-compliance arena where REACH annex XVII and EPA pass-by noise enforcement erect barrier-to-entry moats favoring integrated filtration-acoustic houses with in-house polymer chemistry capabilities.
For Market Incumbents: Deploy firmware partnership strategies to compress electrification schedules and counter electronics-first entrants from adjacent automotive domains. Acquire computational fluid dynamics talent in Germany and Japan to defend specification authority against mid-tier fabricators lacking NVH simulation bandwidth. Anchor backward integration into bio-based fiber formulations to maintain EMA certification eligibility as REACH restrictions tighten. For New Entrants and Emerging Players: Domestic electric two-wheeler and three-wheeler assemblers in India present procurement white space lacking established acoustic tiering. Target localized stamping and packing operations in Maharashtra and Tamil Nadu industrial corridors to capture PLI scheme incentives. Position through BIS certification compliance as a differentiated entry credential against unqualified regional fabricators. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier metal-forming suppliers with captive East Asian forging relationships and idle capacity in Zhejiang province. Long-term viability hinges on hybrid platform module pivots rather than pure combustion exhaust exposure. Monitor EPA test cycle revision timelines as inflection indicators for hardware refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Active Noise Cancellation Module Development | Enables specification capture from BYD, NIO, and XPeng cabin-focused procurement teams. |
| Backward Integration into Bio-Based Fibers | Secures REACH annex XVII compliance for European supply anchoring against reformulation risks. |
| Computational Fluid Dynamics Talent Acquisition | Compresses dual EPA and EMA homologation timelines for global platform resonator contracts. |
| Localized Stamping Operations in India | Captures PLI scheme incentives for electric two-wheeler and three-wheeler acoustic tiering. |
| CAN Bus Integration Partnerships | Accelerates software-defined acoustic tuning capabilities for adaptive driving mode applications. |
Study Parameters
Multi-period observation of nickel-chromium spot indices, EPA test cycle enforcement patterns, and MIIT dual carbon goal implementation anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel heads, and acoustic engineering specialists. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of exhaust system integrators, and customs records of stainless steel feedstock imports. Bottom-up resonator shipment tallies by vehicle platform triangulated against top-down OEM NVH procurement budget disclosures.
Input-output matrices modeled resonator demand across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions throughout the forecast period. CAGRs derived from segment-specific adoption curves weighted by platform-sharing consortium procurement patterns and electrification timelines. Industry-specific forecast inputs included NHTSA pass-by noise threshold revision probabilities and REACH annex XVII enforcement intensity assumptions for acoustic packing materials.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to powertrain electrification acceleration, stainless steel price volatility, and dual carbon goal enforcement intensity in China. Forecasts reflect documented assumptions regarding EPA and EMA regulatory stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Hubcaps Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
Automotive Polycarbonate Glazing Market
Automotive Components
Electric Vehicle Fluid Lubricants Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Global Cylinder Deactivation System Market
Automotive Components
Automotive Spark Plug Market
Automotive Components
UAE Automotive Composites Market
Automotive Components
Global Automotive Active Body Panel Market
Automotive Components
Asia-Pacific Automotive Plastics Market
Automotive Components
Europe Automotive Heat Exchanger Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Brake System and Components Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Platinum Automotive Catalyst Market