
 Global Automotive Sun Visor Market | 2026-2036
Global Automotive Sun Visor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Sun Visor Market Analysis
Aftermarket service revenue is tilting toward integrated electronic visor refurbishment as vehicle lifespans extend and sensor-embedded units require specialized recalibration. Toyota Boshoku leverages its seat and interior systems integration to bundle smart visor modules with overhead consoles, capturing bundled OEM contracts. Gentex Corporation dominates electrochromic technology leadership, sustaining premium pricing through proprietary dimming chemistry and FAA-certified aviation crossover expertise.
An automotive sun visor is a pivot-mounted shield installed above the windshield, typically comprising a rigid substrate arm, hinged panel of polycarbonate or fabric-wrapped foam core, and optional electrochromic glass or LED-integrated vanity assembly; manufacturers injection-mold frames or thermoform acrylic sheets before attaching clip mechanisms rated for thousands of duty cycles, with the primary purpose of blocking solar glare to reduce driver eye strain and comply with occupant safety visibility standards. Premium visor and dual-function visor categories concentrate margin pools where electrochromic auto-dimming and integrated HomeLink transmitters justify higher OEM pricing, while standard visor demand anchors volume in emerging-market compact vehicle platforms where cost engineering dominates supplier selection. Material segmentation shows polycarbonate gaining share against fabric-wrapped foam where weight reduction targets and recycling compliance tighten specification sheets.
The US NHTSA FMVSS 302 flammability standard and Europe's REACH chemical restriction framework both shape material selection and surface finishing chemistry across supplier portfolios, with ECE R43 additionally governing optical transmission properties for tinted or photochromic variants. China's SAMR enforces GB standards for interior component emissions and fogging resistance, creating separate compliance pathways for visors in domestic versus export vehicle programs. Stakeholders must monitor convergence between automotive and consumer electronics supply chains as transparent conductive oxide coatings and miniaturized sensor packages migrate from display manufacturing into next-generation visor assemblies.
Market Dynamics
Electrochromic dimming integration is restructuring supplier hierarchies as OEMs bundle smart visor modules into overhead console ecosystems, compressing standalone component margins while elevating system-level contract values.
Growth Catalysts
- Vehicle Electrification Mandates:Battery-electric platforms prioritize weight-reduced interior components, channeling specification wins toward polycarbonate substrate designs that trim grams per unit versus legacy foam-core assemblies.
- ECE R43 Optical Standards:Europe's revised safety framework mandates enhanced glare transmission controls, forcing Tier-1 suppliers to recertify tint gradients and accelerating replacement cycles for non-compliant legacy inventories.
- Aviation-Certified Chemistry Transfer:FAA-validated electrochromic formulations originally developed for cockpit applications are migrating into automotive programs, shortening validation timelines for premium OEM adoption.
Market Restraints
- Optical-Grade Polycarbonate Concentration:Substrate supply clusters among three specialized polymer compounders in Germany and Japan, creating vulnerability to force majeure disruptions or allocation rationing during semiconductor-adjacent demand surges.
- REACH Chemical Compliance Burden:ECHA restrictions on phthalate plasticizers and flame retardants force reformulation of surface coatings and foam adhesives, extending qualification cycles by 8-14 months for European-bound production.
- Indium Tin Oxide Cost Volatility:Transparent conductive oxide layers essential for electrochromic circuits face price swings tied to rare earth extraction quotas, compressing gross margins on smart visor SKUs during commodity spikes.
Strategic Opportunities
- India Compact Vehicle Electrification:Domestic OEMs launching sub-4-meter electric hatchbacks lack established visor supply chains, creating first-mover advantage for polycarbonate-integrated module suppliers meeting BIS automotive interior standards.
- Sensor-Vanity Convergence:Miniaturized ambient light sensors and gesture recognition packages from consumer electronics supply chains are enabling touchless dimming controls, differentiating premium visor assemblies in flagship sedan programs.
- Extended Vehicle Lifespan Refurbishment:Sensor-embedded visor units require dealer-level recalibration tools, opening captive aftermarket revenue streams as average vehicle operational life stretches beyond 12 years in developed markets.
Industry Challenges
- Cross-Domain Calibration Expertise Gap:Electrochromic visor deployment demands fluency in optical physics, automotive EMC compliance, and human-machine interface design—a skill intersection scarce among traditional interior trim engineering teams.
- Multi-Standard Certification Parallelism:Simultaneous pursuit of NHTSA FMVSS 302 flammability, ECE R43 optical, and GB 9656 fogging compliance triples testing overhead for global platform suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Sun Visor Market |
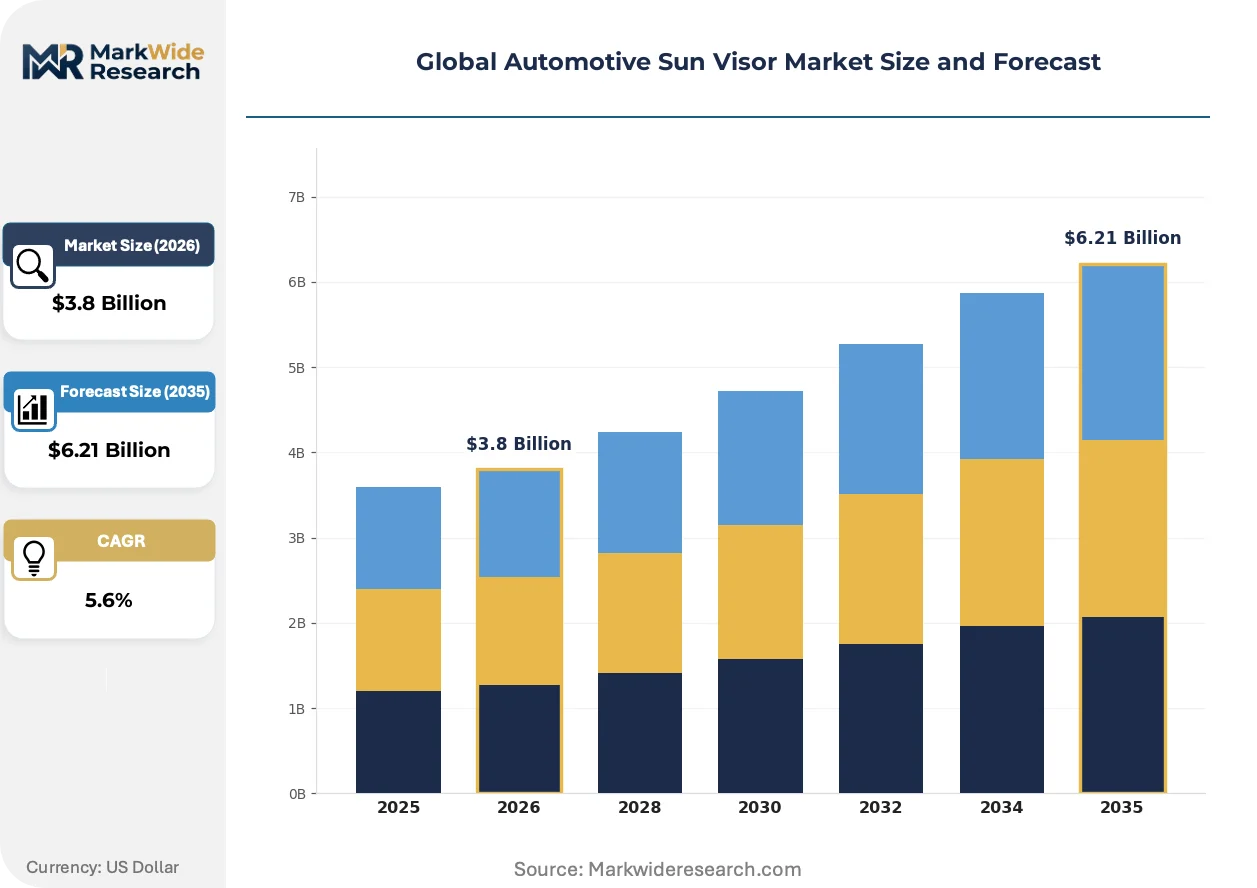
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Visor, Premium Visor, Dual-Function Visor, Retractable Visor Material: Polycarbonate, Acrylic, Fabric, Foam End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Technology: Manual, Automatic, Optical, Hybrid |
| Companies Covered | Toyota Boshoku, IAC Group, Magna International, Gentex Corporation, Lear Corporation, Grupo Antolin, Faurecia, Irvin Automotive Products, Kasai Kogyo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Sun Visor Market Emerging Trajectories
Transparent conductive oxide deposition techniques and solid-state electrochromic chemistry are converging to eliminate mechanical pivot mechanisms, collapsing the boundary between passive shade and active display surface.
Solid-state electrochromic glass eliminates liquid-crystal layers and polarizer films from dimming assemblies, reducing stack thickness by 40 percent. German premium OEMs are specifying these substrates for panoramic roof-integrated visor zones launching in 2026-2027 model years. Mechanical hinge-and-clip hardware is rendering obsolete as frameless electrochromic panels embed directly into windshield header structures.
REACH Annex XVII expansion is restricting per- and polyfluoroalkyl substances in stain-resistant fabric treatments, compelling suppliers to validate silicone-based hydrophobic alternatives. Surface finishing chemistry portfolios face wholesale reformulation, with ECHA SVHC candidate list monitoring now a standing procurement criterion. Tier-2 textile coaters in Portugal and Romania are consolidating to amortize compliance testing costs.
Fleet operators and mobility-as-a-service platforms are unbundling interior component warranties from vehicle powertrain coverage, creating standalone service contracts for sensor-embedded cabin elements. This disintermediates traditional OEM captive parts networks in favor of authorized independent refurbishment chains. North American commercial fleet lessors are piloting visor-unit residual value guarantees tied to electrochromic cell cycle-life certification.
Global Automotive Sun Visor Market Segmentation
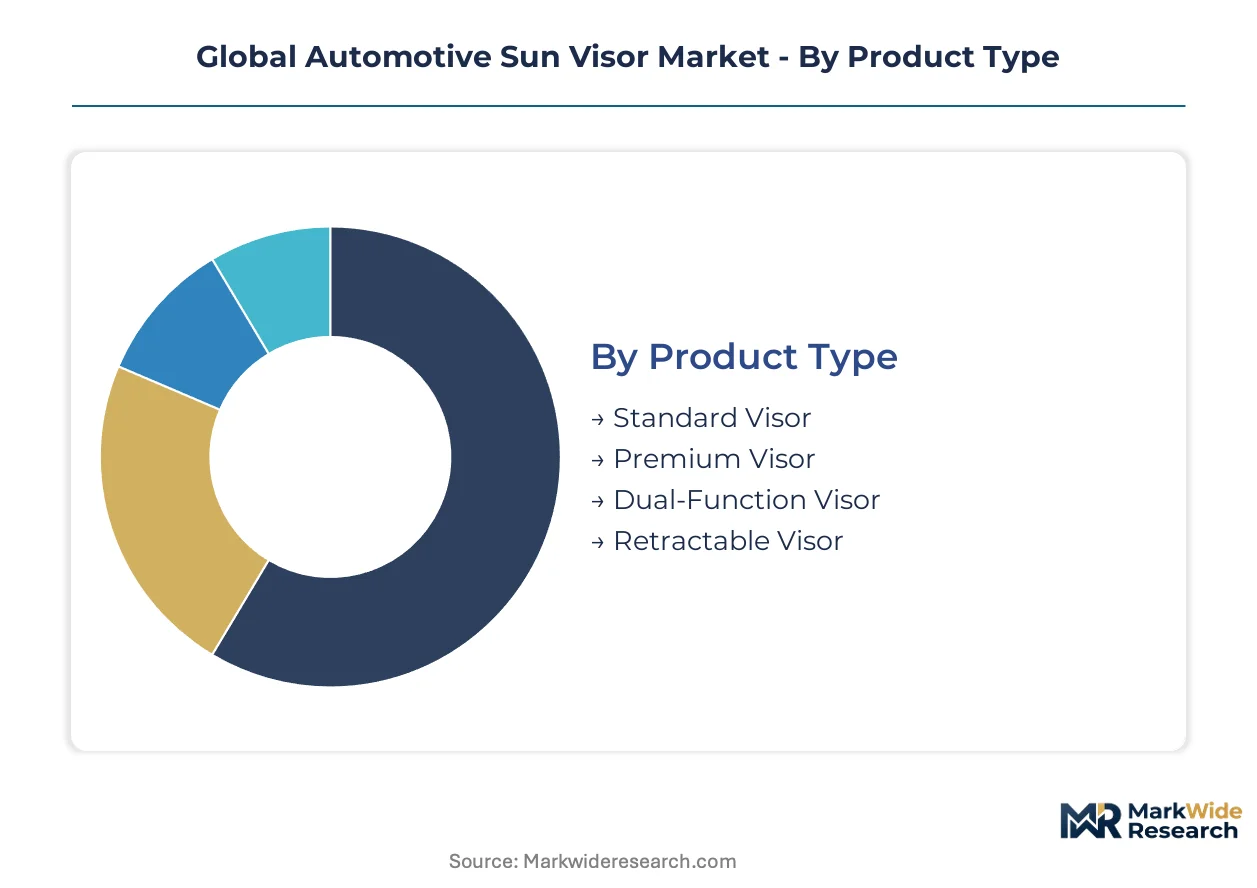
Segmentation reveals how service intensity varies across visor categories. Electrochromic units demand specialized recalibration infrastructure, while standard foam-core designs circulate through independent distributors with minimal technical support.
Product Type:
After-sales-service intensity escalates dramatically from standard mechanical units to sensor-embedded smart visors, reshaping warranty structures and dealer training investments across the value chain.
- Premium Visor:Electrochromic glass substrates with integrated HomeLink transmitters and vanity lighting command the highest installed value. German luxury OEMs specify these assemblies for flagship electric sedan programs where occupant experience differentiation justifies substantial per-unit investment.
- Dual-Function Visor:Pivot mechanisms enabling windshield and side-window deployment combine polycarbonate substrates with dual-axis hinge hardware. Japanese and South Korean OEMs favor this configuration for mid-size crossover platforms where interior packaging efficiency constrains overhead console space.
- Standard Visor:Fabric-wrapped foam core panels with basic clip mechanisms dominate emerging-market compact vehicle production.
- Retractable Visor:Roll-out blind systems integrated into windshield header trim require precision cable-drive actuators and represent the most complex mechanical variant.
Standard visor holds the largest share; momentum sits with premium visor.
Material:
Cost tier stratification separates optical-grade polymer specifications from commodity foam alternatives, with regulatory pressure on recyclability accelerating substrate substitution timelines.
- Polycarbonate:Injection-molded optical-grade substrates deliver weight reduction and impact resistance for electrochromic assemblies. REACH-compliant recycling pathways and ECE R43 transmission certification requirements channel specification wins toward German and Japanese compounders with validated automotive grades.
- Acrylic:Thermoformed sheets offer cost-positioned transparency for standard visor applications where dimming functionality is absent.
- Fabric:Textile-wrapped surfaces face reformulation pressure as ECHA restricts per- and polyfluoroalkyl substances in stain-resistant treatments.
- Foam:Polyurethane core materials anchor economy-tier production but confront emissions compliance burdens under China's GB standards for interior component fogging.
Foam retains volume leadership; polycarbonate climbs the fastest on electrification-driven weight targets.
End User:
Customer type determines contract structure complexity, from multi-year system-level agreements with integrated console suppliers to fragmented spot purchasing through aftermarket distributors.
- OEMs:Direct procurement of complete overhead console modules bundles visor assemblies with lighting, sensors, and trim. Toyota and Volkswagen Group programs specify electrochromic units through single-source contracts with interior system integrators.
- Tier-1 Suppliers:Magna and Faurecia source discrete visor subassemblies for integration into broader cockpit modules, maintaining qualification leverage over substrate and hinge mechanism specifications.
- Aftermarket Providers:Independent distributors service replacement demand for mechanical wear items and collision damage.
- Dealerships:Authorized service networks capture sensor-embedded unit recalibration through proprietary diagnostic tools.
OEMs command the largest share; aftermarket providers are expanding most quickly on extended vehicle lifespan trends.
Technology:
Maturity gradients separate established mechanical designs from emerging solid-state electrochromic platforms, with hybrid architectures bridging transition timelines for cost-sensitive vehicle programs.
- Automatic:Solid-state electrochromic chemistry eliminates liquid-crystal layers, reducing stack thickness for panoramic roof-integrated applications. FAA-validated formulations originally developed for cockpit displays accelerate automotive adoption timelines.
- Hybrid:Mechanical pivot frames with electrochromic insert panels balance cost and functionality for mid-tier vehicle platforms.
- Manual:Passive shade panels with friction hinges retain dominance in emerging-market production.
- Optical:Photochromic substrates responding to UV exposure without electrical control represent a niche alternative.
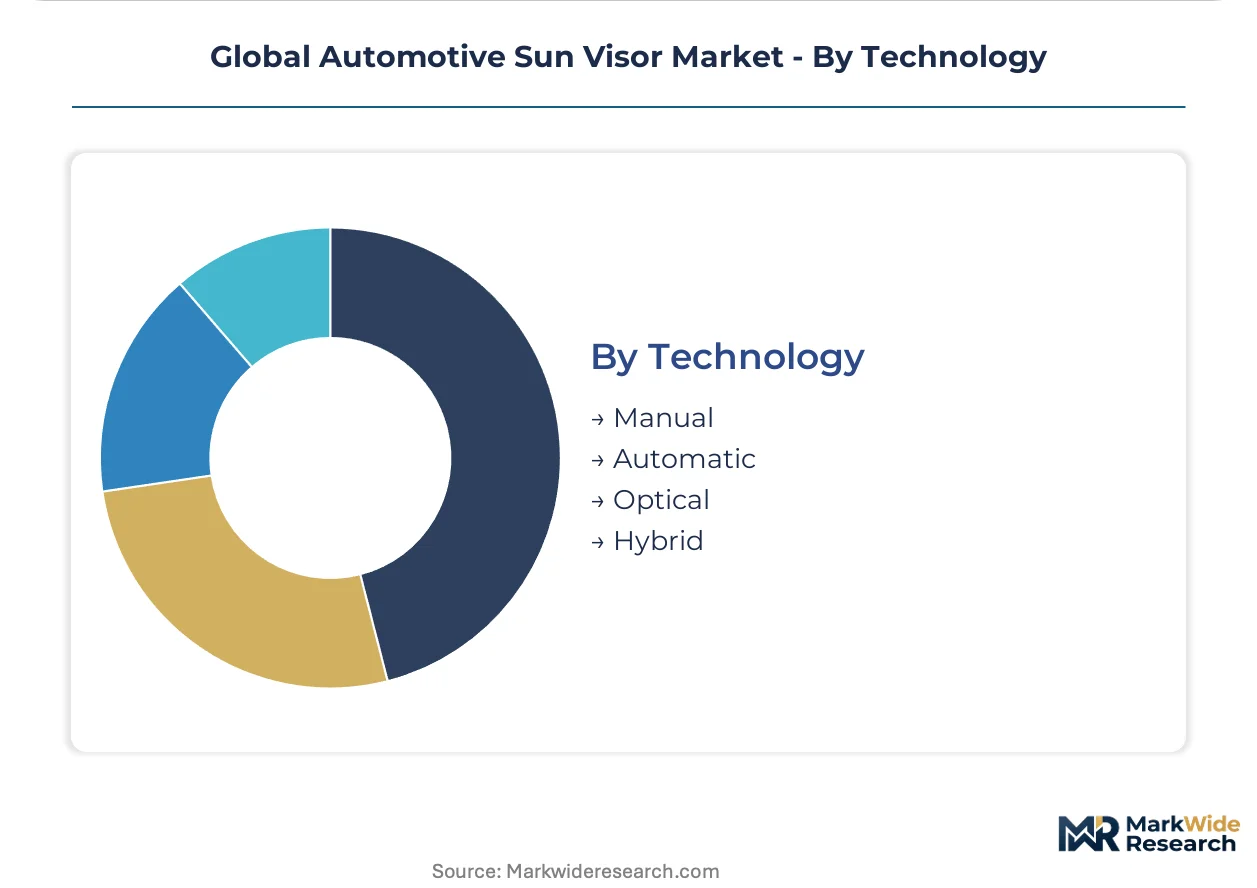
Manual technology holds the largest share; automatic systems show the steepest expansion trajectory on premium platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical-grade polycarbonate supply clusters among three specialized compounders in Germany and Japan, creating geographic concentration that shapes procurement patterns for electrochromic visor programs. OEM specification teams in Stuttgart, Wolfsburg, and Munich source directly from these substrate specialists, while assembly integration occurs across dispersed manufacturing footprints.
Germany
Premium OEM electrification programs in Bavaria and Baden-Württemberg drive demand for electrochromic overhead console modules. KBA vehicle type approval requirements for interior component emissions align with ECE R43 optical transmission standards, accelerating substrate qualification cycles. Stuttgart-based interior system integrators bundle smart visor assemblies with ambient lighting and sensor packages for flagship electric sedan platforms launching through 2027.
United States
NHTSA FMVSS 302 flammability compliance shapes material selection for domestic OEM programs concentrated in Michigan and Ohio. FAA-certified electrochromic chemistry from aviation applications transfers into automotive supply chains through Detroit-area engineering centers. Michigan-based Tier-1 suppliers source polycarbonate substrates from German compounders while maintaining captive hinge mechanism fabrication in-house.
China
GB 9656 automotive glass regulations and SAMR interior component emissions standards create dual compliance pathways for domestic versus export vehicle programs. Yangtze River Delta OEMs in Shanghai and Jiangsu province specify polycarbonate-integrated visor modules for electric vehicle platforms targeting European export markets. Domestic compounders in Zhejiang province are qualifying optical-grade polycarbonate grades to reduce import dependency.
Japan
METI carbon neutrality roadmaps channel investment toward lightweight interior components for battery-electric platforms. Toyota Boshoku in Aichi Prefecture leverages seat and interior systems integration to capture bundled overhead console contracts. JIS standards for automotive interior parts provide baseline specifications that Tier-1 suppliers exceed for export programs to North America and Europe.
India
BIS automotive interior standards and the PLI scheme for advanced automotive components create regulatory scaffolding for domestic visor supply chain development. Sub-4-meter electric hatchback programs from Maharashtra and Tamil Nadu-based OEMs lack established polycarbonate module suppliers, creating specification windows for first-mover entrants. Gujarat-based polymer compounders are qualifying optical-grade grades to serve this emerging demand.
Global Automotive Sun Visor Market Vendor Landscape
Interior system integrators and specialized electrochromic technology developers split the market into distinct capability tiers. Consolidation pressure intensifies as OEMs bundle visor functions into overhead console ecosystems, compressing standalone component margins while elevating system-level contract values. Three archetypes dominate: full-service interior module suppliers, electrochromic substrate specialists, and regional fabrication houses serving cost-sensitive vehicle programs. Competitive moves center on backward integration into polycarbonate substrate supply and strategic partnerships with transparent conductive oxide coating providers.
Among full-service interior module suppliers, Toyota Boshoku and Magna International exemplify the integrated-systems archetype, bundling visor assemblies with broader overhead console portfolios. Gentex Corporation occupies a specialized position in electrochromic technology, leveraging aviation-certified chemistry expertise that transfers into automotive applications. These three companies anchor the competitive structure, with Toyota Boshoku representing Japanese vertical integration models, Magna International exemplifying North American Tier-1 scale, and Gentex Corporation illustrating technology-specialist positioning in premium-tier supply chains.
| Leading Market Players |
|---|
| Toyota Boshoku |
| IAC Group |
| Magna International |
| Gentex Corporation |
| Lear Corporation |
| Grupo Antolin |
| Faurecia |
| Irvin Automotive Products |
| Kasai Kogyo |
| Others |
Supply Flow & Price Mechanics
Undercapacity in optical-grade polycarbonate substrate production across Germany and Japan is driving allocation rationing behavior among specialized compounders, compressing margins for electrochromic visor assemblers while elevating pricing power upstream. This utilization dynamic forces Tier-1 suppliers into long-term offtake commitments or captive capacity investments to secure specification-grade material flows.
Pricing Analysis
ECE R43 optical transmission standards dictate the pricing tier structure across the automotive sun visor market. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified electrochromic assemblies from polycarbonate mechanical units and foam-core commodity panels. Price differentiation rests on certification grade and volume scale, with OEM bundled contracts commanding substantial premiums over spot aftermarket purchases. Cost compression in standard foam-core segments is intensifying because Indian and Chinese domestic OEMs prioritize per-unit cost engineering over performance specifications. Fleet operators and mobility-as-a-service platforms exhibit the highest price sensitivity due to unbundled warranty structures, while German premium OEMs demonstrate minimal elasticity for flagship electric vehicle programs.
Supply Chain Analysis
Upstream bisphenol-A and phosgene feedstock availability constrains optical-grade polycarbonate output across Germany, Japan, and emerging Chinese compounders in Zhejiang province. The electrochromic visor supply chain draws from indium tin oxide deposition specialists in South Korea, transparent conductive oxide coating providers, and precision hinge mechanism fabricators in Michigan and Aichi Prefecture. Single-source vulnerability concentrates in FAA-validated electrochromic chemistry formulations held by aviation-certified suppliers. Distribution runs through Tier-1 interior system integrators bundling visor modules into overhead console ecosystems, with aftermarket channels fragmenting across independent distributors and authorized dealership recalibration networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense imperative as solid-state electrochromic glass eliminates mechanical pivot hardware, threatening legacy hinge-and-clip suppliers with obsolescence. Frameless panel integration into windshield header structures accelerates this technology displacement timeline.
For Market Incumbents: Pre-empt obsolescence by securing backward integration into optical-grade polycarbonate substrate supply through partnership or captive production in Germany or Japan. Invest in cross-domain calibration expertise bridging optical physics, automotive EMC compliance, and human-machine interface design to defend electrochromic system-level contract values against modular commoditization.
For New Entrants and Emerging Players: Build out polycarbonate-integrated module capabilities targeting India's sub-4-meter electric hatchback segment, where established supply chains remain underdeveloped and BIS automotive interior standards create qualification barriers for incumbent foreign suppliers. Pursue direct OEM relationships with Maharashtra and Tamil Nadu-based domestic manufacturers rather than Tier-1 integration routes.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electrochromic technology specialists with FAA-certified aviation crossover expertise and proprietary dimming chemistry IP. Long-term viability favors acquisition targets combining transparent conductive oxide coating capabilities with automotive qualification pathways, particularly those positioned for sensor-vanity convergence in gesture recognition and ambient light integration. Monitor indium tin oxide price volatility and rare earth extraction quota announcements as inflection indicators for smart visor SKU margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polycarbonate Substrate Supply | Secures specification-grade material allocation from German and Japanese compounders amid undercapacity conditions. |
| Cross-Domain Calibration Expertise Development | Bridges optical physics, automotive EMC compliance, and human-machine interface design for electrochromic deployment. |
| Aviation-Certified Chemistry Transfer Investment | Accelerates automotive validation timelines through FAA-validated electrochromic formulation adaptation. |
| Sensor-Vanity Convergence R&D Partnership | Integrates miniaturized ambient light sensors and gesture recognition from consumer electronics supply chains. |
| Extended Lifespan Refurbishment Infrastructure | Captures captive aftermarket revenue through dealer-level recalibration tools for sensor-embedded units. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and dealership service operations managers. Secondary validation incorporated vehicle production databases, IHS Markit registration data, SEC filings from listed interior system integrators, and customs records tracking polycarbonate substrate trade flows. Bottom-up segment sizing across product type, material, end user, and technology dimensions was triangulated against top-down market value estimates derived from OEM program announcements and supplier contract disclosures.
Calibration against historical production volumes and announced platform launches shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompass vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from elasticity-adjusted adoption curves for electrochromic technology penetration and weight-driven polycarbonate substitution rates in battery-electric platforms. Industry-specific forecast inputs included ECE R43 recertification timelines and REACH Annex XVII reformulation cycle impacts on surface finishing chemistry portfolios.
The forecast holds incumbent behavior within observed patterns; aggressive moves by transparent conductive oxide coating specialists or solid-state electrochromic glass developers would shift outcomes beyond modeled ranges. Cross-checking against vehicle electrification mandate acceleration or relaxation in Germany, China, and India is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Interconnecting Shaft Market
Automotive Components
India Passenger Vehicles Lubricants Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market
Automotive Components
Automotive Headliners Market
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
Italy Automotive Actuators Market
Automotive Components
Europe Automotive Bearing Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Global Automotive Plastic Bumper Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Automotive Push Rods Market
Automotive Components
India Automotive Pneumatic Actuators Market
Automotive Components
Global Automotive Water Separation Systems Market