
 Advanced Gear Shifter System Market | 2026-2036
Advanced Gear Shifter System Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Gear Shifter System Market Analysis
ISO 26262 functional-safety certification is reorganizing competitive access in the Advanced Gear Shifter System landscape, forcing tier-one suppliers to demonstrate ASIL-D compliance before securing OEM contracts. ZF Friedrichshafen AG leverages its integrated electronics division to sustain end-to-end validation capabilities. Denso Corporation anchors its position through dominant share in Asian OEM supply chains. Robert Bosch GmbH competes on the strength of its mechatronics R&D intensity across European and North American programs.
An advanced gear shifter system is an electromechanical or fully electronic transmission interface that translates driver input into precise gear-selection commands through Hall-effect sensors, CAN bus signaling, and servo-actuated detent mechanisms, primarily serving to optimize powertrain efficiency and driver ergonomics in modern vehicles. Electronic shifters command the fastest expansion as automakers delete mechanical linkages to save weight and packaging space, while hydraulic systems retain margin concentration in heavy-duty commercial applications where load ratings exceed 450 Nm. OEMs represent the dominant demand channel due to platform-standardization requirements, though aftermarket providers are gaining traction in retrofit programs for classic vehicle electrification.
NHTSA in the United States enforces shift-position indicator visibility standards that directly shape human-machine interface design, while the EU Green Deal and REACH chemical directives in Europe constrain material selection for shifter housings and coatings. China's MIIT mandates domestic content ratios that influence localization decisions for electronic control units. Stakeholders must monitor divergence between ASIL-D safety requirements and cost-down pressures as electrified architectures proliferate across vehicle segments.
Market Dynamics
ISO 26262 ASIL-D certification requirements are restructuring supplier qualification criteria across the Advanced Gear Shifter System market, forcing component vendors to absorb validation costs that previously fell to tier-one integrators.
Growth Catalysts
- EPA fuel-efficiency standards:United States mandates for powertrain optimization compel automakers to adopt electronic shifters that reduce mechanical weight and parasitic losses.
- Hall-effect sensing arrays:These solid-state position detectors eliminate contact wear in shift-by-wire architectures, extending service intervals and reducing warranty exposure for OEMs.
- German precision manufacturing clusters:Concentrated supplier ecosystems around Stuttgart and Friedrichshafen deliver sub-micron tolerance machining for detent mechanisms at production scale.
Market Restraints
- Rare-earth magnet price volatility:Neodymium and dysprosium supply constraints from Chinese export quotas inflate permanent magnet costs for servo-actuated shifter motors.
- Single-source silicon foundry dependence:Microcontroller supply for electronic control units concentrates at TSMC and Samsung facilities in Taiwan and South Korea.
- Mechanical linkage legacy infrastructure:Existing stamping and forging capacity for cable-operated systems creates sunk-cost resistance to platform conversion.
Strategic Opportunities
- India PLI scheme for automotive electronics:Production-linked incentives for advanced driver assistance systems extend to gear position sensing modules, attracting localized assembly investment.
- Classic vehicle electrification retrofit:Aftermarket providers capture demand from restoration shops converting vintage transmissions to electronic control for EV powertrain swaps.
- EU Green Deal material compliance:REACH-compliant polymer formulations for shifter housings open premium positioning against non-compliant Asian imports.
Industry Challenges
- Functional safety engineering talent scarcity:ASIL-D validation requires specialized embedded software engineers with ISO 26262 implementation experience, creating recruitment bottlenecks.
- Legacy CAN bus integration complexity:Electronic shifters must maintain backward compatibility with decade-old vehicle network architectures without compromising real-time response.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Gear Shifter System Market |
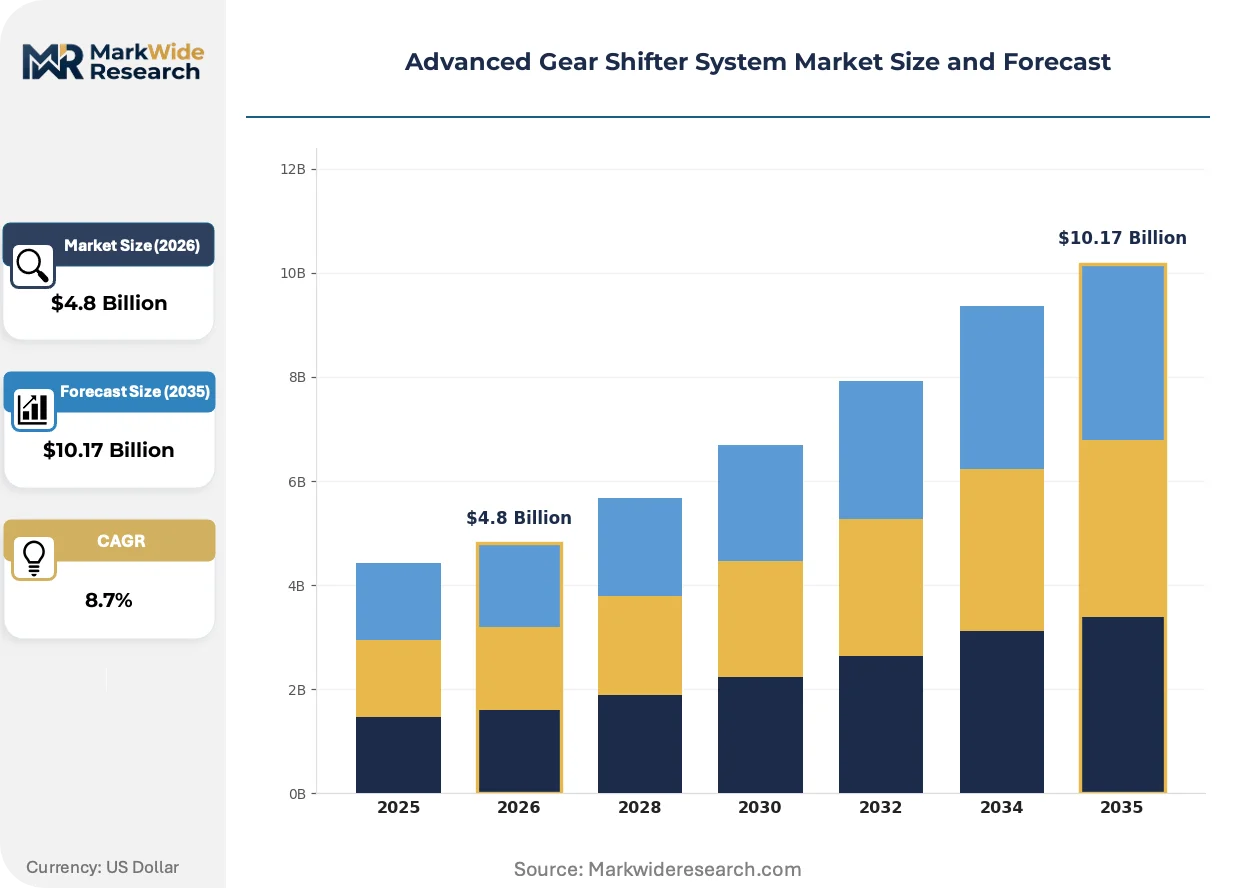
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Shifters, Automatic Shifters, Semi-Automatic Shifters, Electronic Shifters Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Motorcycles Technology: Hydraulic Systems, Mechanical Systems, Electronic Control Units, Cable Systems End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers |
| Companies Covered | Kongsberg Automotive, GHSP, ZF Friedrichshafen AG, Leopold Kostal GmbH & Co. KG, Delta Kogyo Co. Ltd., Robert Bosch GmbH, Fujikiko Co. Ltd., Eissmann Group Automotive, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Gear Shifter System Market Emerging Trajectories
Electromechanical architectures are fragmenting into modular subsystems that separate human interface design from transmission control logic, enabling faster platform updates and supplier specialization.
Haptic feedback actuators are decomposing the traditional mechanical detent into software-defined tactile profiles. Luxury OEMs in Germany and Japan deploy programmable resistance curves that simulate mechanical engagement without physical interlocks. This technology is decomposing the historical link between shift quality and hardware precision, allowing identical base hardware to serve multiple brand positionings through firmware differentiation.
NHTSA shift-position indicator visibility standards are tightening human-machine interface requirements for electronic shifters. The regulation mandates redundant visual and auditory confirmation of gear selection, adding sensor and display cost to every unit. Heavy-duty commercial applications face the steepest compliance burden due to cab vibration environments that challenge display legibility.
Fleet procurement departments are consolidating vendor relationships for transmission controls across multiple vehicle programs. Large rental and logistics operators in the United States now specify single-source electronic shifter suppliers to simplify parts inventory and technician training. This concentration is most visible in Class 3-6 commercial vehicles where standardized shift interfaces reduce driver error incidents during vehicle rotation.
Advanced Gear Shifter System Market Segmentation
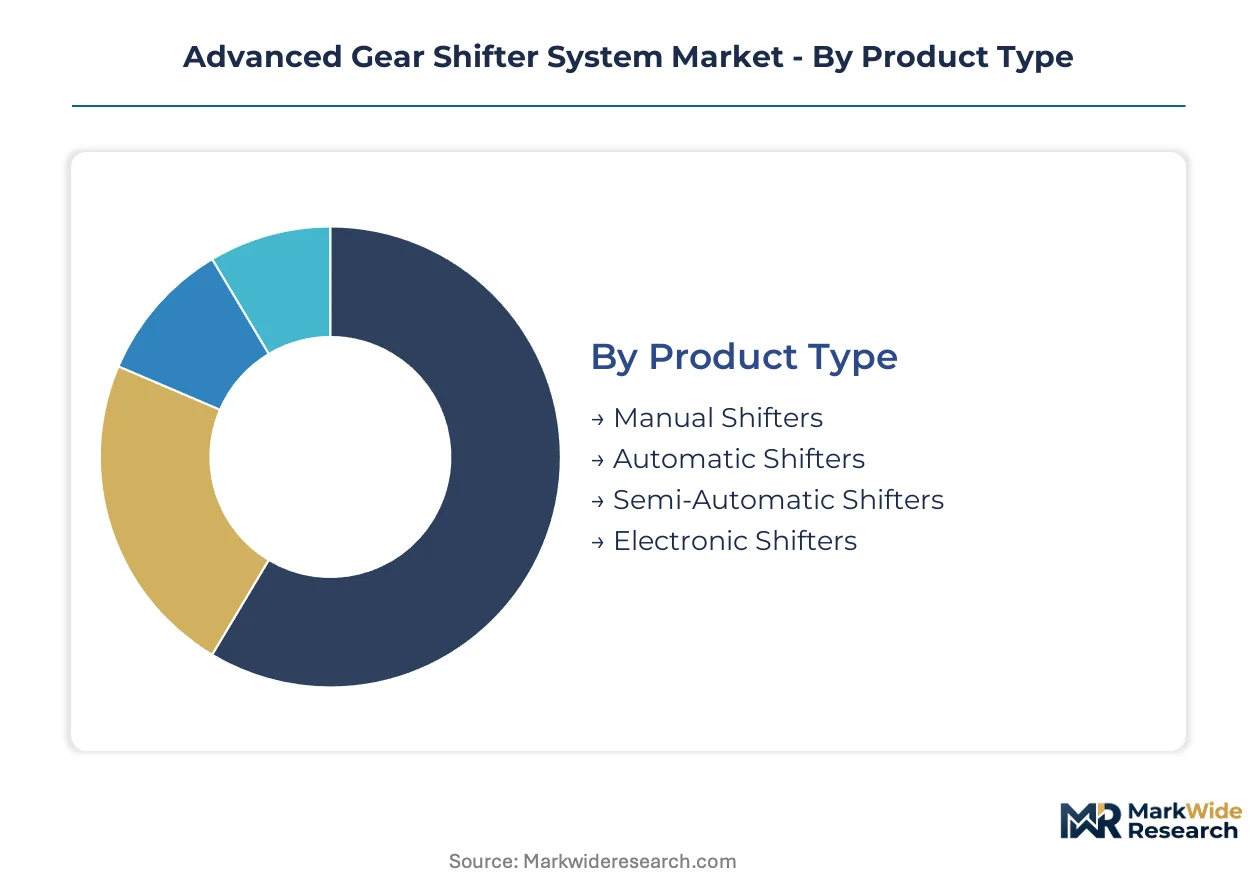
Segmentation in the Advanced Gear Shifter System market reveals how powertrain electrification, regulatory mandates, and supply chain localization are fragmenting demand across incompatible technical specifications. Understanding these divides exposes where procurement leverage concentrates and where validation costs create entry barriers.
Product Type:
Domestic production clusters in Germany and Japan anchor supply for precision-manufactured electronic variants, while mechanical shifter exports from China and India serve cost-sensitive regional markets.
- Manual Shifters:Cable-actuated mechanical assemblies with hardened steel detent mechanisms. Demand clusters in India and Southeast Asia where entry-level passenger vehicles retain stick-shift configurations for cost control.
- Automatic Shifters:Hydraulic valve bodies with torque converter interfaces. Fleet procurement in the United States specifies these for Class 3-6 commercial vehicles where driver training standardization reduces liability exposure.
- Semi-Automatic Shifters:Automated manual transmissions with electro-pneumatic actuation.
- Electronic Shifters:Shift-by-wire architectures using Hall-effect position sensing and CAN bus signaling.
Manual shifters command the established base. The steepest expansion runs through electronic shifters.
Application:
Volume concentration differs sharply by electrification maturity — electric vehicle platforms in China and California drive specialized electronic shifter demand distinct from legacy internal combustion segments.
- Passenger Vehicles:Center console and steering-column-mounted interfaces for sedans, SUVs, and crossovers. European OEMs in Germany specify haptic feedback actuators for premium segment differentiation.
- Commercial Vehicles:Heavy-duty cab-mounted controls for Class 4-8 trucks and buses. NHTSA visibility standards impose redundant indicator requirements that inflate unit costs for US fleet operators.
- Electric Vehicles:Simplified single-speed or multi-speed electronic selectors without mechanical interlocks.
- Motorcycles:Handlebar-mounted twist-grip or thumb-operated selectors for electric two-wheelers.
Passenger vehicles absorb the dominant procurement volume. Electric vehicles are climbing the fastest as platform architectures proliferate.
Technology:
Margin structures stratify by validation burden — electronic control units carry ASIL-D certification costs that mechanical alternatives avoid entirely.
- Hydraulic Systems:Pressurized fluid actuation for torque converter gear selection. Commercial vehicle applications in North America retain this technology for load ratings exceeding 450 Nm.
- Mechanical Systems:Direct cable or linkage transmission of driver input. Aftermarket retrofit demand in Europe converts classic vehicle mechanical shifters to electronic control for EV powertrain swaps.
- Electronic Control Units:Microcontroller-based signal processing with redundant sensor arrays.
- Cable Systems:Bowden cable mechanical linkages with polymer sheath housing.
Mechanical systems retain the installed base. Electronic control units are gaining share fastest as OEMs delete parasitic weight.
End User:
Procurement authority concentrates at OEM platform-engineering teams, though fleet operators are consolidating supplier relationships to simplify inventory and technician certification.
- OEMs:Original equipment manufacturers specifying platform-standardized shifter architectures. German and Japanese OEMs enforce ASIL-D compliance as a non-negotiable qualification threshold.
- Aftermarket Providers:Independent distributors serving restoration shops and vehicle modifiers. Classic vehicle electrification in California and Florida drives demand for electronic shifter retrofit kits.
- Fleet Operators:Rental and logistics companies specifying uniform shift interfaces across vehicle rotations.
- Individual Consumers:Direct retail purchase for DIY installation or repair replacement.
OEMs anchor procurement volume. Fleet operators are expanding their specification authority fastest through consolidated vendor programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA fuel-efficiency mandates in the United States and NHTSA safety standards are accelerating electronic shifter procurement across OEM platforms. Germany's precision manufacturing clusters anchor European supply. China's MIIT domestic content requirements and India's PLI scheme for automotive electronics are reshaping Asian sourcing patterns.
United States
NHTSA shift-position indicator visibility standards and EPA fuel-efficiency mandates drive electronic shifter adoption in passenger and commercial vehicle fleets. The Detroit Three automakers specify redundant visual and auditory confirmation systems for gear selection. Michigan and Ohio host stamping and forging capacity for legacy mechanical systems alongside emerging electronics assembly.
Germany
EU Green Deal REACH compliance requirements and ASIL-D certification thresholds concentrate premium electronic shifter development. Stuttgart and Friedrichshafen precision manufacturing clusters deliver sub-micron tolerance machining for detent mechanisms at production scale. ZF Friedrichshafen AG and Kostal anchor integrated electronics divisions serving German OEM platform engineering teams.
China
MIIT domestic content ratio mandates for electronic control units influence localization decisions across EV platforms. Yangtze River Delta and Pearl River Delta manufacturing hubs scale Hall-effect sensor module production for domestic OEMs. Dual carbon goals accelerate deletion of mechanical linkages to reduce parasitic weight in electrified architectures.
Japan
METI industrial policy supports shift-by-wire R&D for hybrid and electric vehicle exports. Kanto and Kansai automotive electronics corridors supply haptic feedback actuator technology to premium OEM programs. Denso Corporation leverages dominant share in Asian OEM supply chains for microcontroller-based signal processing systems.
India
PLI scheme production-linked incentives for automotive electronics extend to gear position sensing modules, attracting localized assembly investment. Maharashtra and Tamil Nadu automotive corridors develop cable-actuated mechanical assembly for entry-level passenger vehicles retaining stick-shift configurations. Domestic OEMs balance cost control against gradual electronic shifter migration.
Advanced Gear Shifter System Market Vendor Landscape
Player mix skews toward diversified automotive electronics conglomerates with integrated mechatronics divisions. Tier-one suppliers absorb ASIL-D validation costs that previously fell to component vendors, consolidating qualification authority. Three archetypes dominate: precision-machining specialists with captive electronics capabilities, diversified conglomerates with end-to-end validation infrastructure, and regional electronics assemblers serving cost-sensitive platforms. Competitive moves center on strategic partnerships for microcontroller supply security and portfolio diversification into haptic feedback systems.
Within the diversified conglomerate tier, ZF Friedrichshafen AG and Denso Corporation exemplify integrated electronics strategies. Robert Bosch GmbH occupies a position spanning European and North American program engineering. Among precision-focused specialists, Leopold Kostal GmbH & Co. KG anchors German supply clusters. Kongsberg Automotive and GHSP represent transnational fabricators with multi-regional OEM relationships. Delta Kogyo Co. Ltd. and Fujikiko Co. Ltd. sit within the Asia-Pacific electronics assembly archetype. Eissmann Group Automotive exemplifies interior systems integration capabilities.
| Leading Market Players |
|---|
| Kongsberg Automotive |
| GHSP |
| ZF Friedrichshafen AG |
| Leopold Kostal GmbH & Co. KG |
| Delta Kogyo Co. Ltd. |
| Robert Bosch GmbH |
| Fujikiko Co. Ltd. |
| Eissmann Group Automotive |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between OEM platform-engineering teams and tier-one integrators lock in ASIL-D certified electronic shifter supply while capping unit cost escalation across multi-year vehicle programs. These contracts bundle Hall-effect sensor modules and microcontroller supply under single-source arrangements that trade price predictability for volume commitments in Germany, Japan, and United States assembly corridors.
Pricing Analysis
Certification level creates the primary spread between premium ASIL-D validated electronic shifters and standard mechanical alternatives. Per-unit transactional pricing dominates, with ISO 26262 compliance tier and volume scale driving differentiation. Cost compression in entry-level cable-actuated systems is intensifying because Chinese and Indian suppliers compete on legacy stamping capacity. Fleet procurement departments show least price sensitivity due to total-cost-of-ownership calculations, while aftermarket retrofit providers face acute margin pressure from rare-earth magnet cost volatility.
Supply Chain Analysis
Just-in-time inventory strategies dominate electronic shifter assembly, though strategic stockpiling of neodymium and dysprosium permanent magnets persists among German precision manufacturers. Supply concentrates in Germany, China, and Japan for Hall-effect sensor fabrication and detent mechanism machining. The chain rests on Taiwanese and South Korean foundry output for automotive-grade microcontrollers. Single-source silicon vulnerability represents the dominant structural risk. Distribution runs through OEM platform-engineering gatekeepers who qualify tier-one integrators for multi-vehicle program awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The advanced gear shifter market sits at a platform-economics inflection where shift-by-wire architectures are displacing mechanical linkages as the default transmission interface, with CAN bus interoperability standards determining which suppliers capture multi-OEM program wins.
For Market Incumbents: Shield program retention by deepening captive electronics capabilities against emerging Asian semiconductor assemblers. Prioritize ASIL-D validation infrastructure investments that new entrants cannot replicate within OEM qualification windows. Consolidate microcontroller supply relationships through direct foundry partnerships to reduce TSMC and Samsung concentration exposure. For New Entrants and Emerging Players: ASIL-D certification fast-track through partnership with established tier-one integrators offers the most viable entry path. Target aftermarket retrofit demand in California and Florida classic vehicle electrification, where mechanical-to-electronic conversion kits bypass OEM qualification barriers. Pursue fleet operator direct relationships in United States Class 3-6 commercial vehicles, where standardized shift interfaces reduce incumbent brand stickiness. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified mechatronics conglomerates with end-to-end validation infrastructure. Five-to-ten year viability hinges on shift-by-wire penetration rates in entry-level passenger vehicles. Watch microcontroller supply security negotiations as the inflection signal—foundry capacity reservation announcements by tier-one suppliers indicate pricing power capture ahead of capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Unlocks OEM platform-engineering qualification for electronic shifter programs in Germany and Japan. |
| Microcontroller Supply Agreement | Reduces single-source foundry dependence that concentrates at TSMC and Samsung facilities. |
| Haptic Feedback Module Development | Enables firmware-defined brand differentiation for premium German and Japanese OEM segments. |
| Classic Vehicle Retrofit Kit Launch | Captures aftermarket demand from California and Florida restoration shops executing EV powertrain swaps. |
| India PLI Localization | Positions for production-linked incentives covering gear position sensing module assembly investment. |
Methodological Framework
A spread of perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and fleet operations managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against NHTSA regulatory filings, EPA fuel-efficiency rulemakings, MIIT domestic content directives, and vehicle production databases. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segmentation dimensions modeled include product type, application, technology, and end user, with propulsion architecture and regional production cluster as automotive-specific layers. CAGRs were derived from trend extrapolation and adoption curve analysis. Forecast inputs incorporated ASIL-D certification penetration rates and rare-earth magnet price trajectory assumptions throughout the projection horizon.
Decision-makers should treat outputs as directional under stable regulatory enforcement and foundry capacity expansion assumptions; material deviation would warrant model refresh. Specific risk factors include NHTSA rulemaking acceleration, Chinese export quota tightening on neodymium, and OEM platform consolidation decisions. Revision becomes warranted when microcontroller lead time volatility crosses thresholds that disrupt tier-one supplier qualification schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Drivetrain Market
Powertrain
Engine Actuators Market
Powertrain
Automotive Engine Market
Powertrain
Powertrain Testing Market
Powertrain
South America Automotive Market
Powertrain
Power Transmission Gearbox Market
Powertrain
Automatic Transmission Torque Converter Market
Powertrain
Automotive Power Modules Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Automotive Driveline Market
Powertrain
Automotive Fuel Injection Pump Market
Powertrain
Power Liftgate for Automotive Market
Powertrain
Natural Gas Engines Market
Powertrain
Transmission Repair Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Automatic Transmission Market