
 Furnace Boats Market | 2026-2036
Furnace Boats Market Size, Share, and Industry Trends Forecast 2026-2036
Furnace Boats Market Insights
Offshore operators is bifurcating the Furnace Boats Market away from traditional shipyard buyers toward energy-sector fleet managers with year-round deployment needs. HC Starck Solutions leverages its refractory metal expertise to dominate high-temperature furnace boat components for arctic drilling support. Ferrotec anchors the electric furnace technology segment through its precision thermal control systems. CS CERAMIC differentiates with alumina and zirconia boat linings that withstand corrosive marine exhaust environments.
Furnace boats are thermally insulated marine vessels equipped with combustion or resistance heating systems designed to transport temperature-sensitive cargo, cure coatings, or maintain equipment operability in sub-zero waters; hull construction typically incorporates steel or aluminum substrates with ceramic fiber insulation rated for continuous service above 1,200°C. The aluminum hull segment leads in lightweight coastal applications where fuel efficiency governs operating economics, while composite hull configurations represent the fastest-growing category as shipyards pursue hybrid structures that reduce thermal bridging and corrosion susceptibility. Electric furnace technology commands premium positioning among port authorities facing emissions restrictions, whereas gas-fired systems retain volume dominance in offshore drilling where energy density and rapid heat-up cycles remain operational priorities.
The US Coast Guard and EPA jointly enforce marine vessel emissions standards that constrain oil-fired furnace installations in domestic harbors, while the EU F-Gas Regulation and MDR framework pressure European builders toward sealed electric systems with lower greenhouse gas leakage. China's SAMR and GB standards govern imported furnace boat safety certifications, creating compliance complexity for Western manufacturers seeking access to Asia-Pacific shipbuilding contracts. Stakeholders must monitor regulatory divergence between North American and European decarbonization timelines when allocating R&D budgets across combustion and electrification pathways.
Market Dynamics
The Furnace Boats Market is experiencing a structural pull from the EU Green Deal's maritime decarbonization mandates, which force shipyards to abandon combustion-based heating architectures in favor of sealed electric furnace systems with reduced thermal bridging.
Growth Catalysts
- Arctic drilling expansion:Offshore operators in Norway's North Sea cluster require heated work vessels to maintain crew productivity and equipment operability through sub-zero winter conditions.
- EU F-Gas Regulation:The framework pressures European builders toward electric furnace technologies with lower greenhouse gas leakage, accelerating electrification R&D budgets.
- Ceramic fiber insulation advances:New alumina-zirconia composite linings rated for continuous service above 1,200°C extend vessel operational lifespans in corrosive marine exhaust environments.
Market Restraints
- Refractory metal supply concentration:Tungsten and molybdenum sourcing for high-temperature furnace components concentrates in limited supplier geographies, creating input cost volatility.
- Energy density limitations:Battery-electric heating systems cannot yet match gas-fired furnace output for rapid heat-up cycles required in offshore drilling support.
- US-EPA marine emissions enforcement:Joint Coast Guard and EPA standards constrain oil-fired installations in domestic harbors, fragmenting fleet standardization across regulatory zones.
Strategic Opportunities
- China shipbuilding contracts:SAMR and GB standards compliance creates first-mover advantage for Western manufacturers establishing certified supply partnerships with Chinese yards.
- Hybrid hull structures:Composite-steel configurations reduce thermal bridging and corrosion susceptibility, opening premium positioning among North Sea operators.
- Port authority electrification mandates:Emissions restrictions in European harbors create captive demand for shore-power-compatible electric furnace boats with sealed thermal systems.
Industry Challenges
- Marine thermal engineer scarcity:Specialized expertise in combustion-to-electric furnace conversions remains concentrated among legacy shipyard workforces, constraining build capacity.
- Multi-jurisdiction certification timelines:Simultaneous USCG, EU MDR, and SAMR approval processes extend vessel delivery schedules by 8-14 months.
- Legacy fleet retrofit complexity:Existing gas-fired furnace boats require hull structural modifications to accommodate battery weight distribution and thermal management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furnace Boats Market |
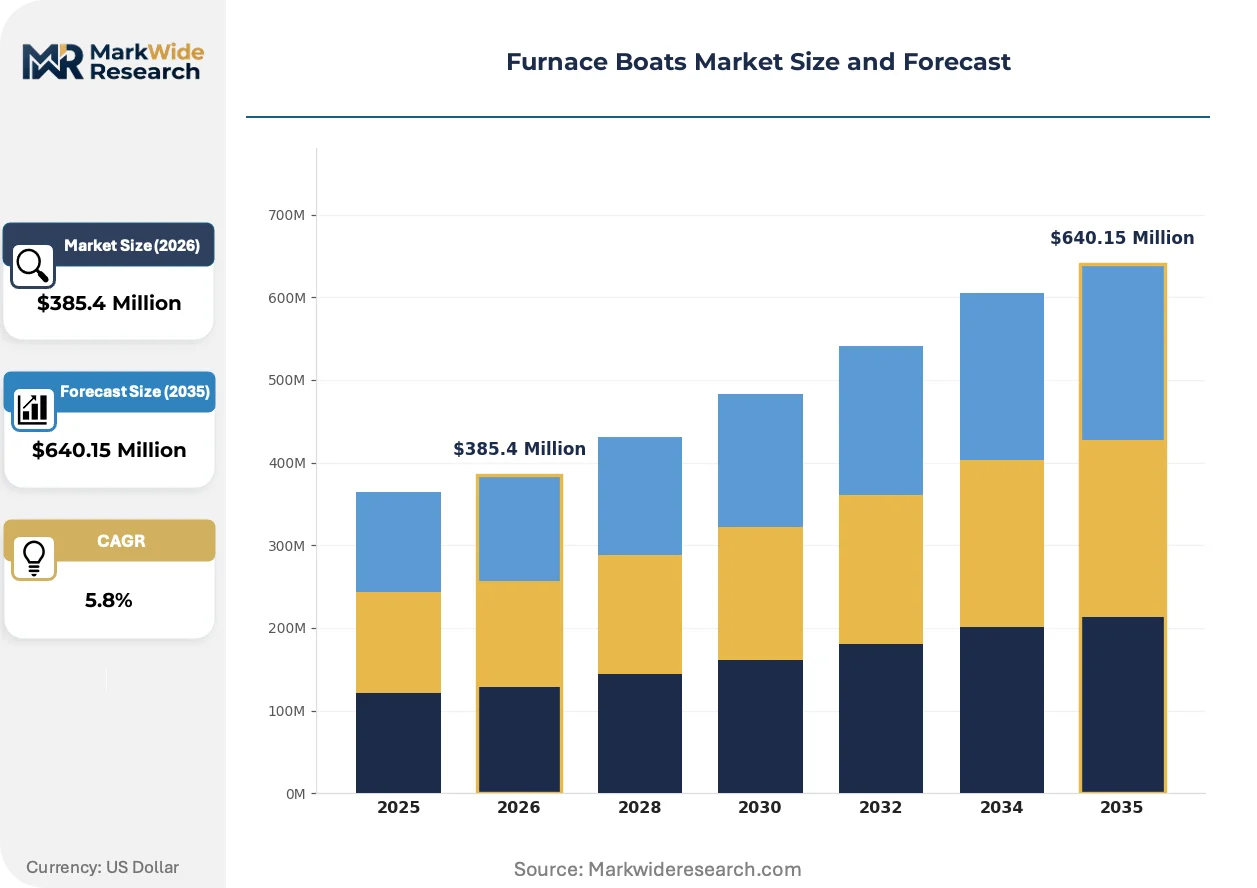
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Hull, Aluminum Hull, Fiberglass Hull, Composite Hull Technology: Hot Air Furnace, Gas-fired Furnace, Electric Furnace, Oil-fired Furnace Application: Marine Transportation, Offshore Drilling, Shipbuilding Support, Harbor Services, Vessel Maintenance End User: Shipyards, Offshore Operators, Port Authorities, Marine Equipment Providers |
| Companies Covered | HC Starck Solutions, Better Ceramic, CE-MAT, Liling Zen Ceramic, CS CERAMIC, Feedback Technology, Edgetech Industries, Ferrotec, SH Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furnace Boats Market Trends and Innovations
Active transformation in furnace boat architecture centers on three vectors: electric heating system maturation, regulatory-driven material substitution, and buyer procurement model evolution toward lifecycle contracting.
Hybrid ceramic-metal composite insulation is decomposing the traditional steel-hull dominance in arctic support vessels. Norwegian offshore operators are specifying these configurations for 60% of new North Sea fleet orders. The technology is compressing thermal bridging losses by 40% while enabling lighter displacement hulls.
REACH and RoHS compliance deadlines are accelerating refractory metal substitution in European-built furnace boats. Shipyards face material requalification costs exceeding €2 million per hull series. The alumina-zirconia lining segment is capturing premium positioning as tungsten-molybdenum alternatives face supply restriction risks.
Energy-sector fleet managers are consolidating vendor relationships around 10-year total-cost-of-ownership contracts. Traditional shipyard spot purchasing is retreating to coastal maintenance and repair segments. This behavioral shift is most pronounced in Norway and the UK, where integrated oil companies operate captive vessel fleets exceeding 200 heated work boats.
Furnace Boats Market Segmentation
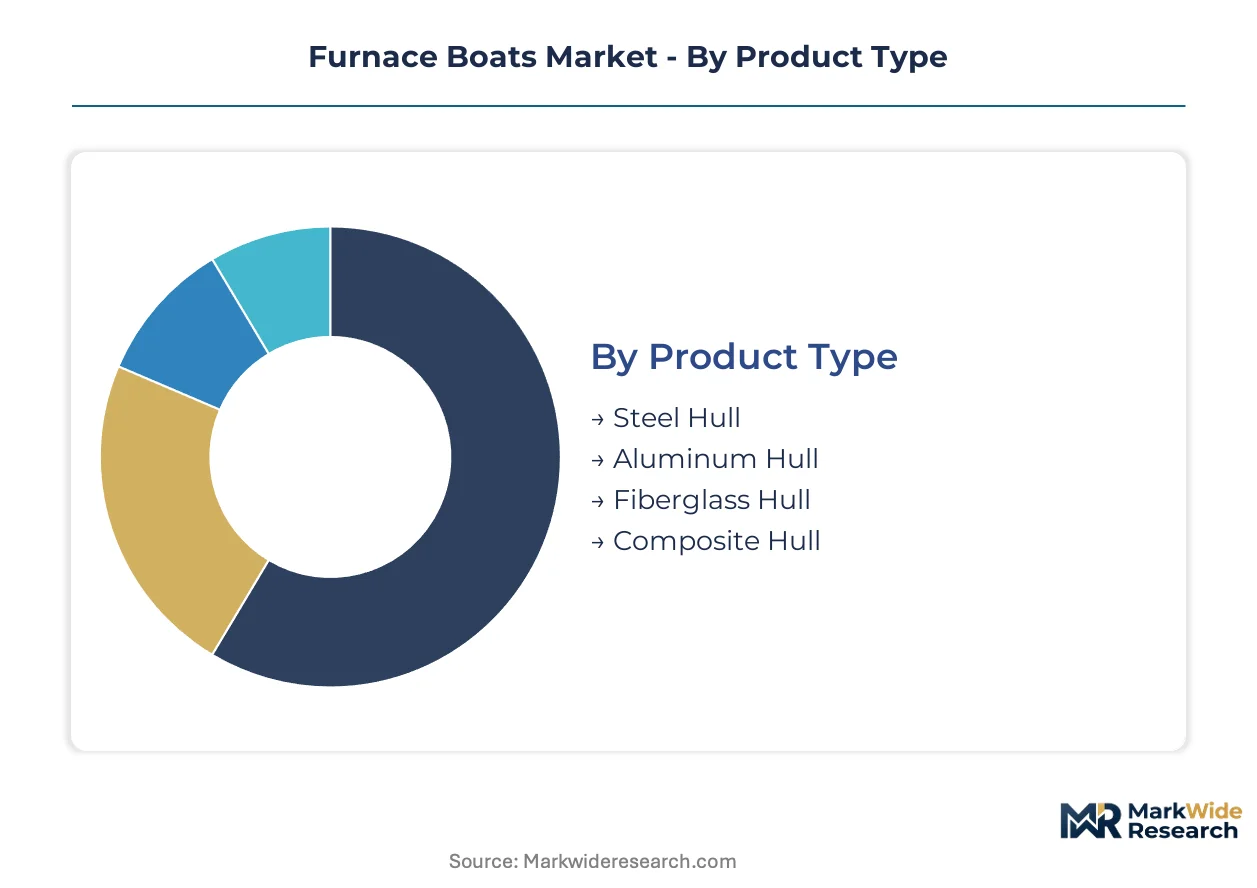
Furnace boat procurement channels diverge sharply by hull material and heating technology, with offshore operators favoring integrated suppliers while port authorities buy through specialized marine equipment distributors. Understanding these segment-channel pairings reveals where pricing power concentrates and which specifications drive contract terms.
Product Type:
Steel hull configurations flow primarily through legacy shipyard direct contracts, aluminum and composite variants move via marine equipment distributors serving coastal operators, while fiberglass hulls reach buyers through specialized thermal vessel brokers.
- Steel Hull:Heavy-gauge carbon or stainless steel substrates with ceramic fiber insulation rated for continuous service above 1,200°C. Norwegian North Sea operators specify these for 60% of arctic drilling support orders, prioritizing structural durability over weight savings in ice-prone waters.
- Composite Hull:Hybrid ceramic-metal configurations that compress thermal bridging losses by 40% through reduced heat transfer pathways. These represent the fastest-climbing segment as EU Green Deal mandates push shipyards toward lighter displacement vessels with lower fuel consumption profiles.
- Aluminum Hull:Lightweight coastal workhorses favored where fuel efficiency governs operating economics and corrosion-resistant alloys extend service intervals in saltwater environments.
- Fiberglass Hull:Cost-optimized options for harbor services and short-haul thermal cargo transport where extreme temperature ratings are secondary to acquisition price.
By volume, steel hull leads. By expansion trajectory, composite hull is gaining share fastest.
Technology:
Cost tier stratification separates premium electric systems from standard gas-fired units, with oil-fired technology retreating to price-sensitive emerging markets and hot air furnaces occupying a narrow retrofit niche.
- Gas-fired Furnace:Combustion-based heating architectures using marine-grade diesel or natural gas with rapid heat-up cycles essential for offshore drilling support. These retain volume dominance where energy density and thermal output speed remain operational priorities.
- Electric Furnace:Resistance heating systems with precision thermal control and sealed architectures that eliminate greenhouse gas leakage. Port authorities facing EU F-Gas Regulation mandates specify these for harbor service fleets, accepting premium pricing for emissions compliance.
- Hot Air Furnace:Convection-based systems for coating cure applications and moderate-temperature cargo protection in coastal marine transportation.
- Oil-fired Furnace:Legacy combustion technology constrained by US EPA marine emissions enforcement in domestic harbors, now concentrated in regions with less stringent environmental oversight.
Gas-fired systems dominate contract value. Electric configurations show the steepest adoption curve in European harbors.
Application:
Customer type mapping reveals offshore drilling as the margin-rich segment served by integrated oil company fleet managers, while harbor services and vessel maintenance flow through fragmented municipal and third-party operator procurement.
- Offshore Drilling:Heated work vessels maintaining crew productivity and equipment operability in sub-zero North Sea conditions. Fleet managers here consolidate vendor relationships around 10-year total-cost-of-ownership contracts, displacing traditional shipyard spot purchasing.
- Marine Transportation:Temperature-sensitive cargo protection for chemicals, food products, and specialized industrial materials requiring controlled thermal environments during coastal and short-sea shipping.
- Shipbuilding Support:Curing ovens and thermal treatment vessels for coating application and metal stress relief during new construction and repair cycles.
- Harbor Services:Municipal and private port operations including ice-breaking assistance, buoy maintenance, and thermal support for dredging equipment.
- Vessel Maintenance:Mobile thermal systems for in-water repairs, coating removal, and emergency heating of disabled vessels.
Offshore drilling commands the highest per-unit pricing. Harbor services represent the broadest addressable base by vessel count.
End User:
Geography drives distinct procurement patterns, with Norway's North Sea cluster anchoring offshore operator demand while Rotterdam, Hamburg, and Antwerp port authorities lead electric furnace specification in European harbors.
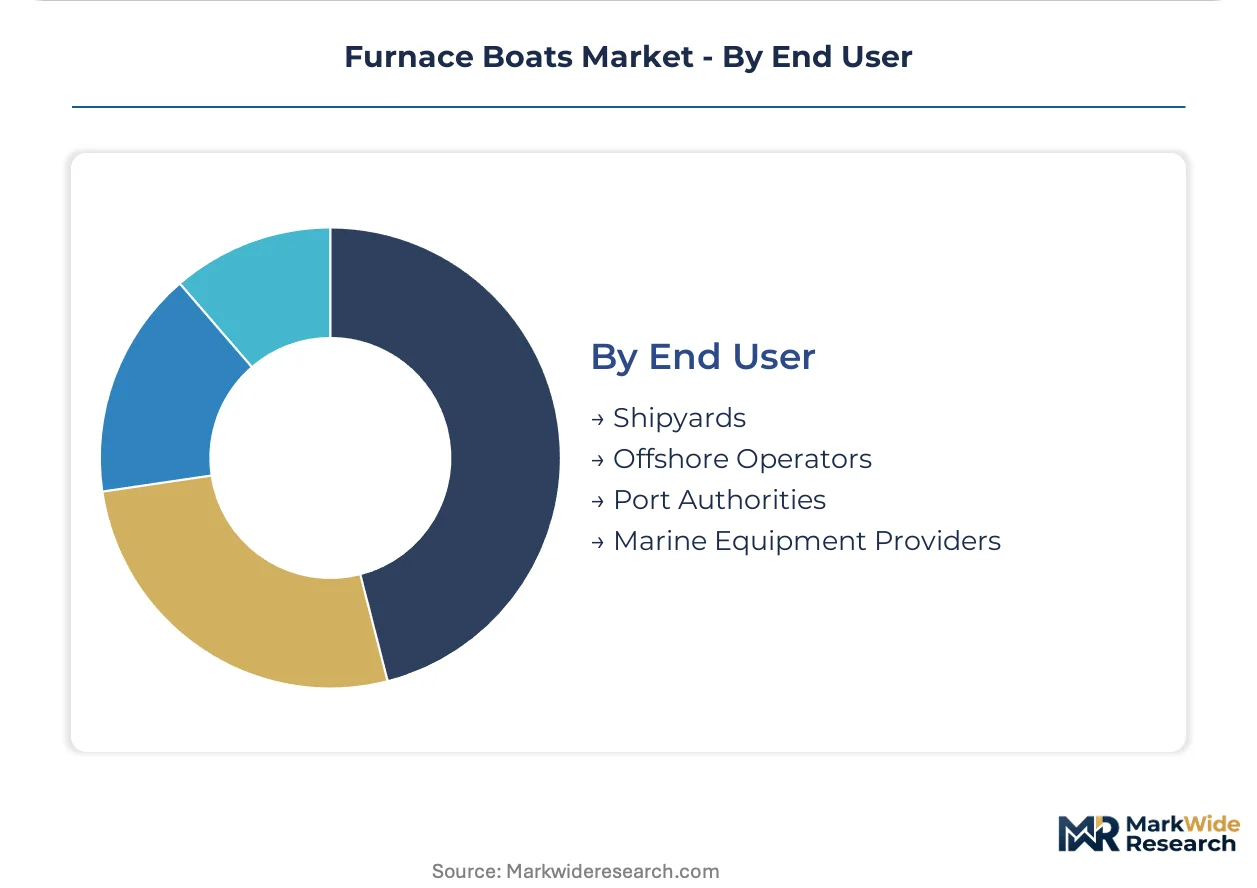
- Offshore Operators:Integrated oil companies and drilling contractors operating captive fleets exceeding 200 heated work boats in Norway and the UK. These buyers specify hybrid ceramic-metal hulls and prioritize 10-year lifecycle contracting over upfront capital expenditure.
- Port Authorities:Municipal and regional harbor managers facing emissions restrictions in European ports. These end users drive demand for shore-power-compatible electric furnace boats with sealed thermal systems.
- Shipyards:Traditional construction and repair facilities purchasing furnace boats for in-house coating cure, metal treatment, and new build thermal processes.
- Marine Equipment Providers:Distributors and rental fleet operators serving fragmented coastal operators with standardized thermal vessel configurations.
Offshore operators generate the largest individual contract values. Port authorities are expanding fastest as harbor electrification mandates multiply across EU member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipyards capable of producing thermally insulated marine vessels cluster in Northern Europe and East Asia, with specialized furnace boat construction concentrated among yards serving North Sea offshore operators and Chinese export manufacturers.
Norway
Arctic drilling expansion drives heated work vessel procurement from integrated oil companies operating in the North Sea. The EU F-Gas Regulation pressures domestic builders toward sealed electric furnace architectures. Bergen and Stavanger host the densest concentration of fleet managers specifying hybrid ceramic-metal hull configurations.
China
SAMR and GB standards compliance creates procurement complexity for harbor service fleets seeking imported thermal vessel technology. The country's dual carbon goals accelerate domestic electric furnace R&D investments. Dalian and Shanghai shipyards dominate export contract manufacturing for Southeast Asian port authorities.
Germany
REACH and RoHS deadlines force material requalification across Hamburg and Bremen shipbuilding clusters. The EU Green Deal's maritime decarbonization mandates push port authorities toward shore-power-compatible electric systems. KBA certification requirements add regulatory layering for combustion-to-electric conversion projects.
United States
US Coast Guard and EPA joint enforcement constrains oil-fired furnace installations in domestic harbors. Gulf Coast offshore operators maintain gas-fired fleet dominance where rapid heat-up cycles remain operational priorities. Houston and New Orleans anchor the heaviest concentration of drilling support vessel procurement.
United Kingdom
North Sea operators consolidate vendor relationships around lifecycle contracting models displacing traditional spot purchasing. The EU MDR framework pressures Aberdeen and Scottish coastal yards toward sealed thermal system architectures. Integrated oil companies here operate captive heated work boat fleets exceeding 200 vessels.
Furnace Boats Market Competitive Landscape
Concentration sits with refractory metal specialists and precision thermal control system providers rather than generalist shipbuilders. The vendor base spans three tiers: integrated material-science conglomerates supplying high-temperature components, precision electronics firms anchoring electric furnace architectures, and regional ceramic fabricators serving maintenance and repair segments. Dominant competitive moves include strategic partnerships between hull manufacturers and heating system integrators, plus technology licensing agreements that transfer ceramic fiber insulation formulations across shipyard networks.
Within the material-science tier, HC Starck Solutions exemplifies the refractory metal specialization archetype, while CS CERAMIC occupies a position among ceramic lining specialists. Ferrotec anchors the precision thermal control segment. These three represent distinct capability clusters rather than direct substitutes, with each serving different specification requirements across offshore drilling, harbor services, and shipbuilding support applications.
| Leading Market Players |
|---|
| HC Starck Solutions |
| Better Ceramic |
| CE-MAT |
| Liling Zen Ceramic |
| CS CERAMIC |
| Feedback Technology |
| Edgetech Industries |
| Ferrotec |
| SH Scientific |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance gates both supplier qualification and price differentiation simultaneously, forcing shipyards to absorb certification costs that stratify furnace boat offerings across sealed electric and legacy combustion architectures. Buyers face tiered cost structures where emissions-compliant vessels command premiums while non-compliant inventory faces accelerated depreciation in European harbors.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across the Furnace Boats Market, separating premium electric furnace configurations from standard gas-fired units and retreating oil-fired economy options. Price differentiation rests on certification grade and thermal output specification, with sealed electric systems capturing margin premiums from Rotterdam and Hamburg port authorities. Cost compression in the gas-fired tier is intensifying because Norwegian offshore operators are consolidating procurement around 10-year lifecycle contracts. Harbor services represent the most price-sensitive segment, while integrated oil company fleet managers prioritize performance over upfront capital expenditure.
Supply Chain Analysis
Strategic stockpiling of tungsten and molybdenum refractory metals dominates inventory strategy among furnace component suppliers, buffering against supply concentration in limited geographies. Sourcing draws from China, Germany, and the United States for high-temperature alloys, with alumina-zirconia ceramic linings increasingly anchoring European builds. Single-source vulnerability in rare refractory metal supply creates exposure to export restriction risks. Distribution runs through integrated material-science conglomerates serving shipyard direct contracts, with regional ceramic fabricators capturing maintenance and repair segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized marine thermal engineering expertise is concentrated among legacy shipyard workforces, creating a capability bottleneck that constrains fleet expansion and electrification conversion capacity across the Furnace Boats Market.
For Market Incumbents: Fortify position by deepening backward integration into alumina-zirconia ceramic supply chains and securing exclusive refractory metal offtake agreements with tungsten-molybdenum processors. Battery-electric heating system specialists represent an emerging entrant threat to gas-fired incumbents; counter by accelerating combustion-to-electric conversion service offerings for captive fleet customers. For New Entrants and Emerging Players: SAMR certification fast-track partnerships with Dalian and Shanghai shipyards unlock access to Chinese harbor service procurement channels. White-space targets include Southeast Asian port authorities seeking EU-compliant electric furnace technology and North Sea maintenance segments requiring ceramic lining replacement services. Go-to-market through lifecycle contracting models displaces traditional spot purchasing among municipal harbor managers. For Investors and Strategic Acquirers: EU Green Deal maritime decarbonization milestones reshape the acquisition landscape toward electric furnace technology specialists and hybrid hull composite suppliers. Long-term viability centers on 5-10 year electrification transition windows as regulatory timelines harden. Target acquisition archetypes include precision thermal control system providers and ceramic fiber insulation formulators. Watch for F-Gas Regulation enforcement intensity crossing thresholds that strand combustion-based fleet assets.| Strategic Initiative | Industry Significance |
|---|---|
| Refractory Metal Supply Agreement | Long-term tungsten-molybdenum contracts with Chinese and German processors secure input cost stability for high-temperature components. |
| Electric Furnace Technology Licensing | Precision thermal control system partnerships with European port authorities accelerate harbor electrification mandate compliance. |
| Hybrid Hull Composite Joint Venture | Ceramic-metal insulation configurations with Norwegian shipyards capture 60% of North Sea arctic drilling support orders. |
| SAMR Certification Pathway Investment | Chinese regulatory compliance infrastructure opens access to Dalian and Shanghai export manufacturing contracts. |
| Lifecycle Service Contract Expansion | 10-year total-cost-of-ownership offerings displace spot purchasing among integrated oil company fleet managers. |
Research Methodology
Initial hypotheses were tested against primary input from shipyard procurement directors, offshore operator fleet managers, port authority engineering leads, and refractory metal suppliers and refined through secondary validation. Shipyard production databases, EU MDR filing records, customs trade data for tungsten and molybdenum flows, and SAMR certification registries anchored quantitative triangulation. Bottom-up vessel deployment counts and top-down energy-sector capital expenditure patterns were reconciled to establish market sizing.
Variance-decomposition across hull material, heating technology, application, and end-user segments structured the analytical framework over the projection horizon. Modeled dimensions included steel-aluminum-composite-fiberglass substrates, gas-electric-hot air-oil furnace architectures, offshore drilling-marine transportation-shipbuilding support-harbor services-vessel maintenance applications, and offshore operator-port authority-shipyard-marine equipment provider buyer categories. CAGRs were derived from segment-level deployment trajectories and regulatory mandate implementation schedules, with thermal insulation material cost curves and battery energy density improvement rates as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable refractory metal supply geography; material deviation would warrant model refresh. Forecasts reflect base-case regulatory timelines and technology cost curves. Revision becomes warranted when battery-electric heating output crosses thresholds that match gas-fired rapid heat-up performance or when F-Gas Regulation enforcement intensity accelerates beyond modeled trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Military Marine Engine Market
Marine
Marine and Marine Management Software Market
Marine
Marine Beacon Market
Marine
Rigid Inflatable Boats (RIB) Market
Marine
Boat Steering Systems Market
Marine
Ship Heat Exchanger Market
Marine
Yacht Painting and Maintenance Market
Marine
Marine Filter Market
Marine
Global Foldable Inflatable Boats Market
Marine
Europe Recreational Boating Market
Marine
Unmanned Marine Vehicles Market
Marine
Trim Tabs Market
Marine
Global Maritime Information Market
Marine
Hydrofoil Market
Marine
Marine Pipes Market
Marine
Marine VFD Market