
 Automotive Integrated Circuit (Ics) Market | 2026-2036
Automotive Integrated Circuit (Ics) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Integrated Circuit (Ics) Market Intelligence
The capital investment gap between leading-edge and legacy semiconductor fabrication is redrawing the competitive landscape for automotive ICs. This divergence separates firms capable of funding 5nm and smaller process nodes from those focused on mature, cost-optimized technologies. Infineon Technologies AG leverages its scale in power semiconductors and microcontrollers to serve a broad base of applications. NXP Semiconductors specializes in secure connectivity and in-vehicle networking solutions, while Texas Instruments competes with a vast portfolio of analog and embedded processing products.
Automotive integrated circuits are specialized semiconductor devices designed to operate reliably in the harsh thermal and electrical environments of vehicles. These components, often built on Complementary Metal-Oxide-Semiconductor (CMOS) or Bipolar Junction Transistor (BJT) technology, manage functions from engine control to in-cabin infotainment. Microcontrollers and Power Management ICs form the foundational volume of the market, serving essential vehicle functions. Application-specific ICs for Advanced Driver Assistance Systems (ADAS) and Infotainment & Telematics represent the fastest-growing segment.
Automotive functional safety standards, particularly ISO 26262, mandate stringent design and validation processes for critical ICs used in systems like braking and steering. Component-level reliability is governed by AEC-Q100 stress test qualifications, which are prerequisites for supplier contracts with major OEMs. Suppliers must navigate the increasing complexity of software-defined vehicle architectures while ensuring compliance across these multiple international standards to maintain market access.
Market Dynamics
The transition toward zonal electronic/electrical (E/E) architectures is the central force shaping the automotive IC market. This architectural shift away from a distributed domain-based ECU model concentrates computing power into fewer, more powerful vehicle computers, altering demand for specific IC types.
Growth Catalysts
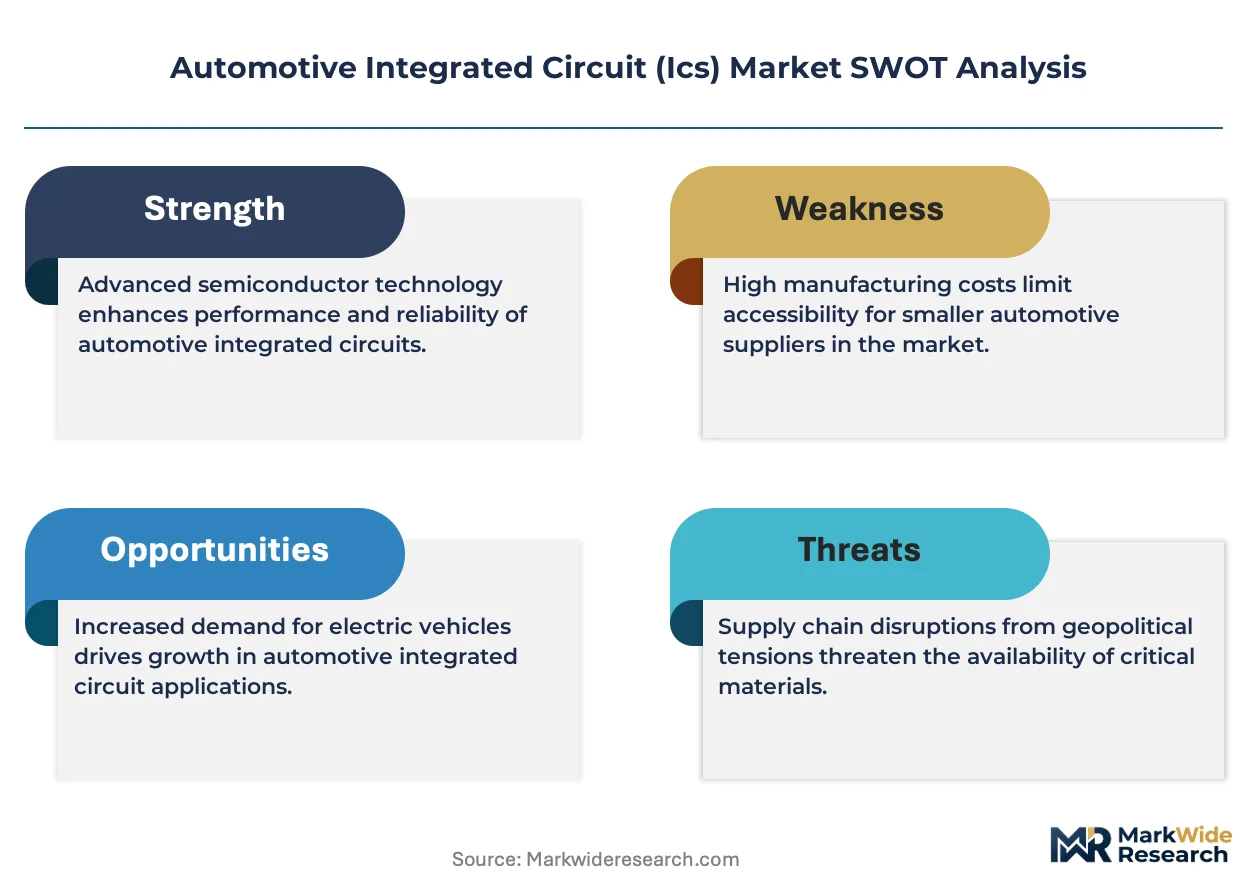
- ADAS Proliferation:The integration of Advanced Driver Assistance Systems (ADAS) across all vehicle segments necessitates a higher density of sensor ICs, vision processors, and high-performance application-specific ICs to manage real-time data processing and decision-making.
- Functional Safety Mandates:Automotive safety standards, led by ISO 26262, require redundant and fault-tolerant electronic systems for critical functions like steering and braking, compelling the use of specialized microcontrollers and power management ICs with built-in safety mechanisms.
- EV Production in China:Accelerated electric vehicle manufacturing in China creates intense demand for power semiconductors, including silicon carbide (SiC) and gallium nitride (GaN) devices, as well as sophisticated battery management system (BMS) ICs.
Market Restraints
- Advanced Node Capex:The immense capital expenditure required to build and operate foundries for sub-7nm process nodes creates a significant barrier to entry, concentrating leading-edge production capacity among a few key global players.
- Qualification Lead Times:The stringent AEC-Q100 stress testing and validation process for automotive-grade components introduces long qualification cycles, delaying the deployment of the latest semiconductor innovations into new vehicle platforms compared to the consumer electronics sector.
- Geopolitical Supply Risks:Heavy reliance on foundries located in specific geopolitical hotspots, particularly for advanced logic and memory ICs, exposes the entire automotive supply chain to potential disruptions from trade disputes or regional instability.
Strategic Opportunities
- Vehicle-to-Everything (V2X) ICs:The rollout of 5G infrastructure provides an opportunity for specialized ICs that enable low-latency V2X communication, a foundational technology for cooperative autonomous driving and advanced traffic management systems.
- AI and Sensor Fusion SoCs:The convergence of artificial intelligence processing with data from multiple sensors (camera, radar, LiDAR) creates a market for powerful, energy-efficient System-on-Chips (SoCs) designed specifically for autonomous driving compute platforms.
- EV Ecosystem in India:Government initiatives like India's Production Linked Incentive (PLI) scheme for automobiles and electronics foster a developing ecosystem for EV manufacturing, opening a new growth frontier for suppliers of power management and motor control ICs.
Industry Challenges
- Functional Safety Talent Gap:A persistent shortage of engineers with dual expertise in semiconductor design and ISO 26262 functional safety protocols hinders the development and validation of safety-critical automotive electronics.
- Software and Hardware Co-Design:Integrating increasingly complex software stacks onto fixed hardware platforms presents a major challenge, requiring new development methodologies and closer collaboration between automakers, Tier-1s, and semiconductor firms.
- Cybersecurity Threat Management:Ensuring the security of connected vehicles against remote attacks requires a multi-layered approach, from secure boot processes at the IC level to over-the-air (OTA) update mechanisms, all governed by emerging standards like UNECE WP.29.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Integrated Circuit (Ics) Market |
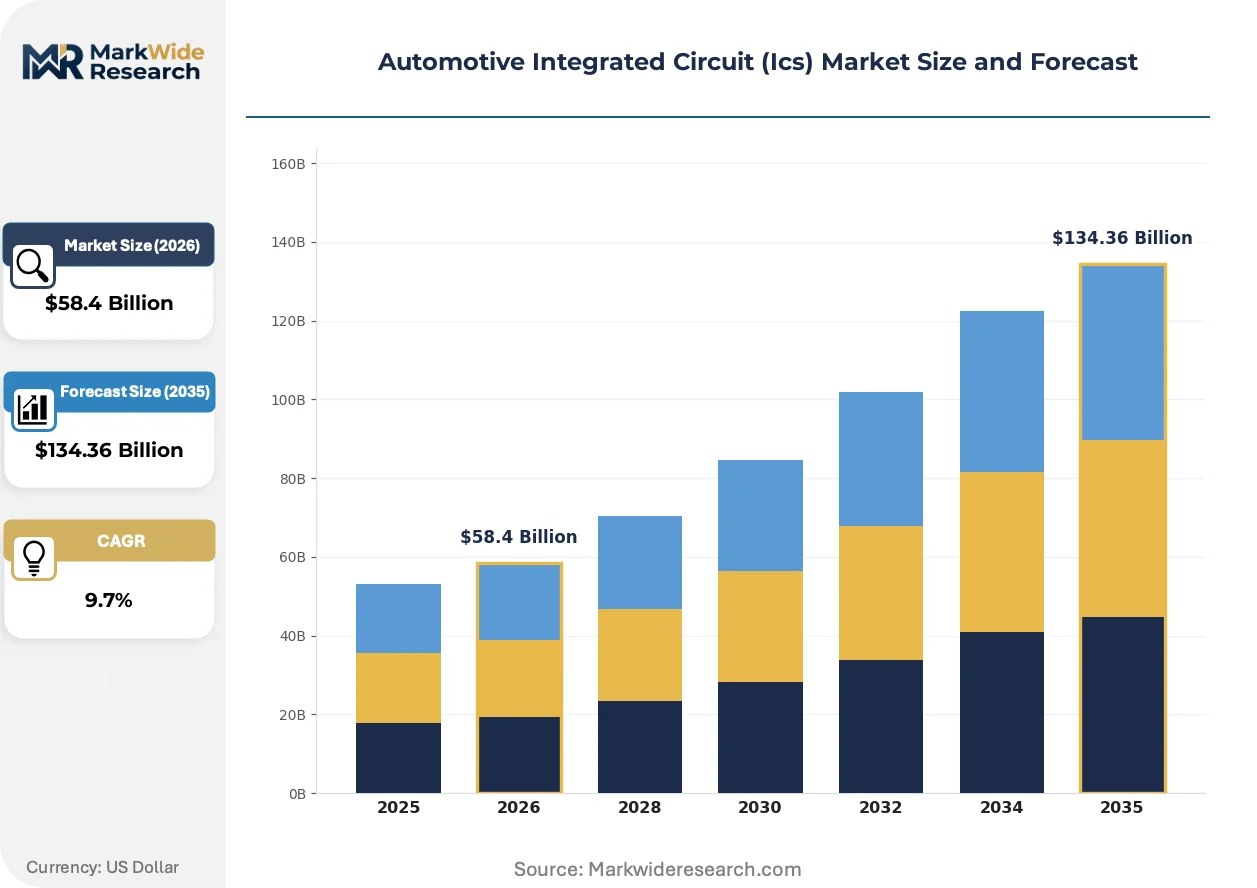
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $134.36 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Power Management ICs, Sensors ICs, Connectivity ICs, Memory ICs, Logic ICs Technology: Complementary Metal-Oxide-Semiconductor, Bipolar Junction Transistor, Silicon-On-Insulator, Gallium Nitride, BiCMOS, Tunnel Field-Effect Transistor Application: Advanced Driver Assistance Systems, Infotainment & Telematics, Electric Power Steering, Engine Management, Airbag Control, Battery Management End User: OEMs, Tier-1 Suppliers, Vehicle Assembly Plants, Aftermarket Providers |
| Companies Covered | Infineon Technologies AG, NXP Semiconductors, STMicroelectronics, Texas Instruments, Renesas Electronics Corporation, Analog Devices, ON Semiconductor, Robert Bosch, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Integrated Circuit (Ics) Market Strategic Shifts & Innovations
The evolution of automotive ICs is defined by a fundamental tension between the soaring computational demands of software-defined vehicles and the strict physical and reliability constraints of the automotive environment. This drives innovation in packaging, process technology, and design methodology.
System-in-Package (SiP) technology integrates multiple heterogeneous dies, such as a microcontroller, memory, and analog components, into a single compact module. Automotive electronics suppliers are rapidly adopting SiP to reduce the physical footprint and complexity of Electronic Control Units (ECUs). This trend is miniaturizing control modules for applications like lighting and gateway functions, which enables more flexible placement within zonal vehicle architectures.
Forthcoming regulations like the EU AI Act are set to impose new compliance burdens on automotive systems. The Act classifies AI used in critical safety applications, such as autonomous driving, as high-risk, mandating stringent documentation, transparency, and oversight. Consequently, ICs designed for ADAS platforms must now incorporate hardware-level features for traceability and auditability to meet these European legal requirements.
A pivotal shift in sourcing strategy involves automotive OEMs bypassing traditional channels to engage directly with semiconductor designers. This model displaces the historical role of Tier-1 suppliers for high-value components like central compute SoCs and custom ADAS processors. This direct-sourcing behavior is most advanced among dedicated EV manufacturers and premium German automakers aiming to secure their technology roadmaps.
Automotive Integrated Circuit (Ics) Market Segmentation
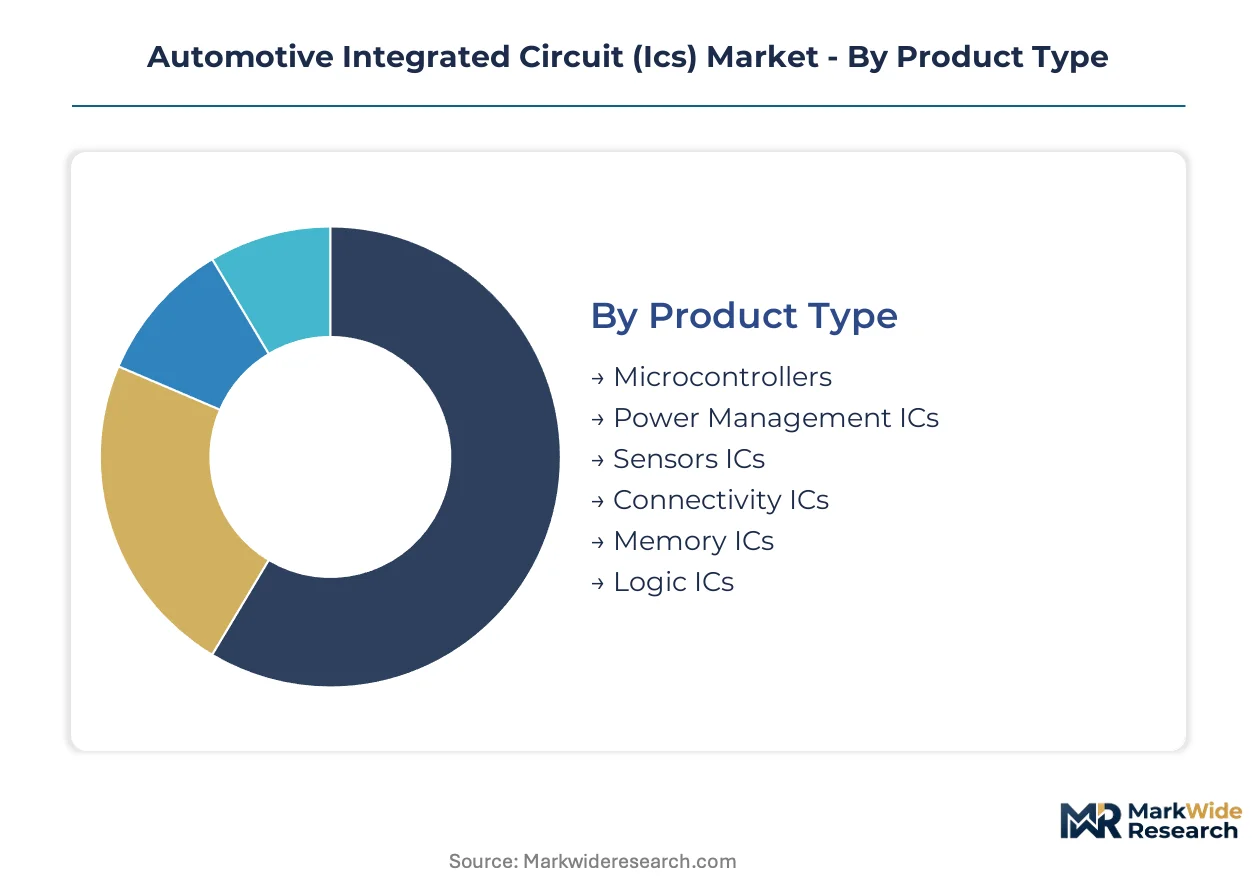
The automotive integrated circuit market segments reflect the diverse technological requirements and application environments within modern vehicles. Understanding these distinctions is critical for suppliers to align product development with evolving industry standards and customer needs. Each segment addresses specific functional demands, from basic vehicle operations to advanced autonomous capabilities.
Product Type:
Regulatory mandates for functional safety and emissions drive significant differentiation across automotive IC product types. These standards influence design complexity and validation requirements for components operating in critical vehicle systems.
- Microcontrollers:These embedded processors execute specific control functions, containing a CPU, memory, and peripherals on a single chip. Demand for high-performance microcontrollers is particularly strong in Germany for advanced engine management and chassis control systems, driven by stringent European emissions regulations.
- Power Management ICs:These circuits regulate and distribute electrical power within vehicle systems, optimizing efficiency and thermal performance. Demand for sophisticated power management ICs is concentrated in China's electric vehicle manufacturing hubs, supporting high-voltage battery systems and efficient motor drives.
- Sensors ICs:These devices convert physical parameters like pressure, temperature, or acceleration into electrical signals for vehicle systems.
- Connectivity ICs:These components enable communication within the vehicle and with external networks, supporting telematics and V2X functions.
- Memory ICs:These chips store data and program instructions for various automotive applications, from infotainment to ADAS.
- Logic ICs:These integrated circuits perform digital processing and control functions across a wide range of vehicle electronics.
Established volume favors Microcontrollers; emerging adoption favors Connectivity ICs.
Technology:
Application-driven performance requirements heavily influence the selection and development of automotive IC technologies. Different vehicle functions demand specific trade-offs in power efficiency, processing speed, and thermal resilience.
- Complementary Metal-Oxide-Semiconductor:CMOS technology is foundational for digital logic and mixed-signal circuits, offering high integration density and low power consumption. Demand often converges in infotainment and ADAS processors manufactured in South Korea, balancing performance with energy efficiency.
- Gallium Nitride:GaN is a wide bandgap semiconductor material offering superior power efficiency and switching speeds compared to silicon, particularly in high-voltage applications. Demand for GaN devices is surging in Japan for electric vehicle power electronics, supporting compact and efficient onboard chargers and inverters.
- Bipolar Junction Transistor:BJT technology provides high current gain and is used in analog circuits and power management applications.
- Silicon-On-Insulator:SOI technology reduces parasitic capacitance, enhancing performance and radiation hardness for demanding automotive environments.
- BiCMOS:BiCMOS combines bipolar and CMOS transistors on a single chip, leveraging the strengths of both for mixed-signal designs.
- Tunnel Field-Effect Transistor:TFETs are emerging low-power devices offering steep subthreshold slopes, promising ultra-low power operation for future automotive sensors.
Volume concentration remains with CMOS; advanced power applications are shifting towards Gallium Nitride.
Application:
The volume and complexity of automotive ICs are directly correlated with the functional capabilities and safety requirements of specific vehicle applications. Each application presents unique demands for processing power, reliability, and real-time responsiveness.
- Advanced Driver Assistance Systems:ADAS applications, including adaptive cruise control and automatic emergency braking, require high-performance vision processors, radar chips, and sensor fusion SoCs. Demand for these ICs is robust in the United States, driven by consumer safety expectations and evolving regulatory frameworks for autonomous features.
- Battery Management:BMS ICs monitor and control battery cells in electric vehicles, ensuring optimal performance, safety, and longevity. Demand for these specialized power and control ICs is surging in China, propelled by accelerated EV production and the need for efficient energy management systems.
- Infotainment & Telematics:These systems provide navigation, communication, and entertainment functionalities within the vehicle cabin.
- Electric Power Steering:EPS systems utilize microcontrollers and power ICs to provide steering assistance, enhancing vehicle maneuverability and fuel efficiency.
- Engine Management:Engine management systems rely on microcontrollers and sensor ICs to optimize fuel injection, ignition timing, and emissions control.
- Airbag Control:Airbag control units integrate sensor ICs and microcontrollers to detect collisions and deploy safety restraints effectively.
ADAS represents the fastest-growing trajectory; Engine Management maintains a stable, foundational volume.
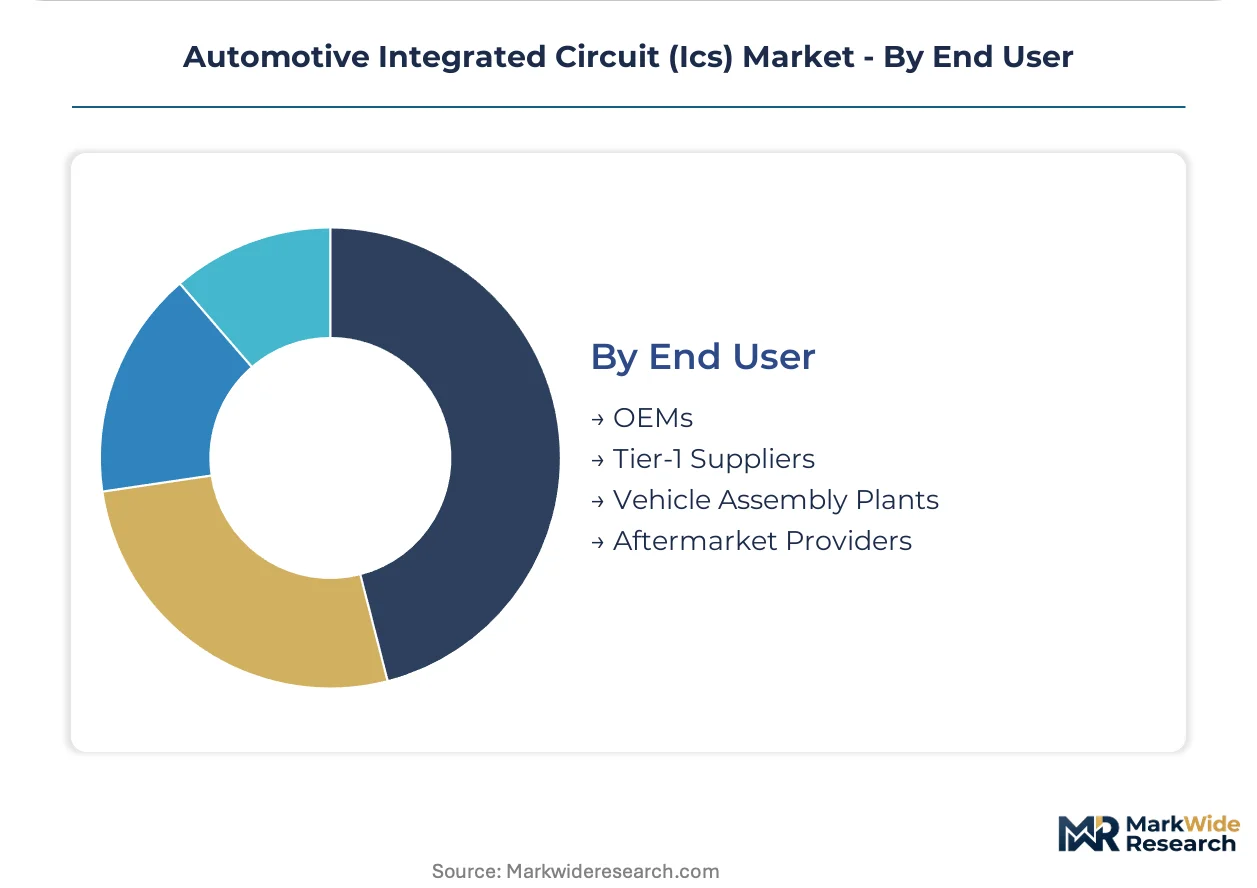
End User:
The procurement models and design influence of different end-user segments directly impact the specifications and supply chain dynamics for automotive ICs. Each end-user type has distinct requirements regarding customization, volume, and validation.
- OEMs:Original Equipment Manufacturers directly integrate ICs into their vehicle platforms, increasingly engaging in direct sourcing for high-value components. Demand from OEMs for custom ADAS processors and central compute SoCs is particularly strong among premium German automakers, seeking to differentiate their technology stacks.
- Tier-1 Suppliers:Tier-1 suppliers design and manufacture complete electronic control units (ECUs) and modules for OEMs, integrating various ICs into their solutions. Demand from Tier-1 suppliers for standard microcontrollers and power management ICs is consistent across global automotive production centers, including Mexico and Eastern Europe.
- Vehicle Assembly Plants:These facilities integrate pre-assembled modules and ECUs into the final vehicle, with less direct influence on IC selection.
- Aftermarket Providers:These companies supply replacement parts and upgrade components, often requiring ICs that are compatible with older vehicle architectures.
Procurement models are shifting, with OEMs increasingly displacing traditional Tier-1 supplier roles for critical ICs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regions with advanced fabrication capabilities, such as South Korea, exert significant pricing power for leading-edge automotive ICs due to high capital expenditure requirements. Conversely, high-volume manufacturing hubs like China increasingly prioritize cost-optimized solutions for their rapidly expanding electric vehicle production. This asymmetry shapes procurement strategies across the global automotive supply chain.
Germany
German automakers drive demand for high-performance microcontrollers in advanced engine management and chassis control systems. European emissions regulations compel IC designs with enhanced efficiency and precision. Automotive R&D centers in Stuttgart and Munich focus on integrating these sophisticated components into premium vehicle platforms.
United States
Consumer safety expectations and evolving regulatory frameworks in the United States fuel demand for ADAS processors and sensor fusion SoCs. NHTSA guidelines influence the design of safety-critical automotive electronics. Silicon Valley continues to innovate AI and sensor fusion SoCs, while Detroit integrates these technologies into new vehicle architectures.
China
Accelerated electric vehicle manufacturing in China creates intense demand for power semiconductors and sophisticated battery management system ICs. MIIT policies and dual carbon goals encourage domestic production and adoption of advanced EV components. Major EV production clusters in Shanghai and Shenzhen are focal points for IC procurement.
Japan
Japanese automotive manufacturers are driving the adoption of Gallium Nitride devices for electric vehicle power electronics, emphasizing efficiency. METI initiatives support the development of advanced materials and components for next-generation mobility. Automotive and electronics R&D hubs in Nagoya and Yokohama concentrate on compact and efficient onboard systems.
South Korea
South Korea's robust semiconductor industry supports demand for CMOS technology in infotainment and ADAS processors, balancing performance with energy efficiency. MFDS regulations for electronics and general automotive safety standards influence component validation. Semiconductor manufacturing centers in Seoul and Gyeonggi specialize in high-density IC production for automotive applications.
Automotive Integrated Circuit (Ics) Market Key Industry Players
Market share resides with a few global players capable of funding advanced sub-7nm process nodes, creating a tiered structure. This divergence separates leading-edge foundries from firms focused on mature, cost-optimized technologies. Archetypes include general-purpose microcontroller providers, specialized power semiconductor firms, and secure connectivity solution developers. Major competitive moves involve substantial capital expenditure into new fabrication capacities and strategic partnerships with OEMs to secure design wins.
Specialists in specific automotive segments, such as Infineon Technologies AG, exemplify scale in power semiconductors and microcontrollers, serving a broad application base. NXP Semiconductors occupies a position in secure connectivity and in-vehicle networking solutions, reflecting its focus on critical communication needs for modern vehicle architectures. Texas Instruments, with its vast portfolio, anchors the market for analog and embedded processing products across diverse vehicle functions, from engine control to infotainment. These firms represent distinct strategic approaches within the complex automotive IC ecosystem.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| NXP Semiconductors |
| STMicroelectronics |
| Texas Instruments |
| Renesas Electronics Corporation |
| Analog Devices |
| ON Semiconductor |
| Robert Bosch |
| Microchip Technology |
| Others |
Cost & Logistics Intelligence
Gallium Nitride's emergence as a power semiconductor material is reshaping automotive IC supply geography and pricing economics. Its superior efficiency and switching speeds command a premium over traditional silicon-based devices.
Pricing Analysis
Configured-to-order pricing for specialized ADAS SoCs commands a premium, contrasting with standard pricing for high-volume microcontrollers. Price differentiation drivers include the stringent AEC-Q100 certification level and the volume scale of procurement. Pricing pressure stems from intense competition among suppliers in mature product segments. OEMs exhibit lower price sensitivity for critical, custom components, while Tier-1 suppliers prioritize cost-optimized standard parts.
Supply Chain Analysis
Long qualification lead times for automotive-grade ICs necessitate strategic inventory buffers across the supply chain. Geographic supply concentration for advanced logic and memory ICs centers on South Korea and Taiwan, creating single-source vulnerability for critical components. Raw material dependencies include high-purity silicon wafers and specialized packaging substrates. Distribution runs through direct channels to OEMs for custom SoCs and via Tier-1s for foundational components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Integrated Circuit market is an early-cycle expansion story, propelled by the accelerating penetration of Advanced Driver Assistance Systems (ADAS) and electric vehicles. This fundamental shift generates sustained demand for high-performance and power-efficient semiconductors.
For Market Incumbents: Shield core microcontroller and power semiconductor positions by continuously investing in ISO 26262 functional safety expertise. Deepen vertical integration into advanced packaging technologies to mitigate potential supply chain disruptions. The emerging threat from new entrants specializing in AI SoCs necessitates strategic R&D in sub-7nm process nodes.
For New Entrants and Emerging Players: Differentiate on specialized AI and sensor fusion SoCs, targeting the burgeoning autonomous driving platforms. Target the rapidly growing EV ecosystem in India for advanced motor control and power management ICs. A key go-to-market angle involves direct collaboration with innovative electric vehicle OEMs to secure design wins.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists in secure connectivity or high-performance computing for a 5-10 year horizon. Long-term viability favors firms with strong intellectual property portfolios in functional safety and advanced packaging. An acquisition target archetype includes firms with proven expertise in silicon carbide and gallium nitride power electronics. Watch for increasing OEM direct-sourcing of central compute SoCs as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces design complexity for OEMs and Tier-1s, accelerating vehicle development cycles. |
| Advanced Packaging R&D | Enables higher integration density and thermal performance for ADAS processors. |
| Functional Safety Certification Investment | Ensures compliance with ISO 26262 standards for critical automotive applications. |
| Direct OEM Engagement | Secures design wins for high-value components like central compute SoCs. |
| Silicon Carbide/Gallium Nitride Capacity Expansion | Addresses intense demand for efficient power semiconductors in electric vehicles. |
Research Approach
Cross-validation between primary interviews and extensive secondary data anchors the qualitative findings and quantitative estimates. Interviews with OEM platform engineers, Tier-1 procurement leads, and semiconductor R&D directors informed market dynamics and competitive positioning. Secondary validation utilized vehicle production databases, regulatory filings from MIIT and NHTSA, and industry association reports. Bottom-up and top-down triangulation ensured data consistency across various market segments.
Sensitivity analysis was applied to key assumptions within the forecast framework across the analysis window, assessing various growth scenarios. Segmentation dimensions modeled include product type, technology, application, end-user, and regional automotive production clusters. Compound Annual Growth Rates were derived using a weighted average approach, integrating historical trends with future growth projections. Industry-specific inputs included electric vehicle production forecasts and Advanced Driver Assistance Systems penetration rates.
Material uncertainties — geopolitical trade disputes and rapid technological obsolescence — sit outside the modeled envelope for this analysis. Forecasts reflect assumptions documented at the time of publication. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Standard Logic IC Market
IC (Integrated Circuits)
3D Integrated Circuit Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market
IC (Integrated Circuits)
Americas Analog IC Market
IC (Integrated Circuits)
China Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
Digital IC Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
Asia Pacific Logic IC Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market
IC (Integrated Circuits)
Semiconductor Integrated Circuit Chip Market
IC (Integrated Circuits)
Isolated Interface Chip Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
CMOS Power Amplifier Market