
 Global Special Purpose Logic IC Market | 2026-2036
Global Special Purpose Logic IC Market Size, Share, and Industry Trends Forecast 2026-2036
Global Special Purpose Logic IC Market Foresight
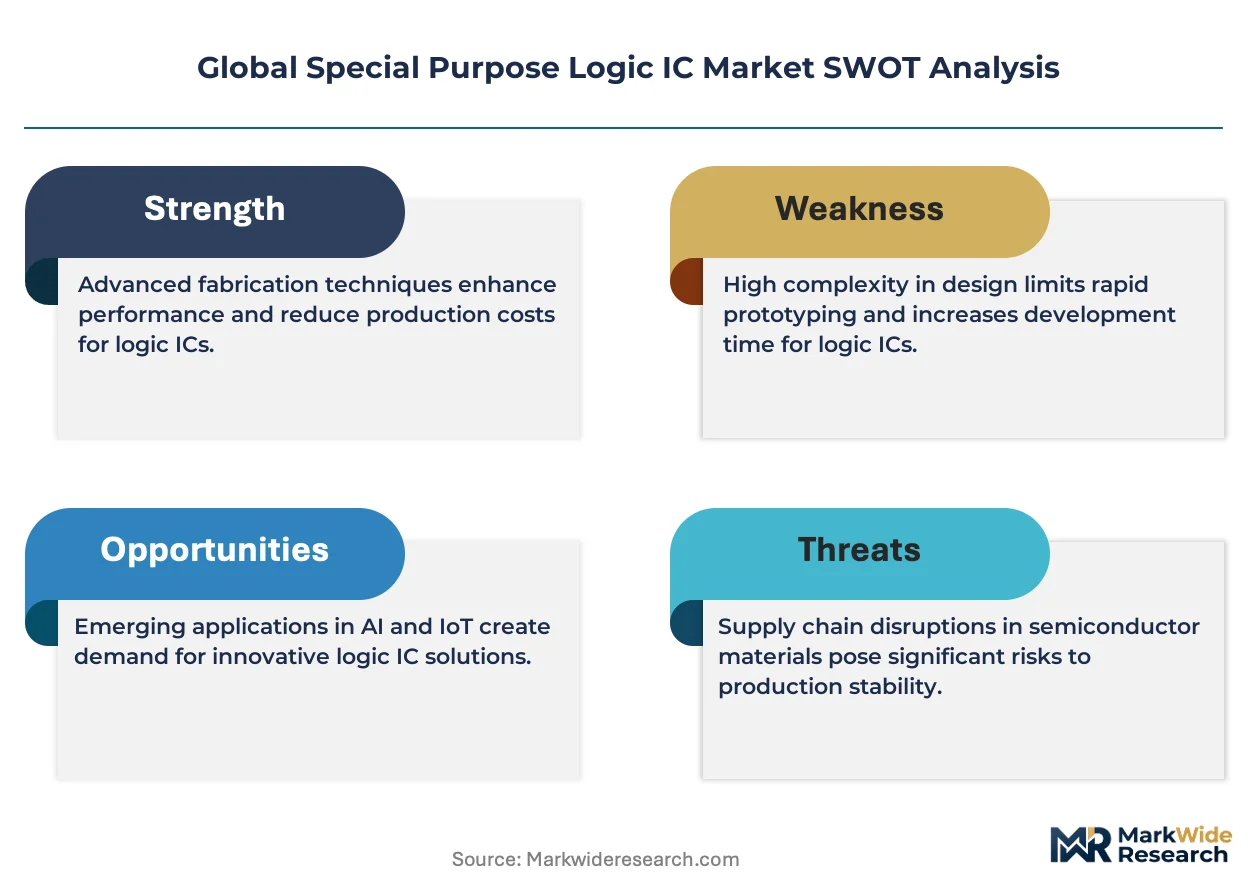
Multi-source foundry strategies is hardening among fabless designers seeking supply resilience. Broadcom leverages captive design flows to sustain margin protection across networking ASICs. Texas Instruments anchors its industrial logic portfolio through in-house 300mm fabrication. Infineon Technologies specializes in automotive-qualified ASSPs with extended temperature-grade certifications.
Special purpose logic ICs are application-optimized semiconductor devices fabricated through CMOS, BiCMOS, or silicon-on-insulator processes to execute predetermined digital functions rather than general-purpose computation. These devices integrate fixed gate arrays, programmable logic blocks, and custom macro cells to achieve deterministic latency and power efficiency in target systems. Application-specific standard products dominate volume shipments for consumer electronics and telecommunications equipment, while programmable logic devices capture expanding share in aerospace systems requiring in-field reconfigurability. Complex programmable logic devices concentrate margin pools within military electronics programs demanding radiation-hardened process nodes.
The US FCC and FDA shape demand through electromagnetic compatibility mandates for medical imaging equipment and radar systems incorporating special purpose logic. China's MIIT enforces GB standards for telecom infrastructure silicon, restricting market access for non-compliant foundry outputs. REACH and RoHS in Europe constrain material compositions across BiCMOS and bipolar process flows. Stakeholders must monitor foundry allocation agreements between leading IDMs and pure-play manufacturers as geopolitical export controls tighten on advanced lithography equipment.
Market Dynamics
Foundry allocation agreements between Taiwan Semiconductor Manufacturing and leading fabless designers are reshaping supply security calculations across advanced node production. Taiwan's concentration of extreme ultraviolet lithography capacity creates single-point vulnerability for radiation-hardened special purpose logic destined for aerospace and defense programs.
Growth Catalysts
- 5G Infrastructure Deployment:Telecommunications equipment manufacturers in South Korea and Germany are accelerating orders for deterministic-latency ASICs. Base station rollouts under the US FCC's spectrum allocation timelines are pulling silicon through foundry queues.
- Automotive Electrification Mandates:The EU Green Deal's vehicle emission targets are forcing powertrain redesigns requiring automotive-qualified ASSPs. Extended temperature-grade certifications from Infineon and NXP are qualifying silicon for under-hood deployment.
- China's Dual Carbon Framework:The MEE's energy-efficiency benchmarks are redirecting domestic foundry investment toward low-power BiCMOS processes. GB standards compliance is becoming a gate for telecom infrastructure silicon access.
Market Restraints
- Advanced Lithography Equipment Controls:Export restrictions on Dutch ASML extreme ultraviolet systems are capping Chinese foundry progression to 7nm and below. SMIC and Hua Hong are stranded at mature nodes for complex programmable logic.
- Substrate Material Cost Volatility:Silicon-on-insulator wafer pricing fluctuates with 300mm raw silicon ingot availability. SOITEC's Bernin facility concentration creates input cost pressure for RF-specialized logic.
- Design Tool Licensing Concentration:Cadence and Synopsys dominate electronic design automation for custom macro cell development. Fabless entrants face seven-figure upfront commitments before first silicon validation.
Strategic Opportunities
- India's Electronics Manufacturing Incentive Scheme:The PLI scheme's semiconductor-specific tier offers 50% capex reimbursement for domestic special purpose logic packaging. Foxconn and Vedanta are evaluating Kolkata and Gujarat for OSAT facilities.
- Space-Qualified Silicon Shortage:Radiation-hardened process nodes at 65nm and above face 18-month lead times. Cobham, BAE Systems, and ISRO's vendors are qualifying alternative foundry sources in Israel and the United States.
- Chiplets and 2.5D Integration:Heterogeneous integration of logic tiles with high-bandwidth memory is compressing board area for military radar systems. The US Department of Defense's trusted foundry program is funding multi-die packaging development.
Industry Challenges
- Analog-Mixed Signal Design Talent Scarcity:BiCMOS process expertise for precision timing circuits concentrates among engineers with 15-plus years of experience. Universities in Taiwan and Germany are the primary pipeline sources.
- Automotive Functional Safety Certification:ISO 26262 ASIL-D qualification for brake-by-wire and steer-by-wire logic requires 24-36 month validation cycles. Tier-1 suppliers are absorbing silicon vendor liability through indemnification clauses.
- Legacy System Integration Friction:Defense primes in the United States and United Kingdom maintain 30-year platform lifecycles. New ASSP introductions must emulate obsolete bipolar logic pinouts and timing characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Special Purpose Logic IC Market |
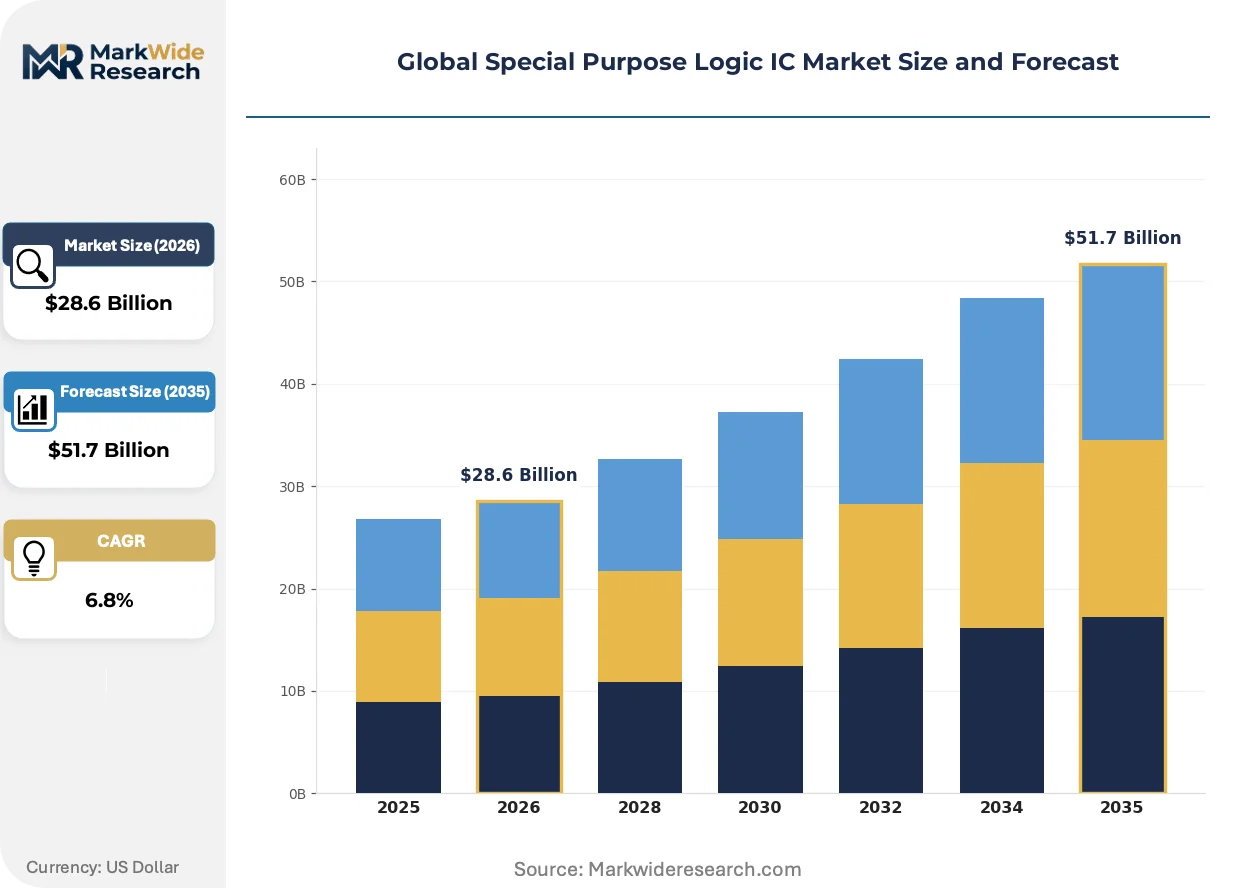
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Application-Specific Standard Products, Gate Arrays, Programmable Logic Devices, Complex Programmable Logic Devices Technology: CMOS, BiCMOS, GaAs, Silicon on Insulator, SOI, Bipolar Application: Consumer Electronics, Telecommunications Equipment, Aerospace Systems, Industrial Controls, Military Electronics End User: Original Equipment Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Contract Manufacturers |
| Companies Covered | Broadcom, STMicroelectronics, Intel Corporation, Microchip Technology, Renesas Electronics Corporation, NXP Semiconductors, Advanced Micro Devices, Infineon Technologies, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Special Purpose Logic IC Market Shifts & Advancements
Silicon photonics integration is dissolving the boundary between electrical signal processing and optical transmission in datacenter interconnects. This convergence is forcing special purpose logic designers to master co-packaged optics assembly.
Gate-all-around transistor architectures are overtaking finFET structures for sub-3nm special purpose logic targeting AI inference accelerators. Samsung Foundry and Intel are prioritizing nanosheet processes for 2025-2026 tapeouts. The shift is compressing power-performance-area tradeoffs for cloud hyperscalers deploying million-unit server fleets.
REACH substance restrictions are eliminating hexavalent chromium from plating processes used in ceramic package lead frames. European automotive Tier-1s are auditing supplier material declarations back to smelter origins. The compliance burden is favoring IDMs with captive packaging operations over fabless competitors reliant on distributed OSAT networks.
Defense procurement offices in the United States and Australia are mandating domestic wafer fabrication for critical program silicon. The US CHIPS Act's national security guardrails are disqualifying Taiwan-fabricated logic from certain radar and electronic warfare contracts. Prime contractors are dual-qualifying parts from GlobalFoundries' Malta facility and Intel's Arizona expansion to maintain program eligibility.
Global Special Purpose Logic IC Market Segmentation
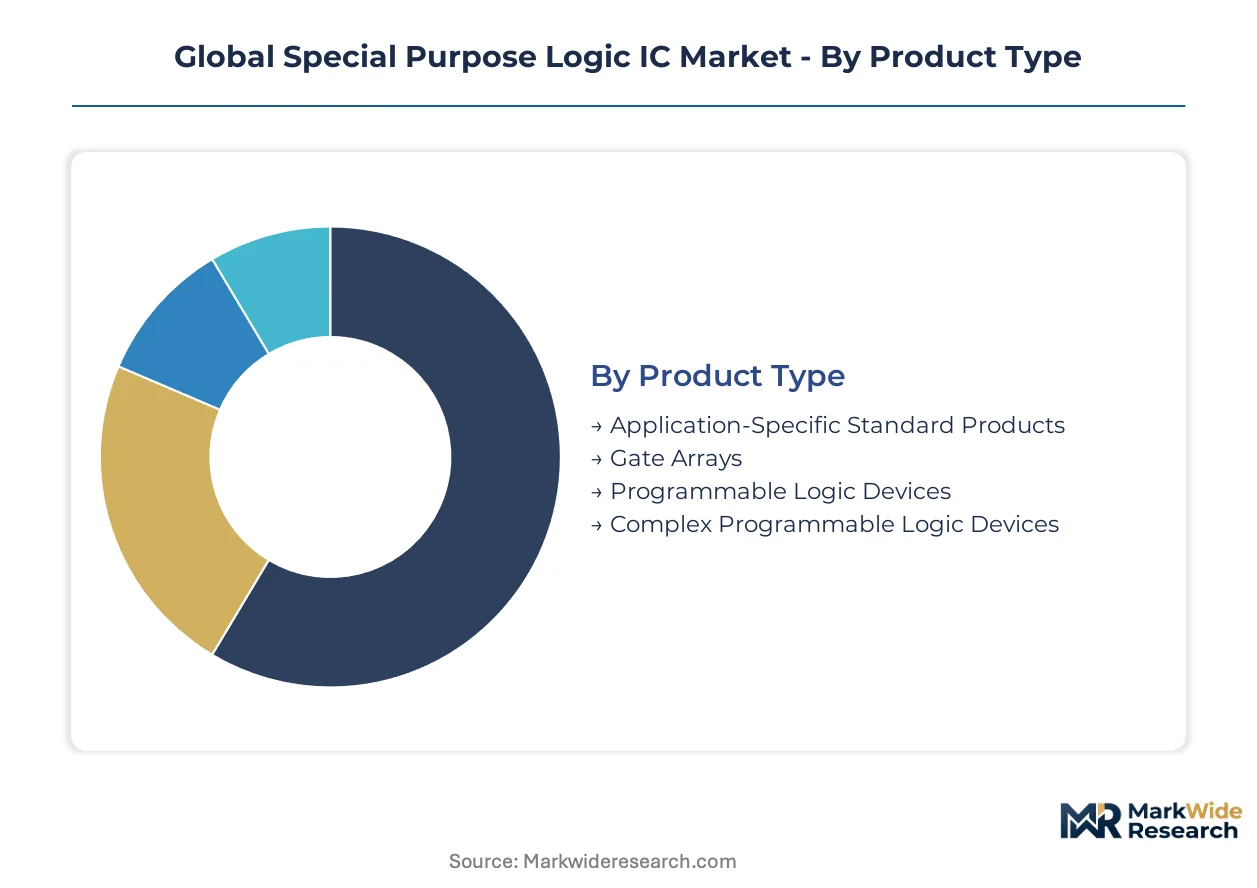
Special purpose logic ICs fragment across four dimensions that reshape procurement priorities. Product type determines whether buyers prioritize unit cost or field reconfigurability. Technology selection locks in power-performance tradeoffs that propagate through system-level thermal design.
Product Type:
Buyers differentiate by the flexibility-cost spectrum they require for their application lifecycle.
- Application-Specific Standard Products:Fixed-function silicon fabricated at high volume for predetermined digital operations. Consumer electronics manufacturers in South Korea and Germany pull ASSPs through foundry queues for smartphone baseband and display timing controllers.
- Complex Programmable Logic Devices:Reconfigurable gate arrays integrating programmable logic blocks with hardened macro cells. Military electronics programs in the United States and Australia mandate CPLDs for radiation-hardened avionics requiring in-field firmware updates.
- Gate Arrays:Semi-custom devices with prefabricated base layers awaiting metal customization. Industrial automation OEMs leverage gate arrays to compress development cycles for motor control systems.
- Programmable Logic Devices:Field-configurable logic enabling rapid prototyping without mask respins. Aerospace systems designers in Israel and the United Kingdom deploy PLDs for satellite payload verification.
Volume sits with Application-Specific Standard Products; growth tilts toward Complex Programmable Logic Devices.
Technology:
Process selection hinges on whether the priority is leakage control, analog precision, or high-frequency switching.
- CMOS:Dominant planar process achieving density scaling through lithography advancement. Datacenter interconnect silicon from Taiwan and Intel facilities exploits CMOS for million-unit server fleet deployments.
- BiCMOS:Heterogeneous integration of bipolar and CMOS transistors for precision mixed-signal circuits. Automotive-qualified timing devices from Infineon and NXP rely on BiCMOS for extended temperature-grade under-hood operation.
- Silicon on Insulator:Dielectric isolation eliminating latch-up and reducing parasitic capacitance. RF-specialized logic for 5G base stations concentrates at SOITEC's Bernin facility and GlobalFoundries' Malta line.
- Bipolar:Legacy junction-isolated process maintaining 30-year platform compatibility. Defense primes in the United States and United Kingdom specify bipolar emulation for obsolete pinout matching in radar retrofits.
- GaAs:III-V compound semiconductor for millimeter-wave and optical conversion stages. Space-qualified transceivers from Cobham and BAE Systems exploit GaAs for radiation tolerance at 65nm-equivalent nodes.
- SOI:Thin-film silicon variant distinct from thick-film SOI for power electronics. The MEE's energy-efficiency benchmarks redirect Chinese domestic foundry investment toward low-power SOI variants.
CMOS captures the widest deployment; BiCMOS gains share fastest in automotive electrification mandates.
Application:
End-use environment dictates certification burden, temperature grade, and supply security tier.
- Telecommunications Equipment:Deterministic-latency silicon for baseband processing and fronthaul aggregation. South Korean and German manufacturers accelerate orders under the US FCC's spectrum allocation timelines.
- Military Electronics:Radiation-hardened and trusted foundry-qualified devices for electronic warfare. The US Department of Defense's trusted foundry program funds domestic wafer fabrication at GlobalFoundries Malta and Intel Arizona.
- Consumer Electronics:Cost-optimized ASSPs for smartphones, tablets, and wearable devices. China's MIIT enforces GB standards compliance as a market access gate for telecom infrastructure silicon.
- Aerospace Systems:Extended temperature-grade and radiation-tolerant logic for satellite and avionics. ISRO's vendors and Israeli foundries are qualifying alternative sources amid Taiwan concentration risks.
- Industrial Controls:Robust interface silicon for factory automation and process instrumentation. Texas Instruments anchors this segment through captive 300mm fabrication in Texas and Utah.
Telecommunications Equipment leads unit volume; Military Electronics commands the steepest expansion trajectory.
End User:
Supply chain position determines whether buyers absorb inventory risk or push it upstream.
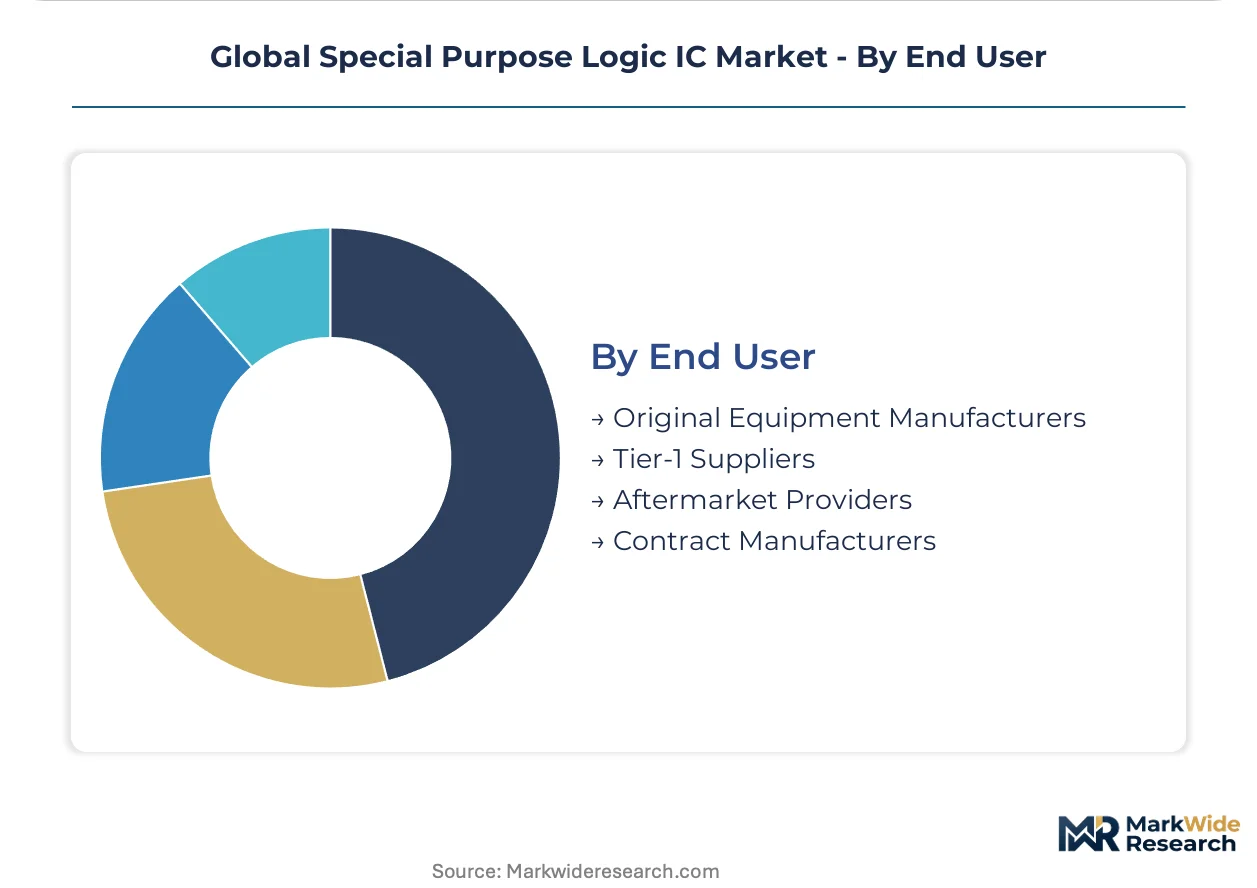
- Original Equipment Manufacturers:Vertically integrated electronics producers specifying silicon for captive system integration. Foxconn and Vedanta evaluate Kolkata and Gujarat OSAT facilities under India's PLI scheme.
- Tier-1 Suppliers:Automotive and aerospace subsystem vendors managing ISO 26262 ASIL-D qualification cycles. These suppliers absorb silicon vendor liability through indemnification clauses for brake-by-wire and steer-by-wire logic.
- Contract Manufacturers:Electronics manufacturing services providers purchasing on consignment or turnkey basis. Multi-source foundry strategies harden among EMS providers seeking supply resilience against geopolitical export controls.
- Aftermarket Providers:Replacement part distributors sourcing legacy bipolar logic for 30-year defense platform sustainment. Obsolete part emulation requirements constrain new ASSP introductions to match vintage pinouts.
Original Equipment Manufacturers dominate procurement volume; Tier-1 Suppliers are expanding their specification authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for special purpose logic ICs concentrates in five national markets where telecommunications infrastructure, automotive electrification, and defense procurement intersect with concentrated foundry capacity.
United States
Defense procurement offices mandate domestic wafer fabrication for radar and electronic warfare silicon under CHIPS Act national security guardrails. The FCC's spectrum allocation timelines pull deterministic-latency ASICs through foundry queues. Prime contractors dual-qualify parts from GlobalFoundries' Malta facility and Intel's Arizona expansion to maintain program eligibility.
China
Domestic foundry investment redirects toward low-power BiCMOS processes under MEE energy-efficiency benchmarks for dual carbon compliance. MIIT enforces GB standards for telecom infrastructure silicon as a market access gate. SMIC and Hua Hong remain stranded at mature nodes for complex programmable logic due to export controls on Dutch lithography equipment.
Germany
Automotive electrification mandates under the EU Green Deal force powertrain redesigns requiring automotive-qualified ASSPs from Infineon and NXP. Extended temperature-grade certifications qualify silicon for under-hood deployment. Industrial automation OEMs in Bavaria leverage gate arrays to compress development cycles for motor control systems.
South Korea
Telecommunications equipment manufacturers accelerate orders for deterministic-latency ASICs as 5G base station rollouts intensify. Samsung Foundry prioritizes nanosheet processes for sub-3nm AI inference accelerators targeting 2025-2026 tapeouts. Seoul-based designers harden multi-source foundry strategies seeking supply resilience.
Israel
Aerospace systems designers deploy programmable logic devices for satellite payload verification requiring in-field reconfigurability. Radiation-hardened process nodes face 18-month lead times, prompting ISRO vendors and Israeli foundries to qualify alternative sources. Cobham and BAE Systems exploit GaAs for space-qualified transceivers at 65nm-equivalent nodes.
Global Special Purpose Logic IC Market Competitive Landscape
Multi-source foundry agreements dominate the current landscape as fabless designers seek supply resilience against geopolitical export controls. The vendor base stratifies across three tiers: integrated device manufacturers with captive fabrication, fabless specialists leveraging Taiwan Semiconductor Manufacturing allocation, and diversified conglomerates with networking and automotive verticals. Strategic archetypes include margin-defended captive designers, automotive-qualified ASSP specialists, and radiation-hardened military suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure advanced node access.
Among diversified semiconductor conglomerates, Broadcom and Intel Corporation exemplify contrasting fabrication strategies—one leveraging captive design flows, the other anchoring domestic expansion. Infineon Technologies occupies a position within the automotive-qualified tier, representing extended temperature-grade specialization. Texas Instruments anchors the industrial logic segment through in-house 300mm fabrication. These three entities collectively illustrate the spectrum from fabless flexibility to captive integration.
| Leading Market Players |
|---|
| Broadcom |
| STMicroelectronics |
| Intel Corporation |
| Microchip Technology |
| Renesas Electronics Corporation |
| NXP Semiconductors |
| Advanced Micro Devices |
| Infineon Technologies |
| Texas Instruments |
| Others |
Supply & Pricing Matrix
300mm silicon ingot spot pricing cascades through foundry wafer costs into tiered ASIC procurement structures, compressing margins for fabless designers while concentrating pricing power among captive-fabrication IDMs.
Pricing Analysis
Volume sits with fixed-function ASSPs at economy tiers; margin pools concentrate in radiation-hardened CPLDs for military programs. Three-tier pricing structure across premium radiation-hardened, standard automotive-qualified, and economy consumer-grade levels separates buyers by certification burden and temperature grade. Pricing pressure stems from substrate material cost volatility as SOITEC's Bernin facility concentration creates input cost spikes for RF-specialized logic. Contract manufacturers exhibit highest price sensitivity due to consignment purchasing models, while defense primes absorb premiums for trusted foundry qualification.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers Shin-Etsu and JSR, tethering advanced node production to Pacific Rim material flows. Extreme ultraviolet lithography equipment draws from Dutch ASML, while 300mm raw silicon ingots feed from South Korean and German polysilicon refiners. Single-source vulnerability concentrates at Taiwan Semiconductor Manufacturing's EUV capacity for sub-7nm special purpose logic. Distribution runs through direct foundry allocation agreements for IDMs, with fabless designers purchasing through quarterly wafer starts contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as gate-all-around transistor architectures displace finFET structures for sub-3nm AI inference accelerators.
For Market Incumbents: Extend radiation-hardened process node roadmaps at GlobalFoundries Malta and Intel Arizona to capture CHIPS Act national security guardrails funding. Deepen captive BiCMOS expertise for automotive electrification mandates as ISO 26262 ASIL-D qualification cycles lengthen to 36 months. Lock in multi-year foundry allocation agreements before export controls tighten further on Dutch lithography equipment. For New Entrants and Emerging Players: Capture India's PLI scheme semiconductor-specific tier offering 50% capex reimbursement for domestic special purpose logic packaging in Kolkata and Gujarat. Target space-qualified silicon shortage segments where 18-month lead times at 65nm radiation-hardened nodes create qualification windows for Israeli and US alternative foundries. Lead with chiplets and 2.5D integration expertise for military radar multi-die packaging programs. For Investors and Strategic Acquirers: Distressed-cycle entries favor automotive-qualified ASSP specialists with extended temperature-grade certifications in Germany and South Korea. Long-term viability centers on 5-10 year electrification and defense procurement windows as EU Green Deal and US CHIPS Act reshape demand. Watch ASML export control enforcement tightness as the inflection signal for Chinese foundry stranded-asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Trusted Foundry Qualification | US Department of Defense funding secures domestic wafer fabrication for radar programs at GlobalFoundries Malta. |
| Multi-Source Foundry Agreements | Fabless designers harden supply resilience against Taiwan concentration risks through Samsung and Intel diversification. |
| Automotive ASIL-D Certification Investment | Infineon and NXP extend qualification cycles to 36 months for brake-by-wire logic liability absorption. |
| Chiplets and 2.5D Integration Development | Heterogeneous logic tiles compress board area for military radar systems under US DoD trusted foundry programs. |
| India OSAT Facility Establishment | Foxconn and Vedanta evaluate Kolkata and Gujarat for 50% PLI scheme capex reimbursement capture. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across foundry operations managers, fabless design house CTOs, automotive Tier 1 procurement leads, and defense prime subsystem engineers. SEC 10-K disclosures, SEMI silicon shipment reports, US Bureau of Industry and Security export control filings, and Taiwan Stock Exchange foundry revenue statements supplied quantitative benchmarks. Bottom-up wafer start tallies reconciled against top-down equipment spending patterns.
Data-stream reconciliation across unit shipment volumes, average selling price trajectories, and foundry capacity utilization rates structured the analytical framework. Segmentation modeling spanned product type, process technology, application vertical, and end-user supply chain position across the projection horizon. CAGRs derived from equipment capex cycles, node migration timelines, and regulatory mandate enforcement schedules. EUV lithography equipment delivery backlogs and automotive platform redesign cadences fed industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Dutch export control enforcement, Taiwan geopolitical stability, and automotive electrification mandate acceleration. Forecasts reflect documented assumptions on node migration pace and foundry capacity expansion timing. ASML equipment licensing restrictions, MEE dual carbon benchmark tightening, and FCC spectrum allocation timeline shifts warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Japan Analog IC Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Touch Controller IC Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
Digital Potentiometer IC Market
IC (Integrated Circuits)
Americas Analog IC Market
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
Ultra Large Scale Ics Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market
IC (Integrated Circuits)
Global Power Management Integrated Circuit (PMIC) Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
NFC Tag Ics Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
Embedded Universal Integrated Circuit Card (eUICC) Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market