
 Global SRAM and ROM Design IP Market | 2026-2036
Global SRAM and ROM Design IP Market Size, Share, and Industry Trends Forecast 2026-2036
Global SRAM and ROM Design IP Market Foresight
Multi-source IP procurement is repositioning how fabless semiconductor companies secure memory compilers across process nodes. Synopsys leverages extensive foundry partnerships to sustain physical verification coverage from 28nm to 3nm. Cadence Design Systems anchors its position through integrated SRAM-PHY co-design tools that dominate high-performance computing sockets. Arm competes by extending architectural licensing into royalty-bearing memory IP cores for IoT endpoints.
SRAM and ROM Design IP encompasses hardened memory macros and synthesizable compiler generators optimized for density, speed, or power tradeoffs at specific lithography nodes; these blocks integrate standard six-transistor bitcells or one-time-programmable antifuse elements to provide non-volatile code storage and volatile data buffering within system-on-chip architectures. Synchronous SRAM commands the largest revenue share among IP types due to its ubiquity in processor cache hierarchies and networking packet buffers, while 5nm and 7nm technology nodes represent the fastest-expanding category as foundries qualify bitcell variants for EUV-based production. Application demand from aerospace systems generates premium pricing because radiation-hardened designs require specialized redundancy and error-correction circuits that standard consumer-grade compilers cannot deliver.
ISO 26262 functional safety standards and IEC 61508 industrial safety frameworks constrain automotive and automation deployments by mandating fault coverage metrics that ROM IP must demonstrate through silicon-proven characterization. Taiwan's NMPA-aligned semiconductor regulations and the EU's CE marking requirements for embedded systems collectively shape market access conditions for memory IP vendors serving medical and automotive end users. Stakeholders must monitor foundry roadmaps for gate-all-around transistor transitions that will force complete bitcell redesigns and invalidate existing physical IP portfolios.
Market Dynamics
Gate-all-around transistor transitions below 3nm are forcing complete bitcell redesigns that invalidate existing physical IP portfolios and compel vendors to rebuild compiler architectures from fundamental device physics.
Growth Catalysts
- Automotive ECU outsourcing:Tier-1 suppliers in Germany and Japan are licensing embedded non-volatile memory IP rather than maintaining captive design teams, accelerating royalty-bearing engagements for antifuse-based ROM compilers.
- ISO 26262 functional safety mandates:Fault coverage metrics required under this automotive standard are creating certified IP demand that standard consumer-grade compilers cannot satisfy, privileging vendors with silicon-proven characterization data.
- EUV lithography qualification:Foundries in Taiwan are qualifying 5nm and 7nm bitcell variants for production, driving custom SRAM compiler engagements from fabless semiconductor companies migrating advanced-node designs.
Market Restraints
- Foundry process concentration:Migration to nodes below 7nm depends on TSMC-led process development in Hsinchu Science Park, creating single-source vulnerability for bitcell qualification timelines and foundry pricing power.
- Specialized input costs:Radiation-hardened SRAM designs for aerospace systems require triple-modular redundancy and error-correction circuits that demand 40-60% additional die area, compressing margins on premium-priced segments.
- Antifuse OTP limitations:One-time-programmable ROM blocks lack post-fabrication reprogrammability, restricting their adoption in over-the-air update architectures that dominate connected vehicle and industrial IoT endpoints.
Strategic Opportunities
- Medical device embedded systems:CE marking requirements under EU MDR and Taiwan's NMPA-aligned semiconductor regulations are creating compliance-driven demand for certified memory IP in implantable and diagnostic equipment.
- High-performance computing sockets:Data center processor designs are integrating SRAM-PHY co-design methodologies that favor vendors offering unified physical and circuit-level optimization tools.
- IoT endpoint architectural licensing:Royalty-bearing memory IP cores are penetrating battery-constrained sensor nodes where area efficiency and sleep-state leakage dominate selection criteria over raw performance.
Industry Challenges
- Physical verification engineer scarcity:Advanced node design rule compliance requires expertise in EUV-aware layout optimization and multi-patterning decomposition that exceeds the supply of experienced practitioners.
- Silicon-proven characterization timelines:ISO 26262 fault coverage demonstration demands exhaustive test chip fabrication and automotive temperature-grade qualification cycles that extend product development schedules.
- Legacy bitcell integration friction:Existing six-transistor SRAM architectures face fundamental redesign requirements for gate-all-around transistor structures, stranding prior IP investments and forcing parallel development tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global SRAM and ROM Design IP Market |
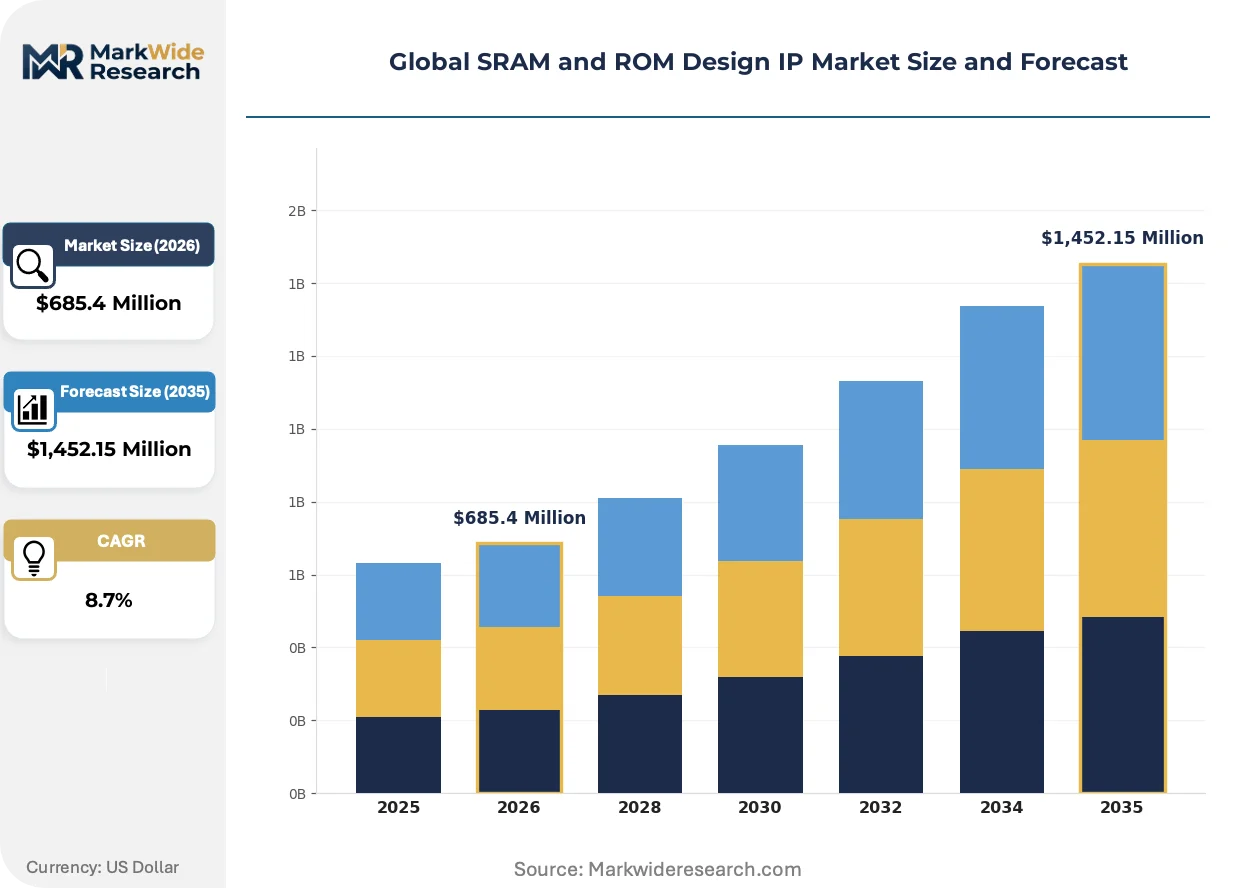
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | IP Type: Asynchronous SRAM, Synchronous SRAM, Mask ROM, Flash ROM, One-Time Programmable ROM Technology Node: 65nm, 40nm, 28nm, 14nm, 7nm, 5nm Application: Consumer Electronics, Networking Equipment, Aerospace Systems, Wearable Devices, Industrial Automation End User: Fabless Semiconductor Companies, Integrated Device Manufacturers, Foundries, Original Design Manufacturers |
| Companies Covered | Rambus, Siemens EDA, Synopsys, Surecore, Dolphin Technology, Cadence Design Systems, eMemory Technology, Memory Forge AI, Arm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global SRAM and ROM Design IP Market Shifts & Advancements
Memory IP vendors are restructuring compiler architectures around process-specific device physics rather than portable cell libraries, compressing the viable vendor base to those with direct foundry partnerships.
Compute-in-memory bitcell arrays are electrifying neural network accelerator designs by embedding multiply-accumulate operations within SRAM subarrays rather than shuttling data to discrete logic. AI processor startups in Israel and the United States are adopting these macros at 5nm to reduce memory wall bottlenecks. This convergence of memory and logic functions is electrifying traditional compiler business models that separated bitcell design from compute architecture.
EU's F-Gas Regulation and REACH chemical restrictions are constraining the etch chemistries and deposition precursors used in antifuse ROM manufacturing, forcing IP vendors to qualify alternative dielectric materials for one-time-programmable elements. Industrial automation OEMs sourcing CE-marked embedded systems are now requiring material compliance documentation that extends upstream to IP-level substance declarations. Memory IP vendors serving European automotive and medical end users are responding by pre-qualifying bitcell stacks against ECHA substance candidate lists.
Multi-source procurement strategies are fragmenting the traditional single-vendor compiler relationship as fabless semiconductor companies qualify second-source IP for supply resilience. Networking equipment manufacturers in North America are now requiring dual-qualified SRAM compilers for 7nm switch fabric designs, replacing sole-source engagements that dominated prior node migrations. This pattern is most visible in Taiwan's Hsinchu corridor where TSMC customers are maintaining parallel Synopsys and Cadence tool flows despite integration overhead.
Global SRAM and ROM Design IP Market Segmentation
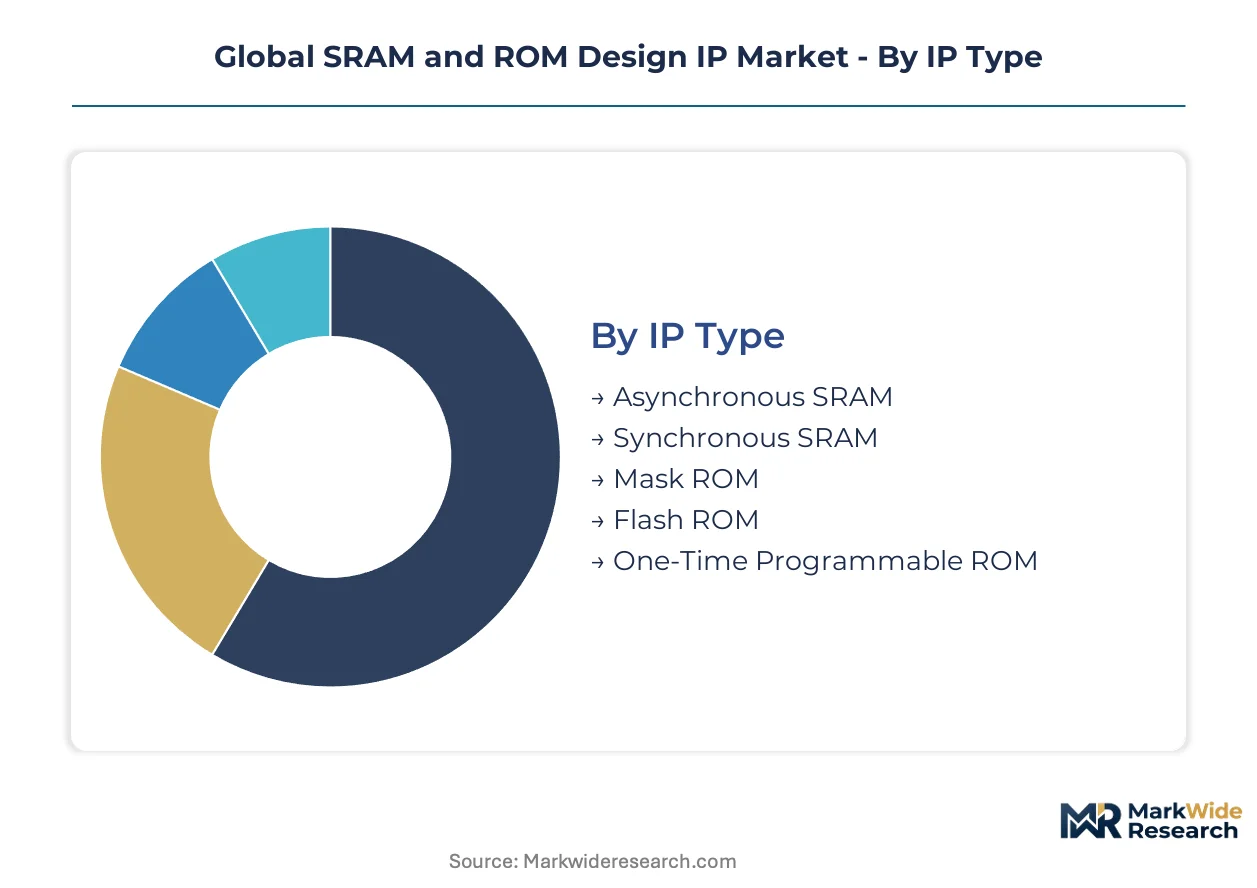
SRAM and ROM Design IP procurement decisions cascade across process node selection, application safety requirements, and foundry qualification timelines. Understanding how these dimensions intersect reveals why automotive and aerospace buyers pay premium pricing for certified compilers while consumer electronics prioritizes density-optimized standard cells.
IP Type:
Compiler replacement cycles accelerate when new process nodes invalidate existing bitcell architectures, forcing licensees to requalify entire memory subsystems.
- Synchronous SRAM:Six-transistor bitcell designs with clocked access protocols dominate processor cache hierarchies and networking packet buffers. Demand concentrates in Taiwan's Hsinchu Science Park where TSMC customers commission custom compilers for 5nm data center processors.
- Asynchronous SRAM:Self-timed bitcell arrays eliminate clock distribution overhead for ultra-low-power IoT endpoints. Battery-constrained sensor nodes in Germany's industrial automation corridor favor these macros for sleep-state leakage reduction.
- One-Time Programmable ROM:Antifuse-based code storage provides tamper-resistant firmware anchoring for automotive ECUs under ISO 26262 mandates.
- Flash ROM:Electrically erasable variants support over-the-air update architectures in connected vehicle platforms.
- Mask ROM:Hard-coded pattern programming delivers lowest unit cost for high-volume consumer electronics with frozen firmware requirements.
Synchronous SRAM sits at the top of the volume ranking, with One-Time Programmable ROM climbing the fastest on automotive safety certification demand.
Technology Node:
Cost tier stratification sharpens as EUV lithography qualification expenses concentrate advanced node access among well-capitalized fabless designers.
- 5nm:Gate-all-around transistor structures at this node demand complete bitcell redesigns from fundamental device physics. AI processor startups in Israel and the United States commission these compilers for compute-in-memory neural network accelerators.
- 7nm:EUV single-patterning qualification enables density-optimized six-transistor variants for high-performance computing sockets. Networking equipment manufacturers in North America require dual-qualified SRAM compilers at this node for supply resilience.
- 14nm:FinFET maturity supports cost-optimized consumer electronics with proven yield baselines.
- 28nm:Mature node demand persists in industrial automation for mixed-signal integration and analog-friendly design rules.
- 40nm:Specialty foundries in Japan maintain these nodes for automotive-grade temperature qualification.
- 65nm:Legacy node support continues for aerospace radiation-hardened designs requiring extensive silicon-proven characterization.
7nm commands the highest revenue concentration, with 5nm gaining share fastest on AI accelerator deployment.
Application:
Customer type diversity fragments procurement patterns as medical device OEMs impose compliance documentation requirements unknown to consumer electronics buyers.
- Aerospace Systems:Radiation-hardened SRAM with triple-modular redundancy and error-correction circuits occupies 40-60% additional die area. CE marking under EU REACH substance restrictions constrains antifuse material selection for European satellite manufacturers.
- Industrial Automation:IEC 61508 safety frameworks mandate fault coverage metrics that privilege vendors with exhaustive test chip data. Germany's KBA-aligned automotive suppliers source certified ROM IP for factory floor controllers.
- Networking Equipment:Data center switch fabrics demand SRAM-PHY co-design methodologies with unified physical and circuit-level optimization.
- Wearable Devices:Taiwan's NMPA-aligned semiconductor regulations shape memory IP selection for health-monitoring endpoints.
- Consumer Electronics:Volume-scale pricing dominates selection criteria for smartphone and tablet SoC integration.
Networking Equipment leads by unit volume, with Aerospace Systems expanding most quickly on premium-priced radiation-hardened requirements.
End User:
Supply concentration dynamics intensify as foundry migration below 7nm tightens design rule compliance under functional safety mandates.
- Fabless Semiconductor Companies:Multi-source IP procurement strategies fragment traditional single-vendor compiler relationships. These designers maintain parallel tool flows from Synopsys and Cadence despite integration overhead.
- Foundries:TSMC-led process development in Taiwan's Hsinchu Science Park creates single-source vulnerability for bitcell qualification timelines.
- Integrated Device Manufacturers:Captive fabrication facilities in Japan and the United States preserve internal memory design teams for proprietary differentiation.
- Original Design Manufacturers:Electronics manufacturing services in China qualify standard cell libraries for white-label device production.
Fabless Semiconductor Companies anchor procurement volume, with Foundries gaining strategic leverage fastest on advanced node access control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping memory IP procurement as automotive safety certification costs in Europe and Japan push non-critical compiler development toward Taiwan's streamlined foundry qualification pathways. Cost-of-compliance gaps between jurisdictions now determine where fabless designers stage their advanced-node tape-outs.
United States
AI processor startups in Silicon Valley and Austin are commissioning 5nm compute-in-memory compilers for neural network accelerators. NHTSA automotive safety guidelines and FCC equipment authorization requirements constrain antifuse ROM deployment in connected vehicle platforms. Design activity concentrates in California's Santa Clara County, where venture-backed semiconductor firms maintain parallel tool flows from multiple EDA vendors.
Taiwan
TSMC-led process development in Hsinchu Science Park drives custom SRAM compiler engagements for data center processors and networking switch fabrics. NMPA-aligned semiconductor regulations shape medical device memory IP qualification for export-bound diagnostic equipment. The Hsinchu-Taichung corridor anchors global bitcell characterization capacity, with foundry customers qualifying EUV-based production at 5nm and 3nm nodes.
Germany
Tier-1 automotive suppliers in Stuttgart and Munich are licensing embedded non-volatile memory IP rather than maintaining captive design teams under KBA-aligned supplier mandates. EU REACH substance restrictions and CE marking requirements constrain antifuse material selection for European satellite and medical device manufacturers. The Baden-Württemberg automation corridor favors asynchronous SRAM macros for industrial controller sleep-state leakage reduction.
Japan
Integrated device manufacturers in Tokyo and Osaka preserve internal memory design teams for proprietary automotive microcontroller differentiation. METI industrial standards and PMDA medical device regulations impose documentation requirements that extend upstream to IP-level substance declarations. Specialty foundries in Kyushu maintain 40nm nodes for automotive-grade temperature qualification of radiation-tolerant bitcell variants.
Israel
AI accelerator startups in Tel Aviv and Haifa are adopting compute-in-memory bitcell arrays at 5nm to reduce memory wall bottlenecks in neural network inference engines. The country's national cybersecurity regulator imposes tamper-resistance standards that favor antifuse-based ROM for defense and critical infrastructure applications. The Tel Aviv metropolitan cluster has emerged as a design hub for memory-compute convergence architectures.
Global SRAM and ROM Design IP Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized safety certification and compute-in-memory integration. The vendor base stratifies across three maturity levels: full-suite EDA platforms with foundry partnerships, boutique compiler specialists focused on low-power or radiation-hardened variants, and AI-native entrants embedding multiply-accumulate operations within SRAM subarrays. Consolidation pressure intensifies as gate-all-around transitions below 3nm force complete bitcell redesigns. Dominant competitive moves include strategic foundry partnerships for advanced-node access and portfolio diversification into safety-certified IP segments.
Among full-suite EDA vendors, Synopsys, Cadence Design Systems, and Siemens EDA exemplify the established tier through their extensive foundry partnerships and physical verification coverage spanning 28nm to 3nm. These companies occupy positions that privilege silicon-proven characterization data and integrated SRAM-PHY co-design methodologies. Boutique specialists such as Surecore and Dolphin Technology represent the low-power optimization archetype, while Rambus anchors the high-performance memory interface segment. Arm exemplifies architectural licensing extension into royalty-bearing memory IP cores for IoT endpoints.
| Leading Market Players |
|---|
| Rambus |
| Siemens EDA |
| Synopsys |
| Surecore |
| Dolphin Technology |
| Cadence Design Systems |
| eMemory Technology |
| Memory Forge AI |
| Arm |
| Others |
Supply & Pricing Matrix
Multi-source IP procurement mandates from networking equipment manufacturers are compressing compiler pricing power as fabless designers demand dual-qualified SRAM at 7nm, forcing vendors to absorb requalification costs or concede margin.
Pricing Analysis
Input-cost pass-through from EUV mask sets and specialized characterization wafers anchors premium tiering for 5nm and 3nm compilers. Pricing stratifies across automotive safety-certified, high-performance computing, and consumer-grade tiers, with ISO 26262 fault coverage documentation commanding substantial premiums. Cost compression in mature nodes is intensifying as 28nm and 40nm libraries commoditize. Consumer electronics SoC teams exhibit highest price sensitivity, while aerospace prime contractors accept steep premiums for radiation-hardened redundancy.
Supply Chain Analysis
Single-source vulnerability sits with TSMC's Hsinchu Science Park cluster for bitcell qualification below 7nm, where gate-all-around transistor transitions demand complete physical IP rebuilds. Taiwan, South Korea, and the United States anchor wafer fabrication and EDA tool development. Supply chain risk centers on EUV scanner allocation constraints and foundry pricing power. Distribution runs through direct foundry partnerships and EDA platform bundling rather than discrete IP marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play where automotive safety certification costs in Germany under KBA-aligned supplier mandates push non-critical compiler development toward Taiwan's streamlined NMPA-aligned qualification pathways.
For Market Incumbents: Anticipate gate-all-around transitions below 3nm to strand legacy six-transistor bitcell investments and accelerate consolidation. Defensive moves center on deepening foundry partnerships for early EUV process access and pre-qualifying safety-certified IP portfolios against ECHA substance restrictions. Certification investment in IEC 61508 and ISO 26262 documentation represents the critical lever against boutique specialists. For New Entrants and Emerging Players: Capture white-space in compute-in-memory compiler architectures for AI accelerators, where Israel-based neural network startups demand SRAM-PHY co-design integration absent from established EDA bundles. The most penetrable segment sits with 5nm AI processor designs seeking multiply-accumulate embedding within bitcell subarrays. Go-to-market leverage rests on direct engagement with venture-backed semiconductor firms in Silicon Valley and Tel Aviv rather than incumbent channel structures. For Investors and Strategic Acquirers: Asymmetric upside sits with boutique compiler specialists holding radiation-hardened or ultra-low-power IP portfolios that full-suite EDA vendors cannot replicate without architectural overhaul. Long-term viability favors vendors with silicon-proven characterization data spanning multiple foundry nodes. The signal to watch is TSMC's gate-all-around roadmap disclosures, which will force bitcell redesigns and create acquisition windows for distressed IP portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Deepening | Early EUV process access at 3nm secures compiler qualification timelines against TSMC's allocation constraints. |
| Safety Certification Pre-Qualification | ISO 26262 and IEC 61508 documentation investment opens automotive ECU licensing under KBA-aligned mandates. |
| Compute-in-Memory Integration | Embedding multiply-accumulate operations within SRAM subarrays captures AI accelerator demand from Israel and US startups. |
| Material Compliance Documentation | ECHA substance pre-qualification satisfies EU REACH and F-Gas Regulation requirements for European medical and satellite manufacturers. |
| Multi-Source Tool Flow Support | Parallel Synopsys and Cadence compatibility addresses networking equipment manufacturer dual-qualification requirements. |
Research Methodology
Direct dialogue with EDA platform product managers, fabless semiconductor physical design leads, foundry IP ecosystem directors, and automotive Tier 1 supplier procurement officers grounded qualitative assessment. Secondary validation drew from SEC 10-K filings of publicly traded EDA vendors, TSMC technology symposium disclosures, ISO 26262 certification registries, and EU ECHA substance candidate lists. Bottom-up project tracking across 5nm and 7nm tape-outs triangulated against top-down EDA revenue segmentation.
Segmentation outputs across IP type, technology node, application, and end-user categories were modeled over the projection horizon. CAGRs were derived from node migration velocity, automotive safety mandate adoption curves, and AI accelerator deployment rates. Industry-specific inputs included EUV lithography qualification timelines, ISO 26262 fault coverage demonstration cycles, and gate-all-around transistor transition roadmaps.
Foundry process delays, automotive safety standard revisions, and gate-all-around bitcell redesign failures are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about TSMC's technology roadmap and regulatory enforcement continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Lithium Battery Charger Ics Market
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
Global Power Management Integrated Circuit (PMIC) Market
IC (Integrated Circuits)
Digital Audio IC Market
IC (Integrated Circuits)
Automotive IC Market
IC (Integrated Circuits)
Semiconductor Integrated Circuit Chip Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
Integrated CMOS Tri-Gate Transistor Market
IC (Integrated Circuits)
NFC Tag Ics Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
Motor Control IC Market
IC (Integrated Circuits)
Europe Analog IC Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
China Integrated Circuit (IC) Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market