
 Isolated Interface Chip Market | 2026-2036
Isolated Interface Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Isolated Interface Chip Market Insights
The EU Green Deal is rebalancing procurement priorities across European industrial automation, compelling OEMs to specify reinforced isolation in motor drives and inverters. Texas Instruments leverages its capacitive isolation portfolio to sustain design wins across factory automation controllers. Analog Devices anchors high-reliability medical imaging segments with magnetic coupling architectures. Infineon Technologies dominates automotive-qualified isolated gate drivers for traction inverters and onboard chargers.
An isolated interface chip electrically separates two circuit domains while transmitting signals across a dielectric barrier, typically achieving isolation ratings from 2.5 kVrms to 5 kVrms through capacitive, magnetic, or optical coupling techniques; its core purpose is to protect sensitive control electronics from high-voltage transients in industrial, automotive, and medical systems. Digital isolators lead volume shipments due to proliferation of SPI and I2C bus protection in factory PLCs, while isolated gate drivers command premium margins from silicon carbide power module pairings in EV inverters. Capacitive coupling technologies extend reach fastest as manufacturers push data rates beyond 150 Mbps for precision motion control.
EU REACH restrictions on hazardous substances and the EU AI Act's safety-critical system classifications are tightening material and traceability standards for isolation components deployed in medical and autonomous applications. FDA 21 CFR Part 820 quality system regulations and IEC 60601-1 medical safety standards shape product validation cycles for US and European device manufacturers. Stakeholders must monitor how emerging wide-bandgap semiconductor pairings redefine isolation voltage and propagation delay specifications before committing to next-generation platform designs.
Market Dynamics
Silicon carbide power module adoption in electric vehicle traction inverters is forcing fundamental redesigns of isolation architectures, compressing propagation delay requirements while pushing voltage ratings toward 5 kVrms thresholds. This semiconductor-material transition is reshaping procurement specifications across automotive and industrial verticals simultaneously.
Growth Catalysts
- EU Green Deal industrial emissions mandates:Factory automation OEMs in Germany and France must specify reinforced isolation in motor drives and servo controllers, accelerating replacement cycles for legacy optocoupler designs.
- 800V EV powertrain architectures:Traction inverter and onboard charger designs require automotive-qualified isolated gate drivers capable of switching silicon carbide MOSFETs at frequencies above 100 kHz.
- Medical imaging equipment upgrade cycles:IEC 60601-1 compliance requirements for patient safety isolation are driving magnetic coupling adoption in CT and MRI system designs across US and European hospitals.
Market Restraints
- Specialized foundry capacity concentration:Capacitive isolation manufacturing requires dielectric deposition equipment concentrated in Taiwan and South Korea, creating single-source vulnerability for high-voltage barrier layers.
- Raw material cost volatility:Polyimide and silicon dioxide substrates face pricing pressure from semiconductor packaging demand, squeezing margins for mid-tier digital isolator suppliers.
- Optocoupler substitution inertia:Industrial maintenance teams in legacy factory floors resist magnetic and capacitive isolation retrofits due to familiarity with optical coupling failure modes and replacement procedures.
Strategic Opportunities
- India automotive semiconductor localization:PLI scheme incentives for EV component manufacturing are attracting isolated gate driver design centers to Bangalore and Pune industrial corridors.
- Wide-bandgap semiconductor convergence:Pairing gallium nitride power stages with sub-10 ns propagation delay isolators enables compact server power supply designs for hyperscale data centers.
- EU AI Act safety-critical classifications:Autonomous vehicle and surgical robotics applications face mandatory isolation redundancy requirements, creating certified-component premiums for dual-channel architectures.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-D qualification for automotive isolated gate drivers requires 18-24 month validation cycles, delaying revenue recognition for new product families.
- Legacy fieldbus protocol fragmentation:Factory automation customers demand isolation compatibility across Profibus, DeviceNet, and EtherCAT physical layers, forcing redundant SKU proliferation.
- Electromagnetic interference design complexity:High-speed digital isolators in precision motion control systems require shielding expertise scarce among regional system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isolated Interface Chip Market |
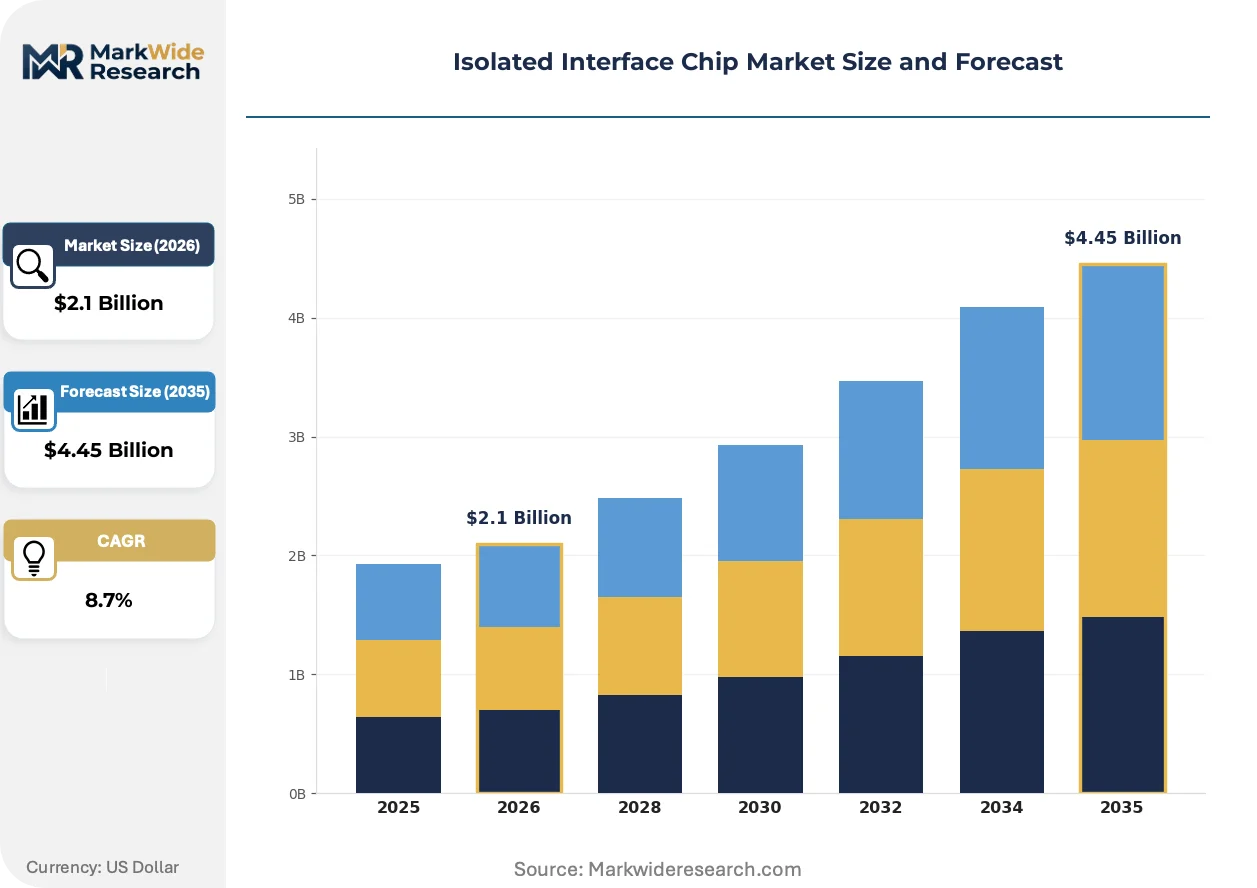
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Isolators, Analog Isolators, Isolated Gate Drivers, Isolated Transceivers Application: Industrial Automation, Medical Devices, Telecommunications, Consumer Electronics Technology: Capacitive Coupling, Magnetic Coupling, Optical Coupling, Radio Frequency End User: OEMs, System Integrators, Repair Services, Research Institutions |
| Companies Covered | Texas Instruments, Analog Devices, Infineon Technologies, NXP Semiconductors, Renesas Electronics, STMicroelectronics, Broadcom, Microchip Technology, Silicon Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isolated Interface Chip Market Trends and Innovations
Isolation technology is fragmenting across coupling methodologies as application-specific performance requirements harden. Manufacturers are abandoning universal-platform strategies in favor of architecture-optimized designs.
Capacitive digital isolators with integrated DC-DC converters are modularizing power delivery and signal transmission into single-package solutions. Industrial PLC manufacturers in Germany are adopting these consolidated modules for space-constrained I/O cards. This integration is compressing bill-of-materials complexity while elevating barrier voltage ratings above 3 kVrms in factory floor deployments.
EU REACH restrictions on hazardous substances are prohibiting certain epoxy formulations traditionally used in optocoupler encapsulation. Medical device manufacturers face material requalification costs for existing isolation barrier designs. The MDR compliance timeline is accelerating magnetic coupling adoption in patient-connected equipment across European hospital procurement channels.
Buyer concentration among tier-one automotive suppliers is forcing component vendors into direct engineering partnerships rather than distribution-mediated sales. Isolated gate driver specifications for EV platforms are now co-developed with semiconductor module suppliers before public release. This collaboration pattern is most visible in Stuttgart and Munich automotive engineering centers, where traction inverter design teams embed isolation requirements into silicon carbide module datasheets.
Isolated Interface Chip Market Segmentation
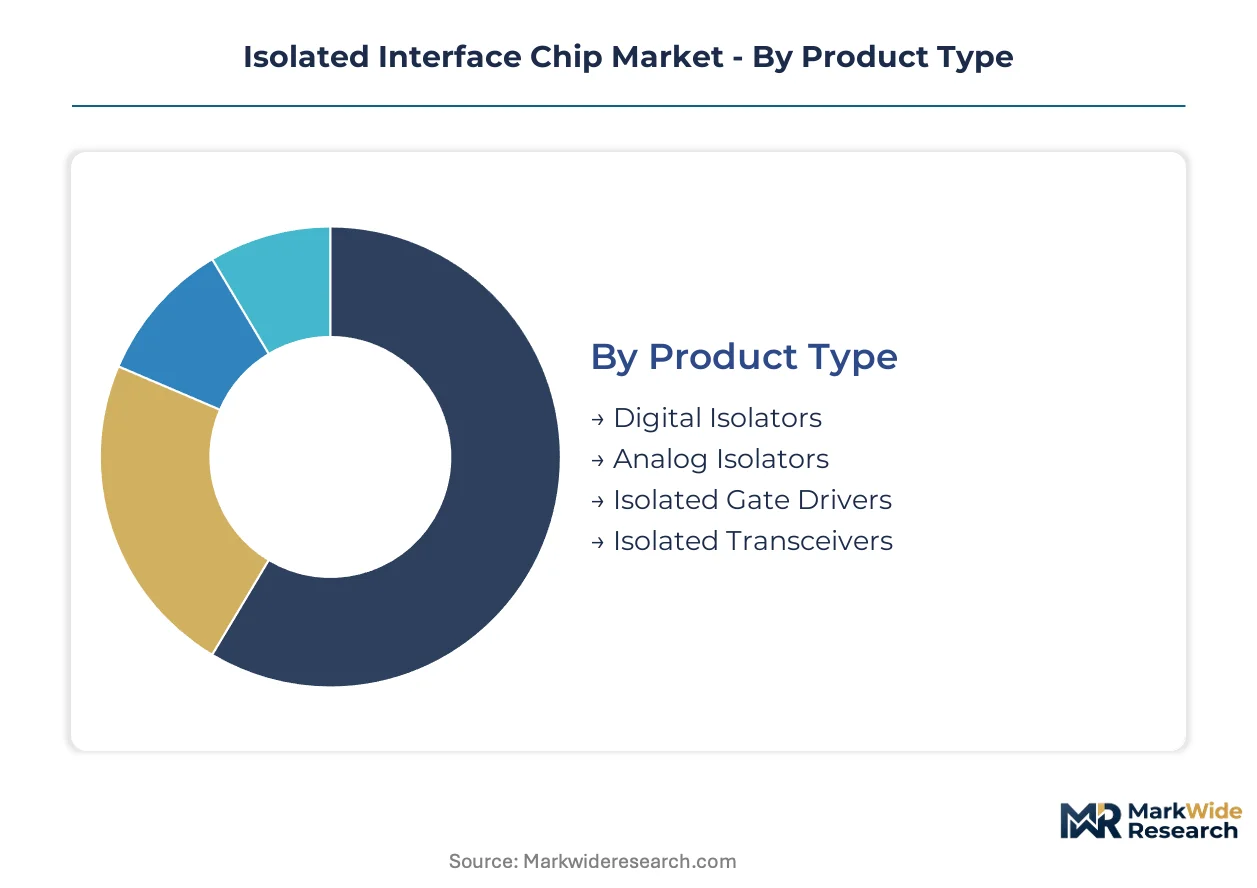
Isolated interface chip procurement varies sharply by coupling methodology and voltage rating, with automotive and industrial buyers demanding distinct propagation delay specifications. Segment boundaries are hardening as manufacturers abandon universal-platform strategies for architecture-specific designs.
Product Type:
Capital intensity concentrates in isolated gate drivers, where automotive qualification cycles and silicon carbide compatibility testing demand substantial upfront investment.
- Digital Isolators:These chips protect SPI, I2C, and UART buses using capacitive or magnetic coupling, achieving data rates above 150 Mbps. Factory automation OEMs in Germany specify these for PLC I/O cards, driven by EU Green Deal emissions mandates requiring reinforced isolation in motor drives.
- Isolated Gate Drivers:Purpose-built for power MOSFET and IGBT switching, these devices integrate undervoltage lockout and desaturation detection. EV traction inverter designs in Stuttgart and Munich engineering centers co-develop these specifications with silicon carbide module suppliers.
- Analog Isolators:Precision signal conditioning for industrial process control.
- Isolated Transceivers:CAN, LIN, and RS-485 physical layer protection for automotive networks.
Isolated gate drivers absorb the bulk of installed capacity; digital isolators are expanding most quickly.
Application:
Medical device applications command premium pricing due to IEC 60601-1 compliance burdens and patient safety liability exposure.
- Industrial Automation:Motor drives, servo controllers, and PLC systems deploy reinforced isolation to withstand factory floor voltage transients. German automotive semiconductor corridors source these for robotic welding and assembly line equipment.
- Medical Devices:CT scanners, MRI systems, and patient monitors require 2.5-5 kVrms isolation ratings with fail-safe outputs. US hospital procurement channels favor magnetic coupling architectures under FDA 21 CFR Part 820 quality system oversight.
- Telecommunications:Base station power supplies and network interface cards.
- Consumer Electronics:Smart home devices and appliance motor controls.
Industrial automation dominates current shipment volumes; medical devices command the steepest expansion trajectory.
Technology:
Coupling methodology selection determines foundry equipment requirements and barrier material supply chains.
- Capacitive Coupling:Silicon dioxide dielectric barriers enable sub-10 ns propagation delays and integrated DC-DC conversion. Taiwan and South Korea foundries concentrate capacity for high-voltage dielectric deposition.
- Magnetic Coupling:Transformer-based architectures achieve high common-mode transient immunity without LED degradation. Analog Devices anchors medical imaging segments with these designs.
- Optical Coupling:Legacy LED-photodiode architectures face EU REACH restrictions on epoxy encapsulants.
- Radio Frequency:Emerging wireless isolation for extreme voltage differentials.
Capacitive coupling captures the largest design win pipeline; magnetic coupling is gaining share fastest in safety-critical applications.
End User:
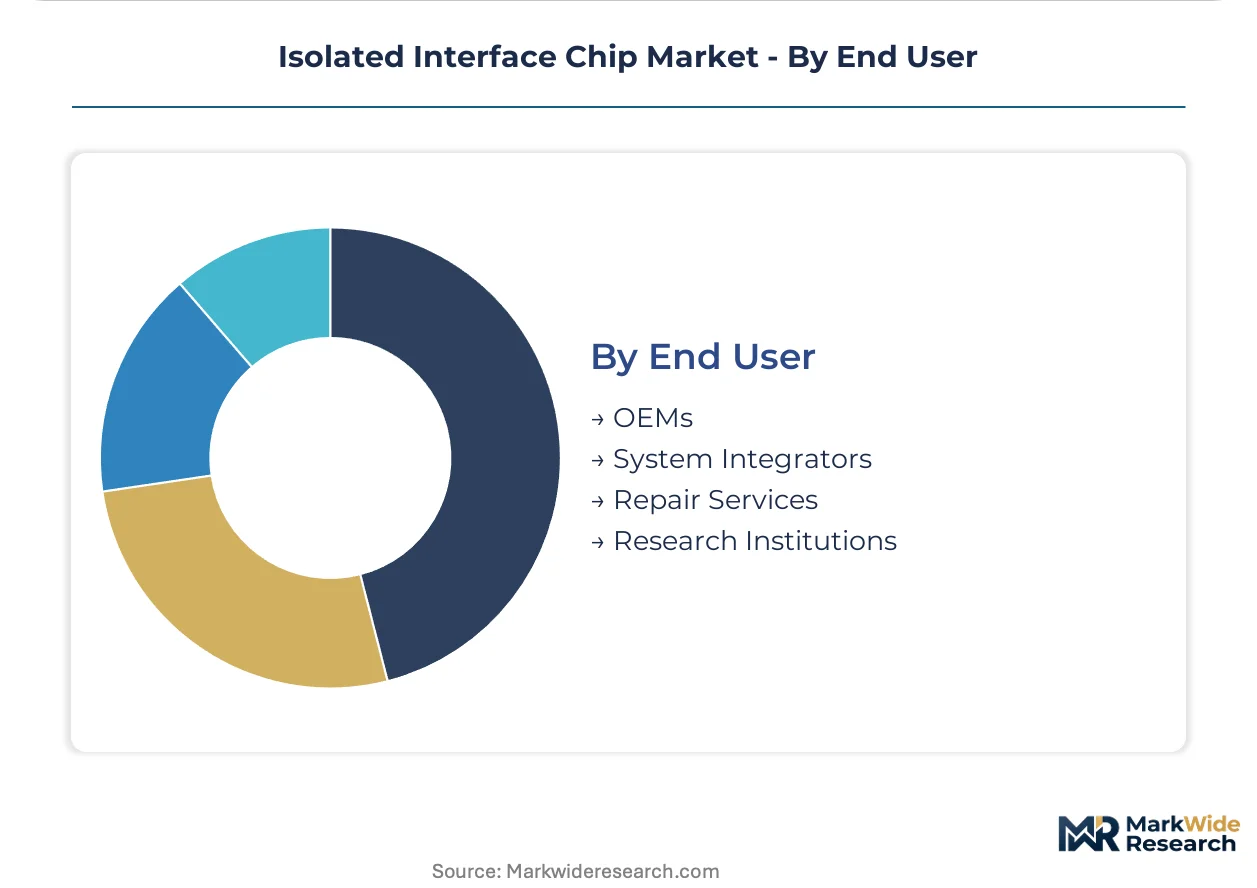
OEMs drive specification authority, though system integrators mediate adoption in fragmented industrial maintenance channels.
- OEMs:Tier-one automotive suppliers and industrial equipment manufacturers define isolation requirements upstream. Direct engineering partnerships with component vendors now precede public datasheet release.
- System Integrators:Regional automation specialists specify retrofit isolators for legacy factory floors. Maintenance team familiarity with optocoupler failure modes slows magnetic and capacitive substitution.
- Repair Services:Aftermarket replacement demand for industrial fieldbus networks.
- Research Institutions:Wide-bandgap semiconductor pairing studies and next-generation barrier characterization.
OEMs concentrate procurement value; system integrators represent the most contested channel for share gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors automotive semiconductor demand for isolated interface chips, where traction inverter engineering teams co-develop gate driver specifications with silicon carbide module suppliers before public release.
Germany
Factory automation OEMs in Munich and Stuttgart specify reinforced isolation in motor drives and servo controllers under EU Green Deal industrial emissions mandates. The KBA enforces automotive qualification standards for traction inverter components. Bavaria's automotive semiconductor corridor concentrates design partnerships between tier-one suppliers and component vendors.
United States
FDA 21 CFR Part 820 quality system regulations shape magnetic coupling adoption in CT and MRI equipment across US hospital procurement channels. The FDA oversees medical device isolation validation cycles for patient safety compliance. Greater Boston's medical imaging cluster drives precision isolation specifications for next-generation diagnostic systems.
China
MIIT industrial automation standards accelerate digital isolator deployment in factory PLCs for precision motion control applications. The NMPA regulates medical device isolation barriers under converging safety frameworks. Yangtze River Delta manufacturing zones concentrate capacitive isolation foundry capacity for high-voltage dielectric deposition.
India
PLI scheme incentives attract isolated gate driver design centers to Bangalore and Pune industrial corridors for EV component localization. The CEA mandates reinforced isolation standards for grid-connected industrial equipment. Karnataka's electronics manufacturing clusters host expanding semiconductor packaging operations for automotive qualification.
South Korea
Silicon dioxide dielectric deposition equipment concentrates in South Korean foundries serving capacitive isolation data rates above 150 Mbps. The MFDS regulates medical device isolation under harmonized IEC standards. Seoul Capital Area semiconductor fabrication facilities supply high-voltage barrier layers for precision motion control systems.
Isolated Interface Chip Market Competitive Landscape
Premium-margin players sit above commodity-margin players across automotive qualification and medical certification vectors, with tiered pricing separating ASIL-D qualified gate drivers from standard digital isolators. The vendor base clusters around three strategic archetypes: diversified semiconductor conglomerates with captive isolation portfolios, specialized analog and mixed-signal houses with magnetic coupling expertise, and fabless designers outsourcing high-voltage barrier fabrication. Dominant competitive moves include direct engineering partnerships with tier-one automotive suppliers and vertical integration into silicon carbide module co-development programs.
Within the diversified semiconductor tier, Texas Instruments, Analog Devices, and Infineon Technologies exemplify distinct coupling methodology specializations. Texas Instruments occupies a position representing capacitive isolation portfolios for factory automation controllers. Analog Devices anchors magnetic coupling architectures for medical imaging segments under FDA and EMA regulatory frameworks. Infineon Technologies sits within the automotive-qualified gate driver segment for traction inverter applications. These three entities represent the archetype spectrum from broad industrial coverage to automotive-specific qualification depth.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| Infineon Technologies |
| NXP Semiconductors |
| Renesas Electronics |
| STMicroelectronics |
| Broadcom |
| Microchip Technology |
| Silicon Labs |
| Others |
Pricing and Supply Chain Analysis
Specialized analog and mixed-signal houses backed by private-equity rollups dominate mid-tier digital isolator supply, concentrating pricing power among three foundry-dependent players while compressing margins through captive wafer allocation discipline.
Pricing Analysis
Value-based pricing anchored to system uptime guarantees separates automotive-qualified isolated gate drivers from standard industrial digital isolators. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 26262 ASIL certification grade and propagation delay performance. Cost compression in mid-tier digital isolators is intensifying because polyimide substrate pricing pressure from advanced packaging demand squeezes barrier material margins. Tier-one automotive OEMs exhibit the lowest price sensitivity due to co-development partnership lock-in, while regional system integrators in fragmented industrial maintenance channels drive the hardest unit-cost negotiations.
Supply Chain Analysis
Dual-sourcing requirements for high-voltage dielectric deposition equipment mandate multi-supplier qualification among Taiwan, South Korea, and emerging Yangtze River Delta packaging hubs. Capacitive isolation manufacturing draws from silicon dioxide substrates, polyimide barrier layers, and automotive-grade copper leadframes. Single-source vulnerability concentrates in Taiwan foundry capacity for sub-10 ns propagation delay devices. Distribution runs through direct engineering partnerships with tier-one automotive suppliers rather than traditional component distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around automotive qualification depth and medical certification barriers, with ISO 26262 validation timelines forcing weaker fabless designers toward distressed exits.
For Market Incumbents: Deploy silicon carbide module co-development programs to lock in gate driver specification authority before public datasheet release. Tier-one automotive suppliers in Stuttgart and Munich engineering centers now embed isolation requirements directly into traction inverter platforms, threatening marginal players lacking direct OEM access. Backward integration into high-voltage dielectric deposition capacity secures barrier layer supply against Taiwan foundry concentration risk.
For New Entrants and Emerging Players: The EU AI Act's safety-critical system classifications in Europe opens a window for dual-channel isolation architectures in autonomous vehicle and surgical robotics applications. White-space concentrates in certified-component premiums for redundant magnetic coupling designs where Analog Devices lacks dedicated product lines. Target India's PLI scheme incentives through Bangalore design center partnerships with local EV powertrain developers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless designers with existing ISO 13485 medical quality systems in Greater Boston and Bavaria geographies. Long-term viability hinges on captive foundry relationships or guaranteed capacity agreements with Taiwan and South Korean barrier deposition specialists. The signal to watch is silicon carbide power module vendor consolidation, which would collapse gate driver specification authority into fewer co-development slots.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Co-Development | Locks in gate driver specifications with Infineon and STMicroelectronics traction inverter platforms. |
| Dual-Channel Redundancy Certification | Captures EU AI Act safety-critical premiums in autonomous vehicle applications. |
| India Design Center Localization | Positions for PLI scheme EV component manufacturing incentives in Karnataka. |
| Magnetic Coupling Medical Platform | Targets FDA 21 CFR Part 820 validation cycles for CT and MRI system upgrades. |
| Capacitive Isolation Foundry Partnership | Secures Taiwan and South Korean dielectric deposition capacity against single-source risk. |
Research Methodology
Multi-period observation of silicon carbide power module adoption rates, EU Green Deal industrial emissions compliance timelines, and FDA medical device isolation validation cycles anchored the trend analysis, supplemented by interviews with tier-one automotive supplier procurement directors, industrial PLC platform engineers, hospital biomedical equipment managers, and semiconductor foundry operations leads. Secondary validation drew from SEC 10-K semiconductor segment disclosures, KBA automotive qualification registries, IEC 60601-1 medical safety standard updates, and MIIT industrial automation equipment certifications. Bottom-up shipment modeling across coupling methodologies and voltage ratings triangulated against top-down OEM procurement spend estimates.
Input-output matrices mapped unit demand by application segment against foundry capacity utilization and barrier material supply constraints across the projection horizon. Segmentation dimensions included coupling technology, isolation voltage rating, propagation delay tier, certification level, and regional regulatory cluster. CAGRs derived from weighted average of historical adoption curve fitting and technology substitution elasticity modeling. Forecast inputs incorporated wide-bandgap semiconductor penetration assumptions and EU REACH material restriction implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for capacitive coupling with integrated DC-DC conversion would alter the outlook if magnetic coupling achieves breakthrough propagation delay performance. Deviation in Taiwan foundry capacity allocation or South Korean equipment export controls would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
NFC Reader Ics Market
IC (Integrated Circuits)
South Korea Analog Integrated Circuits Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
United States Integrated Circuits Market
IC (Integrated Circuits)
Global Application Specific Consumer Analog Integrated Circuit Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
Motor Driver IC Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
APAC Analog IC Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market