
 Americas Microcontroller (MCU) Market | 2026-2036
Americas Microcontroller (MCU) Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Microcontroller (MCU) Market Insights
Shortage of analog mixed-signal design engineers is collapsing foundry expansion timelines across the Americas. Texas Instruments Incorporated sustains captive wafer capacity in Sherman, Texas, insulating its automotive MCU lines from external foundry queues. Microchip Technology Inc. specializes in 8-bit and 16-bit portfolios for industrial automation clients throughout the Midwest and Southeast United States. NXP Semiconductors N.V. dominates Arm Cortex-M supply to Mexican tier-one automotive suppliers near the U.S. border.
An Americas microcontroller is a self-contained system-on-chip integrating a processor core, volatile and non-volatile memory, and programmable peripheral interfaces onto a single die, typically fabricated at process nodes between 40nm and 90nm for cost-sensitive applications. The device executes real-time control tasks in embedded systems where deterministic response and minimal external component count determine design viability. Automotive and IoT Devices end-user segments command the deepest margin pools as firmware security requirements and functional safety certification escalate unit pricing. Mixed Signal technology variants are displacing discrete analog front-end designs in medical and wearable applications, concentrating value capture among suppliers with in-house converter IP.
The U.S. CHIPS and Science Act directs Department of Commerce funding toward onshore MCU fabrication, while FCC Part 15 emissions rules constrain radio-integrated microcontroller architectures for IoT Devices. FDA 21 CFR Part 820 quality system regulations govern Medical Devices applications, forcing suppliers to maintain validated manufacturing records across each lot shipped to U.S. healthcare OEMs. Stakeholders must weigh the fixed cost of dual-source qualification against single-foundry concentration risk as domestic capacity ramps in Arizona and Texas.
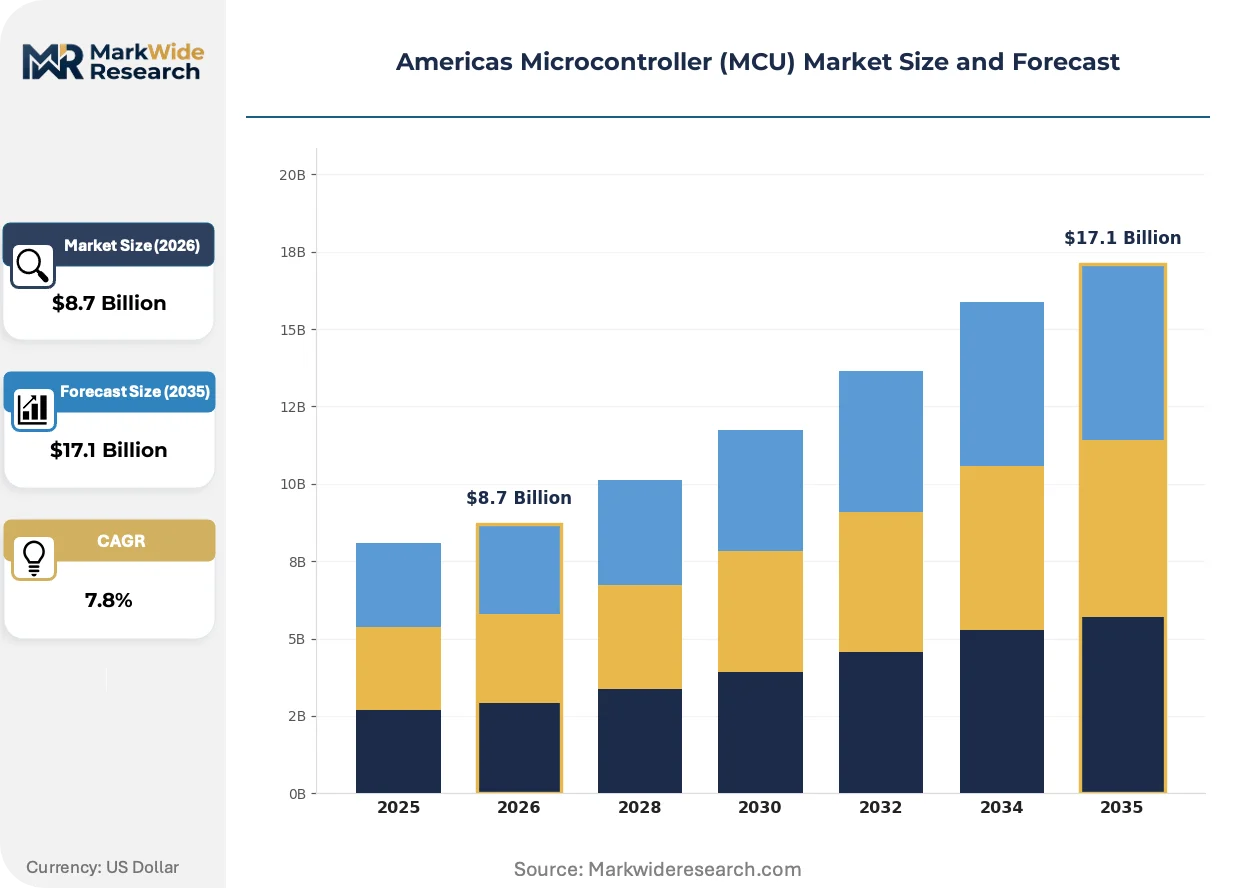
Market Dynamics
The Americas MCU market is restructuring around foundry capacity constraints as analog mixed-signal engineering talent scarcity collides with CHIPS Act-funded domestic fabrication buildouts in Arizona and Texas.
Growth Catalysts
- Electric powertrain controllers:Automotive OEMs in Detroit and São Paulo are expanding embedded MCU procurement for battery management and motor control systems. Tier-one suppliers near the U.S.-Mexico border are scaling Arm Cortex-M based designs for EV platforms.
- CHIPS Act funding:The U.S. Department of Commerce is redirecting foundry investment toward domestic 32-bit fabrication capacity, accelerating onshore production timelines for automotive-qualified devices.
- Industrial automation corridors:Brazil's São José dos Campos cluster and Mexico's Baja California aerospace electronics hub are concentrating demand for deterministic real-time control systems in factory automation and avionics.
Market Restraints
- Analog mixed-signal talent scarcity:The shortage of design engineers with converter and power management IP expertise is collapsing foundry expansion timelines across the Americas, delaying new product qualifications.
- Single-foundry concentration risk:Captive wafer capacity at Sherman, Texas insulates only select suppliers from external foundry queues, leaving most MCU vendors exposed to Taiwan and South Korea fab bottlenecks.
- FCC Part 15 emissions compliance:Radio-integrated microcontroller architectures for IoT devices face stringent electromagnetic interference testing requirements that extend development cycles and certification costs.
Strategic Opportunities
- Medical device convergence:FDA 21 CFR Part 820 quality system regulations are creating validated manufacturing barriers that favor suppliers with in-house mixed-signal converter IP for wearable and diagnostic applications.
- Functional safety certification premium:Automotive firmware security requirements and ISO 26262 compliance are escalating unit pricing for 32-bit automotive-grade MCUs, deepening margin pools for qualified suppliers.
- Mexico nearshoring acceleration:Tier-one automotive suppliers in Baja California and Chihuahua are demanding localized MCU sourcing to mitigate cross-border logistics risk and tariff exposure.
Industry Challenges
- Dual-source qualification burden:Stakeholders must weigh fixed costs of second-source validation against single-foundry concentration risk as domestic capacity ramps, straining engineering resources.
- Legacy 8-bit to 32-bit migration friction:Industrial automation clients throughout the U.S. Midwest and Southeast face firmware rewrite costs and peripheral incompatibility when upgrading from 16-bit portfolios.
- Process node optimization:Cost-sensitive applications at 40nm to 90nm nodes require precise die size and yield management as foundry pricing for mature nodes tightens with automotive demand competition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Microcontroller (MCU) Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
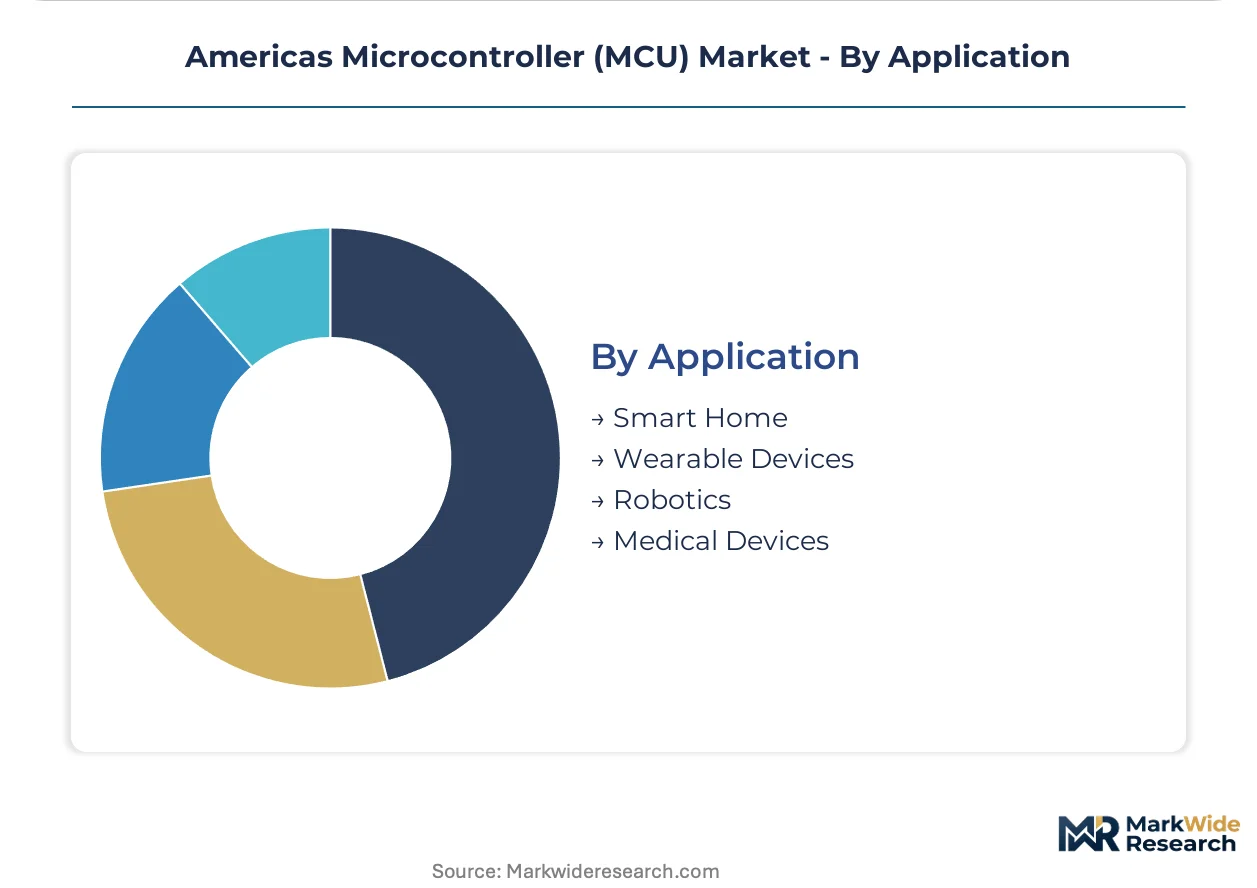
| Segmentation | Product Type: 8-bit, 16-bit, 32-bit, ARM Cortex Technology: Embedded, Analog, Digital, Mixed Signal End User: Automotive, Consumer Electronics, Industrial Automation, IoT Devices Application: Smart Home, Wearable Devices, Robotics, Medical Devices |
| Companies Covered | NXP Semiconductors N.V., Texas Instruments Incorporated, Microchip Technology Inc., STMicroelectronics N.V., Renesas Electronics Corporation, Infineon Technologies AG, Silicon Laboratories Inc., Analog Devices Inc., ON Semiconductor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Microcontroller (MCU) Market Trends and Innovations
Mixed-signal integration is compressing discrete component counts while regulatory mandates and procurement model evolution are rewriting supplier qualification requirements across automotive and medical verticals.
RISC-V open instruction set architectures are fragmenting the historically Arm-dominated MCU landscape as automotive and industrial OEMs seek to reduce royalty burdens and customize core extensions. Tier-one suppliers in Mexico and Brazil are piloting RISC-V based designs for non-safety-critical subsystems, creating alternative sourcing pathways outside proprietary ecosystems. This fragmentation is enabling second-tier suppliers to compete on feature customization rather than ecosystem lock-in.
The U.S. CHIPS and Science Act is mandating domestic content thresholds for federally funded infrastructure projects, forcing MCU suppliers to qualify Arizona and Texas fab output for government-adjacent applications. Department of Commerce funding conditions require validated manufacturing records and supply chain transparency that exceed commercial automotive standards. Medical device OEMs sourcing for Veterans Affairs and Medicare-funded equipment are prioritizing suppliers with onshore fabrication to satisfy Buy America provisions.
Automotive OEM procurement teams are consolidating vendor lists around suppliers with captive wafer capacity, compressing qualification cycles from multi-year evaluations to 12-month competitive bake-offs. Tier-one suppliers near Detroit and São Paulo are demanding direct foundry relationships and lot-level traceability that bypass traditional distribution channels. This concentration is most visible in electric powertrain controller sourcing, where OEMs are awarding sole-source contracts to vertically integrated MCU vendors with in-house 32-bit fabrication.
Americas Microcontroller (MCU) Market Segmentation
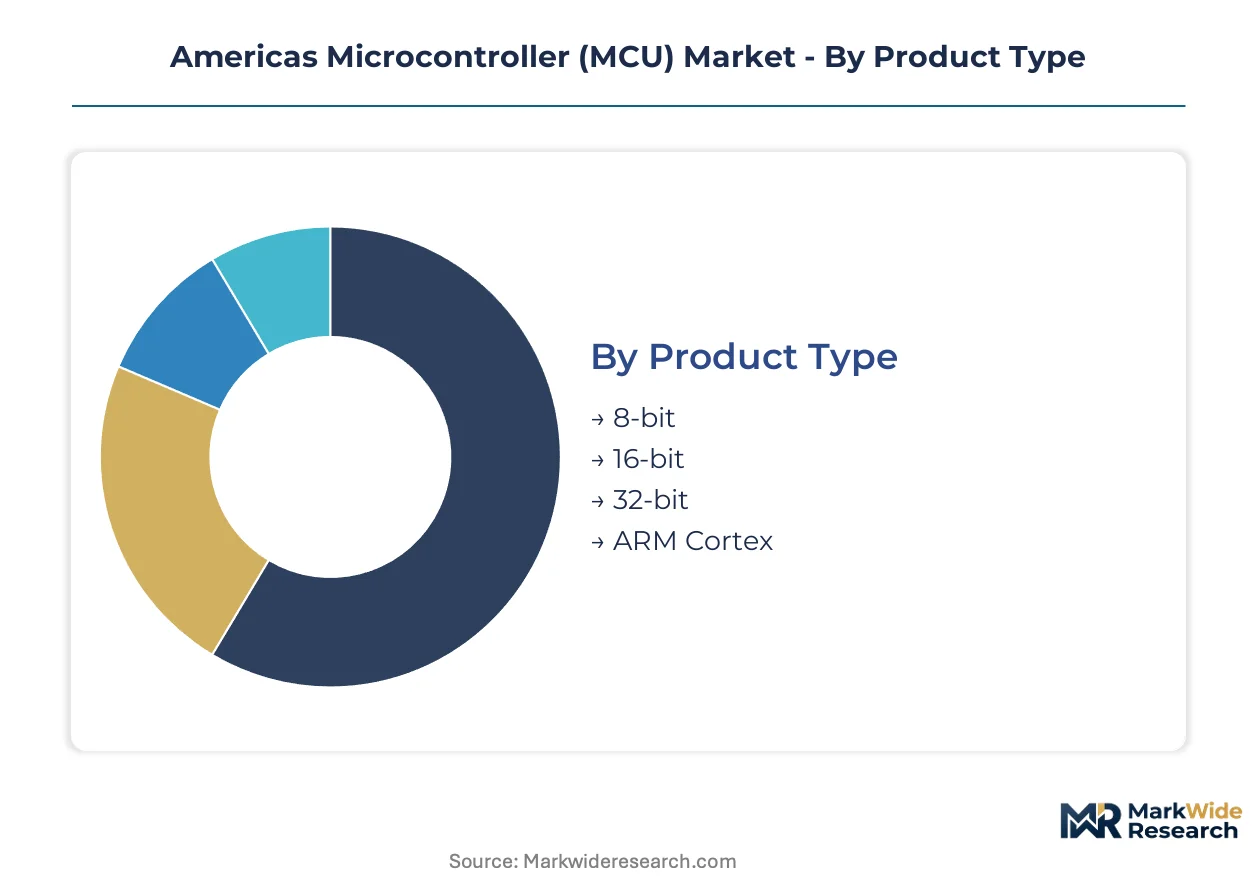
MCU segmentation in the Americas reflects divergent certification burdens and process node economics. Product architecture choices determine foundry access, while end-use verticals impose distinct regulatory compliance frameworks.
Product Type:
FDA 21 CFR Part 820 quality system regulations and ISO 26262 functional safety standards create tiered validation requirements across bit-width architectures.
- 32-bit:These architectures integrate Arm Cortex-M or RISC-V cores at 40nm to 90nm nodes for deterministic real-time control. Electric powertrain controllers in Detroit and São Paulo are consolidating procurement around 32-bit devices with automotive-qualified flash memory. ISO 26262 ASIL-B through ASIL-D certification timelines extend unit pricing premiums.
- ARM Cortex:Proprietary core licensing dominates Mexican tier-one automotive supplier specifications near the U.S. border. NXP Semiconductors N.V. maintains supply chain concentration for these designs, though RISC-V fragmentation is eroding royalty advantages in Brazil's industrial automation corridor.
- 8-bit:Legacy architectures persist in cost-constrained sensor nodes throughout the U.S. Midwest.
- 16-bit:Transitional portfolio for industrial clients facing firmware rewrite friction during 32-bit migration.
Established volume favors 32-bit; emerging adoption favors ARM Cortex alternatives.
Technology:
Process integration depth determines margin capture as mixed-signal expertise scarcity reshapes supplier competitiveness.
- Mixed Signal:Analog-to-digital converters and power management IP integrated onto single die eliminate discrete front-end components. Medical device OEMs sourcing for Veterans Affairs equipment prioritize these variants to satisfy Buy America domestic content thresholds.
- Embedded:Self-contained flash and SRAM configurations dominate IoT Devices requiring minimal external component count. FCC Part 15 emissions testing for radio-integrated variants extends development cycles.
- Analog:Peripheral-rich designs target sensor interface applications in Baja California aerospace electronics.
- Digital:Pure logic implementations concentrate in high-volume consumer Electronics with relaxed timing constraints.
Margin concentration sits with Mixed Signal; volume scaling favors Embedded.
End User:
Procurement consolidation patterns vary sharply across verticals as captive foundry capacity becomes a vendor selection filter.
- Automotive:Battery management and motor control systems in Detroit and São Paulo are driving 12-month competitive qualification cycles. Tier-one suppliers demand direct foundry relationships and lot-level traceability bypassing distribution channels.
- IoT Devices:Smart home and wearable subsystems face FCC Part 15 electromagnetic interference mandates that compress design windows. Radio-integrated architectures require pre-certification module strategies.
- Industrial Automation:Deterministic control requirements in São José dos Campos cluster favor 16-bit to 32-bit migration programs.
- Consumer Electronics:Price-sensitive volumes concentrate in Mexico's maquiladora assembly nodes.
Automotive commands qualification rigor; IoT Devices represent the steepest expansion trajectory.
Application:
Functional safety and data integrity requirements stratify addressable value across use cases.
- Medical Devices:Diagnostic and wearable applications require validated manufacturing records per FDA 21 CFR Part 820. Suppliers with in-house mixed-signal converter IP capture preference for Medicare-funded equipment procurement.
- Robotics:Factory automation in Brazil's industrial corridors demands real-time deterministic response with minimal jitter. Arm Cortex-M based motor control dominates.
- Smart Home:Connectivity modules face FCC Part 15 emissions constraints and interoperability certification burdens.
- Wearable Devices:Power-optimized 8-bit and 16-bit variants target fitness and health monitoring with extended battery life requirements.
Medical Devices anchor premium pricing; Robotics is climbing the fastest on automation investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Americas diverge sharply by vertical concentration. The United States prioritizes automotive-grade 32-bit devices with functional safety certification, while Mexico and Brazil emphasize cost-optimized industrial automation portfolios. Canada anchors aerospace and medical device demand with stringent domestic content requirements.
United States
Automotive OEMs in Detroit and Austin are consolidating procurement around 32-bit MCUs for electric powertrain controllers. The CHIPS and Science Act directs Department of Commerce funding toward domestic fabrication capacity in Arizona and Texas. Tier-one suppliers in Sherman, Texas leverage captive wafer capacity to insulate automotive lines from external foundry queues.
Mexico
Tier-one automotive suppliers in Baja California and Chihuahua are demanding localized MCU sourcing to mitigate cross-border logistics risk. The country's national industrial development programs incentivize nearshoring of electronics manufacturing. Aerospace electronics clusters in Baja California concentrate demand for deterministic real-time control systems in avionics applications.
Brazil
Industrial automation corridors around São José dos Campos and São Paulo are scaling embedded MCU procurement for factory automation systems. ANVISA regulations govern medical device applications, forcing suppliers to maintain validated manufacturing records. The São Paulo state industrial policy supports migration from 16-bit to 32-bit architectures in automotive subsystems.
Canada
Medical device OEMs in Ontario and Quebec prioritize suppliers with onshore fabrication to satisfy procurement requirements for federally funded healthcare equipment. Health Canada regulations enforce quality system standards for diagnostic and wearable applications. Aerospace electronics demand concentrates in Montreal and Toronto, where avionics suppliers require mixed-signal integration for sensor interface designs.
Americas Microcontroller (MCU) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Americas MCU supply. Captive wafer capacity distinguishes the upper tier from foundry-dependent competitors. Three archetypes dominate: vertically integrated semiconductor manufacturers with in-house fabrication, fabless designers reliant on external foundry partnerships, and mixed-signal specialists with converter IP expertise. Competitive moves center on foundry capacity expansion and strategic qualification partnerships with tier-one automotive suppliers.
Within the integrated manufacturing tier, Texas Instruments Incorporated and NXP Semiconductors N.V. exemplify the captive-capacity archetype that insulates supply from external fab bottlenecks. Microchip Technology Inc. occupies a position bridging portfolio breadth with industrial automation specialization across the U.S. Midwest and Southeast. These three anchors represent distinct competitive vectors: one emphasizing automotive-grade fabrication scale, another dominating Arm-based supply to Mexican tier-ones, and the third capturing 8-bit and 16-bit legacy demand in factory automation.
| Leading Market Players |
|---|
| NXP Semiconductors N.V. |
| Texas Instruments Incorporated |
| Microchip Technology Inc. |
| STMicroelectronics N.V. |
| Renesas Electronics Corporation |
| Infineon Technologies AG |
| Silicon Laboratories Inc. |
| Analog Devices Inc. |
| ON Semiconductor |
| Others |
Pricing and Supply Chain Analysis
Discrete analog front-end replacement by mixed-signal MCU integration is simultaneously shifting procurement geography toward domestic foundries and collapsing price premiums previously commanded by multi-chip solutions. This substitution dynamic concentrates buyer leverage around suppliers with in-house converter IP while CHIPS Act funding redraws cost curves for Arizona and Texas fab output.
Pricing Analysis
Long-term offtake contracts dominate automotive procurement as Detroit and São Paulo OEMs secure 32-bit capacity through sole-source agreements bypassing distribution channels. Price differentiation hinges on ISO 26262 ASIL certification grade and captive wafer availability, with automotive-grade devices commanding substantial premiums over industrial variants. Cost compression in 8-bit and 16-bit tiers is intensifying as Midwest factory automation clients delay migration programs. Consumer electronics buyers in Mexico's maquiladora nodes exhibit highest price sensitivity, while medical device OEMs sourcing for Veterans Affairs equipment show lowest sensitivity due to Buy America compliance requirements.
Supply Chain Analysis
Inventory buffers at tier-one automotive suppliers near the U.S.-Mexico border remain thin as lead times for external foundry wafers extend beyond comfortable planning horizons. Geographic concentration centers on Taiwan and South Korea for leading-edge process nodes, with domestic capacity expansion in Arizona and Texas feeding government-adjacent applications. Raw material dependencies span silicon wafers, specialty gases for 40nm-90nm etching, and automotive-qualified flash memory substrates. Single-source vulnerability persists for Arm Cortex core licensing concentrated with NXP Semiconductors N.V. Distribution runs through direct foundry relationships for automotive tier-ones, while industrial clients retain distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RISC-V open instruction set architectures constitute a credible substitution threat that incumbent Arm-license holders must neutralize through ecosystem lock-in and certification moats.
For Market Incumbents: Shield automotive-grade revenue pools by accelerating ISO 26262 ASIL-D certification timelines for 32-bit portfolios before RISC-V pilots in Mexico and Brazil scale into safety-critical subsystems. Deepen backward integration into mixed-signal converter IP to capture FDA 21 CFR Part 820 validated manufacturing premiums in medical devices.
For New Entrants and Emerging Players: Firmware migration services for industrial automation clients stranded on 16-bit architectures present a service-layer gap where incumbents under-serve. Target São José dos Campos factory automation corridors with deterministic control reference designs and direct engineering support models that Microchip Technology Inc.'s broad portfolio cannot match.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors vertically integrated manufacturers with captive wafer supply over foundry-dependent competitors. Acquisition targets should demonstrate validated manufacturing records for Medicare-funded equipment and Arm Cortex-M supply relationships to Mexican tier-ones. Monitor CHIPS Act disbursement velocity as the inflection signal for domestic fab output qualification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Wafer Capacity Expansion | Sherman, Texas fab investments insulate automotive MCU lines from Taiwan and South Korea bottlenecks. |
| RISC-V Core Customization Program | São Paulo industrial OEMs pilot open ISA designs to reduce Arm royalty burdens in non-safety subsystems. |
| FDA 21 CFR Part 820 Validation Investment | In-house mixed-signal converter IP captures preference for Veterans Affairs diagnostic equipment procurement. |
| Direct Foundry Relationship Consolidation | Tier-one suppliers in Baja California demand lot-level traceability bypassing traditional distribution channels. |
| Functional Safety Certification Acceleration | ISO 26262 ASIL-B through ASIL-D compliance deepens margin pools for electric powertrain controller suppliers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, Department of Commerce CHIPS Act disbursement records, and FDA 510(k) submission databases to establish baseline supply and demand parameters. Primary inputs encompass semiconductor procurement executives at Detroit and São Paulo automotive OEMs, analog mixed-signal design engineering directors, and tier-one supplier quality assurance leads managing FDA 21 CFR Part 820 compliance. Bottom-up unit demand estimates triangulate against top-down foundry capacity allocation data from Arizona and Texas fab construction disclosures.
Segmentation dimensions modeled span bit-width architecture, process node tier, end-use vertical, and geographic regulatory cluster across the analysis window. CAGRs derive from regression analysis of historical procurement volumes against projected electric vehicle platform ramp schedules and industrial automation investment cycles. Forecast inputs incorporate CHIPS Act funding disbursement trajectories and ANVISA medical device registration timelines for Brazilian market entry.
Forecasts assume regulatory continuity in U.S. FCC Part 15 emissions enforcement and FDA quality system mandates; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Leap Engine Market
Semiconductor Devices
Rad-Hard Mosfets Market
Semiconductor Devices
APAC Semiconductor Device in Consumer Industry Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
Gan and Sic Power Semiconductor Market
Semiconductor Devices
Digital Transistor Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
Flip Chip Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Silicon Carbide Semiconductor Devices Market
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
N-Topcon Solar Cells Market
Semiconductor Devices
Gan-On-Silicon Market
Semiconductor Devices
ADC & DAC In Quantum Computing Market
Semiconductor Devices
Transistor Arrays Market